# ASC 360-932-S99: Property, Plant, and Equipment — Extractive Activities—Oil and Gas — SEC 99 SEC Materials
Source: FASB Accounting Standards Codification, Basic View
[Read online](https://asc.understandingaccounting.org/asc/360/932/#sec-99-sec-materials)
Study and research edition. Verify current requirements with the official source. Summaries, enrichment, and tags are machine-generated study aids. Paragraph html preserves source markup; snippet is abbreviated. Pending content is not necessarily effective.
Tables and mathematical or amendment markup are retained as HTML where Markdown would lose structure.
Source downloaded (UTC): 2026-09-10T00:09:33.153Z to 2026-09-10T00:09:33.153Z
Record version: sha256:4a602d6544b674e6184156f483bc09fd755b6a9eea8213f48a060ced3635bd39
Snapshot version: sha256:15aea8165dff9f5ae47d9484f8470588b13b307f56e1d50801bf4d85ec190e3f
Effective as of: not established by retrieval timestamps.
## ASC 360-932-S99: SEC 99 SEC Materials
[Read section](https://asc.understandingaccounting.org/asc/360/932/#sec-99-sec-materials)
SEC content: yes
#### SEC Staff Guidance
##### [360-932-S99-1](https://asc.understandingaccounting.org/asc/360/932/#360-932-S99-1)
Pending content: no
Source downloaded (UTC): 2026-09-10T00:09:33.153Z to 2026-09-10T00:09:33.153Z
Record version: sha256:ddbcc5c341b35f4f2cb519b926ab26e6f6e2f0365ac5ccf24cc639bf2ae95866
Snapshot version: sha256:15aea8165dff9f5ae47d9484f8470588b13b307f56e1d50801bf4d85ec190e3f
Effective as of: not established by retrieval timestamps.
The following is the text of SAB Topic 12.A, Accounting Series Release 257—Requirements for Financial Accounting and Reporting Practices for Oil and Gas Producing Activities.
- 1\. Estimates of Quantities of Proved Reserves
- Facts: Rule 4-10 contains definitions of proved reserves, proved developed reserves, and proved undeveloped reserves to be used in determining quantities of oil and gas reserves to be reported in filings with the Commission.
- Question 1: The definition of proved reserves states that reservoirs are considered proved if "economic producibility is supported by either actual production or conclusive formation test." May oil and gas reserves be considered proved if economic producibility is supported only by core analyses and/or electric or other log interpretations?
- Interpretive Response: Economic producibility of estimated proved reserves can be supported to the satisfaction of the Office of Engineering if geological and engineering data demonstrate with reasonable certainty that those reserves can be recovered in future years under existing economic and operating conditions. The relative importance of the many pieces of geological and engineering data which should be evaluated when classifying reserves cannot be identified in advance. In certain instances, proved reserves may be assigned to reservoirs on the basis of a combination of electrical and other type logs and core analyses which indicate the reservoirs are analogous to similar reservoirs in the same field which are producing or have demonstrated the ability to produce on a formation test.
- Question 2: In determining whether "proved undeveloped reserves" encompass acreage on which fluid injection (or other improved recovery technique) is contemplated, is it appropriate to distinguish between (i) fluid injection used for pressure maintenance during the early life of a field and (ii) fluid injection used to effect secondary recovery when a field is in the late stages of depletion? The definition in Rule 4-10(a)(4) does not make this distinction between pressure maintenance activity and fluid injection undertaken for purposes of secondary recovery.
- Interpretive Response: The Office of Engineering believes that the distinction identified in the above question may be appropriate in a few limited circumstances, such as in the case of certain fields in the North Sea. The staff will review estimates of proved reserves attributable to fluid injection in the light of the strength of the evidence presented by the registrant in support of a contention that enhanced recovery will be achieved.
- Question 3: What volumes of natural gas liquids should be reported as net reserves, that portion recovered in a gas processing plant and allocated to the leasehold interest or the total recovered by a plant from net interest gas?
- Interpretive Response: Companies should report reserves of natural gas liquids which are net to their leasehold interests, i.e., that portion recovered in a processing plant and allocated to the leasehold interest. It may be appropriate in the case of natural gas liquids not clearly attributable to leasehold interests ownership to follow instructions to Item 3 of Securities Act Industry Guide 2 and report such reserves separately and describe the nature of the ownership.
- Question 4: What pressure base should be used for reporting gas and production, 14.73 psia or the pressure base specified by the state?
- Interpretive Response: The reporting instructions to the Department of Energy's Form EIA-28 specify that natural gas reserves are to be reported at 14.73 psia and 60 degrees F. There is no pressure base specified in Regulation S-X or S-K. At the present time the staff will not object to natural gas reserves and production data calculated at other pressure bases, if such other pressure bases are identified in the filing.
- 2\. Estimates of Future Net Revenues
- Facts: Paragraphs 30-34 of Statement 69 \[paragraphs
[932-235-50-29 through 50-36](https://asc.understandingaccounting.org/asc/235/932/#235-932-50-29)
\] require the disclosure of the standardized measure of discounted future net cash flows from production of proved oil and gas reserves, computed by applying year-end prices of oil and gas (with consideration of price changes only to the extent provided by contractual arrangements) to estimated future production as of the latest balance sheet date, less estimated future expenditures (based on current costs) of developing and producing the proved reserves, and assuming continuation of existing economic conditions.
- Question 1: For purposes of determining reserves and estimated future net revenues, what price should be used for gas which will be produced after an existing contract expires or after the redetermination date in a contract?
- Interpretive Response: The price to be used for gas which will be produced after a contract expires or has a redetermination is the current market price at the end of the fiscal year for that category of gas. This price may be increased thereafter only for additional fixed and determinable escalations, as appropriate, for that category of gas. A fixed and determinable escalation is one which is specified in amount and is not based on future events such as rates of inflation.
- Question 2: What price should be applied to gas which at the end of a fiscal year is not yet subject to a gas sales contract?
- Interpretive Response: The price to be used is the current market price for similarly situated gas at the end of the fiscal year provided the company can reasonably expect to sell the gas at the prevailing market price.
- Question 3: To what extent should price increases announced by OPEC or by certain government agencies not yet effective at the date of the reserve report be considered in determining current prices?
- Interpretive Response: Current prices should not reflect price increases announced but not yet effective at the date of the reserve valuation, i.e., the end of the fiscal year.
- 3\. Disclosure of Reserve Information
- a. Deleted by SAB 103
- b. Unproved properties.
- Facts: Disclosures of reserve information are based on estimated quantities of proved reserves of oil and gas. Regulation S-K prohibits disclosure of estimated quantities of probable or possible reserves of oil and gas and any estimated value thereof in any document publicly filed with the Commission.
- Question: What types of disclosures will be permitted by registrants who wish to indicate that some of their properties have value other than that attributable to proved reserves?
- Interpretive Response: The Office of Engineering has, for the past several years, suggested to registrants the following form of disclosure for undeveloped lease acreage:
- "In addition to proved reserves, the estimated (or appraised) value of leases or parts of leases to which proved reserves cannot be attributable is $xxx."
- The registrant should describe the basis on which the estimate was made. For example, such estimated values are often based on the market demand for leasehold acreage which, in turn, is based on a number of qualitative factors such as proximity to production. If the disclosed amount is based on an appraisal, the person making the appraisal should be named.
##### [360-932-S99-2](https://asc.understandingaccounting.org/asc/360/932/#360-932-S99-2)
Pending content: no
Source downloaded (UTC): 2026-09-10T00:09:33.153Z to 2026-09-10T00:09:33.153Z
Record version: sha256:f6368840753414ab8fcee763557db431ec88ad8c3e8bee53e99b9e69dbdba42b
Snapshot version: sha256:15aea8165dff9f5ae47d9484f8470588b13b307f56e1d50801bf4d85ec190e3f
Effective as of: not established by retrieval timestamps.
The following is the text of SAB Topic 12.D, Application of Full Cost Method of Accounting.
- 1\. Treatment of Income Tax Effects in the Computation of the Limitation on Capitalized Costs
- Facts: Item (D) of Rule 4-10(c)(4)(i) of Regulation S-X states that the income tax effects related to the properties involved should be deducted in computing the full cost ceiling.
- Question 1: What specific types of income tax effects should be considered in computing the income tax effects to be deducted from estimated future net revenues?
- Interpretive Response: The rule refers to income tax effects generally. Thus, the computation should take into account (i) the tax basis of oil and gas properties, (ii) net operating loss carryforwards, (iii) foreign tax credit carryforwards, (iv) investment tax credits, (v) minimum taxes on tax preference items, and (vi) the impact of statutory (percentage) depletion.
- It may often be difficult to allocate net operating loss carryforwards (NOLs) between oil and gas assets and other assets. However, to the extent that the NOLs are clearly attributable to oil and gas operations and are expected to be realized within the carryforward period, they should be added to tax basis.
- Similarly, to the extent that investment tax credit (ITC) carryforwards and foreign tax credit carryforwards are attributable to oil and gas operations and are expected to be realized within the carryforward period, they should be considered as a deduction from the tax effect otherwise computed. Consideration of NOLs and ITC or foreign tax credit carryforwards should not, of course, reduce the total tax effect below zero.
- Question 2: How should the tax effect be computed considering the various factors discussed above?
- Interpretive Response: Theoretically, taxable income and tax could be determined on a year-by-year basis and the present value of the related tax computed. However, the "shortcut" method illustrated below is also acceptable.
- 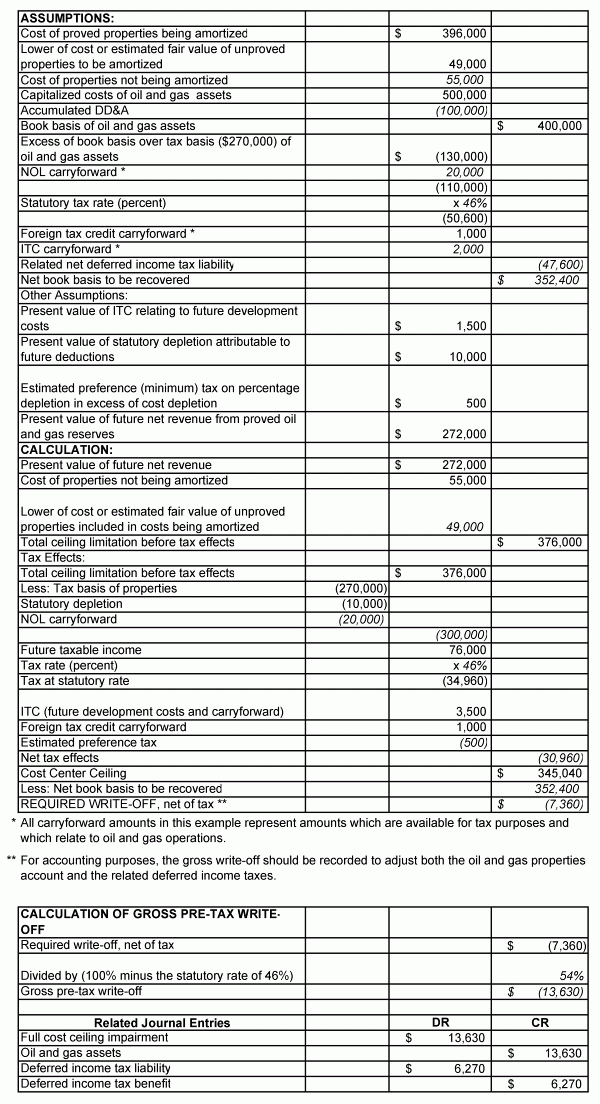
ASSUMPTIONS: Cost of proved properties being amortized " $396,000 " Lower of cost or estimated fair value of unproved properties to be amortized " 49,000 " Cost of properties not being amortized " 55,000 " Capitalized costs of oil and gas assets " 500,000 " Accumulated DD&A " (100,000)" Book basis of oil and gas assets " $400,000 " "Excess of book basis over tax basis ($270,000) of oil and gas assets" " $(130,000)" NOL carryforward \* " 20,000 " " (110,000)" Statutory tax rate (percent) x 46% " (50,600)" Foreign tax credit carryforward \* " 1,000 " ITC carryforward \* " 2,000 " Related net deferred income tax liability " (47,600)" Net book basis to be recovered " $352,400 " Other Assumptions: Present value of ITC relating to future development costs " $1,500 " Present value of statutory depletion attributable to future deductions " $10,000 " Estimated preference (minimum) tax on percentage depletion in excess of cost depletion $500 Present value of future net revenue from proved oil and gas reserves " $272,000 " CALCULATION: Present value of future net revenue " $272,000 " Cost of properties not being amortized " 55,000 " Lower of cost or estimated fair value of unproved properties included in costs being amortized " 49,000 " Total ceiling limitation before tax effects " $376,000 " Tax Effects: Total ceiling limitation before tax effects " $376,000 " Less: Tax basis of properties " (270,000)" Statutory depletion " (10,000)" NOL carryforward " (20,000)" " (300,000)" Future taxable income " 76,000 " Tax rate (percent) x 46% Tax at statutory rate " (34,960)" ITC (future development costs and carryforward) " 3,500 " Foreign tax credit carryforward " 1,000 " Estimated preference tax (500) Net tax effects " (30,960)" Cost Center Ceiling " $345,040 " Less: Net book basis to be recovered " 352,400 " "REQUIRED WRITE-OFF, net of tax \*\* " " $(7,360)" \* All carryforward amounts in this example represent amounts which are available for tax purposes and which relate to oil and gas operations. \*\* "For accounting purposes, the gross write-off should be recorded to adjust both the oil and gas properties account and the related deferred income taxes." CALCULATION OF GROSS PRE-TAX WRITE-OFF "Required write-off, net of tax" " $(7,360)" Divided by (100% minus the statutory rate of 46%) 54% Gross pre-tax write-off " $(13,630)" Related Journal Entries DR CR Full cost ceiling impairment " $13,630 " Oil and gas assets " $13,630 " Deferred income tax liability " $6,270 " Deferred income tax benefit " $6,270 "
- 2\. Exclusion of Costs From Amortization
- Facts: Rule 4-10(c)(3)(ii) indicates that the costs of acquiring and evaluating unproved properties may be excluded from capitalized costs to be amortized if the costs are unusually significant in relation to aggregate costs to be amortized. Costs of major development projects may also be incurred prior to ascertaining the quantities of proved reserves attributable to such properties.
- Question: At what point should amortization of previously excluded costs commence-when proved reserves have been established or when those reserves become marketable? For instance, a determination of proved reserves may be made before completion of an extraction plant necessary to process sour crude or a pipeline necessary to market the reserves. May the costs continue to be excluded from amortization until the plant or pipeline is in service?
- Interpretive Response: No. The proved reserves and the costs allocable to such reserves should be transferred into the amortization base on an ongoing (well-by-well or property-by-property) basis as the project is evaluated and proved reserves are established.
- Once the determination of proved reserves has been made, there is no justification for continued exclusion from the full cost pool, regardless of whether other factors prevent immediate marketing. Moreover, at the same time that the costs are transferred into the amortization base, it is also necessary in accordance with FASB ASC Subtopic 932-835, Extractive Activities—Oil and Gas—Interest, and FASB ASC Subtopic 835-20, Interest—Capitalization of Interest to terminate capitalization of interest on such properties.
- In this regard, registrants are reminded of their responsibilities not to delay recognizing reserves as proved once they have met the engineering standards.
- 3\. Full Cost Ceiling Limitation
- a. Exemptions for purchased properties.
- Facts: During 20x1, a registrant purchases proved oil and gas reserves in place ("the purchased reserves") in an arm's length transaction for the sum of $9.8 million. Primarily because the registrant expects oil and gas prices to escalate, it paid $1.2 million more for the purchased reserves than the "Present Value of Estimated Future Net Revenues" computed as defined in Rule 4-10(c)(4)(i)(A) of Regulation S-X. An analysis of the registrant's full cost center in which the purchased reserves are located at December 31, 20x1 is as follows:
- 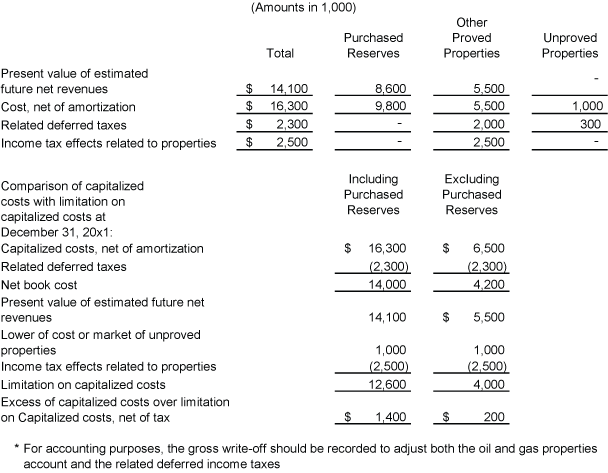
"(Amounts in 1,000) " Total Purchased Reserves Other Proved Properties Unproved Properties "Present value of estimated future net revenues " " $14,100 " " 8,600 " " 5,500 " - "Cost, net of amortization " " $16,300 " " 9,800 " " 5,500 " " 1,000 " Related deferred taxes " $2,300 " - " 2,000 " 300 Income tax effects related to properties " $2,500 " - " 2,500 " - "Comparison of capitalized costs with limitation on capitalized costs at December 31, 20x1: " Including Purchased Reserves ExcIuding Purchased Reserves "Capitalized costs, net of amortization " " $16,300 " " $6,500 " Related deferred taxes " (2,300)" " (2,300)" Net book cost " 14,000 " " 4,200 " Present value of estimated future net revenues " 14,100 " " $5,500 " Lower of cost or market of unproved properties " 1,000 " " 1,000 " Income tax effects related to properties " (2,500)" " (2,500)" Limitation on capitalized costs " 12,600 " " 4,000 " "Excess of capitalized costs over limitation on Capitalized costs, net of tax " " $1,400 " $200 \* "For accounting purposes, the gross write-off should be recorded to adjust both the oil and gas properties account and the related deferred income taxes"
- Question: Is it necessary for the registrant to write down the carrying value of its full cost center at December 31, 20x1 by $1,400,000?
- Interpretive Response: Although the net carrying value of the full cost center exceeds the cost center's limitation on capitalized costs, the text of ASR 258 provides that a registrant may request an exemption from the rule if as a result of a major purchase of proved properties, a write down would be required even though the registrant believes the fair value of the properties in a cost center clearly exceeds the unamortized costs.
- Therefore, to the extent that the excess carrying value relates to the purchased reserves, the registrant may seek a temporary waiver of the full-cost ceiling limitation from the staff of the Commission. Registrants requesting a waiver should be prepared to demonstrate that the additional value exists beyond reasonable doubt.
- To the extent that the excess costs relate to properties other than the purchased reserves, however, a write-off should be recorded in the current period. In order to determine the portion of the total excess carrying value which is attributable to properties other than the purchased reserves, it is necessary to perform the ceiling computation on a "with and without" basis as shown in the example above. Thus in this case, the registrant must record a write-down of $200,000 applicable to other reserves. An additional $1,200,000 write-down would be necessary unless a waiver were obtained.
- b. Use of cash flow hedges in the computation of the limitation on capitalized costs.
- Facts: Rule 4-10(c)(4) of Regulation S-X provides, in pertinent part, that capitalized costs, net of accumulated depreciation and amortization, and deferred income taxes, should not exceed an amount equal to the sum of \[components that include\] the present value of estimated future net revenues computed by applying current prices of oil and gas reserves (with consideration of price changes only to the extent provided by contractual arrangements) to estimated future production of proved oil and gas reserves as of the date of the latest balance sheet presented.
- As of the reported balance sheet date, capitalized costs of an oil and gas producing company exceed the full cost limitation calculated under the above described rule based on current spot market prices for oil and natural gas. However, prior to the balance sheet date, the company enters into certain hedging arrangements for a portion of its future natural gas and oil production, thereby enabling the company to receive future cash flows that are higher than the estimated future cash flows indicated by use of the spot market price as of the reported balance sheet date. These arrangements qualify as cash flow hedges under the provisions of FASB ASC Topic 815, Derivatives and Hedging, and are documented, designated, and accounted for as such under the criteria of that standard.
- Question: Under these circumstances, must the company use the higher prices to be received after taking into account the hedging arrangements ("hedge-adjusted prices") in calculating the current price of the quantities of its future production of oil and gas reserves covered by the hedges as of the reported balance sheet date?
- Interpretive Response: Yes. Derivative contracts that qualify as hedging instruments in a cash flow hedge and are accounted for as such pursuant to FASB ASC Topic 815 represent the type of contractual arrangements for which consideration of price changes should be given under the existing rule. While the SEC staff has objected to previous proposals to consider various hedging techniques as being equivalent to the contractual arrangements permitted under the existing rules, the staff's objection was based on concerns that the lack of clear, consistent guidance in the accounting literature would lead to inconsistent application in practice. However, the staff believes that FASB ASC Topic 815 and related guidance (including a more systematic approach to documentation) provides sufficient guidance so that comparable financial reporting in comparable factual circumstances should result.
- This interpretive response reflects the SEC staff's view that, assuming compliance with the prerequisite accounting requirements, hedge adjusted prices represent the best measure of estimated cash flows from future production of the affected oil and gas reserves to use in calculating the ceiling limitation. Nonetheless, the staff expects that oil and gas producing companies subject to the full cost rules will clearly indicate the effects of using cash flow hedges in calculating ceiling limitations within their financial statement footnotes. The staff further expects that disclosures will indicate the portion of future oil and gas production being hedged. The dollar amount that would have been charged to income had the effects of the cash flow hedges not been considered in calculating the ceiling limitation also should be disclosed.
- The use of hedge-adjusted prices should be consistently applied in all reporting periods, including periods in which the hedge-adjusted price is less than the current spot market price. Oil and gas producers whose computation of the ceiling limitation includes hedge-adjusted prices because of the use of cash flow hedges also should consider the disclosure requirements under the FASB ASC Section 275-10-50, Risks and Uncertainties—Overall—Disclosure. FASB ASC paragraph [275-10-50-9](https://asc.understandingaccounting.org/asc/275/10/#275-10-50-9) calls for disclosure when it is at least reasonably possible that the effects of cash flow hedges on capitalized costs on the reported balance sheet date will change in the near term due to one or more confirming events, such as potential future changes in commodity prices.
- In addition, the use of cash flow hedges in calculating the ceiling limitation may represent a type of critical accounting policy that oil and gas producers should consider disclosing consistent with the cautionary advice provided in FR 60. Through this release, the Commission has encouraged companies to include, within their MD&A disclosures, full explanations, in plain English, of the judgments and uncertainties affecting the application of critical accounting policies, and the likelihood that materially different amounts would be reported under different conditions or using different assumptions.
- The staff's guidance on this issue would apply to calculations of ceiling limitations both in interim and annual periods.
- c. Effect of subsequent events on the computation of the limitation on capitalized costs.
- Facts: Rule 4-10(c)(4)(ii) of Regulation S-X provides that an excess of unamortized capitalized costs within a cost center over the related cost ceiling shall be charged to expense in the period the excess occurs.
- Question: Assume that at the date of company's fiscal year-end, its capitalized costs of oil and gas producing properties exceed the limitation prescribed by Rule 4-10(c)(4) of Regulation S-X. Thus, a write down is indicated. Subsequent to year-end but before the date of the auditors' report on the company's financial statements, assume that additional reserves are proved up (excluding the effect of increased oil and gas prices subsequent to year-end) on properties owned at year-end. The present value of future net revenues from the additional reserves is sufficiently large that if the full cost ceiling limitation were recomputed giving effect to those factors as of year-end, the ceiling would more than cover the costs. It is necessary to record a write down?
- Interpretive Response: No. In this case, the proving up of additional reserves on properties owned at year-end or the increase in prices indicates that the capitalized costs were not in fact impaired at year-end. However, for purposes of the revised computation of the "ceiling," the net book costs capitalized as of year-end should be increased by the amount of any additional costs incurred subsequent to year-end to prove the additional reserves or by any related costs previously excluded from amortization.
- While the fact pattern described herein relates to annual periods, the guidance on the effects of subsequent events applies equally to interim period calculations of the ceiling limitation.
- The registrant's financial statements should disclose that capitalized costs exceeded the limitation thereon at year-end and should explain why the excess was not charged against earnings. In addition, the registrant's supplemental disclosures of estimated proved reserve quantities and related future net revenues and costs should not give effect to the reserves proved up or the cost incurred after year-end or to the price increases occurring after year-end. However, such quantities and amounts may be disclosed separately, with appropriate explanations.
- Registrants should be aware that oil and gas reserves related to properties acquired after year-end would not justify avoiding a write-off indicated as of year-end. Similarly, the effects of cash flow hedging arrangements entered into after year-end cannot be factored into the calculation of the ceiling limitation at year-end. Such acquisitions and financial arrangements do not confirm situations existing at year-end.
- 4\. Interaction of FASB ASC Subtopic 410-20, Asset Retirement and Environmental Obligations—Asset Retirement Obligations, and the Full Cost Rules
- a. Impact of FASB ASC Subtopic 410-20 on the full cost ceiling test.
- Facts: A company following the full cost method of accounting under Rule 4-10(c) of Regulation S-X must periodically calculate a limitation on capitalized costs, i.e., the full cost ceiling. Under FASB ASC Subtopic 410-20, a company must recognize a liability for an asset retirement obligation (ARO) at fair value in the period in which the obligation is incurred, if a reasonable estimate of fair value can be made. The company also must initially capitalize the associated asset retirement costs by increasing long-lived oil and gas assets by the same amount as the liability. Any asset retirement costs capitalized pursuant to FASB ASC Subtopic 410-20 are subject to the full cost ceiling limitation under Rule 4-10(c)(4) of Regulation S-X. If a company were to continue calculating the full cost ceiling by reducing expected future net revenues by the cash flows required to settle the ARO, then the effect would be to "double-count" such costs in the ceiling test. The assets that must be recovered would be increased while the future net revenues available to recover the assets continue to be reduced by the amount of the ARO settlement cash flows.
- Question: How should a company compute the full cost ceiling to avoid double-counting the expected future cash outflows associated with asset retirement costs?
- Interpretive Response: The future cash outflows associated with settling AROs that have been accrued on the balance sheet should be excluded from the computation of the present value of estimated future net revenues for purposes of the full cost ceiling calculation. FN1, FN2
- FN1 If an obligation for expected asset retirement costs has not been accrued under FASB ASC Subtopic 410-20 for certain asset retirement costs required to be included in the full cost ceiling calculation under Rule 4-10(c)(4), such costs should continue to be included in the full cost ceiling calculation.
- FN2 This approach is consistent with the guidance in FASB ASC Subtopic 410-20 on testing for impairment under FASB ASC Section 360-10-35, Property, Plant, and Equipment—Overall—Subsequent Measurement. Under that guidance, the asset tested should include capitalized asset retirement costs. The estimated cash flows related to the associated ARO that has been recognized in the financial statements are to be excluded from both the undiscounted cash flows used to test for recoverability and the discounted cash flows used to measure the asset's fair value.
- b. Impact of FASB ASC Subtopic 410-20 on the calculation of depreciation, depletion, and amortization.
- Facts: Regarding the base for depreciation, depletion, and amortization (DD&A) of proved reserves, Rule 4-10(c)(3)(i) of Regulation S-X states that "\[c\]osts to be amortized shall include (A) all capitalized costs, less accumulated amortization, other than the cost of properties described in paragraph (ii) below; FN3 (B) the estimated future expenditures (based on current costs) to be incurred in developing proved reserves; and (C) estimated dismantlement and abandonment costs, net of estimated salvage values." FASB ASC Subtopic 410-20 requires that upon initial recognition of an ARO, the associated asset retirement costs be included in the capitalized costs of the company. Therefore, the estimated dismantlement and abandonment costs described in (C) above may be included in the capitalized costs described in (A) above, at least to the extent that an ARO has been incurred as a result of acquisition, exploration and development activities to date. Future development activities on proved reserves may result in additional asset retirement obligations when such activities are performed and the associated asset retirement costs will be capitalized at that time.
- FN3 The reference to "cost of properties described in paragraph (ii) below" relates to the costs of investments in unproved properties and major development projects, as defined.
- Question: Should the costs to be amortized under Rule 4-10(c)(3) of Regulation S-X include an amount for estimated dismantlement and abandonment costs, net of estimated salvage values, that are expected to result from future development activities?
- Interpretive Response: Yes. Companies should estimate the amount of dismantlement and abandonment costs that will be incurred as a result of future development activities on proved reserves and include those amounts in the costs to be amortized.
##### [360-932-S99-3](https://asc.understandingaccounting.org/asc/360/932/#360-932-S99-3)
Pending content: no
Source downloaded (UTC): 2026-09-10T00:09:33.153Z to 2026-09-10T00:09:33.153Z
Record version: sha256:8233d06d165c82373d5c76ebb03a6cf6fad2fc1544ffcb6d99ae43b19ab68b09
Snapshot version: sha256:15aea8165dff9f5ae47d9484f8470588b13b307f56e1d50801bf4d85ec190e3f
Effective as of: not established by retrieval timestamps.
The following is the text of SAB Topic 12.F, Gross Revenue Method of Amortizing Capitalized Costs.
- Facts: Rule 4-10(c)(3)(iii) of Regulation S-X states in part:
- Amortization shall be computed on the basis of physical units, with oil and gas converted to a common unit of measure on the basis of their approximate relative energy content, unless economic circumstances (related to the effects of regulated prices) indicate that use of units of revenue is a more appropriate basis of computing amortization. In the latter case, amortization shall be computed on the basis of current gross revenues (excluding royalty payments and net profits disbursements) from production in relation to future gross revenues based on current prices (including consideration of changes in existing prices provided only by contractual arrangements), from estimated production of proved oil and gas reserves.
- Question: May entities using the full cost method of accounting for oil and gas producing activities compute amortization based on the gross revenue method described in the above rule when substantial production is not subject to pricing regulation?
- Interpretive Response: Yes. Under the existing rules for cost amortization adopted in ASR 258, the use of the gross revenue method of amortization was permitted in those circumstances where, because of the effect of existing pricing regulations, the use of the units of production method would result in an amortization provision that would be inconsistent with the current prices being received. While the effect of regulation on gas prices has lessened, factors other than price regulation (such as changes in typical contract lengths and methods of marketing natural gas) have caused oil and gas prices to be disproportionate to their relative energy content. The staff therefore believes that it may be more appropriate for registrants to compute amortization based on the gross revenue method whenever oil and gas sales prices are disproportionate to their relative energy content to the extent that the use of the units of production method would result in an improper matching of the costs of oil and gas production against the related revenue received. The method should be consistently applied and appropriately disclosed within the financial statements.
##### [360-932-S99-4](https://asc.understandingaccounting.org/asc/360/932/#360-932-S99-4)
Pending content: no
Source downloaded (UTC): 2026-09-10T00:09:33.153Z to 2026-09-10T00:09:33.153Z
Record version: sha256:859dd90473b1d0702be1220265d55bca1a1ee4ee3e9819f222812d425b70a586
Snapshot version: sha256:15aea8165dff9f5ae47d9484f8470588b13b307f56e1d50801bf4d85ec190e3f
Effective as of: not established by retrieval timestamps.
The following is the text of SAB Topic 12.G, Inclusion of Methane Gas in Proved Reserves.
- Facts: Because of a concern over worldwide oil and gas supplies, Congress, in 1980, provided for tax incentives (credits) for the production of oil and gas from other than conventional sources. As a consequence, significant amounts of gas are now recovered from seams of coal beds. This gas is referred to as coalbed methane. It is produced using conventional drilling methods, but for various reasons, it may be more costly to produce than oil and gas recovered from customary sources and some reserves may not be economical without the tax credits.
- Rule 4-10(a)(1)(i)(A) of Regulation S-X indicates that oil and gas producing activities include the search for crude oil, including condensate and natural gas liquids, or natural gas in their natural states and original locations. Rule 4-10(a)(2)(iii)(D) of Regulation S-X states that estimates of proved reserves do not include (among other things) natural gas that can be recovered from coal. FN5 In addition, the definition of proved oil and gas reserves includes a provision that the quantities of natural gas be recovered from existing reservoirs. Under these definitions, "coalbed methane" gas has generally not been included in the disclosures in Commission filings required by Statement 69. Further, coalbed methane has generally not been counted in proved oil and gas reserves for purposes of the full cost ceiling test in Rule 4-10(c)(4) since that test is based on the same definition of proved oil and gas reserves.
- FN5 Similar language appears in Statements 19 and 25 \[paragraph [932-10-15-3](https://asc.understandingaccounting.org/asc/932/10/#932-10-15-3)\].
- Question: Is it appropriate to consider coalbed methane gas within the definition of proved reserves for purposes of the disclosures relating to oil and gas producing activities and the full cost ceiling test?
- Interpretive Response: Yes. The prohibition against the inclusion of gas derived from coal was meant to apply to the recovery of hydrocarbons from the processing of coal. The extraction of methane gas from coalbed seams using conventional methods was not contemplated at the time Rule 4-10(a) was developed. The staff believes that, since coalbed methane gas can be recovered from coal in its natural state and original location, it should be included in proved reserves, provided that it complies in all other respects with the definition of proved oil and gas reserves as specified in Rule 4-10(a)(2) including the requirement that methane production be economical at current prices, costs (net of the tax credit) and existing operating conditions. FN6 Methane gas from coalbeds (like any other hydrocarbon obtained from conventional reservoirs) that cannot be produced at a profit under current economic and operating conditions, or for which there is no market or any existing method of delivery to the market, cannot be included in the category of proved reserves.
- FN6 Proved oil and gas reserves are the estimated quantities of crude oil, natural gas, and natural gas liquids which geological and engineering data demonstrate with reasonable certainty to be recoverable in future years from known reservoirs under existing economic and operating conditions. (Emphasis added.).
- In instances where methane gas is deemed to be economically producible only as a consequence of existing Federal tax incentives, the staff believes that additional disclosure should be provided as to the specific quantities and values of reported proved reserves that are dependent on existing U.S. tax policy together with any other information necessary to inform readers of the risks attendant with any future change to existing Federal tax policy.