ASC 235-944
Financial Services—Insurance
235 Notes to Financial Statements
Source downloaded: .Record version 11f51c01b1a5. Effective date must be checked in the source.
235-944-S00StatusSEC
Source downloaded: .Record version 6e13c785fa3c. Effective date must be checked in the source.
235-944-S00-1
The following table identifies the changes made to this Subtopic.
| Paragraph | Action | Accounting Standards Update | Date |
| Amended | Accounting Standards Update No. 2019-07 | 07/26/2019 |
235-944-S50DisclosureSEC
Source downloaded: .Record version 8b4675cea22c. Effective date must be checked in the source.
Supplemental Schedules
235-944-S50-1
See paragraph 946-320-S99-7, Regulation S-X Rule 12-15, for the requirements of Schedule I—Summary of Investments—Other than Investments in Related Parties.
235-944-S50-2
See paragraph 235-10-S99-3, Regulation S-X Rule 12-04, for the requirements of Schedule II—Condensed Financial Information of Registrant.
235-944-S50-3
See paragraph 944-235-S99-1, Regulation S-X Rule 12-16, for the requirements of Schedule III—Supplementary Insurance Information.
235-944-S50-4
See paragraph 944-235-S99-2, Regulation S-X Rule 12-17, for the requirements of Schedule IV—Reinsurance
235-944-S50-5
See paragraph 235-10-S99-4, Regulation S-X Rule 12-09, for the requirements of Schedule V—Valuation and Qualifying Accounts.
235-944-S50-6
See paragraph 944-235-S99-3, Regulation S-X Rule 12-18, for the requirements of Schedule VI—Supplemental Information Concerning Property-Casualty Insurance Operations.
235-944-S99SEC MaterialsSEC
Source downloaded: .Record version 2526de10717a. Effective date must be checked in the source.
SEC Rules, Regulations, and Interpretations
235-944-S99-1
The following is the text of Regulation S-X Rule 12-16, Supplementary Insurance Information (17 CFR 210.12-16).
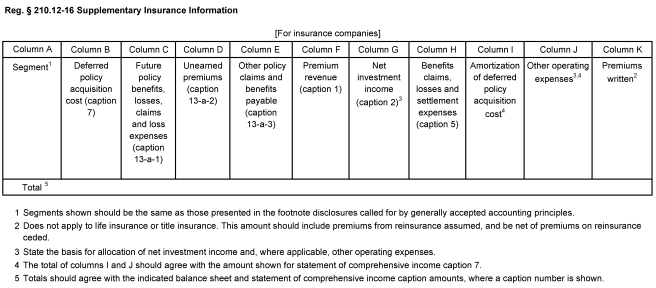 Reg. § 210.12-16 Supplementary Insurance Information [For insurance companies] Column A Column B Column C Column D Column E Column F Column G Column H Column I Column J Column K Segment1 Deferred policy acquisition cost (caption 7) "Future policy benefits, losses, claims and loss expenses (caption 13-a-1) " Unearned premiums (caption 13-a-2) " Other policy claims and benefits payable (caption 13-a-3) " Premium revenue (caption 1) Net investment income (caption 2)3 "Benefits claims, losses and settlement expenses (caption 5) " Amortiza-tion of deferred policy acquisition cost4 "Other operating expenses3,4" Premiums written2 Total 5 1 Segments shown should be the same as those presented in the footnote disclosures called for by generally accepted accounting principles. 2 "Does not apply to life insurance or title insurance. This amount should include premiums from reinsurance assumed, and be net of premiums on reinsurance ceded." 3 "State the basis for allocation of net investment income and, where applicable, other operating expenses." 4 The total of columns I and J should agree with the amount shown for statement of comprehensive income caption 7. 5 "Totals should agree with the indicated balance sheet and statement of comprehensive income caption amounts, where a caption number is shown."
235-944-S99-2
The following is the text of Regulation S-X Rule 12-17, Reinsurance (17 CFR 210.12-17).
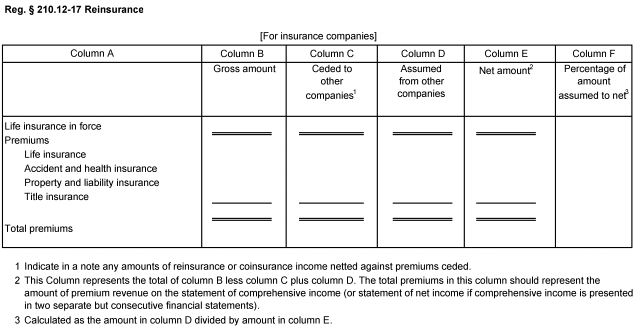 Reg. § 210.12-17 Reinsurance [For insurance companies] Column A Column B Column C Column D Column E Column F Gross amount Ceded to other companies1 "Assumed from other companies" Net amount2 Percentage of amount assumed to net3 Life insurance in force Premiums Life insurance Accident and health insurance Property and liability insurance Title insurance Total premiums 1 Indicate in a note any amounts of reinsurance or coinsurance income netted against premiums ceded. 2 This Column represents the total of column B less column C plus column D. The total premiums in this column should represent the amount of premium revenue on the statement of comprehensive income (or statement of net income if comprehensive income is presented in two separate but consecutive financial statements). 3 Calculated as the amount in column D divided by amount in column E. 3 Calculated as the amount in column D divided by amount in column E.
235-944-S99-3
The following is the text of Regulation S-X Rule 12-18, Supplemental Information (for Property-Casualty Insurance Underwriters) (17 CFR 210.12-18).
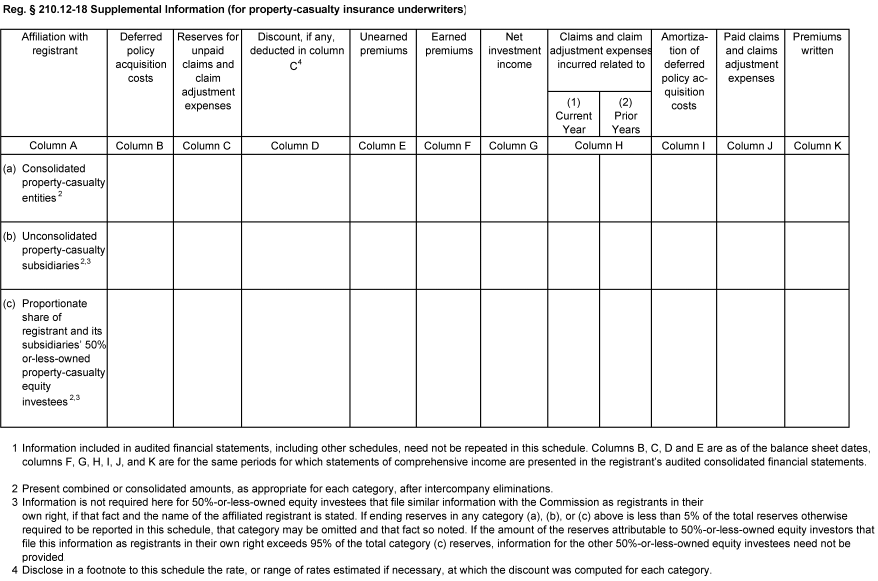 Reg. § 210.12-18 Supplemental Information (for property-casualty insurance underwriters) Affiliation with registrant Deferred policy acquisition costs Reserves for unpaid claims and claim adjustment expenses "Discount, if any, deducted in column C4 " Unearned premiums Earned premiums Net investment income Claims and claim adjustment expenses incurred related to Amortiza-tion of deferred policy ac-quisition costs Paid claims and claims adjustment expenses Premiums written "(1) Current Year " "(2) Prior Years" Column A Column B Column C Column D Column E Column F Column G Column H Column I Column J Column K (a) "Consolidated property-casualty entities 2" (b) "Unconsolidated property-casualty subsidiaries 2,3" (c) "Proportionate share of registrant and its subsidiaries' 50%-or-less-owned property-casualty equity investees 2,3" 1 "Information included in audited financial statements, including other schedules, need not be repeated in this schedule. Columns B, C, D and E are as of the balance sheet dates, columns F, G, H, I, J, and K are for the same periods for which statements of comprehensive income are presented in the registrant's audited consolidated financial statements." 2 "Present combined or consolidated amounts, as appropriate for each category, after intercompany eliminations." 3 "Information is not required here for 50%-or-less-owned equity investees that file similar information with the Commission as registrants in their own right, if that fact and the name of the affiliated registrant is stated. If ending reserves in any category (a), (b), or (c) above is less than 5% of the total reserves otherwise required to be reported in this schedule, that category may be omitted and that fact so noted. If the amount of the reserves attributable to 50%-or-less-owned equity investors that file this information as registrants in their own right exceeds 95% of the total category (c) reserves, information for the other 50%-or-less-owned equity investees need not be provided." 4 "Disclose in a footnote to this schedule the rate, or range of rates estimated if necessary, at which the discount was computed for each category."
Related subtopics
- 944-10 OverallFinancial Services—Insurance
- 225-944 Financial Services—InsuranceIncome Statement
- 220-944 Financial Services—InsuranceIncome Statement—Reporting Comprehensive Income
- 210-944 Financial Services—InsuranceBalance Sheet
- 225-942 Financial Services—Depository and LendingIncome Statement
- 235-946 Financial Services—Investment CompaniesNotes to Financial Statements