ASC 235-932
Extractive Activities—Oil and Gas
235 Notes to Financial Statements
Source downloaded: .Record version f2088a724b6d. Effective date must be checked in the source.
ASC 932-235 sets the note and supplemental disclosure requirements for entities with oil- and gas-producing activities. All such entities must disclose their cost accounting method (successful efforts vs. full cost), how capitalized costs are disposed of, and information about exploratory well costs still capitalized pending determination of proved reserves. Publicly traded companies with significant oil and gas activities must additionally provide, as supplementary information with annual statements, proved reserve quantities and changes, capitalized costs, costs incurred, results of operations, the standardized measure of discounted future net cash flows, and changes in that measure.
Key points (7)
- All entities engaged in oil- and gas-producing activities must disclose the method of accounting for costs incurred and the manner of disposing of capitalized costs (932-235-50-1).
- Continued capitalization of exploratory well costs is a required note disclosure (expressly not supplementary): amounts pending determination of proved reserves with a rollforward of additions, reclassifications to wells/equipment, and charges to expense; amounts capitalized more than one year after completion of drilling with an aging and project count; and a description of the projects and remaining activities needed to classify reserves as proved (932-235-50-1A through 50-1B).
- Publicly traded companies with significant oil- and gas-producing activities must disclose, as supplementary information with complete annual financial statements, the seven categories listed in 932-235-50-2.
- Net proved, proved developed, and proved undeveloped reserve quantities of oil, gas, synthetic oil/gas, and other nonrenewable resources must be disclosed at the beginning and end of year, with changes broken out by revisions of previous estimates, improved recovery, purchases of minerals in place, extensions and discoveries, production, and sales of minerals in place (932-235-50-4 through 50-5).
- Reserve, cost, results-of-operations, and standardized measure disclosures must be presented in the aggregate and separately by geographic area, at a minimum for each country containing 15 percent or more of proved reserves on an oil-equivalent-barrels basis (932-235-50-6 through 50-6B).
- Results of operations for oil- and gas-producing activities equal revenues less production (lifting) costs, exploration expenses, DD&A and valuation provisions, and income taxes at the statutory rate, excluding general corporate overhead and interest costs (932-235-50-23 through 50-26).
- The standardized measure applies prices used in estimating proved reserves to year-end quantities, subtracts future development and production costs at year-end costs and future income taxes at year-end statutory rates, and discounts at 10 percent per year; equity method investee amounts are generally disclosed separately from consolidated entities (932-235-50-31, 50-33).
For students. This is the classic supplemental oil and gas disclosure package presented with E&P company financial statements; the standardized measure is a prescribed computation (reserve-estimation prices, year-end costs, 10% discount) and is not the fair value of the reserves. A common mistake is treating the exploratory well cost disclosures as supplementary—932-235-50-1A makes them required notes for all entities with oil and gas activities, not just public companies.
Machine-generated study aid for ASC 235-932. Check the source paragraphs below.
235-932-00Status
Source downloaded: .Record version 3195cb9adb57. Effective date must be checked in the source.
235-932-05Overview and Background
Source downloaded: .Record version 32a4da1defe1. Effective date must be checked in the source.
- aProved oil and gas reserve quantities (see paragraphs )
- bCapitalized costs relating to oil- and gas-producing activities (see paragraphs )
- cContinued capitalization of exploratory well costs (see paragraphs )
- dCosts incurred for property acquisition, exploration, and development (see paragraphs )
- eResults of operations of oil- and gas-producing activities (see paragraphs )
- fA standardized measure of discounted future net cash flows related to proved oil and gas reserve quantities (see paragraphs )
235-932-10Objectives
Source downloaded: .Record version 72bd688760e0. Effective date must be checked in the source.
235-932-15Scope and Scope Exceptions
Source downloaded: .Record version 2f4d06aec9ea. Effective date must be checked in the source.
Overall Guidance
235-932-50Disclosure
Source downloaded: .Record version 83b65cd4ca1d. Effective date must be checked in the source.
All Entities
- a The amount of capitalized exploratory well costs that is pending the determination of proved reserves. An entity also shall separately disclose for each annual period that an income statement is presented changes in those capitalized exploratory well costs resulting from all of the following:
- 1 Additions to capitalized exploratory well costs that are pending the determination of proved reserves
- 2 Capitalized exploratory well costs that were reclassified to wells, equipment, and facilities based on the determination of proved reserves
- 3 Capitalized exploratory well costs that were charged to expense.
This disclosure shall not include amounts that were capitalized and subsequently expensed in the same annual period. - 1
- b The amount of exploratory well costs that have been capitalized for a period of greater than one year after the completion of drilling at the most recent balance sheet date and the number of projects for which those costs relate. Additionally, for exploratory well costs that have been capitalized for periods greater than one year at the most recent balance sheet date, an entity shall provide an aging of those amounts by year, or by using a range of years, and the number of projects to which those costs relate.
- c For exploratory well costs that continue to be capitalized for more than one year after the completion of drilling at the most recent balance sheet date, a description of the projects and the activities that the entity has undertaken to date in order to evaluate the reserves and the projects, and the remaining activities required to classify the associated reserves as proved.
Publicly Traded Companies
- a The entity's equity method investments were acquired before December 31, 2009.
- b After making an exhaustive effort, the entity is unable to obtain the information necessary to provide the required disclosures.
- a Proved oil and gas reserve quantities (see paragraphs 932-235-50-3 through 50-11B)
- b Capitalized costs relating to oil- and gas-producing activities (see paragraphs )
- c
- d Costs incurred for property acquisition, exploration, and development activities (see paragraphs )
- e Results of operations for oil- and gas-producing activities (see paragraphs )
- f A standardized measure of discounted future net cash flows relating to proved oil and gas reserve quantities (see paragraphs )
- g Changes in the standardized measure of discounted future net cash flows (see paragraphs ).
- a Information that relates to annual periods for each annual period for which a statement of comprehensive income is required
- b Information required as of the end of an annual period for which a balance sheet is required
- c Information required as of the beginning of an annual period for each annual period for which a statement of comprehensive income is required.
- a Crude oil, including condensate and natural gas liquids (If significant, the reserve quantity information shall be disclosed separately for natural gas liquids.)
- b Natural gas
- c Synthetic oil
- d Synthetic gas
- e Other nonrenewable natural resources that are intended to be upgraded into synthetic oil and gas.
- a Revisions of previous estimates. Revisions represent changes in previous estimates of proved reserves, either upward or downward, resulting from new information (except for an increase in proved acreage) normally obtained from development drilling and production history or resulting from a change in economic factors.
- b Improved recovery. Changes in reserve estimates resulting from application of improved recovery techniques shall be shown separately, if significant. If not significant, such changes shall be included in revisions of previous estimates.
- c Purchases of minerals in place.
- d Extensions and discoveries. Additions to proved reserves that result from either of the following:
- 1 Extension of the proved acreage of previously discovered (old) reservoirs through additional drilling in periods subsequent to discovery
- 2 Discovery of new fields with proved reserves or of new reservoirs of proved reserves in old fields.
- 1
- e Production.
- f Sales of minerals in place.
- a An individual country
- b A group of countries within a continent
- c A continent.
- a An entity shall consider all facts and circumstances and not solely the quantity of reserves.
- b At a minimum, net quantities of reserves shall be presented in the aggregate and separately by geographic area and for each country containing 15 percent or more of an entity's proved reserves, expressed on an oil-equivalent-barrels basis.
- a If the entity issues consolidated financial statements, 100 percent of the net reserve quantities attributable to the parent and 100 percent of the net reserve quantities attributable to its consolidated subsidiaries (whether or not wholly owned) shall be included. If a significant portion of those reserve quantities at the end of the year is attributable to a consolidated subsidiary or subsidiaries in which there is a significant noncontrolling interest, that fact and the approximate portion shall be disclosed.
- b If the entity's financial statements include investments that are proportionately consolidated, the entity's reserve quantities shall include its proportionate share of the investees' net oil and gas reserves.
- c If the entity's financial statements include investments that are accounted for by the equity method, the entity shall separately disclose the net reserve quantities required by paragraphs for both of the following:
- 1 Consolidated entities
- 2 The entity's share of equity method investees.
The entity may, in addition to separate disclosure, disclose a combined total for items (1) and (2) for each of the quantities required to be disclosed by this paragraph. - 1
- a The government of a country containing reserves prohibits disclosing reserves in that country.
- b The government of a country containing reserves prohibits disclosing a particular field, and disclosing reserves in that country would have the effect of disclosing reserves in particular fields.
- a Consolidated entities
- b The entity's share of equity method investees.
- a Property acquisition costs
- b Exploration costs
- c Development costs.
- a Consolidated entities
- b The entity's share of equity method investees.
- a Revenues (see the following paragraph)
- b Production (lifting) costs
- c Exploration expenses (Generally, only entities utilizing the successful efforts accounting method will have exploration expenses to disclose, since entities utilizing the full cost accounting method generally capitalize all exploration costs when incurred and subsequently reflect those costs in the determination of earnings through depreciation, depletion, and amortization, and valuation provisions.)
- d Depreciation, depletion, and amortization, and valuation provisions
- e Income tax expenses (see paragraph 932-235-50-25)
- f Results of operations for oil- and gas-producing activities (excluding corporate overhead and interest costs) (see paragraphs ).
- a Consolidated entities
- b The entity's share of equity method investees.
- a Proved oil and gas reserves (see paragraphs 932-235-50-3 through 50-11B)
- b Oil and gas subject to purchase under long-term supply, purchase, or similar agreements and contracts in which the entity participates in the operation of the properties on which the oil or gas is located or otherwise serves as the producer of those reserves (see paragraph 932-235-50-7).
- a Future cash inflows. These shall be computed by applying prices used in estimating the entity's proved oil and gas reserves to the year-end quantities of those reserves. Future price changes shall be considered only to the extent provided by contractual arrangements in existence at year-end.
- b Future development and production costs. These costs shall be computed by estimating the expenditures to be incurred in developing and producing the proved oil and gas reserves at the end of the year, based on year-end costs and assuming continuation of existing economic conditions. If estimated development expenditures are significant, they shall be presented separately from estimated production costs.
- c Future income tax expenses. These expenses shall be computed by applying the appropriate year-end statutory tax rates, with consideration of future tax rates already legislated, to the future pretax net cash flows relating to the entity's proved oil and gas reserves, less the tax basis of the properties involved. The future income tax expenses shall give effect to tax deductions and tax credits and allowances relating to the entity's proved oil and gas reserves.
- d Future net cash flows. These amounts are the result of subtracting future development and production costs and future income tax expenses from future cash inflows.
- e Discount. This amount shall be derived from using a discount rate of 10 percent a year to reflect the timing of the future net cash flows relating to proved oil and gas reserves.
- f Standardized measure of discounted future net cash flows. This amount is the future net cash flows less the computed discount.
- a Consolidated entities
- b The entity's share of equity method investees.
- a Net change in sales and transfer prices and in production (lifting) costs related to future production
- b Changes in estimated future development costs
- c Sales and transfers of oil and gas produced during the period
- d Net change due to extensions, discoveries, and improved recovery
- e Net change due to purchases and sales of minerals in place
- f Net change due to revisions in quantity estimates
- g Previously estimated development costs incurred during the period
- h Accretion of discount
- i Other—unspecified
- j Net change in income taxes.
- a Consolidated entities
- b The entity's share of equity method investees.
235-932-55Implementation Guidance and Illustrations
Source downloaded: .Record version c624144d944b. Effective date must be checked in the source.
Illustrations
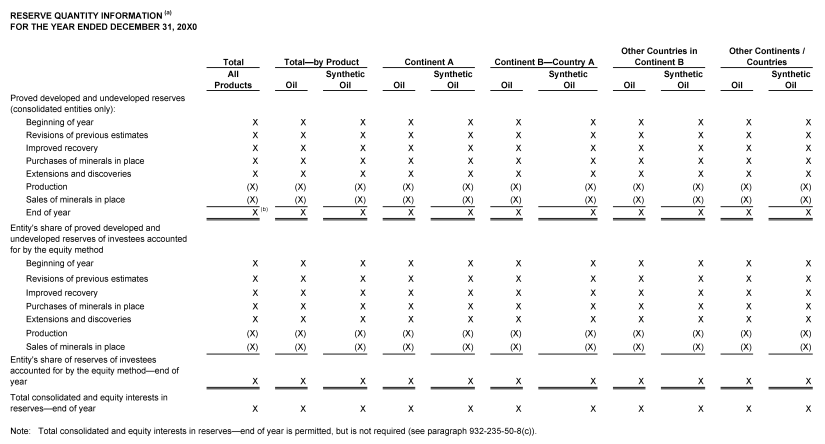 "RESERVE QUANTITY INFORMATION (a) FOR THE YEAR ENDED DECEMBER 31, 20X0" Total Total—by product Continent A Continent B—Country A Other Countries in Continent B Other Continents / Countries Oil All Products Synthetic Oil Oil Synthetic Oil Oil "Synthetic Oil" Oil Synthetic Oil Oil Synthetic Oil Proved developed and undeveloped reserves (consolidated entities only): Beginning of year X X X X X X X X X X X "Revisions of previous estimates " X X X X X X X X X X X Improved recovery X X X X X X X X X X X Purchases of minerals in place X X X X X X X X X X X Extensions and discoveries X X X X X X X X X X X Production (X) (X) (X) (X) (X) (X) (X) (X) (X) (X) (X) Sales of minerals in place (X) (X) (X) (X) (X) (X) (X) (X) (X) (X) (X) End of year X (b) X X X X X X X X X X Entity's share of proved developed and undeveloped reserves of investees accounted for by the equity method Beginning of the year X X X X X X X X X X X Revisions of previous estimates X X X X X X X X X X X Improved recovery X X X X X X X X X X X Purchases of minerals in place X X X X X X X X X X X Extensions and discoveries X X X X X X X X X X X Production (X) (X) (X) (X) (X) (X) (X) (X) (X) (X) (X) Sales of minerals in place (X) (X) (X) (X) (X) (X) (X) (X) (X) (X) (X) Entity's share of reserves of investees accounted for by the equity method—end of year X X X X X X X X X X X Total consolidated and equity interests in reserves—end of year X X X X X X X X X X X "Note: Total consolidated and equity interests in reserves—end of year is permitted, but is not required (see paragraph 932-235-50-6(c))."
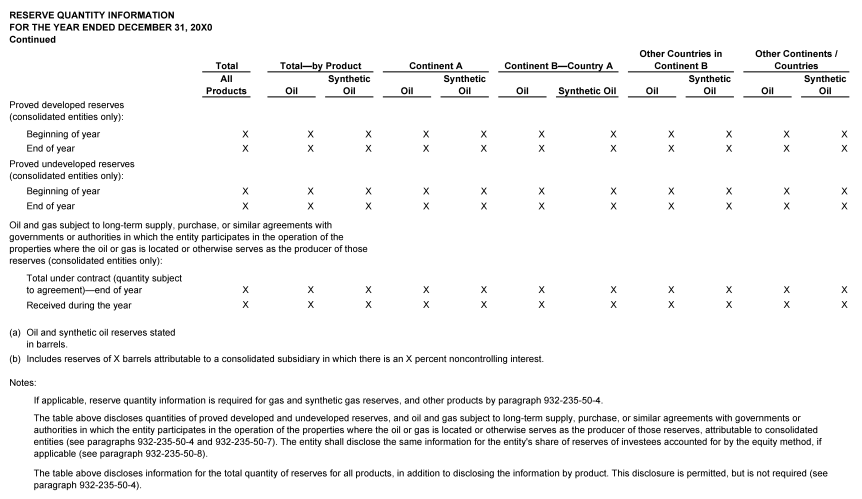 "RESERVE QUANTITY INFORMATION FOR THE YEAR ENDED DECEMBER 31, 20X0 Continued" Total Total—by product Continent A Continent B—Country A Other Countries in Continent B Other Continents / Countries All Products Oil Synthetic Oil Oil Synthetic Oil Oil Synthetic Oil Oil Synthetic Oil Oil Synthetic Oil Proved developed reserves (consolidated entities only): Beginning of year X X X X X X X X X X X End of year X X X X X X X X X X X Proved undeveloped reserves (consolidated entities only): Beginning of year X X X X X X X X X X X End of year X X X X X X X X X X X "Oil and gas subject to long-term supply, purchase, or similar agreements with governments or authorities in which the entity participates in the operation of the properties where the oil or gas is located or otherwise serves as the producer of those reserves (consolidated entities only):" Total under contract (quantity subject to agreement)—end of year X X X X X X X X X X X Received during the year X X X X X X X X X X X (a) Oil and synthetic oil reserves stated in barrels. (b) Includes reserves of X barrels attributable to a consolidated subsidiary in which there is an X percent noncontrolling interest. Notes: "If applicable, reserve quantity information is required for gas and synthetic gas reserves, and other products by paragraph 932-235-50-4. " "The table above discloses quantities of proved developed and undeveloped reserves, and oil and gas subject to long-term supply, purchase, or similar agreements with governments or authorities in which the entity participates in the operation of the properties where the oil or gas is located or otherwise serves as the producer of those reserves, attributable to consolidated entities (see paragraphs 932-235-50-4 and 50-7). The entity shall disclose the same information for the entity's share of reserves of investees accounted for by the equity method, if applicable (see paragraph 932-235-50-8)." "The table above discloses information for the total quantity of reserves for all products, in addition to disclosing the information by product. This disclosure is permitted, but is not required (see paragraph 932-235-50-4)."
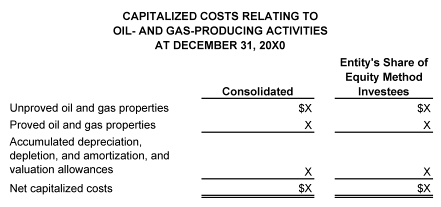 "CAPITALIZED COSTS RELATING TO OIL- AND GAS-PRODUCING ACTIVITIES AT DECEMBER 31, 20X0" Consolidated Entity's Share of Equity Method Investees Unproved oil and gas properties $X $X Proved oil and gas properties X X X X "Accumulated depreciation, depletion, and amortization, and valuation allowances" X X Net capitalized costs $X $X
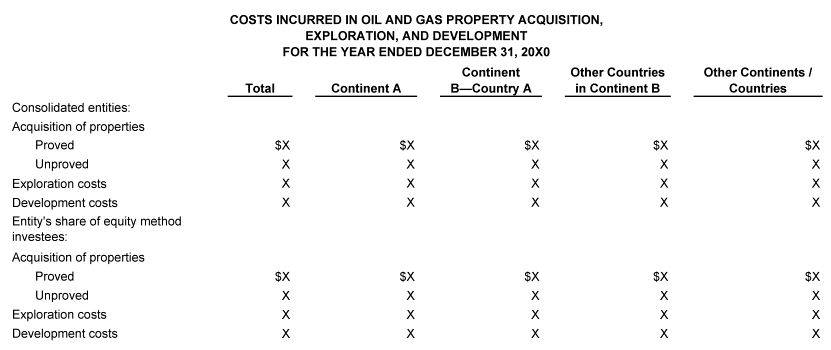 "COSTS INCURRED IN OIL AND GAS PROPERTY ACQUISITION, EXPLORATION, AND DEVELOPMENT FOR THE YEAR ENDED DECEMBER 31, 20X0" Total Continent A Continent B—Country A Other Countries in Continent B Other Continents / Countries Consolidated entities: Acquisition of properties Proved $X $X $X $X $X Unproved X X X X X Exploration costs X X X X X Development costs X X X X X Entity's share of equity method investees: Acquisition of properties Proved $X $X $X $X $X Unproved X X X X X Exploration costs X X X X X Development costs X X X X X
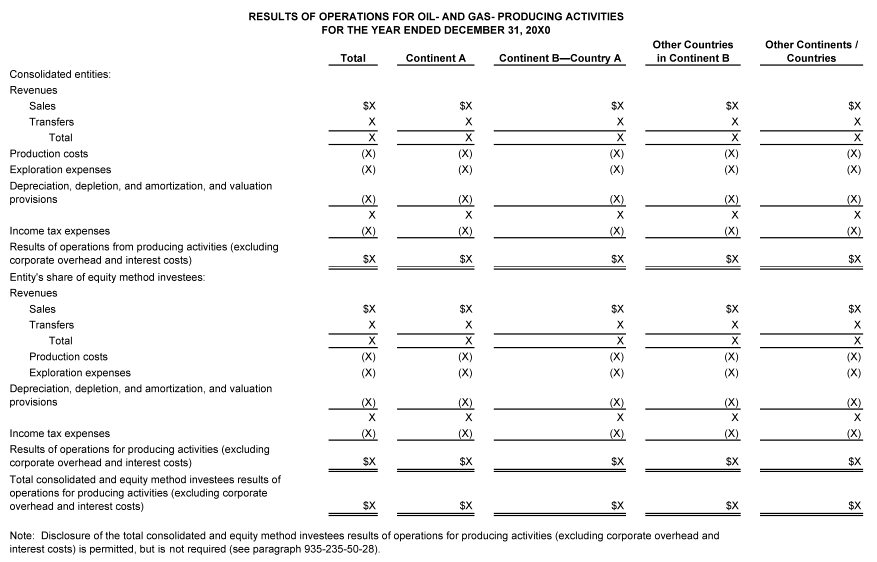 "RESULTS OF OPERATIONS FOR OIL- AND GAS- PRODUCING ACTIVITIES FOR THE YEAR ENDED DECEMBER 31, 20X0" Total Continent A Continent B—Country A Other Countries in Continent B Other Continents / Countries Consolidated entities: Revenues Sales $X $X $X $X $X Transfers X X X X X Total X X X X X Production costs (X) (X) (X) (X) (X) Exploration expenses (X) (X) (X) (X) (X) "Depreciation, depletion, and amortization, and valuation provisions" (X) (X) (X) (X) (X) X X X X X Income tax expenses (X) (X) (X) (X) (X) Results of operations from producing activities (excluding corporate overhead and interest costs) $X $X $X $X $X Entity's share of equity method investees: Revenues Sales $X $X $X $X $X Transfers X X X X X Total X X X X X Production costs (X) (X) (X) (X) (X) Exploration expenses (X) (X) (X) (X) (X) "Depreciation, depletion, and amortization, and valuation provisions" (X) (X) (X) (X) (X) X X X X X Income tax expenses (X) (X) (X) (X) (X) Results of operations for producing activities (excluding corporate overhead and interest costs) $X $X $X $X $X Total consolidated and equity method investees results of operations for producing activities (excluding corporate overhead and interest costs) $X $X $X $X $X "Note: Disclosure of the total consolidated and equity method investees results of operations for producing activities (excluding corporate overhead and interest costs) is permitted, but not required (see paragraph 935-235-50-28)."
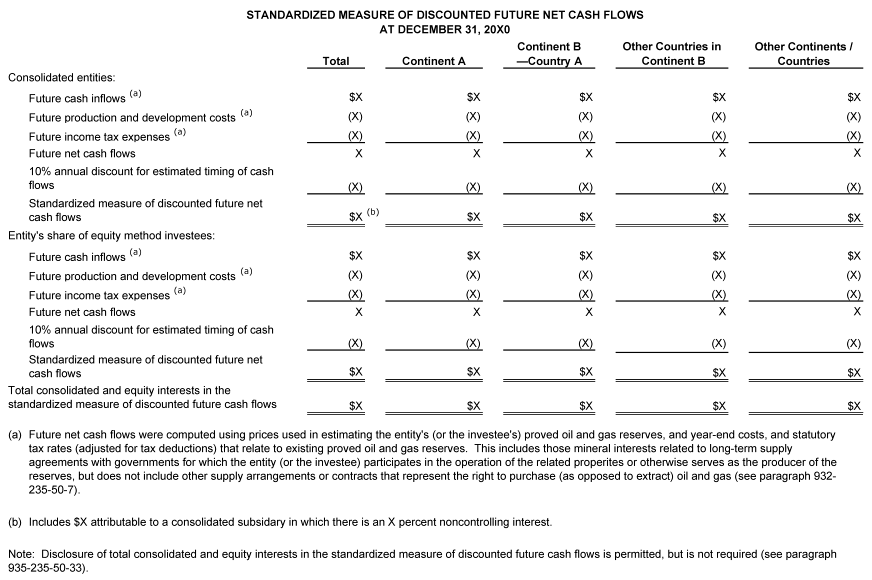 "STANDARDIZED MEASURE OF DISCOUNTED FUTURE NET CASH FLOWS AT DECEMBER 31, 20X0" Total Continent A Continent B —Country A "Other Countries in Continent B " Other Continents / Countries Consolidated entities: Future cash inflows (a) $X $X $X $X $X Future production and development costs (a) (X) (X) (X) (X) (X) Future income tax expenses (a) (X) (X) (X) (X) (X) Future net cash flows X X X X X 10% annual discount for estimated timing of cash flows (X) (X) (X) (X) (X) Standardized measure of discounted future net cash flows $X (b) $X $X $X $X Entity's share of equity method investees: Future cash inflows (a) $X $X $X $X $X Future production and development costs (a) (X) (X) (X) (X) (X) Future income tax expenses (a) (X) (X) (X) (X) (X) Future net cash flows X X X X X 10% annual discount for estimated timing of cash flows (X) (X) (X) (X) (X) Standardized measure of discounted future net cash flows $X $X $X $X $X Total consolidated and equity interests in the standardized measure of discounted future cash flows $X $X $X $X $X (a) "Future net cash flows were computed using prices used in estimating the entity's (or the investee's) proved oil and gas reserves, and year-end costs, and statutory tax rates (adjusted for tax deductions) that relate to existing proved oil and gas reserves. This includes those mineral interests related to long-term supply agreements with governments for which the entity (or the investee) participates in the operation of the related properites or otherwise serves as the producer of the reserves, but does not include other supply arrangements or contracts that represent the right to purchase (as opposed to extract) oil and gas (see paragraph 932-235-50-7)." (b) Includes $X attributable to a consolidated subsidary in which there is an X percent noncontrolling interest. "Note: Disclosure of total consolidated and equity interests in the standardized measure of discounted future cash flows is permitted, but is not required (see paragraph 935-235-50-33)."
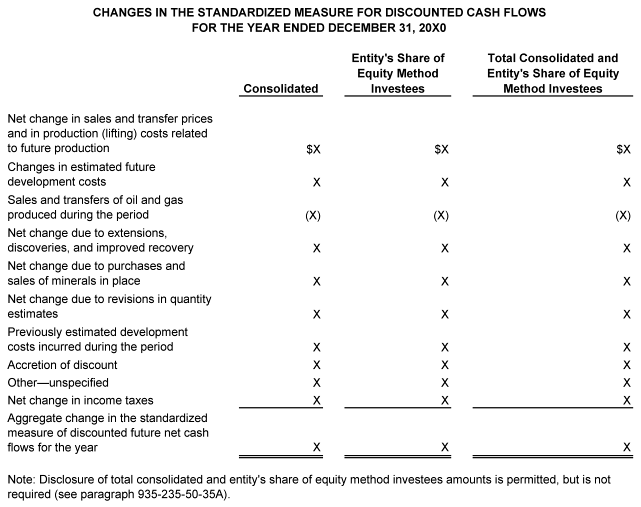 "CHANGES IN THE STANDARDIZED MEASURE FOR DISCOUNTED CASH FLOWS FOR THE YEAR ENDED DECEMBER 31, 20X0 " Consolidated Entity's Share of Equity Method Investees Total Consolidated and Entity's Share of Equity Method Investees Net change in sales and transfer prices and in production (lifting) costs related to future production $X $X $X Changes in estimated future development costs X X X Sales and transfers of oil and gas produced during the period (X) (X) (X) "Net change due to extensions, discoveries, and improved recovery" X X X Net change due to purchases and sales of minerals in place X X X Net change due to revisions in quantity estimates X X X Previously estimated development costs incurred during the period X X X Accretion of discount X X X Other—unspecified X X X Net change in income taxes X X X Aggregate change in the standardized measure of discounted future net cash flows for the year X X X "Note: Disclosure of total consolidated and entity's share of equity method investees amounts is permitted, but is not required (see paragraph 935-235-50-35A)."
235-932-S00StatusSEC
Source downloaded: .Record version f66ec296aeb4. Effective date must be checked in the source.
| Paragraph | Action | Accounting Standards Update | Date |
| 932-235-S99-1 | Amended | Accounting Standards Update No. 2012-03 | 08/27/2012 |
235-932-S50DisclosureSEC
Source downloaded: .Record version 68ebbf2d97b9. Effective date must be checked in the source.
Disclosures Related to Oil- and Gas-Producing Activities
235-932-S99SEC MaterialsSEC
Source downloaded: .Record version 4f1160c62099. Effective date must be checked in the source.
SEC Staff Guidance
- c. Limited partnership 10-K reports.
- Facts: Securities Act Industry Guide 2 contains an exemption from the requirements of the Guide to disclose certain information relating to oil and gas operations for "limited partnerships or joint ventures that conduct, operate, manage, or report upon oil and gas drilling income programs which acquire properties either for drilling and production, or for production of oil, gas, or geothermal steam."
- Limited partnership agreements often contain buy-out provisions under which the general partner agrees to purchase limited partnership interests that are offered for sale, based upon a specified valuation formula. Because of these arrangements, the requirements for disclosure of reserve value information may be of little significance to the limited partners.
- Question: Must the financial statements of limited partnerships included in reports on Form 10-K contain the disclosures of estimated future net revenues, present values and changes therein, and supplemental summary of oil and gas activities specified by in FASB ASC paragraphs (Extractive Activities—Oil and Gas Topic)?
- Interpretive Response: The staff will not take exception to the omission of these disclosures in a limited partnership Form 10-K if reserve value information is available to the limited partners pursuant to the partnership agreement (even though the valuations may be computed differently and may be as of a date other than year end). However, the staff will require all of the information listed in FASB ASC paragraphs for partnerships which are the subject of a merger or exchange offer under which various limited partnerships are to be combined into a single entity.
- e. Rate regulated companies.
- Question: If a company has cost-of-service oil and gas producing properties, how should they be treated in the supplemental disclosures of reserve quantities and related future net revenues provided pursuant to FASB ASC paragraphs ?
- Interpretive Response: Rule 4-10 provides that registrants may give effect to differences arising from the ratemaking process for cost-of-service oil and gas properties. Accordingly, in these circumstances, the staff believes that the company's supplemental reserve quantity disclosures should indicate separately the quantities associated with properties subject to cost-of-service ratemaking, and that it is appropriate to exclude those quantities from the future net revenue disclosures. The company should also disclose the nature and impact of its cost-of-service ratemaking, including the unamortized cost included in the balance sheet.