Updates
Accounting Standards Updates
310 items: final updates, proposals, and routine maintenance to the codification, grouped by year.
Accounting Standards Updates
Final ASUs that amend the codification.
2026
2026-01Accounting Standards Update 2026-01—Equity (Topic 505): Initial Measurement of Paid-in-Kind Dividends on Equity-Classified Preferred Stock505
The amendments in this Update improve generally accepted accounting principles by providing authoritative guidance on how an issuer should initially measure paid-in-kind dividends on equity-classified preferred stock.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2025-ED300—Equity (Topic 505): Initial Measurement of Paid-in-Kind Dividends on Equity-Classified Preferred Stock.
For more information, see the following:
Issued: April 23, 2026
2026-02Accounting Standards Update 2026-02—Environmental Credits and Environmental Credit Obligations (Topic 818)818
The amendments in this Update improve generally accepted accounting principles (GAAP) by providing specific authoritative guidance for environmental credits and environmental credit obligations.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2024-ED910—Environmental Credits and Environmental Credit Obligations (Topic 818), which has been deleted.
For more information, see the following:
Issued: May 19, 2026
2026-03Accounting Standards Update 2026-03—Fair Value Measurement (Topic 820): Investment Companies with Equity Securities Subject to Contractual Sale Restrictions820
For investment companies within the scope of Topic 946, Financial Services—Investment Companies, the amendments in this Update require that a contractual restriction on the sale of an equity security (such as a lock-up agreement) be considered in measuring fair value.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2026-ED300—Fair Value Measurement (Topic 820): Investment Companies with Equity Securities Subject to Contractual Sale Restrictions, which has been deleted.
For more information, see the following:
Issued: September 9, 2026
2025
2025-01Accounting Standards Update No. 2025-01—Income Statement—Reporting Comprehensive Income—Expense Disaggregation Disclosures (Subtopic 220-40): Clarifying the Effective Date220
The amendment in this Update clarifies the effective date of Update 2024-03, which is that public business entities are required to adopt the guidance in annual reporting periods beginning after December 15, 2026, and interim periods within annual reporting periods beginning after December 15, 2027.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2024-ED800—Income Statement—Reporting Comprehensive Income—Expense Disaggregation Disclosures (Subtopic 220-40): Clarifying the Effective Date, which has been deleted.
For more information, see the following:
Issued: January 6, 2025
2025-02Accounting Standards Update 2025-02—Liabilities (Topic 405): Amendments to SEC Paragraphs Pursuant to SEC Staff Accounting Bulletin No. 122405
The amendments in this Accounting Standards Update amend various SEC paragraphs pursuant to the issuance of SEC Staff Accounting Bulletin No. 122.
For more information, see the following:
Issued: March 18, 2025
2025-03Accounting Standards Update 2025-03—Business Combinations (Topic 805) and Consolidation (Topic 810): Determining the Accounting Acquirer in the Acquisition of a Variable Interest Entity805810
The amendments in this Update would enhance the comparability of financial statements across entities engaging in acquisition transactions effected primarily by exchanging equity interests when the legal acquiree meets the definition of a business.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2024-ED500—Business Combinations (Topic 805) and Consolidation (Topic 810): Determining the Accounting Acquirer in the Acquisition of a Variable Interest Entity, which has been deleted.
For more information, see the following:
Issued: May 12, 2025
2025-04Accounting Standards Update 2025-04—Compensation—Stock Compensation (Topic 718) and Revenue from Contracts with Customers (Topic 606): Clarifications to Share-Based Consideration Payable to a Customer606718
The amendments in this Update would reduce diversity in practice and improve the decision usefulness and operability of the guidance for share-based consideration granted to a customer in conjunction with selling goods or services.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2024-ED300—Compensation—Stock Compensation (Topic 718) and Revenue from Contracts with Customers (Topic 606), which has been deleted.
For more information, see the following:
Issued: May 15, 2025
2025-05Accounting Standards Update 2025-05—Financial Instruments–Credit Losses (Topic 326): Measurement of Credit Losses for Accounts Receivable and Contract Assets326
The amendments in this Update provide (1) all entities with a practical expedient and (2) entities other than public business entities with an accounting policy election when applying the guidance in Topic 326, Financial Instruments–Credit Losses, to current accounts receivable and current contract assets arising from transactions accounted for under Topic 606, Revenue from Contracts with Customers.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2024-ED900 Financial Instruments—Credit Losses (Topic 326): Measurement of Credit Losses for Accounts Receivable and Contract Assets for Private Companies and Certain Not-for-Profit Entities, which has been deleted.
For more information see the following:
Issued: July 30, 2025
2025-06Accounting Standards Update 2025-06—Intangibles—Goodwill and Other—Internal-Use Software (Subtopic 350-40): Targeted Improvements to the Accounting for Internal-Use Software350
The amendments in this Update make targeted improvements to Subtopic 350-40, Intangibles—Goodwill and Other—Internal-Use Software to increase the operability of the recognition guidance considering different methods of software development.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2024-ED400—Intangibles—Goodwill and Other—Internal-Use Software (Subtopic 350-40), which has been deleted.
For more information see the following:
Issued: September 18, 2025
2025-07Accounting Standards Update 2025-07—Derivatives and Hedging (Topic 815) and Revenue from Contracts with Customers (Topic 606): Derivatives Scope Refinements and Scope Clarification for Share-Based Noncash Consideration from a Customer in a Revenue Contract606815
The amendments in this Update address stakeholders’ concerns about (1) the application of derivative accounting to contracts with features based on the operations or activities of one of the parties to the contract and (2) the diversity in accounting for share-based noncash consideration from a customer that is consideration for the transfer of goods or services.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2024-ED100—Derivatives and Hedging (Topic 815) and Revenue from Contracts with Customers (Topic 606), which has been deleted.
For more information, see the following:
Issued: September 29, 2025
2025-08Accounting Standards Update 2025-08—Financial Instruments—Credit Losses (Topic 326): Purchased Loans326
The amendments in this Update expand the gross-up approach for initial recognition and measurement of acquired financial assets to purchased seasoned loans.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2023-ED400—Financial Instruments—Credit Losses (Topic 326): Purchased Financial Assets, which has been deleted.
For more information, see the following:
Issued: November 12, 2025
2025-09Accounting Standards Update 2025-09—Derivatives and Hedging (Topic 815): Hedge Accounting Improvements815
The amendments in this Update clarify certain aspects of the guidance on hedge accounting and address several incremental hedge accounting issues arising from global reference rate reform.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2024-ED200—Derivatives and Hedging (Topic 815): Hedge Accounting Improvements, which has been deleted.
For more information, see the following:
Issued: November 25, 2025
2025-10Accounting Standards Update 2025-10—Government Grants (Topic 832): Accounting for Government Grants Received by Business Entities832
The amendments in this Update improve generally accepted accounting principles (GAAP) by establishing authoritative guidance on the accounting for government grants received by business entities.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2024-ED700—Government Grants (Topic 832): Accounting for Government Grants by Business Entities, which has been deleted.
For more information, see the following:
Issued: December 4, 2025
2025-11Accounting Standards Update 2025-11—Interim Reporting (Topic 270): Narrow-Scope Improvements270
The amendments in this Update clarify interim disclosure requirements and the applicability of Topic 270.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2024-ED600—Interim Reporting (Topic 270): Narrow-Scope Improvements, which has been deleted.
For more information, see the following:
Issued: December 8, 2025
2025-12Accounting Standards Update 2025-12—Codification Improvements
The amendments in this Update address stakeholder suggestions on the Accounting Standards Codification and make other incremental improvements to generally accepted accounting principles (GAAP). The amendments make Codification updates to a broad range of Topics arising from technical corrections, unintended application of the Codification, clarifications, and other minor improvements.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2025-ED100—Codification Improvements, which has been deleted.
For more information, see the following:
Issued: December 17, 2025
2024
2024-01Accounting Standards Update No. 2024-01—Compensation—Stock Compensation (Topic 718)—Scope Application of Profits Interest and Similar Awards718
The amendments in this Update improve the clarity of paragraph 718-10-15-3 and its application to profits interest or similar awards, primarily through the addition of an illustrative example that includes four fact patterns.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2023-ED300—Compensation—Stock Compensation (Topic 718): Scope Application of Profits Interest Awards, which has been deleted.
For more information, see the following:
Issued: March 21, 2024
2024-02Accounting Standards Update No. 2024-02—Codification Improvements—Amendments to Remove References to the Concepts Statements
This Update contains amendments to the Codification that remove references to various FASB Concepts Statements. Removing all references to Concepts Statements in the guidance will simplify the Codification and draw a distinction between authoritative and nonauthoritative literature.
For more information, see the following:
Issued: March 29, 2024
2024-03Accounting Standards Update No. 2024-03—Income Statement—Reporting Comprehensive Income—Expense Disaggregation Disclosures (Subtopic 220-40)220
The amendments in this Update require a public business entity to disclose specific information about certain costs and expenses in the notes to its financial statements for interim and annual reporting periods. The objective of the disclosure requirements is to provided disaggregated information about a public business entity's expenses to help investors (a) better understand the entity's performance, (b) better assess the entity's prospects for future cash flows, and (c) compare an entity's performance over time and with that of other entities.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2023-ED500—Income Statement—Reporting Comprehensive Income—Expense Disaggregation Disclosures (Subtopic 220-40): Disaggregation of Income Statement Expenses, which has been deleted.
The effective of Update 2024-03 was amended by Accounting Standards Update No. 2025-01, Income Statement—Reporting Comprehensive Income—Expense Disaggregation Disclosures (Subtopic 220-40): Clarifying the Effective Date. Public business entities are required to adopt the guidance in annual reporting periods beginning after December 15, 2026, and interim periods within annual reporting periods beginning after December 15, 2027. Early adoption of Update 2024-03 is permitted.
For more information, see the following:
Issued: November 4, 2024
2024-04Accounting Standards Update No. 2024-04—Debt—Debt with Conversion and Other Options (Subtopic 470-20): Induced Conversions of Convertible Debt Instruments470
Stakeholders noted that the current guidance is not clear on whether the induced conversion guidance can be applied to the settlement of a convertible debt instrument that does not require the issuance of equity securities upon conversion (for example, a convertible debt instrument with a cash conversion feature) or the early settlement of a convertible debt instrument that is not currently convertible. They also noted that current GAAP does not address how the incorporation, elimination, or modification of a volume-weighted average price (VWAP) formula interacts with the criterion in the existing induced conversion guidance.
The amendments in this Update improve the consistent application and relevance of the induced conversion guidance in Subtopic 470-20, Debt—Debt with Conversion and Other Options.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2023-ED600—Debt—Debt with Conversion and Other Options (Subtopic 470-20): Induced Conversions of Convertible Debt Instruments (a consensus of the Emerging Issues Task Force), which has been deleted.
For more information, see the following:
Issued: November 26, 2024
2023
2023-01Accounting Standards Update No. 2023-01—Leases (Topic 842): Common Control Arrangements842
The amendments in this Update address two issues:
Issue 1: Terms and Conditions to Be Considered
The amendments in this Update provide a practical expedient for private companies and not-for-profit entities that are not conduit bond obligors to use the written terms and conditions of a common control arrangement to determine:
- 1Whether a lease exists and, if so,
- 2The classification of and accounting for that lease.
The practical expedient may be applied on an arrangement-by-arrangement basis.
Issue 2: Accounting for Leasehold Improvements
The amendments in this Update are applicable for all entities and require that leasehold improvements associated with leases between entities under common control be:
- 1Amortized by the lessee over the useful life of the leasehold improvements to the common control group as long as the lessee controls the use of the underlying asset through a lease. If the lessor obtained the underlying asset through a lease with another entity not within the same common control group, the amortization period may not exceed the lease term associated with the lessor’s lease with the other entity.
- 2Accounted for as a transfer between entities under common control through an adjustment to equity (or net assets for not-for-profit entities), if, and when, the lessee no longer controls the use of the underlying asset.
Additionally, those leasehold improvements are subject to the impairment guidance in Topic 360, Property, Plant, and Equipment.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2022-ED500—Leases (Topic 842): Common Control Arrangements, which has been deleted.
Issued: March 27, 2023
2023-02Accounting Standards Update No. 2023-02—Investments—Equity Method and Joint Ventures (Topic 323): Accounting for Investments in Tax Credit Structures Using the Proportional Amortization Method (a consensus of the Emerging Issues Task Force)323
The amendments in this Update permit reporting entities to elect to account for their tax equity investments, regardless of the program from which the income tax credits are recieved, using the proportional amortaziation method if certain conditions are met. A reporting entity may make an accounting policy election to apply the proportional amortization method on a tax-credit-program-by-tax-credit-program basis rather than electing to apply the proportional amortization method at the reporting entity level or to individual investments.
To qualify for the proportional amortization method, if elected in accordance with paragraph 323-740-25-4, all of the following conditions must be met:
- 1It is probable that the income tax credits allocable to the tax equity investor will be available.
- 2The tax equity investor does not have the ability to exercise significant influence over the operating and financial policies of the underlying project.
- 3Substantially all of the projected benefits are from income tax credits and other income tax benefits. Projected benefits include income tax credits, other income tax benefits, and other non-income-tax-related benefits. The projected benefits should be determined on a discounted basis, using a discount rate that is consistent with the cash flow assumptions used by the tax equity investor in making its decision to invest in the project.
- 4The tax equity investor’s projected yield based solely on the cash flows from the income tax credits and other tax benefits is positive.
- 5The tax equity investor is a limited liability investor in the limited liability entity for both legal and tax purposes, and the tax equity investor’s liability is limited to its capital investment.
The amendments in the Update also remove certain guidance for Qualified Affordable Housing Project investments and require the application of the delayed equity contribution guidance to all tax equity investments.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2022-004—Investments—Equity Method and Joint Ventures (Topic 323): Accounting for Investments in Tax Credit Structures Using the Proportional Amortization Method (a consensus of the Emerging Issues Task Force), which has been deleted.
Issued: March 29, 2023
2023-03Accounting Standards Update No. 2023-03—Presentation of Financial Statements (Topic 205), Income Statement—Reporting Comprehensive Income (Topic 220), Distinguishing Liabilities from Equity (Topic 480), Equity (Topic 505), and Compensation—Stock Compensation (Topic 718): Amendments to SEC Paragraphs Pursuant to SEC Staff Accounting Bulletin No. 120, Staff Announcement at the March 24, 2022 EITF Meeting, and Staff Accounting Bulletin Topic 6.B, Accounting Series Release 280—General Revision of Regulation S-X: Income or Loss Applicable to Common Stock205220480505718
This Accounting Standards Update amends and supersedes various SEC paragraphs pursuant to the issuance of SEC Staff Accounting Bulletin No. 120 and pursuant to the SEC Staff Announcement at the March 24, 2022 Emerging Issues Task Force meeting. This Update also updates an SEC paragraph to conform to the latest version of SEC Staff Accounting Bulletin Topic 6.B, Accounting Series Release No. 280—General Revision of Regulation S-X: Income or Loss Applicable to Common Stock.
Issued: July 14, 2023
2023-04Accounting Standards Update No. 2023-04—Liabilities (Topic 405)—Amendments to SEC Paragraphs Pursuant to SEC Staff Accounting Bulletin No. 121405
This Accounting Standards Update amends and adds various SEC paragraphs pursuant to the issuance of SEC Staff Accounting Bulletin No. 121.
Issued: August 3, 2023
2023-05Accounting Standards Update No. 2023-05—Business Combinations—Joint Venture Formations (Subtopic 805-60): Recognition and Initial Measurement805
The amendments in this Update address the accounting for contributions made to a joint venture, upon its formation, in a joint venture’s separate financial statements. The amendments require that a joint venture apply a new basis of accounting upon formation. By applying a new basis of accounting, a joint venture, upon formation, will recognize and initially measure its assets and liabilities at fair value (with exceptions to fair value measurement that are consistent with the business combinations guidance).
The amendments in this Update affect the acounting for contributions received upon formation by entities that meet the definition of a joint venture or a corporate joint venture, as defined in the Master Glossary of the Codification.
This Accounting Standards Update is the final version of the Proposed Accounting Standards Update 2022-300—Business Combinations—Joint Venture Formations (Subtopic 805-60): Recognition and Initial Measurement.
Issued: August 23, 2023
2023-06Accounting Standards Update No. 2023-06—Disclosure Improvements—Codification Amendments in Response to the SEC’s Disclosure Update and Simplification Initiative
The amendments in this Update modify the disclosure or presentation requirements of a variety of Topics in the Codification. The amendments are in response to the U.S. Securities and Exchange Commission's (SEC) Release No. 33-10532, Disclosure Update and Simplification, in which the SEC referred certain of its disclosure requirements that overlap with, but require incremental information to, generally accepted accounting principles to the FASB for potential incorporation into the Codification. The amendments in this Update are the result of the Board’s decision to incorporate into the Codification 14 of the 27 disclosures referred by the SEC. Certain of the amendments represent clarifications to or technical corrections of the current requirements and other amendments add incremental disclosure requirements to align with the SEC's regulations.
For entities subject to the SEC’s existing disclosure requirements and for entities required to file or furnish financial statements with or to the SEC in preparation for the sale of or for purposes of issuing securities that are not subject to contractual restrictions on transfer, the effective date for each amendment will be the date on which the SEC’s removal of that related disclosure from Regulation S-X or Regulation S-K becomes effective, with early adoption prohibited. For all other entities, the amendments will be effective two years later.
For all entities, if by June 30, 2027, the SEC has not removed the applicable requirement from Regulation S-X or Regulation S-K, the pending content of the related amendment will be removed from the Codification and will not become effective for any entity.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2019-600—Disclosure Improvements—Codification Amendments in Response to the SEC΄s Disclosure Update and Simplification Initiative, which has been deleted.
Issued: October 9, 2023
2023-07Accounting Standards Update No. 2023-07—Segment Reporting (Topic 280)—Improvements to Reportable Segment Disclosures280
The amendments in this Update improve reportable segment disclosure requirements, primarily through enhanced disclosures about significant segment expenses. The amendments in this update:
- Require that a public entity disclose, on an annual and interim basis, significant segment expenses that are regularly provided to the chief operating decision maker (CODM) and included within each reported measure of segment profit or loss (collectively referred to as the “significant expense principle”).
- Require that a public entity disclose, on an annual and interim basis, an amount for other segment items by reportable segment and a description of its composition. The other segment items category is the difference between segment revenue less the segment expenses disclosed under the significant expense principle and each reported measure of segment profit or loss.
- Require that a public entity provide all annual disclosures about a reportable segment’s profit or loss and assets currently required by Topic 280 in interim periods.
- Clarify that if the CODM uses more than one measure of a segment’s profit or loss in assessing segment performance and deciding how to allocate resources, a public entity may report one or more of those additional measures of segment profit. However, at least one of the reported segment profit or loss measures (or the single reported measure, if only one is disclosed) should be the measure that is most consistent with the measurement principles used in measuring the corresponding amounts in the public entity’s consolidated financial statements. In other words, in addition to the measure that is most consistent with the measurement principles under generally accepted accounting principles (GAAP), a public entity is not precluded from reporting additional measures of a segment’s profit or loss that are used by the CODM in assessing segment performance and deciding how to allocate resources.
- Require that a public entity disclose the title and position of the CODM and an explanation of how the CODM uses the reported measure(s) of segment profit or loss in assessing segment performance and deciding how to allocate resources.
- Require that a public entity that has a single reportable segment provide all the disclosures required by the amendments in this Update and all existing segment disclosures in Topic 280.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2022-ED100—Segment Reporting (Topic 280)—Improvements to Reportable Segment Disclosures, which has been deleted.
Issued: November 27, 2023
2023-08Accounting Standards Update No. 2023-08—Intangibles—Goodwill and Other—Crypto Assets (Subtopic 350-60): Accounting for and Disclosure of Crypto Assets350
The amendments in this Update improve the accounting for and disclosure of crypto assets held that meet all of the following criteria:
- 1 Meet the definition of intangible asset as defined in the Codification
- 2 Do not provide the asset holder with enforceable rights to, or claims on, underlying goods, services, or other assets
- 3 Are created or reside on a distributed ledger based on blockchain or similar technology
- 4 Are secured through cryptography
- 5 Are fungible
- 6 Are not created or issued by the reporting entity or its related parties.
The amendments in the Update address measurement, presentation, disclosure, and transition requirements for holders of crypto assets that meet the criteria.
The amendments in this Update are effective for all entities for fiscal years beginning after December 15, 2024, including interim periods within those fiscal years. Early adoption is permitted for both interim and annual financial statements that have not yet been issued (or made available for issuance).
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2023-ED200—Intangibles–Goodwill and Other: Crypto Assets (Subtopic 350-60): Accounting for and Disclosure of Crypto Assets, which has been deleted.
For more information, see the following:
Issued: December 13, 2023
2023-09Accounting Standards Update No. 2023-09—Income Taxes (Topic 740)—Improvements to Income Tax Disclosures740
The amendments in this Update provide more transparency about income tax information through improvements to income tax disclosures primarily related to the rate reconciliation and income taxes paid information.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2023-ED100—Income Taxes (Topic 740): Improvements to Income Tax Disclosures, which has been deleted.
For more information, see the following:
Issued: December 14, 2023
2022
2022-01Accounting Standards Update No. 2022-01—Derivatives and Hedging (Topic 815): Fair Value Hedging—Portfolio Layer Method815
The amendments in this Update expand the current last-of-layer method of hedge accounting that permits only one hedged layer to allow multiple hedged layers of a single closed portfolio. To reflect that expansion, the last-of-layer method is renamed the portfolio layer method.
Additionally, amendments in this Update:
- 1Expand the scope of the portfolio layer method to include nonprepayable assets
- 2Specify eligible hedging instruments in a single-layer hedge
- 3Provide additional guidance on the accounting for and disclosure of hedge basis adjustments
- 4Specify how hedge basis adjustments should be considered when determining credit losses for the assets included in the closed portfolio.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2021-002—Derivatives and Hedging (Topic 815): Fair Value Hedging—Portfolio Layer Method, which has been deleted.
Issued: March 28, 2022
2022-02Accounting Standards Update No. 2022-02—Financial Instruments—Credit Losses (Topic 326): Troubled Debt Restructurings and Vintage Disclosures326
The amendments in this Update eliminate the accounting guidance for troubled debt restructurings (TDRs) by creditors in Subtopic 310-40, Receivables—Troubled Debt Restructurings by Creditors, while enhancing disclosure requirements for certain loan refinancings and restructurings by creditors when a borrower is experiencing financial difficulty. Specifically, rather than applying the recognition and measurement guidance for TDRs, an entity must apply the loan refinancing and restructuring guidance in paragraphs 310-20-35-9 through 35-11 to determine whether a modification results in a new loan or a continuation of an existing loan.
Additionally, for public business entities, the amendments in this Update require that an entity disclose current-period gross writeoffs by year of origination for financing receivables and net investments in leases within the scope of Subtopic 326-20, Financial Instruments—Credit Losses—Measured at Amortized Cost in the vintage disclosures required by paragraph 326-20-50-6.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2021-006—Financial Instruments—Credit Losses (Topic 326): Troubled Debt Restructurings and Vintage Disclosures, which has been deleted.
Issued: March 31, 2022
2022-03Accounting Standards Update No. 2022-03—Fair Value Measurement (Topic 820): Fair Value Measurement of Equity Securities Subject to Contractual Sale Restrictions820
The amendments in this Update affect all entities that have investments in equity securities measured at fair value that are subject to a contractual sale restriction. The amendments clarify that a contractual restriction on the sale of an equity security is not considered part of the unit of account of the equity security and, therefore, is not considered in measuring fair value. The amendments also clarify that an entity cannot, as a separate unit of account, recognize and measure a contractual sale restriction. The amendments also require the following disclosures for equity securities subject to contractual sale restrictions:
- The fair value of equity securities subject to contractual sale restrictions reflected on the balance sheet
- The nature and remaining duration of the restriction(s)
- The circumstances that could cause a lapse in the restriction(s).
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2021-005—Fair Value (Topic 820): Fair Value Measurement of Equity Securities Subject to Contractual Sale Restrictions, which has been deleted.
Issued: June 30, 2022
2022-04Accounting Standards Update No. 2022-04—Liabilities—Supplier Finance Programs (Subtopic 405-50): Disclosure of Supplier Finance Program Obligations405
Subtopic 405-50, Supplier Finance Programs—Disclosure of Supplier Finance Program Obligations, requires that a buyer in a supplier finance program disclose sufficient information about the program to allow a user of financial statements to understand the program’s nature, activity during the period, changes from period to period, and potential magnitude.
The amendments in this Update require qualitative and quantitative disclosures about supplier finance programs and thereby allow financial statement users to better understand the effect of those programs on an entity’s working capital, liquidity, and cash flows.
This Accounting Standard Update applies to all entities that use supplier finance programs in connection with the purchase of goods and services.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2021-007—Liabilities—Supplier Finance Programs (Subtopic 405-50): Disclosure of Supplier Finance Program Obligations, which has been deleted.
Issued: September 29, 2022
2022-05Accounting Standards Update No. 2022-05—Financial Services—Insurance (Topic 944): Transition for Sold Contracts944
The amendments in this Update modify the current application requirements of Accounting Standards Update No. 2018-12, Financial Services—Insurance (Topic 944): Targeted Improvements to the Accounting for Long-Duration Contracts (LDTI). The amendments in this Update amend the LDTI transition guidance to allow an insurance entity to make an accounting policy election on a transaction-by-transaction basis. An insurance entity may elect to exclude contracts that meet certain criteria from applying the amendments in Update 2018-12. To qualify for the accounting policy election, as of the LDTI effective date both of the following conditions must be met:
- 1 The insurance contracts must have been derecognized because of a sale or disposal of individual or a group of contracts or legal entities
- 2 The entity has no significant continuing involvement with the derecognized contracts.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2022-003—Financial Services—Insurance (Topic 944): Transition for Sold Contracts, which has been deleted.
Issued: December 15, 2022
2022-06Accounting Standards Update No. 2022-06—Reference Rate Reform (Topic 848): Deferral of the Sunset Date of Topic 848848
In 2020, the Board issued Accounting Standards Update No. 2020-04, Reference Rate Reform (Topic 848): Facilitation of the Effects of Reference Rate Reform on Financial Reporting, which provides optional guidance to ease the potential burden in accounting for (or recognizing the effects of) reference rate reform on financial reporting.
The objective of the guidance in Topic 848 is to provide temporary relief during the transition period. The Board included a sunset provision within Topic 848 based on expectations of when the London Interbank Offered Rate (LIBOR) would cease being published. At the time that Update 2020-04 was issued, the UK Financial Conduct Authority (FCA) had established its intent that it would no longer be necessary to persuade, or compel, banks to submit to LIBOR after December 31, 2021. As a result, the sunset provision was set for December 31, 2022—12 months after the expected cessation date of all currencies and tenors of LIBOR.
In March 2021, the FCA announced that the intended cessation date of the overnight 1-, 3-, 6-, and 12-month tenors of USD LIBOR would be June 30, 2023, which is beyond the current sunset date of Topic 848.
Because the current relief in Topic 848 may not cover a period of time during which a significant number of modifications may take place, the amendments in this Update defer the sunset date of Topic 848 from December 31, 2022, to December 31, 2024, after which entities will no longer be permitted to apply the relief in Topic 848.
The amendments in this Update apply to all entities, subject to meeting certain criteria, that have contracts, hedging relationships, and other transactions that reference LIBOR or another reference rate expected to be discontinued because of reference rate reform.
The amendments in this Update are effective for all entities upon issuance of this Update.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update—Reference Rate Reform (Topic 848) and Derivatives and Hedging (Topic 815): Deferral of the Sunset Date of Topic 848 and Amendments to the Definition of the Secured Overnight Financing Rate (SOFR) Overnight Index Swap Rate, which has been deleted.
Issued: December 21, 2022
2021
2021-01Accounting Standards Update No. 2021-01—Reference Rate Reform (Topic 848): Scope848
The amendments in this Update clarify that certain optional expedients and exceptions in Topic 848 for contract modifications and hedge accounting apply to derivative instruments that use an interest rate for margining, discounting, or contract price alignment that is modified as a result of reference rate reform. Amendments in this Update to the expedients and exceptions in Topic 848 capture the incremental consequences of the scope clarification and tailor the existing guidance to derivative instruments affected by the discounting transition.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2020-900—Reference Rate Reform (Topic 848): Scope Refinement, which has been deleted.
Issued: January 7, 2021
2021-02Accounting Standards Update No. 2021-02—Franchisors—Revenue from Contracts with Customers (Subtopic 952-606): Practical Expedient952
The amendments in this Update are intended to reduce the cost and complexity of applying Topic 606, Revenue from Contracts with Customers, to pre-opening services for franchisors that are not public business entities. The amendments in this Update introduce a new practical expedient that simplifies the application of the guidance in Topic 606 about identifying performance obligations.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2020-600—Franchisors—Revenue from Contracts with Customers (Subtopic 952-606): Practical Expedient, which has been deleted.
Issued: January 28, 2021
2021-03Accounting Standards Update No. 2021-03—Intangibles—Goodwill and Other (Topic 350): Accounting Alternative for Evaluating Triggering Events350
The amendments in this Update provide private companies and not-for-profit entities with an accounting alternative to perform the goodwill impairment triggering event evaluation as required in Subtopic 350-20 as of the end of the reporting period, whether the reporting period is an interim or annual period.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2020-1100—Intangibles—Goodwill and Other (Topic 350): Accounting Alternative for Evaluating Triggering Events, which has been deleted.
Issued: March 30, 2021
2021-04Accounting Standards Update No. 2021-04—Earnings Per Share (Topic 260), Debt—Modifications and Extinguishments (Subtopic 470-50), Compensation—Stock Compensation (Topic 718), and Derivatives and Hedging—Contracts in Entity's Own Equity (Subtopic 815-40): Issuer's Accounting for Certain Modifications or Exchanges of Freestanding Equity-Classified Written Call Options (a consensus of the FASB Emerging Issues Task Force)260470718815
The amendments in this Update clarify and reduce diversity in an issuer's accounting for modifications or exchanges of freestanding equity-classified written call options (for example, warrants) that remain equity classified after modification or exchange. The guidance clarifies whether an issuer should account for a modification or an exchange of a freestanding equity-classified written call option that remains equity classified after modification or exchange as (1) an adjustment to equity and, if so, the related earnings per share (EPS) effects, if any, or (2) an expense and, if so, the manner and pattern of recognition.
The amendments in this Update affect all entities that issue freestanding written call options that are classified in equity. The amendments do not apply to modifications or exchanges of financial instruments that are within the scope of another Topic and do not affect a holder's accounting for freestanding call options.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2020-800—Earnings Per Share (Topic 260), Debt—Modifications and Extinguishments (Subtopic 470-50), Compensation—Stock Compensation (Topic 718), and Derivatives and Hedging—Contracts in Entity's Own Equity (Subtopic 815-40): Issuer's Accounting for Certain Modifications or Exchanges of Freestanding Equity-Classified Forwards and Options (a consensus of the Emerging Issues Task Force), which has been deleted.
Issued: May 3, 2021
2021-05Accounting Standards Update No. 2021-05—Leases (Topic 842): Lessors—Certain Leases with Variable Lease Payments842
The amendments in this Update require lessors to classify and account for a lease with variable lease payments that do not depend on a reference index or a rate as an operating lease if both of the following criteria are met:
1. The lease would have been classified as a sales-type lease or a direct financing lease in accordance with the classification criteria in paragraphs 842-10-25-2 through 25-3.
2. The lessor would have otherwise recognized a day-one loss.
The amendments in this Update affect lessors with lease contracts that (1) have variable lease payments that do not depend on a reference index or a rate and (2) would have resulted in the recognition of a selling loss at lease commencement if classified as sales-type or direct financing.
This Accounting Standards Update is the final version of a portion of Proposed Accounting Standards Update 2020-700—Leases (Topic 842): Targeted Improvements.
2021-06Accounting Standards Update No. 2021-06—Presentation of Financial Statements (Topic 205), Financial Services—Depository and Lending (Topic 942), and Financial Services— Investment Companies (Topic 946)—Amendments to SEC Paragraphs Pursuant to SEC Final Rule Releases No. 33-10786, Amendments to Financial Disclosures about Acquired and Disposed Businesses, and No. 33-10835, Update of Statistical Disclosures for Bank and Savings and Loan Registrants205942946
This Accounting Standards Update amends and adds various SEC paragraphs pursuant to the issuance of SEC Final Rule Releases No. 33-10786, Amendments to Financial Disclosures about Acquired and Disposed Businesses, and No. 33-10835, Update of Statistical Disclosures for Bank and Savings and Loan Registrants.
Issued: August 9, 2021
2021-07Accounting Standards Update No. 2021-07—Compensation—Stock Compensation (Topic 718)—Determining the Current Price of an Underlying Share718
The objective of this Update is to address the concerns of private company stakeholders about the cost and complexity associated with determining the current price input into the valuation of a share-based award granted as compensation. The amendments in this Update provide a practical expedient for a nonpublic entity to determine the current price input of equity-classified share-based awards issued to both employees and nonemployees.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update—Compensation—Stock Compensation (Topic 718): Determining the Current Price of an Underlying Share for Equity-Classified Share Option Awards, which has been deleted.
Issued: October 25, 2021
2021-08Accounting Standards Update No. 2021-08—Business Combinations (Topic 805)—Accounting for Contract Assets and Contract Liabilities from Contracts with Customers805
The amendments in this Update address diversity and inconsistency related to the recognition and measurement of contract assets and contract liabilities acquired in a business combination. The amendments in this Update require that an acquirer recognize and measure contract assets and contract liabilities acquired in a business combination in accordance with Topic 606, Revenue from Contracts with Customers.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2020-1000—Business Combinations (Topic 805): Accounting for Contract Assets and Contract Liabilities from Contracts with Customers, which has been deleted.
Issued: October 28, 2021
2021-09Accounting Standards Update No. 2021-09—Leases (Topic 842)—Discount Rate for Lessees That Are Not Public Business Entities842
The amendments in this Update allow a lessee that is not a public business entity to elect an accounting policy to use a risk-free rate as its discount rate by class of underlying asset rather than at an entity-wide level, as is currently required by Topic 842, Leases.
The amendments in this Update also require that when the rate implicit in the lease is readily determinable for any individual lease, the lessee would use that rate (rather than a risk-free rate or an incremental borrowing rate), regardless of whether it has made the risk-free rate election.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2021-003—Leases (Topic 842)—Discount Rate for Lessees That Are Not Public Business Entities, which has been deleted.
Issued: November 11, 2021
2021-10Accounting Standards Update No. 2021-10—Government Assistance (Topic 832)—Disclosures by Business Entities about Government Assistance832
The amendments in this Update require disclosures about transactions with a government that have been accounted for by analogizing to a grant or contribution accounting model to increase transparency about (1) the types of transactions, (2) the accounting for the transactions, and (3) the effect of the transactions on an entity's financial statements.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2015-340—Government Assistance (Topic 832): Disclosures by Business Entities about Government Assistance, which has been deleted.
Issued: November 17, 2021
2020
2020-01Accounting Standards Update No. 2020-01—Investments—Equity Securities (Topic 321), Investments—Equity Method and Joint Ventures (Topic 323), and Derivatives and Hedging (Topic 815)—Clarifying the Interactions between Topic 321, Topic 323, and Topic 815321323815
The amendments in this Update clarify the interaction of the accounting for equity securities under Topic 321 and investments under the equity method of accounting in Topic 323 and the accounting for certain forward contracts and purchased options accounted for under Topic 815. The amendments clarify that an entity should consider observable transactions that require it to either apply or discontinue the equity method of accounting for the purposes of applying the measurement alternative in accordance with Topic 321 immediately before applying or upon discontinuing the equity method. The amendments also clarify that for the purpose of applying paragraph 815-10-15-141(a) an entity should not consider whether, upon the settlement of the forward contract or exercise of the purchased option, individually or with existing investments, the underlying securities would be accounted for under the equity method in Topic 323 or the fair value option in accordance with the financial instruments guidance in Topic 825. An entity also would evaluate the remaining characteristics in paragraph 815-10-15-141 to determine the accounting for those forward contracts and purchased options.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2019-740—Investments—Equity Securities (Topic 321), Investments—Equity Method and Joint Ventures (Topic 323), and Derivatives and Hedging (Topic 815): Clarifying the Interactions between Topic 321, Topic 323, and Topic 815, which has been deleted.
Issued: January 16, 2020
2020-02Accounting Standards Update No. 2020-02—Financial Instruments—Credit Losses (Topic 326) and Leases (Topic 842)—Amendments to SEC Paragraphs Pursuant to SEC Staff Accounting Bulletin No. 119 and Update to SEC Section on Effective Date Related to Accounting Standards Update No. 2016-02, Leases (Topic 842)326842
This Accounting Standards Update adds an SEC paragraph pursuant to the issuance of SEC Staff Accounting Bulletin No. 119, which adds Topic 6M on Accounting for Loan Losses by Registrants Engaged in Lending Activities Subject to FASB ASC Topic 326. It also adds a note in paragraph 842-10-S65-1 regarding the updated effective date for Leases pursuant to the issuance of Accounting Standards Update 2019-10, Financial Instruments—Credit Losses (Topic 326), Derivatives and Hedging (Topic 815), and Leases (Topic 842): Effective Dates.
Issued: February 6, 2020
2020-03Accounting Standards Update No. 2020-03—Codification Improvements to Financial Instruments
The amendments in this Update represent changes to clarify or improve the Codification that are not expected to have a significant effect on current accounting practice or create a significant administrative cost to most entities.
Issued: March 9, 2020
2020-04Accounting Standards Update No. 2020-04—Reference Rate Reform (Topic 848)—Facilitation of the Effects of Reference Rate Reform on Financial Reporting848
In response to concerns about structural risks of interbank offered rates (IBORs), and, particularly, the risk of cessation of the London Interbank Offered Rate (LIBOR), regulators around the world have undertaken reference rate reform initiatives to identify alternative reference rates that are more observable or transaction-based and less susceptible to manipulation. The amendments in this Update provide optional guidance for a limited time to ease the potential burden in accounting for (or recognizing the effects) of reference rate reform on financial reporting.
The amendments in this Update provide optional expedients and exceptions for applying generally accepted accounting principles (GAAP) to contracts, hedging relationships, and other transactions affected by reference rate reform if certain criteria are met.
The amendments in this Update apply only to contracts and hedging relationships that reference LIBOR or another reference rate expected to be discontinued due to reference rate reform. The expedients and exceptions provided by the amendments do not apply to contract modifications made and hedging relationships entered into or evaluated after December 31, 2022.
The amendments in this Update are elective and are effective upon issuance for all entities.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2019-770—Reference Rate Reform (Topic 848)—Facilitation of the Effects of Reference Rate Reform on Financial Reporting, which has been deleted.
Issued: March 12, 2020
2020-05Accounting Standards Update No. 2020-05—Revenue from Contracts with Customers (Topic 606) and Leases (Topic 842)—Effective Dates for Certain Entities606842
Coronavirus Disease 2019 (COVID-19) pandemic is adversely affecting the global economy and causing significant and widespread business and capital market disruptions. The Board is committed to supporting and assisting stakeholders during this difficult time.
The Board is issuing this Update as a limited deferral of the effective dates of the following Updates (including amendments issued after the issuance of the original Update) to provide immediate, near-term relief for certain entities for whom these Updates are either currently effective or imminently effective:
1. Accounting Standards Update No. 2014-09, Revenue from Contracts with Customers (Topic 606) (Revenue)
2. Accounting Standards Update No. 2016-02, Leases (Topic 842) (Leases).
The amendments in this Update defer, for one year, the required effective date of Revenue for entities, that are not public business entities, that have not yet issued their financial statements (or made financial statements available for issuance) reflecting the adoption of Revenue. Those entities may elect to adopt the guidance for annual reporting periods beginning after December 15, 2019 and for interim reporting periods within annual reporting periods beginning after December 15, 2020. Those entities may elect to follow the original effective date of annual reporting periods beginning after December 15, 2018 and interim reporting periods within annual reporting periods beginning after December 15, 2019.
The amendments in this Update defer the effective date of Leases for private entities (the “all other” category) to fiscal years beginning after December 15, 2021, and interim periods within fiscal years beginning after December 15, 2022. Additionally, the amendments defer the effective date of Leases to fiscal years beginning after December 15, 2019, including interim periods within those fiscal years, for not-for-profit entities that have issued or are conduit bond obligors for securities that are traded, listed, or quoted on an exchange or an over-the-counter market that have not yet issued financial statements (or made financial statements available for issuance). Early application continues to be permitted which means that an entity may choose to implement Leases before those deferred effective dates.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2020-300—Revenue from Contracts with Customers (Topic 606) and Leases (Topic 842)—Effective Dates for Certain Entities, which has been deleted.
Issued: June 3, 2020
2020-06Accounting Standards Update No. 2020-06—Debt—Debt with Conversion and Other Options (Subtopic 470-20) and Derivatives and Hedging—Contracts in Entity's Own Equity (Subtopic 815-40)—Accounting for Convertible Instruments and Contracts in an Entity's Own Equity470815
The objective of the amendments in this Update is to address issues identified as a result of the complexity associated with applying generally accepted accounting principles (GAAP) for certain financial instruments with characteristics of liabilities and equity.
The amendments in this Update reduce the number of accounting models for convertible debt instruments and convertible preferred stock. For convertible instruments with conversion features that are not required to be accounted for as derivatives under Topic 815, Derivatives and Hedging, or that do not result in substantial premiums accounted for as paid-in capital, the embedded conversion features no longer are separated from the host contract.
The amendments in this Update remove certain conditions that should be considered in the derivatives scope exception evaluation under Subtopic 815-40, Derivatives and Hedging—Contracts in Entity's Own Equity, and clarify the scope and certain requirements under Subtopic 815-40.
The amendments in this Update also improve the guidance related to the disclosures and earnings-per-share (EPS) for convertible instruments and contract in entity's own equity.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2019-730—Debt—Debt with Conversion and Other Options (Subtopic 470-20) and Derivatives and Hedging—Contracts in Entity's Own Equity (Subtopic 815-40)—Accounting for Convertible Instruments and Contracts in an Entity's Own Equity, which has been deleted.
Issued: August 5, 2020
2020-07Accounting Standards Update No. 2020-07—Not-for-Profit Entities (Topic 958)—Presentation and Disclosures by Not-for-Profit Entities for Contributed Nonfinancial Assets958
The objective of the amendments in this Update is to increase transparency of contributed nonfinancial assets for not-for-profit (NFP) entities through enhancements in presentation and disclosure requirements. NFP entities will now be required to present contributed nonfinancial assets as a separate line item in the statement of activities, apart from contributions of cash and other financial contributions. NFPs will also be required to disclose various information related to contributed nonfinancial assets.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2020-100—Not-for-Profit Entities (Topic 958)—Presentation and Disclosures by Not-for-Profit Entities for Contributed Nonfinancial Assets, which has been deleted.
Issued: September 17, 2020
2020-08Accounting Standards Update No. 2020-08—Codification Improvements to Subtopic 310-20, Receivables—Nonrefundable Fees and Other Costs310
The amendments in this Update clarify the Board's intent that an entity should reevaluate whether a callable debt security that has multiple call dates is within the scope of paragraph 310-20-35-33 for each reporting period.
Issued: October 15, 2020
2020-09Accounting Standards Update No. 2020-09—Debt (Topic 470)—Amendments to SEC Paragraphs Pursuant to SEC Release No. 33-10762470
This Accounting Standards Update amends and supersedes various SEC paragraphs pursuant to the issuance of SEC Final Rule Release No. 33-10762, Financial Disclosures about Guarantors and Issuers of Guaranteed Securities and Affiliates Whose Securities Collateralize a Registrant's Securities.
Issued: October 22, 2020
2020-10Accounting Standards Update No. 2020-10—Codification Improvements
The amendments in this Update represent changes to clarify the Codification, correct unintended application of guidance, or make minor improvements to the Codification that are not expected to have a significant effect on current accounting practice or create a significant administrative cost to most entities.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2019-800—Codification Improvements, which has been deleted.
Issued: October 29, 2020
2020-11Accounting Standards Update No. 2020-11—Financial Services—Insurance (Topic 944): Effective Date and Early Application944
The Board is issuing this Update to provide implementation relief to insurance entities adopting Accounting Standards Update No. 2018-12, Financial Services—Insurance (Topic 944): Targeted Improvements to the Accounting for Long-Duration Contracts. The amendments in this Update:
1. Defer the required effective date of Update 2018-12 by one year for all insurance entities.
2. Provide transition relief for entities that elect early application by amending the transition date to be the beginning of the prior period presented or the beginning of the earliest period presented.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2020-400—Financial Services—Insurance (Topic 944): Effective Date and Early Application, which has been deleted.
Issued: November 5, 2020
2019
2019-01Accounting Standards Update No. 2019-01—Leases (Topic 842)—Codification Improvements842
Determining the Fair Value of the Underlying Asset by Lessors That Are Not Manufacturers or Dealers
The amendments in this Update reinstate the exception in Topic 842 for lessors that are not manufacturers or dealers. Specifically, those lessors will use their cost, reflecting any volume or trade discounts that may apply, as the fair value of the underlying asset. However, if a significant lapse of time occurs between the acquisition of the underlying asset and lease commencement, those lessors will be required to apply the definition of fair value (exit price) in Topic 820.
Presentation on the Statement of Cash Flows—Sales-Type and Direct Financing Leases
The amendments in this Update address the concerns of lessors within the scope of Topic 942 about where “principal payments received under leases” should be presented. Specifically, lessors that are depository and lending institutions within the scope of Topic 942 will present all “principal payments received under leases” within investing activities.
Transition Disclosures Related to Topic 250, Accounting Changes and Error Corrections
The amendments in this Update address those concerns by explicitly providing an exception to the paragraph 250-10-50-3 interim disclosure requirements in the Topic 842 transition disclosure requirements.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2018-310—Leases (Topic 842)—Codification Improvements for Lessors, which has been deleted.
Issued: March 05, 2019
2019-02Accounting Standards Update No. 2019-02—Entertainment—Films—Other Assets—Film Costs (Subtopic 926-20) and Entertainment—Broadcasters—Intangibles—Goodwill and Other (Subtopic 920-350)—Improvements to Accounting for Costs of Films and License Agreements for Program Materials920926
This update releases Accounting Standards Update No. 2019-02—Entertainment—Films—Other Assets—Film Costs (Subtopic 926-20) and Entertainment—Broadcasters—Intangibles—Goodwill and Other (Subtopic 920-350). This update is the final version of Proposed Accounting Standards Update 2018-290, which has been deleted.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2018-290—Entertainment—Films—Other Assets—Film Costs (Subtopic 926-20) and Entertainment—Broadcasters—Intangibles—Goodwill and Other (Subtopic 920-350), which has been deleted.
Issued: March 06, 2019
2019-03Accounting Standards Update No. 2019-03—Not-for-Profit Entities (Topic 958)—Updating the Definition of Collections958
The amendments in this final Update improve the definition of the term collections in the Master Glossary by realigning it with the definition in the American Alliance of Museums' (AAM) Code of Ethics for Museums (the Code) in order to eliminate the diversity in practice that exists today between the application of the Master Glossary's definition compared with the definition that many entities use for accreditation purposes. The amendments in this Update also are an improvement because aligning the definition and permitting proceeds to be utilized for the direct care of collections is consistent with the basis for conclusions in FASB Statement No. 116, Accounting for Contributions Received and Contributions Made, about the care and preservation of collections. The amendments in this Update require that a collection-holding entity disclose its policy for the use of proceeds from when collection items are deaccessioned (that is, removed from a collection). If a collection-holding entity has a policy that allows proceeds from deaccessioned collection items to be used for direct care, it should disclose its definition of the term direct care.
The amendments in this Update also make a Codification improvement in Topic 360, Property, Plant, and Equipment, to clarify that the collections guidance in Subtopic 958-360, Not-for-Profit Entities—Property, Plant, and Equipment, applies to business entities as well as not-for-profit entities, consistent with what was indicated in Statement 116.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2018-250—Not-for-Profit Entities (Topic 958): Updating the Definition of Collections, which has been deleted.
Issued: March 21, 2019
2019-04Accounting Standards Update No. 2019-04—Codification Improvements to Topic 326, Financial Instruments—Credit Losses, Topic 815, Derivatives and Hedging, and Topic 825, Financial Instruments326815825
The amendments in this Update clarify, correct, and improve various aspects of the guidance in the following Accounting Standards Updates related to financial instruments:
- Accounting Standards Update No. 2016-01, Financial Instruments—Overall (Subtopic 825-10): Recognition and Measurement of Financial Assets and Liabilities
- Accounting Standards Update No. 2016-13, Financial Instruments—Credit Losses (Topic 326): Measurement of Credit Losses on Financial Instruments
- Accounting Standards Update No. 2017-12, Derivatives and Hedging (Topic 815): Targeted Improvements to Accounting for Hedging Activities
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2018-320—Intangibles—Goodwill and Other (Topic 350), Business Combinations (Topic 805), and Not-for-Profit Entities (Topic 958): Extending the Private Company Accounting Alternatives on Goodwill and Certain Identifiable Intangible Assets to Not-for-Profit Entities, which has been deleted.
Issued: April 25, 2019
2019-05Accounting Standards Update No. 2019-05—Financial Instruments—Credit Losses (Topic 326)—Targeted Transition Relief326
The amendments in this Update provide entities with an option to irrevocably elect the fair value option applied on an instrument-by-instrument basis for certain financial assets upon the adoption of Topic 326.
The fair value option election does not apply to held-to-maturity debt securities.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2019-100—Targeted Transition Relief for Topic 326, Financial Instruments—Credit Losses, which has been deleted.
Issued: May 15, 2019
2019-06Accounting Standards Update No. 2019-06—Intangibles—Goodwill and Other (Topic 350), Business Combinations (Topic 805), and Not-for-Profit Entities (Topic 958): Extending the Private Company Accounting Alternatives on Goodwill and Certain Identifiable Intangible Assets to Not-for-Profit Entities350805958
The objective of the amendments in this Update is to address the concerns of not-for-profit stakeholders that the benefits of the current accounting for goodwill and certain identifiable intangible assets acquired in a business combination do not justify the related costs. Therefore, the amendments in this Update permit a not-for-profit entity to elect the private company alternatives. Under Topic 350, instead of testing goodwill for impairment annually at the reporting unit level, a not-for-profit entity can elect to amortize goodwill on a straight-line basis, test for impairment upon a triggering event, and have the option to elect to test for impairment at the entity level. Under the Topic 805, a not-for-profit entity can elect to recognize fewer items as separate intangible assets in an acquisition. The amendments in this Update are effective immediately.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2018-320—Intangibles—Goodwill and Other (Topic 350), Business Combinations (Topic 805), and Not-for-Profit Entities (Topic 958): Extending the Private Company Accounting Alternatives on Goodwill and Certain Identifiable Intangible Assets to Not-for-Profit Entities, which has been deleted.
Issued: May 30, 2019
2019-07Accounting Standards Update No. 2019-07—Codification Updates to SEC Sections: Amendments to SEC Paragraphs Pursuant to SEC Final Rule Releases No. 33-10532, Disclosure Update and Simplification, and Nos. 33-10231 and 33-10442, Investment Company Reporting Modernization, and Miscellaneous Updates
This Accounting Standards Update amends various SEC paragraphs pursuant to the issuance of SEC Final Rule Releases No. 33-10532, Disclosure Update and Simplification, and Nos. 33-10231 and 33-10442, Investment Company Reporting Modernization. Other miscellaneous updates to agree to the electronic Code of Federal Regulations also have been incorporated.
Issued: July 26, 2019
2019-08Accounting Standards Update No. 2019-08—Compensation—Stock Compensation (Topic 718) and Revenue from Contracts with Customers (Topic 606)606718
After the effective date of the amendments in Update 2018-07, the Codification would have no longer provided explicit guidance on when to measure share-based payment awards granted to a customer. The amendments in this Update require that an entity measure and classify share-based payment awards granted to a customer by applying the guidance in Topic 718. The amount recorded as a reduction of the transaction price is required to be measured on the basis of the grant-date fair value of the share-based payment award in accordance with Topic 718.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2019-400—Compensation—Stock Compensation (Topic 718) and Revenue from Contracts with Customers (Topic 606): Codification Improvements—Share-Based Consideration Payable to a Customer, which has been deleted.
Issued: November 11, 2019
2019-09Accounting Standards Update No. 2019-09—Financial Services—Insurance (Topic 944)—Effective Date944
Pursuant to a philosophy developed by the Board for establishing effective dates for major Updates, the Board decided that, generally, a major Update will first be effective for public business entities (per the Master Glossary) that are Securities and Exchange Commission (SEC) filers (per the Master Glossary), excluding entities eligible to be smaller reporting companies (SRCs) under the U.S. Securities and Exchange Commission's definition. For all other entities, including entities eligible to be SRCs, it is anticipated that the Board will consider requiring an effective date staggered at least two years after the effective date for public business entities that are SEC filers, excluding entities eligible to be SRCs. Generally, it is expected that early application would continue to be permitted for all entities. The Board applied this philosophy to the effective date for Accounting Standards Update No. 2018-12, Financial Services—Insurance (Topic 944): Targeted Improvements to the Accounting for Long-Duration Contracts (Insurance).
The Board decided to change the effective date for Insurance for public business entities that are SEC filers, excluding entities eligible to be SRCs, to be applied for fiscal years beginning after December 15, 2021, including interim periods within those years. The Board also decided to change the effective date for all other entities for fiscal years beginning after December 15, 2023, including interim periods within those fiscal years beginning after December 14, 2024. Early application continues to be allowed for all entities.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2019-760—Financial Services—Insurance (Topic 944): Effective Date, which has been deleted.
Issued: November 15, 2019
2019-10Accounting Standards Update No. 2019-10—Financial Instruments—Credit Losses (Topic 326), Derivatives and Hedging (Topic 815), and Leases (Topic 842)—Effective Dates326815842
Pursuant to a philosophy developed by the Board for establishing effective dates for major Updates, the Board decided that, generally, a major Update will first be effective for public business entities (per the Master Glossary) that are Securities and Exchange Commission (SEC) filers (per the Master Glossary), excluding entities eligible to be smaller reporting companies (SRCs) under the U.S. Securities and Exchange Commission's definition. Those entities are bucket-one entities. All other entities (bucket two), including entities eligible to be SRCs, all other public business entities, and all nonpublic business entities (private companies, not-for-profit organizations, and employee benefit plans) compose bucket two. For those entities, it is anticipated that the Board will consider requiring an effective date staggered at least two years after bucket one for major Updates. Generally, it is expected that early application would continue to be permitted for all entities. The Board applied this philosophy to the effective dates for the following major Updates (including amendments issued after the issuance of the original Update):
- 1Accounting Standards Update No. 2016-13, Financial Instruments—Credit Losses (Topic 326): Measurement of Credit Losses on Financial Instruments (Credit Losses), and, as a consequential amendment, Accounting Standards Update No. 2017-04, Intangibles—Goodwill and Other (Topic 350): Simplifying the Test for Goodwill Impairment (Goodwill)
- 2Accounting Standards Update No. 2017-12, Derivatives and Hedging (Topic 815): Targeted Improvements to Accounting for Hedging Activities (Hedging)
- 3Accounting Standards Update No. 2016-02, Leases (Topic 842) (Leases).
The Board addressed the application of the philosophy to Accounting Standards Update No. 2018-12, Financial Services—Insurance (Topic 944): Targeted Improvements to the Accounting for Long-Duration Contracts (Insurance), in a separate project.
For Credit Losses and Goodwill, the amended mandatory effective dates are as follows:
- 1Public business entities that meet the definition of an SEC filer, excluding entities eligible to be SRCs as defined by the SEC, for fiscal years beginning after December 15, 2019, including interim periods within those fiscal years
- 2All other entities for fiscal years beginning after December 15, 2022, including interim periods within those fiscal years.
For Hedging, because the Update already is effective for all public business entities, the Board retained the existing effective date for those entities, including SRCs. Consistent with having bucket two be at least two years after the initial effective date, the Board deferred the mandatory effective date for all other entities by an additional year. Therefore, Hedging is now effective for entities other than public business entities for fiscal years beginning after December 15, 2020, and interim periods within fiscal years beginning after December 15, 2021. Early application continues to be allowed.
For Leases, because the Update already is effective for (a) public business entities; (b) not-for-profit entities that have issued or are conduit bond obligors for securities that are traded, listed, or quoted on an exchange or an over-the-counter-market; and (c) employee benefit plans that file or furnish financial statements with or to the SEC, the Board retained the existing effective date for those entities, including SRCs. Consistent with having bucket two be at least two years after the initial effective date, the Board deferred the mandatory effective date for all other entities by an additional year. Therefore, Leases is now effective for those entities for fiscal years beginning after December 15, 2020, and interim periods within fiscal years beginning after December 15, 2021. Early application continues to be allowed.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2019-750—Financial Instruments—Credit Losses (Topic 326), Derivatives and Hedging (Topic 815), and Leases (Topic 842), which has been deleted.
Issued: November 15, 2019
2019-11Accounting Standards Update No. 2019-11—Codification Improvements to Topic 326, Financial Instruments—Credit Losses326
The amendments in this Update require entities to include expected recoveries of the amortized cost basis previously written off or expected to be written off in the valuation account for purchased financial assets with credit deterioration. In addition, the amendments in this Update clarify and improve various aspects of the guidance for Accounting Standards Update No. 2016-13, Financial Instruments—Credit Losses (Topic 326): Measurement of Credit Losses on Financial Instruments.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2019-710—Codification Improvements to Topic 326, Financial Instruments—Credit Losses, which has been deleted.
Issued: November 26, 2019
2019-12Accounting Standards Update No. 2019-12—Income Taxes (Topic 740)—Simplifying the Accounting for Income Taxes740
The amendments in this Update simplify the accounting for income taxes by removing certain exceptions to the general principles in Topic 740, Income Taxes. The amendments also improve consistent application or and simplify GAAP for other areas of Topic 740 by clarifying and amending existing guidance.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2019-700—Income Taxes (Topic 740)—Simplifying the Accounting for Income Taxes, which has been deleted.
Issued: December 18, 2019
2018
2018-01Accounting Standards Update No. 2018-01—Leases (Topic 842)—Land Easement Practical Expedient for Transition to Topic 842842
A number of stakeholders inquired about the application of Topic 842 to land easements. Land easements (also commonly referred to as rights of way) represent the right to use, access, or cross another entity's land for a specified purpose. There currently is diversity in practice in accounting for land easements.
The amendments in this Update provide an optional transition practical expedient to not evaluate under Topic 842 existing or expired land easements that were not previously accounted for as leases under Topic 840, Leases. An entity that elects this practical expedient should evaluate new or modified land easements under Topic 842 beginning at the date that the entity adopts Topic 842. An entity that does not elect this practical expedient should evaluate all existing or expired land easements in connection with the adoption of the new lease requirements in Topic 842 to assess whether they meet the definition of a lease.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2017-290—Leases (Topic 842)—Land Easement Practical Expedient for Transition to Topic 842, which has been deleted.
Issued: January 25, 2018
2018-02Accounting Standards Update No. 2018-02—Income Statement—Reporting Comprehensive Income (Topic 220)—Reclassification of Certain Tax Effects from Accumulated Other Comprehensive Income220
On December 22, 2017, the U.S. federal government enacted a tax bill, H.R.1, An Act to Provide for Reconciliation Pursuant to Titles II and V of the Concurrent Resolution on the Budget for Fiscal Year 2018 (Tax Cuts and Jobs Act of 2017). Stakeholders raised a narrow-scope financial reporting issue that arose as a consequence of the Tax Cuts and Jobs Act of 2017. The amendments in this Update allow a reclassification from accumulated other comprehensive income to retained earnings for stranded tax effects resulting from the Tax Cuts and Jobs Act of 2017. The amendments in this Update affect any entity that is required to apply the provisions of Topic 220, Income Statement-Reporting Comprehensive Income, and has items of other comprehensive income for which the related tax effects are presented in other comprehensive income as required by GAAP.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2018-210—Income Statement—Reporting Comprehensive Income (Topic 220), which has been deleted.
Issued: February 14, 2018
2018-03Accounting Standards Update No. 2018-03—Technical Corrections and Improvements to Financial Instruments—Overall (Subtopic 825-10)—Recognition and Measurement of Financial Assets and Financial Liabilities825
This update releases final Accounting Standards Update 2018-03—Technical Corrections and Improvements to Financial Instruments—Overall (Subtopic 825-10)—Recognition and Measurement of Financial Assets and Financial Liabilities. This update is the final version of Proposed Accounting Standards Update 2017-300, which has been deleted.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2017-300—Technical Corrections and Improvements to Recently Issued Standards—Accounting Standards Update No. 2016-01, Financial Instruments—Overall (Subtopic 825-10): Recognition and Measurement of Financial Assets and Financial Liabilities, which has been deleted.
Issued: February 28, 2018
2018-04Accounting Standards Update No. 2018-04—Investments—Debt Securities (Topic 320) and Regulated Operations (Topic 980)—Amendments to SEC Paragraphs Pursuant to SEC Staff Accounting Bulletin No. 117 and SEC Release No. 33-9273320980
This Accounting Standards Update supersedes SEC paragraphs pursuant to the SEC Staff Accounting Bulletin No. 117, which brings existing guidance into conformity with Topic 321, Investments—Equity Securities, and SEC Release No. 33-9273, which removed Regulation S-X Rule 3A-05, Special Requirements as to Public Utility Holding Companies.
Issued: March 9, 2018
2018-05Accounting Standards Update No. 2018-05—Income Taxes (Topic 740)—Amendments to SEC Paragraphs Pursuant to SEC Staff Accounting Bulletin No. 118740
This Accounting Standards Update adds SEC paragraphs pursuant to the SEC Staff Accounting Bulletin No. 118, which expresses the view of the staff regarding application of Topic 740, Income Taxes, in the reporting period that includes December 22, 2017 - the date on which the Tax Cuts and Jobs Act (H.R.1, An Act to Provide for Reconciliation Pursuant to Titles II and V of the Concurrent Resolution on the Budget for Fiscal Year 2018) was signed into law.
Issued: March 13, 2018
2018-06Accounting Standards Update No. 2018-06—Codification Improvements to Topic 942, Financial Services—Depository and Lending942
This Accounting Standards Update supersedes outdated guidance related to the Office of the Comptroller of the Currency's Banking Circular 202, Accounting for Net Deferred Tax Charges.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2017-260—Technical Corrections and Improvements to Topic 942, Financial Services—Depository and Lending—Elimination of Certain Guidance for Bad Debt Reserves of Savings and Loans, which has been deleted.
Issued: May 7, 2018
2018-07Accounting Standards Update No. 2018-07—Compensation—Stock Compensation (Topic 718)—Improvements to Nonemployee Share-Based Payment Accounting718
The amendments in this Update expand the scope of Topic 718 to include share-based payment transactions for acquiring goods and services from nonemployees.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2017-220—Compensation—Stock Compensation (Topic 718)—Improvements to Nonemployee Share-Based Payment Accounting, which has been deleted.
Issued: June 20, 2018
2018-08Accounting Standards Update No. 2018-08—Not-for-Profit Entities (Topic 958)—Clarifying the Scope and the Accounting Guidance for Contributions Received and Contributions Made958
The FASB is issuing this Update to clarify and improve the scope and the accounting guidance for contributions received and contributions made. The amendments in this Update should assist entities in (1) evaluating whether transactions should be accounted for as contributions (nonreciprocal transactions) within the scope of Topic 958, Not-for-Profit Entities, or as exchange (reciprocal) transactions subject to other guidance and (2) determining whether a contribution is conditional.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2017-270—Not-for-Profit Entities (Topic 958)—Clarifying the Scope and Accounting Guidance for Contributions Received and Contributions Made, which has been deleted.
Issued: June 21, 2018
2018-09Accounting Standards Update No. 2018-09—Codification Improvements
The amendments in this Update represent changes to clarify the Codification, correct unintended application of guidance, or make minor improvements to the Codification that are not expected to have a significant effect on current accounting practice or create a significant administrative cost to most entities. Some of the amendments make the Codification easier to understand and easier to apply by eliminating inconsistencies, providing needed clarifications, and improving the presentation of guidance in the Codification.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2017-320—Codification Improvements, which has been deleted.
Issued: July 16, 2018
2018-10Accounting Standards Update No. 2018-10—Codification Improvements to Topic 842, Leases842
The amendments in this Update are of a similar nature to the items typically addressed in the Codification improvements project. However, the Board decided to issue a separate Update for the improvements related to Accounting Standards Update No. 2016-02, Leases (Topic 842), to increase stakeholders' awareness of the amendments and to expedite the improvements. The amendments in this Update affect narrow aspects of the guidance issued in Update 2016-02.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2017-310—Technical Corrections and Improvements to Recently Issued Standards−Accounting Standards Update No. 2016-02, Leases (Topic 842), which has been deleted.
Issued: July 18, 2018
2018-11Accounting Standards Update No. 2018-11—Leases (Topic 842): Targeted Improvements842
Transition—Comparative Reporting at Adoption
The amendments in this Update will provide entities with an additional (and optional) transition method to adopt the new lease requirements by allowing entities to initially apply the requirements by recognizing a cumulative-effect adjustment to the opening balance of retained earnings in the period of adoption. Consequently, an entity's reporting for the comparative periods presented in the financial statements in which the entity adopts the new lease requirements would continue to be in accordance with current GAAP (Topic 840). An entity electing this additional (and optional) transition method must provide the required Topic 840 disclosures for all periods that continue to be in accordance with Topic 840. The amendments do not change the existing disclosure requirements in Topic 840 (for example, they do not create interim disclosure requirements that entities previously were not required to provide.
Separating Components of a Contract
The amendments in this Update provide lessors with a practical expedient, by class of underlying asset, to not separate nonlease components from the associated lease component and, instead, to account for those components as a single component if the nonlease components otherwise would be accounted for under the new revenue guidance (Topic 606) and both of the following are met:
- 1The timing and pattern of transfer of the nonlease component(s) and associated lease component are the same.
- 2The lease component, if accounted for separately, would be classified as an operating lease.
If the nonlease component or components associated with the lease component are the predominant component of the combined component, an entity is required to account for the combined component in accordance with Topic 606. Otherwise, the entity must account for the combined component as an operating lease in accordance with Topic 842. In addition, an entity electing this practical expedient (including an entity that accounts for the combined component entirely in Topic 606) is required to provide certain disclosures.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2018-200—Leases (Topic 842)—Targeted Improvements, which has been deleted.
Issued: July 30, 2018
2018-12Accounting Standards Update No. 2018-12—Financial Services—Insurance (Topic 944): Targeted Improvements to the Accounting for Long-Duration Contracts944
The amendments in this Update make targeted improvements to the existing recognition, measurement, presentation, and disclosure requirements for long-duration contracts issued by an insurance entity. Specifically, the amendments in this Update (1) improve the timeliness of recognizing changes in the liability for future policy benefits and modify the rate used to discount future cash flows, (2) simplify and improve the accounting for certain market-based options or guarantees associated with deposit (or account balance) contracts, (3) simplify the amortization of deferred acquisition costs, and (4) improve the effectiveness of the required disclosures.
This Update is the final version of Proposed Accounting Standards Update 2016-330 - Financial Services - Insurance (Topic 944) - Targeted Improvements to the Accounting for Long-Duration Contracts, which has been deleted.
Issued: August 15, 2018
2018-13Accounting Standards Update No. 2018-13—Fair Value Measurement (Topic 820)—Disclosure Framework—Changes to the Disclosure Requirements for Fair Value Measurement820
The Board is issuing the amendments in this Update to improve the effectiveness of fair value measurement disclosures. The amendments in this Update modify the disclosure requirements on fair value measurements in Topic 820, Fair Value Measurement, based on the concepts in FASB Concepts Statement, Conceptual Framework for Financial Reporting—Chapter 8: Notes to Financial Statements, including the consideration of costs and benefits.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2015-350—Fair Value Measurement (Topic 820)—Disclosure Framework—Changes to the Disclosure Requirements for Fair Value Measurements, which has been deleted.
Issued: August 28, 2018
2018-14Accounting Standards Update No. 2018-14—Compensation—Retirement Benefits—Defined Benefit Plans—General (Subtopic 715-20)—Disclosure Framework—Changes to the Disclosure Requirements for Defined Benefit Plans715
Subtopic 715-20 addresses the disclosure of other accounting and reporting requirements related to single-employer defined benefit pension or other postretirement benefit plans.
The amendments in this Update remove disclosures that no longer are considered cost-beneficial, clarify the specific requirements of disclosures, and add disclosure requirements identified as relevant. Although narrow in scope, the amendments are considered an important part of the Board's efforts to improve the effectiveness of disclosures in the notes to financial statements by applying concepts in the FASB Concepts Statement, Conceptual Framework for Financial Reporting—Chapter 8: Notes to Financial Statements. The amendments in this Update apply to all employers that sponsor defined benefit pension or other postretirement plans.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2016-210—Compensation—Retirement Benefits—Defined Benefit Plans—General (Subtopic 715-20)—Changes to the Disclosure Requirements for Defined Benefit Plans, which has been deleted.
Issued: August 28, 2018
2018-15Accounting Standards Update No. 2018-15—Intangibles—Goodwill and Other—Internal-Use Software (Subtopic 350-40): Customer's Accounting for Implementation Costs Incurred in a Cloud Computing Arrangement That Is a Service Contract350
The amendments in this Update align the requirements for capitalizing implementation costs incurred in a hosting arrangement that is a service contract with the requirements for capitalizing implementation costs incurred to develop or obtain internal-use software (and hosting arrangements that include an internal-use software license). Accordingly, the amendments require an entity (customer) in a hosting arrangement that is a service contract to follow the guidance in Subtopic 350-40 to determine which implementation costs to capitalize as an asset related to the service contract and which costs to expense.
The amendments also require the entity (customer) to expense the capitalized implementation costs of a hosting arrangement that is a service contract over the term of the hosting arrangement, which includes reasonably certain renewals.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2018-230—Intangibles—Goodwill and Other—Internal-Use Software (Subtopic 350-40): Customer's Accounting for Implementation Costs Incurred in a Cloud Computing Arrangement That Is a Service Contract, which has been deleted.
Issued: August 29, 2018
2018-16Accounting Standards Update No. 2018-16—Derivatives and Hedging (Topic 815)—Inclusion of the Secured Overnight Financing Rate (SOFR) Overnight Index Swap (OIS) Rate as a Benchmark Interest Rate for Hedge Accounting Purposes815
During the hedge accounting project that led to the issuance of Update 2017-12, the Federal Reserve Board and the Federal Reserve Bank of New York (Fed) requested that the OIS rate based on SOFR be considered eligible as a U.S. benchmark interest rate for purposes of applying hedge accounting under Topic 815. Similar to the OIS rate based on the Fed Funds Effective Rate, which is a swap rate based on the underlying overnight Fed Funds Effective Rate, the OIS rate based on SOFR will be a swap rate based on the underlying overnight SOFR rate. The Fed and Alternative Reference Rate Committee (ARRC) expressed the importance of including the OIS rate based on SOFR as a benchmark rate for hedge accounting purposes in facilitating broader use of the underlying SOFR rate in the marketplace.
The amendments in this Update permit use of the OIS rate based on SOFR as a U.S. benchmark interest rate for hedge accounting purposes under Topic 815 in addition to the UST, the LIBOR swap rate, the OIS rate based on the Fed Funds Effective Rate, and the SIFMA Municipal Swap Rate.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2018-220—Derivatives and Hedging (Topic 815)—Inclusion of the Secured Overnight Financing Rate (SOFR) Overnight Index Swap (OIS) Rate as a Benchmark Interest Rate for Hedge Accounting Purposes, which has been deleted.
Issued: October 25, 2018
2018-17Accounting Standards Update No. 2018-17—Consolidation (Topic 810)—Targeted Improvements to Related Party Guidance for Variable Interest Entities810
The amendments in this Update affect reporting entities that are required to determine whether they should consolidate a legal entity under the guidance within the Variable Interest Entities Subsections of Subtopic 810-10, Consolidation—Overall.
Private Company Accounting Alternative
A private company (reporting entity) may elect not to apply VIE guidance to legal entities under common control (including common control leasing arrangements) if both the parent and the legal entity being evaluated for consolidation are not public business entities. The accounting alternative provides an accounting policy election that a private company will apply to all current and future legal entities under common control that meet the criteria for applying this alternative. If the alternative is elected, a private company should continue to apply other consolidation guidance, particularly the voting interest entity guidance, unless another scope exception applies.
Decision-Making Fees
Indirect interests held through related parties in common control arrangements should be considered on a proportional basis for determining whether fees paid to decision makers and service providers are variable interests. This is consistent with how indirect interests held through related parties under common control are considered for determining whether a reporting entity must consolidate a VIE.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2017-240—Consolidation (Topic 810)—Targeted Improvements to Related Party Guidance for Variable Interest Entities, which has been deleted.
Issued: October 31, 2018
2018-18Accounting Standards Update No. 2018-18—Collaborative Arrangements (Topic 808)—Clarifying the Interaction between Topic 808 and Topic 606606808
The amendments in this Update clarify the interaction between Topic 808 and Topic 606 by (1) clarifying that certain transactions between collaborative arrangement participants should be accounted for under Topic 606, (2) adding unit-of-account guidance in Topic 808 to align with the guidance in Topic 606, and (3) clarifying presentation guidance for transactions with a collaborative arrangement participant that are not accounted for under Topic 606.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2018-240—Collaborative Arrangements (Topic 808): Targeted Improvements, which has been deleted.
Issued: November 5, 2018
2018-19Accounting Standards Update No. 2018-19—Codification Improvements to Topic 326, Financial Instruments—Credit Losses326
This update releases Accounting Standards Update No. 2018-19—Codification Improvements to Topic 326, Financial Instruments—Credit Losses. This update is the final version of Proposed Accounting Standards Update 2018-270, which has been deleted.
Additionally, the amendments clarify that receivables arising from operating leases are not within the scope of Subtopic 326-20. Instead, impairment of receivables arising from operating leases should be accounted for in accordance with Topic 842, Leases.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2018-270—Codification Improvements to Topic 326, Financial Instruments—Credit Losses, which has been deleted.
Issued: November 15, 2018
2018-20Accounting Standards Update No. 2018-20—Leases (Topic 842)—Narrow-Scope Improvements for Lessors842
Sales Taxes and Other Similar Taxes Collected from Lessees
The amendments in this Update permit lessors, as an accounting policy election, to not evaluate whether certain sales taxes and other similar taxes are lessor costs (as described in paragraph 842-10-15-30(b)) or lessee costs. Instead, those lessors will account for those costs as if they are lessee costs. Consequently, a lessor making this election will exclude from the consideration in the contract and from variable payments not included in the consideration in the contract all collections from lessees of taxes within the scope of the election and will provide certain disclosures.
Certain Lessor Costs
The amendments in this Update related to certain lessor costs require lessors to exclude from variable payments, and therefore revenue, lessor costs paid by lessees directly to third parties from variable payments. The amendments also require lessors to account for costs excluded from the consideration of a contract that are paid by the lessor and reimbursed by the lessee as variable payments. A lessor will record those reimbursed costs as revenue.
Recognition of Variable Payments for Contracts with Lease and Nonlease Components
The amendments in this Update related to recognizing variable payments for contracts with lease and nonlease components require lessors to allocate (rather than recognize as currently required) certain variable payments to the lease and nonlease components when the changes in facts and circumstances on which the variable payment is based occur. After the allocation, the amount of variable payments allocated to the lease components will be recognized as income in profit or loss in accordance with Topic 842, while the amount of variable payments allocated to nonlease components will be recognized in accordance with other Topics, such as Topic 606.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2018-260—Leases (Topic 842)—Narrow-Scope Improvements for Lessors, which has been deleted.
Issued: December 10, 2018
2017
2017-01Accounting Standards Update No. 2017-01—Business Combinations (Topic 805): Clarifying the Definition of a Business805
The amendments in this Update clarify the definition of a business with the objective of adding guidance to assist entities with evaluating whether transactions should be accounted for as acquisitions (or disposals) of businesses.
The amendments in this Update provide a screen to determine when a set is not a business. If the screen is not met, it (1) requires that to be considered a business, a set must include, at a minimum, an input and a substantive process that together significantly contribute to the ability to create output and (2) removes the evaluation of whether a market participant could replace the missing elements.
This Update is the final version of Proposed Accounting Standards Update 2015-330 BusinessCombinations (Topic 805)- Clarifying The Definition of a Business, which has been deleted.
Issued: January 5, 2017
2017-02Accounting Standards Update No. 2017-02—Not-for-Profit Entities—Consolidation (Subtopic 958-810): Clarifying When a Not-for-Profit Entity That Is a General Partner or a Limited Partner Should Consolidate a For-Profit Limited Partnership or Similar Entity958
The FASB is issuing this Accounting Standards Update to amend the consolidation guidance in Subtopic 958-810, Not-for-Profit Entities—Consolidation, to clarify when a not-for-profit entity (NFP) that is a general partner or a limited partner should consolidate a for-profit limited partnership or similar legal entity once the amendments in Accounting Standards Update No. 2015-02, Consolidation (Topic 810): Amendments to the Consolidation Analysis, become effective. The amendments in this Update maintain how NFP general partners currently apply the consolidation guidance in Subtopic 810-20 by including that guidance within Subtopic 958-810. The amendments also add to Subtopic 958-810 the general guidance in Subtopic 810-10 on when NFP limited partners should consolidate a limited partnership.
This Update is the final version of Proposed Accounting Standards Update 2016-280—Not-for-Profit Entities—Consolidation (Subtopic 958-810)—Clarifying When a Not-for-Profit Entity That Is a General Partner Should Consolidate a For-Profit Limited Partnership or Similar Entity, which has been deleted.
Issued: January 12, 2017
2017-03Accounting Standards Update No. 2017-03—Accounting Changes and Error Corrections (Topic 250) and Investments—Equity Method and Joint Ventures (Topic 323)250323
This Accounting Standards Update adds and amends SEC paragraphs pursuant to the SEC Staff Announcements at the September 22, 2016 and November 17, 2016 Emerging Issues Task Force (EITF) meetings. The September announcement is about the Disclosure of the Impact That Recently Issued Accounting Standards Will Have on the Financial Statements of a Registrant When Such Standards are Adopted in a Future Period. The November announcement made amendments to conform the SEC Observer Comment on Accounting for Tax Benefits Resulting from Investments in Qualified Affordable Housing Projects to the guidance issued in Accounting Standards Update No. 2014-01, Investments—Equity Method and Joint Ventures (Topic 323): Accounting for Investments in Qualified Affordable Housing Projects.
Issued: January 23, 2017
2017-04Accounting Standards Update No. 2017-04—Intangibles—Goodwill and Other (Topic 350): Simplifying the Test for Goodwill Impairment350
Topic 350, Intangibles—Goodwill and Other (Topic 350), currently requires an entity that has not elected the private company alternative for goodwill to perform a two-step test to determine the amount, if any, of goodwill impairment. In Step 1, an entity compares the fair value of a reporting unit with its carrying amount, including goodwill. If the carrying amount of the reporting unit exceeds its fair value, the entity performs Step 2 and compares the implied fair value of goodwill with the carrying amount of that goodwill for that reporting unit. An impairment charge equal to the amount by which the carrying amount of goodwill for the reporting unit exceeds the implied fair value of that goodwill is recorded, limited to the amount of goodwill allocated to that reporting unit.
To address concerns over the cost and complexity of the two-step goodwill impairment test, the amendments in this Update remove the second step of the test. An entity will apply a one-step quantitative test and record the amount of goodwill impairment as the excess of a reporting unit's carrying amount over its fair value, not to exceed the total amount of goodwill allocated to the reporting unit. The new guidance does not amend the optional qualitative assessment of goodwill impairment.
This Update is the final version of Proposed Accounting Standards Update 2016-230—Intangibles—Goodwill and Other (Topic 350)—Simplifying the Accounting for Goodwill Impairment, which has been deleted.
Issued: January 26, 2017
2017-05Accounting Standards Update No. 2017-05—Other Income—Gains and Losses from the Derecognition of Nonfinancial Assets (Subtopic 610-20): Clarifying the Scope of Asset Derecognition Guidance and Accounting for Partial Sales of Nonfinancial Assets610
The amendments in this Update clarify the scope of the nonfinancial asset guidance in Subtopic 610-20. The amendments also clarify that the derecognition of all businesses and nonprofit activities (except those related to conveyances of oil and gas mineral rights or contracts with customers) should be accounted for in accordance with the derecognition and deconsolidation guidance in Subtopic 810-10. In addition, the amendments eliminate the exception in the financial asset guidance for transfers of investments (including equity method investments) in real estate entities and supersede the guidance in the Exchanges of a Nonfinancial Asset for a Noncontrolling Ownership Interest Subsection within Topic 845. The amendments in this Update also provide guidance on the accounting for what often are referred to as partial sales of nonfinancial assets within the scope of Subtopic 610-20 and contributions of nonfinancial assets to a joint venture or other noncontrolled investee.
This Update is the final version of Proposed Accounting Standards Update 2016-250—Other Income—Gains and Losses from the Derecognition of Nonfinancial Assets (Subtopic 610-20)—Clarifying the Scope of Asset Derecognition Guidance and Accounting for Partial Sales of Nonfinancial Assets, which has been deleted.
Issued: February 22, 2017
2017-06Accounting Standards Update No. 2017-06—Plan Accounting (Topics 960, 962, and 965): Employee Benefit Plan Master Trust Reporting
The Board is issuing this Update to improve the usefulness of the information reported to users of employee benefit plan financial statements. This Update relates primarily to the reporting by an employee benefit plan (a plan) for its interest in a master trust. A master trust is a trust for which a regulated financial institution (bank, trust company, or similar financial institution that is regulated, supervised, and subject to periodic examination by a state or federal agency) serves as a trustee or custodian and in which assets of more than one plan sponsored by a single employer or by a group of employers under common control are held.
This Update is the final version of Proposed Accounting Standards Update EITF-16B—Plan Accounting: Defined Benefit Pension Plans (Topic 960), Defined Contribution Pension Plans (Topic 962), Health and Welfare Benefit Plans (Topic 965), which has been deleted.
Issued: February 27, 2017
2017-07Accounting Standards Update No. 2017-07—Compensation—Retirement Benefits (Topic 715): Improving the Presentation of Net Periodic Pension Cost and Net Periodic Postretirement Benefit Cost715
Topic 715, Compensation-Retirement Benefits, requires an entity to present net periodic pension cost and net periodic postretirement benefit cost as a net amount that may be capitalized as part of an asset where appropriate.
Users have communicated that the service cost component generally is analyzed differently from the other components of net periodic pension cost and net periodic postretirement benefit cost. To improve the consistency, transparency, and usefulness of financial information for users, the amendments in this Update require that an employer report the service cost component in the same line item or items as other compensation costs arising from services rendered by the pertinent employees during the period. It also requires the other components of net periodic pension cost and net periodic postretirement benefit cost as defined in paragraphs 715-30-35-4 and 715-60-35-9 to be presented in the income statement separately from the service cost component and outside a subtotal of income from operations, if one is presented. Additionally, only the service cost component is eligible for capitalization, when applicable.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2016-200—Compensation—Retirement Benefits (Topic 715): Improving the Presentation of Net Periodic Pension Cost and Net Periodic Postretirement Benefit Cost, which has been deleted.
Issued: March 10, 2017
2017-08Accounting Standards Update No. 2017-08—Receivables—Nonrefundable Fees and Other Costs (Subtopic 310-20): Premium Amortization on Purchased Callable Debt Securities310
This Accounting Standards Update amends guidance on the amortization period of premiums on certain purchased callable debt securities. Specifically, the amendments shorten the amortization period of premiums on certain purchased callable debt securities to the earliest call date. The amendments affect all entities that hold investments in callable debt securities that have an amortized cost basis in excess of the amount that is repayable by the issuer at the earliest call date (that is, at a premium).
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2016-340—Receivables—Nonrefundable Fees and Other Costs (Subtopic 310-20): Premium Amortization on Purchased Callable Debt Securities, which has been deleted.
Issued: March 30, 2017
2017-09Accounting Standards Update No. 2017-09—Compensation—Stock Compensation (Topic 718): Scope of Modification Accounting718
The Board is issuing this Update to provide clarity and reduce both (1) diversity in practice and (2) cost and complexity when applying the guidance in Topic 718, Compensation—Stock Compensation, to a change to the terms or conditions of a share-based payment award.
The amendments in this Update provide guidance about which changes to the terms or conditions of a share-based payment award require an entity to apply modification accounting in Topic 718.
This Update is the final version of Proposed Accounting Standards Update 2016-360—Compensation—Stock Compensation (Topic 718)—Scope of Modification Accounting, which has been deleted.
Issued: May 10, 2017
2017-10Accounting Standards Update No. 2017-10—Service Concession Arrangements (Topic 853): Determining the Customer of the Operation Services853
Stakeholders indicated that there is diversity in practice in how an operating entity determines the customer of the operation services for transactions within the scope of Topic 853, Service Concession Arrangements.
A service concession arrangement is one between a public-sector entity grantor and an operating entity whereby the operating entity will operate and sometimes maintain the grantor's infrastructure (for example, airports, roads, bridges, tunnels, prisons, and hospitals) for a specified period of time. The amendments in this Update clarify that the grantor, rather than a third-party, is the customer of the operation services in all cases for service concession arrangements within the scope of Topic 853.
This Update is the final version of Proposed Accounting Standards Update EITF-16C—Service Concession Arrangements (Topic 853): Determining the Customer of the Operation Services, which has been deleted.
Issued: May 16, 2017
2017-11Accounting Standards Update No. 2017-11—Earnings Per Share (Topic 260); Distinguishing Liabilities from Equity (Topic 480); Derivatives and Hedging (Topic 815): (Part I) Accounting for Certain Financial Instruments with Down Round Features, (Part II) Replacement of the Indefinite Deferral for Mandatorily Redeemable Financial Instruments of Certain Nonpublic Entities and Certain Mandatorily Redeemable Noncontrolling Interests with a Scope Exception260480815
The amendments in the Update change the classification of certain equity-linked financial instruments (or embedded features) with down round features. The amendments also clarify existing disclosure requirements for equity-classified instruments.
For freestanding equity-classified financial instruments, the amendments require entities that present earnings per share (EPS) in accordance with Topic 260, Earnings Per Share, to recognize the effect of the down round feature when it is triggered. That effect is treated as a dividend and as a reduction of income available to common shareholders in basic EPS.
Convertible instruments with embedded conversion options that have down round features would be subject to the specialized guidance for contingent beneficial conversion features (in Subtopic 470-20, Debt—Debt with Conversion and Other Options), including related EPS guidance (in Topic 260).
The amendments in Part II of this Update recharacterize the indefinite deferral of certain provisions of Topic 480, Distinguishing Liabilities from Equity, that now are presented as pending content in the Codification, to a scope exception. Those amendments do not have an accounting effect.
This Update is the final version of Proposed Accounting Standards Update 2016-370—Distinguishing Liabilities from Equity (Topic 480), which has been deleted.
Issued: July 13, 2017
2017-12Accounting Standards Update No. 2017-12—Derivatives and Hedging (Topic 815): Targeted Improvements to Accounting for Hedging Activities815
The amendments in this Update better align an entity's risk management activities and financial reporting for hedging relationships through changes to both the designation and measurement guidance for qualifying hedging relationships and the presentation of hedge results. To meet that objective, the amendments expand and refine hedge accounting for both nonfinancial and financial risk components and align the recognition and presentation of the effects of the hedging instrument and the hedged item in the financial statements.
The amendments in this Update also make certain targeted improvements to simplify the application of hedge accounting guidance and ease the administrative burden of hedge documentation requirements and assessing hedge effectiveness.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2016-310—Derivatives and Hedging (Topic 815): Targeted Improvements to Accounting for Hedging Activities, which has been deleted.
Issued: August 28, 2017
2017-13Accounting Standards Update No. 2017-13—Revenue Recognition (Topic 605), Revenue from Contracts with Customers (Topic 606), Leases (Topic 840), and Leases (Topic 842)605606840842
This Accounting Standards Update adds SEC paragraphs pursuant to the SEC Staff Announcement at the July 20, 2017 Emerging Issues Task Force (EITF) meeting. The July announcement addresses Transition Related to Accounting Standards Updates No. 2014-09, Revenue from Contracts with Customers (Topic 606), and No. 2016-02, Leases (Topic 842). This Update also supersedes SEC paragraphs pursuant to the rescission of SEC Staff Announcement, “Accounting for Management Fees Based on a Formula,” effective upon the initial adoption of Topic 606, Revenue from Contracts with Customers, and SEC Staff Announcement, “Lessor Consideration of Third-Party Value Guarantees,” effective upon the initial adoption of Topic 842, Leases. The amendments in this Update also rescind three SEC Observer Comments effective upon the initial adoption of Topic 842. One SEC Staff Observer comment is being moved to Topic 842.
Issued: September 29, 2017
2017-14Accounting Standards Update No. 2017-14—Income Statement—Reporting Comprehensive Income (Topic 220), Revenue Recognition (Topic 605), and Revenue from Contracts with Customers (Topic 606)220605606
This Accounting Standards Update amends SEC paragraphs pursuant to the SEC Staff Accounting Bulletin No. 116 and SEC Release No. 33-10403, which bring existing guidance into conformity with Topic 606, Revenue from Contracts with Customers.
Issued: November 22, 2017
2017-15Accounting Standards Update No. 2017-15—Codification Improvements to Topic 995, U.S. Steamship Entities: Elimination of Topic 995
The amendments in this Update supersede Topic 995, U.S. Steamship Entities, because its guidance is no longer relevant. FASB Statement No. 109, Accounting for Income Taxes, provided an option in the reporting of deferred taxes for steamship entities that had statutory reserve deposits that were made before December 15, 1992. The Department of Transportation program from which these statutory reserve deposits originate and the Internal Revenue Service (IRS) provide a 25-year time frame in which to use the reserves or forfeit the tax deferral. The Board decided that all steamship entities with statutory reserve funds should be reporting all deferred taxes in accordance with Topic 740, Income Taxes, and that the guidance in Topic 995 on transitioning to the requirements of Topic 740 is no longer relevant because statutory funds deposited on or before December 15, 1992, have reached the 25-year limit.
This Update is the final version of Proposed Accounting Standards Update 2017-250—Technical Corrections and Improvements to Topic 995, U.S. Steamship Entities: Elimination of Topic 995.
Issued: December 5, 2017
2016
2016-01Accounting Standards Update No. 2016-01—Financial Instruments—Overall (Subtopic 825-10)825
The amendments in this Update require all equity investments to be measured at fair value with changes in the fair value recognized through net income (other than those accounted for under equity method of accounting or those that result in consolidation of the investee).
The amendments in this Update also require an entity to present separately in other comprehensive income the portion of the total change in the fair value of a liability resulting from a change in the instrument-specific credit risk when the entity has elected to measure the liability at fair value in accordance with the fair value option for financial instruments. In addition the amendments in this Update eliminate the requirement to disclose the fair value of financial instruments measured at amortized cost for entities that are not public business entities and the requirement for to disclose the method(s) and significant assumptions used to estimate the fair value that is required to be disclosed for financial instruments measured at amortized cost on the balance sheet for public business entities.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2013-220—Financial Instruments—Overall (Subtopic 825-10) and Proposed Accounting Standards Update 2013-221—Financial Instruments—Overall (Subtopic 825-10).
For more information, see the following:
Issued: January 5, 2016
2016-02Accounting Standards Update No. 2016-02—Leases (Topic 842)842
The amendments in this Update create Topic 842, Leases, and supersede the leases requirements in Topic 840, Leases. Topic 842 specifies the accounting for leases. The objective of Topic 842 is to establish the principles that lessees and lessors shall apply to report useful information to users of financial statements about the amount, timing, and uncertainty of cash flows arising from a lease.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update (Revised) 2013-270—Leases (Topic 842), which has been deleted.
Accounting Standards Update 2016-02
Section A (PDF)—Summary and Amendments to the Accounting Standards Codification
Section B (PDF)—Conforming Amendments to Other Topics and Subtopics in the Codification and Status Tables
Section C (PDF)—Background Information and Basis for Conclusions
Issued: February 25, 2016
2016-03Accounting Standards Update No. 2016-03—Intangibles—Goodwill and Other (Topic 350); Business Combinations (Topic 805); Consolidation (Topic 810); Derivatives and Hedging (Topic 815): Effective Date and Transition Guidance350805810815
The amendments in this Update address the concerns of private company stakeholders about the required assessment of preferability when electing a private company accounting alternative for the first time after its effective date. Those stakeholders were concerned about scenarios in which it may be suboptimal for a private company to elect the alternative by its effective date because of the private company's facts and circumstances or because it was unaware of the alternative until after the effective date. Stakeholders were also concerned about whether private companies were benefiting from the favorable transition provisions provided in other Updates when a private company voluntarily elects an alternative in those Update after its effective date.
The amendments in this Update resolve stakeholders' concerns by making the guidance in Updates 2014-02, 2014-03, 2014-07, and 2014-18 effective immediately by removing their effective dates. The amendments in this Update also extend the transition guidance in those Updates indefinitely.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update PCC-15-01—Intangibles—Goodwill and Other (Topic 350), Business Combinations (Topic 805), Consolidation (Topic 810), and Derivatives and Hedging (Topic 815): Effective Date and Transition Guidance, which has been deleted.
For more information, see the following:
Issued: March 7, 2016
2016-04Accounting Standards Update No. 2016-04—Liabilities—Extinguishments of Liabilities (Subtopic 405-20): Recognition of Breakage for Certain Prepaid Stored-Value Products405
When an entity sells a prepaid stored-value product (such as gift cards, telecommunication cards, and traveler's checks), it recognizes a financial liability for its obligation to provide the product holder with the ability to purchase goods or services at a third-party merchant. When a prepaid stored-value product goes unused wholly or partially for an indefinite time period, the amount that remains on the product is referred to as breakage. There currently is diversity in the methodology used to recognize breakage. Subtopic 405-20 includes derecognition guidance for both financial liabilities and nonfinancial liabilities, and Topic 606, Revenue from Contracts with Customers, includes authoritative breakage guidance but excludes financial liabilities.
The amendments in this Update provide a narrow scope exception to the guidance in Subtopic 405-20 to require that breakage be accounted for consistent with the breakage guidance in Topic 606.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update EITF-15B—Liabilities—Extinguishments of Liabilities (Subtopic 405-20): Recognition of Breakage for Certain Prepaid Stored-Value Cards, which has been deleted.
For more information, see the following:
Issued: March 8, 2016
2016-05Accounting Standards Update No. 2016-05—Derivatives and Hedging (Topic 815): Effect of Derivative Contract Novations on Existing Hedge Accounting Relationships815
The term novation refers to replacing one counterparty to a derivative instrument with a new counterparty. That change occurs for a variety of reasons, including financial institution mergers, intercompany transactions, an entity exiting a particular derivatives business or relationship, an entity managing against internal credit limits, or in response to laws or regulatory requirements.
The amendments in this Update clarify that a change in the counterparty to a derivative instrument that has been designated as the hedging instrument under Topic 815, does not, in and of itself, require dedesignation of that hedging relationship provided that all other hedge accounting criteria continue to be met.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update EITF-15D—Derivatives and Hedging (Topic 815): Effect of Derivative Contract Novations on Existing Hedge Accounting Relationships, which has been deleted.
For more information, see the following:
Issued: March 10, 2016
2016-06Accounting Standards Update No. 2016-06—Derivatives and Hedging (Topic 815): Contingent Put and Call Options in Debt Instruments815
Topic 815 requires that embedded derivatives be separated from the host contract and accounted for separately as derivatives if certain criteria are met, including the “clearly and closely related” criterion. The amendments in this Update clarify the requirements for assessing whether contingent call (put) options that can accelerate the payment of principal on debt instruments are clearly and closely related to their debt hosts. An entity performing the assessment under the amendments is required to assess the embedded call (put) options solely in accordance with the four-step decision sequence. The amendments apply to all entities that are issuers of or investors in debt instruments (or hybrid financial instruments that are determined to have a debt host) with embedded call (put) options.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update EITF-15E—Derivatives and Hedging (Topic 815): Contingent Put and Call Options in Debt Instruments, which has been deleted.
For more information, see the following:
Issued: March 14, 2016
2016-07Accounting Standards Update No. 2016-07—Investments—Equity Method and Joint Ventures (Topic 323)323
To simplify the accounting for equity method investments, the amendments in the Update eliminate the requirement in Topic 323 that an entity retroactively adopt the equity method of accounting if an investment qualifies for use of the equity method as a result of an increase in the level of ownership or degree of influence. The amendments require that the equity method investor add the cost of acquiring the additional interest in the investee to the current basis of the investor's previously held interest and adopt the equity method of accounting as of the date the investment becomes qualified for equity method accounting.
The amendments require that the equity method investor add the cost of acquiring the additional interest in the investee to the current basis of the investor's previously held interest and adopt the equity method of accounting as of the date the investment becomes qualified for equity method accounting.
For more information, see the following:
Issued: March 15, 2016
2016-08Accounting Standards Update No. 2016-08—Revenue from Contracts with Customers (Topic 606): Principal versus Agent Considerations (Reporting Revenue Gross versus Net)606
This update releases Accounting Standards Update No. 2016-08--Revenue from Contracts with Customers (Topic 606): Principal versus Agent Considerations (Reporting Revenue Gross versus Net). The amendments in this Update will clarify the implementation guidance on principal versus agent considerations.
For more information, see the following:
Issued: March 17, 2016
2016-09Accounting Standards Update No. 2016-09—Compensation—Stock Compensation (Topic 718): Improvements to Employee Share-Based Payment Accounting718
The Board is issuing this Update as part of its initiative to reduce complexity in accounting standards. The areas for simplification in this Update involve several aspects of the accounting for employee share-based payment transactions, including the income tax consequences, classification of awards as either equity or liabilities, and classification on the statement of cash flows. Some of the areas for simplification apply only to nonpublic entities. In addition, the amendments in this Update eliminate the guidance in Topic 718 that was indefinitely deferred shortly after the issuance of FASB Statement No. 123 (revised 2004), Share-Based Payment.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update—Compensation—Stock Compensation (Topic 718): Improvements to Employee Share-Based Payment Accounting, which has been deleted.
For more information, see the following:
Issued: March 30, 2016
2016-10Accounting Standards Update No. 2016-10—Revenue from Contracts with Customers (Topic 606): Identifying Performance Obligations and Licensing606
This update releases Accounting Standards Update No. 2016-10—Revenue from Contracts with Customers (Topic 606): Identifying Performance Obligations and Licensing. This Update clarifies guidance related to identifying performance obligations and licensing implementation guidance contained in the new revenue recognition standard.
The Update includes targeted improvements based on input the Board received from the Transition Resource Group for Revenue Recognition and other stakeholders. The Update seeks to proactively address areas in which diversity in practice potentially could arise, as well as to reduce the cost and complexity of applying certain aspects of the guidance both at implementation and on an ongoing basis.
For more information, see the following:
Issued: April 14, 2016
2016-11Accounting Standards Update No. 2016-11—Revenue Recognition (Topic 605) and Derivatives and Hedging (Topic 815): Rescission of SEC Guidance Because of Accounting Standards Updates 2014-09 and 2014-16 Pursuant to Staff Announcements at the March 3, 2016 EITF Meeting605815
This Accounting Standards Update rescinds SEC paragraphs pursuant to the SEC Staff Announcement, “Rescission of Certain SEC Staff Observer Comments upon Adoption of Topic 606,” and the SEC Staff Announcement, “Determining Whether the Host Contract in a Hybrid Financial Instrument Issued in the Form of a Share Is More Akin to Debt or Equity,” announced at the March 3, 2016 Emerging Issues Task Force (EITF) meeting.
For more information, see the following:
Issued: May 2, 2016
2016-12Accounting Standards Update No. 2016-12—Revenue from Contracts with Customers (Topic 606): Narrow-Scope Improvements and Practical Expedients606
The amendments in this Update address narrow-scope improvements to the guidance on collectibility, noncash consideration, and completed contracts at transition. Additionally, the amendments in this Update provide a practical expedient for contract modifications at transition and an accounting policy election related to the presentation of sales taxes and other similar taxes collected from customers.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2015-320—Revenue from Contracts with Customers (Topic 606)—Narrow-Scope Improvements and Practical Expedients, which has been deleted.
For more information, see the following:
Issued: May 09, 2016
2016-13Accounting Standards Update No. 2016-13—Financial Instruments—Credit Losses (Topic 326): Measurement of Credit Losses on Financial Instruments326
Topic 326 amends guidance on reporting credit losses for assets held at amortized cost basis and available for sale debt securities.
For assets held at amortized cost basis, Topic 326 eliminates the probable initial recognition threshold in current GAAP and, instead, requires an entity to reflect its current estimate of all expected credit losses. The allowance for credit losses is a valuation account that is deducted from the amortized cost basis of the financial assets to present the net amount expected to be collected.
For available for sale debt securities, credit losses should be measured in a manner similar to current GAAP, however Topic 326 will require that credit losses be presented as an allowance rather than as a write-down.
This Accounting Standards Update affects entities holding financial assets and net investment in leases that are not accounted for at fair value through net income. The amendments affect loans, debt securities, trade receivables, net investments in leases, off balance sheet credit exposures, reinsurance receivables, and any other financial assets not excluded from the scope that have the contractual right to receive cash.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2012-260—Financial Instruments—Credit Losses (Subtopic 825-15), which has been deleted.
For more information, see the following:
Issued: June 16, 2016
2016-14Accounting Standards Update No. 2016-14—Not-for-Profit Entities (Topic 958): Presentation of Financial Statements of Not-for-Profit Entities958
The amendments in this Accounting Standards Update make improvements to the information provided in financial statements and accompanying notes of not-for-profit entities. The amendments set forth the FASB's improvements to net asset classification requirements and the information presented about a not-for-profit entity's liquidity, financial performance, and cash flows.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2015-230—Not-for-Profit Entities (Topic 958) and Health Care Entities (Topic 954), which has been deleted.
For more information, see the following:
Issued: August 18, 2016
2016-15Accounting Standards Update No. 2016-15—Statement of Cash Flows (Topic 230): Classification of Certain Cash Receipts and Cash Payments230
Stakeholders indicated that there is diversity in practice in how certain cash receipts and cash payments are presented and classified in the statement of cash flows under Topic 230, Statement of Cash Flows, and other Topics.
This Accounting Standards Update addresses the following eight specific cash flow issues: Debt prepayment or debt extinguishment costs; settlement of zero-coupon debt instruments or other debt instruments with coupon interest rates that are insignificant in relation to the effective interest rate of the borrowing; contingent consideration payments made after a business combination; proceeds from the settlement of insurance claims; proceeds from the settlement of corporate-owned life insurance policies (COLIs) (including bank-owned life insurance policies (BOLIs)); distributions received from equity method investees; beneficial interests in securitization transactions; and separately identifiable cash flows and application of the predominance principle.
The amendments in this Update apply to all entities, including both business entities and not-for-profit entities that are required to present a statement of cash flows under Topic 230.
This Update is the final version of Proposed Accounting Standards Update EITF-15F—Statement of Cash Flows—Classification of Certain Cash Receipts and Cash Payments (Topic 230), which has been deleted.
Issued: August 26, 2016
2016-16Accounting Standards Update No. 2016-16—Income Taxes (Topic 740): Intra-Entity Transfers of Assets Other Than Inventory740
Topic 740, Income Taxes, prohibits the recognition of current and deferred income taxes for an intra-entity asset transfer until the asset has been sold to an outside party. In addition, interpretations of this guidance have developed in practice for transfers of certain intangible and tangible assets. This prohibition on recognition is an exception to the principle of comprehensive recognition of current and deferred income taxes in GAAP.
To more faithfully represent the economics of intra-entity asset transfers, the amendments in this Update require that entities recognize the income tax consequences of an intra-entity transfer of an asset other than inventory when the transfer occurs. The amendments in this Update do not change GAAP for the pre-tax effects of an intra-entity asset transfer under Topic 810, Consolidation, or for an intra-entity transfer of inventory.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2015-200—Income Taxes (Topic 740), which has been deleted.
Issued: October 24, 2016
2016-17Accounting Standards Update No. 2016-17—Consolidation (Topic 810): Interests Held through Related Parties That Are under Common Control810
The Board is issuing this Accounting Standards Update to amend the consolidation guidance on how a reporting entity that is the single decision maker of a variable interest entity (VIE) should treat indirect interests in the entity held through related parties that are under common control with the reporting entity when determining whether it is the primary beneficiary of that VIE. Under the amendments, a single decision maker is not required to consider indirect interests held through related parties that are under common control with the single decision maker to be the equivalent of direct interests in their entirety. Instead, a single decision maker is required to include those interests on a proportionate basis consistent with indirect interests held through other related parties.
This Update is the final version of Proposed Accounting Standards Update 2016-260—Consolidation (Topic 810)—Interests Held through Related Parties That Are under Common Control, which has been deleted.
Issued: October 26, 2016
2016-18Accounting Standards Update No. 2016-18—Statement of Cash Flows (Topic 230): Restricted Cash230
Stakeholders indicated that diversity exists in the classification and presentation of changes in restricted cash on the statement of cash flows under Topic 230, Statement of Cash Flows. This Update addresses that diversity.
The amendments in this Update require that a statement of cash flows explain the change during the period in the total of cash, cash equivalents, and amounts generally described as restricted cash or restricted cash equivalents. Therefore, amounts generally described as restricted cash and restricted cash equivalents should be included with cash and cash equivalents when reconciling the beginning-of-period and end-of-period total amounts shown on the statement of cash flows. The amendments in this Update apply to all entities that have restricted cash or restricted cash equivalents and are required to present a statement of cash flows under Topic 230.
This Update is the final version of Proposed Accounting Standards Update EITF-16A—Statement of Cash Flows (Topic 230), which has been deleted.
Issued: November 17, 2016
2016-19Accounting Standards Update No. 2016-19—Technical Corrections and Improvements
The amendments in this Update cover a wide range of Topics in the Codification. The amendments in this Update represent changes to make corrections or improvements to the Codification that are not expected to have a significant effect on current accounting practice or create a significant administrative cost to most entities.
This Update is the final version of Proposed Accounting Standards Update 2016-220—Technical Corrections and Improvements, which has been deleted.
Issued: December 14, 2016
2016-20Accounting Standards Update No. 2016-20—Technical Corrections and Improvements to Topic 606, Revenue from Contracts with Customers606
The amendments in this Update cover a variety of Topics in the Codification related to the new revenue recognition standard (Accounting Standards Update No. 2014-09). The amendments in this Update represent changes to make minor corrections or minor improvements to the Codification that are not expected to have a significant effect on current accounting practice or create a significant administrative cost to most entities.
This Update is the final, combined version of Proposed Accounting Standards Updates 2016-240 and 2016-320 (both entitled Technical Corrections and Improvements), which have been deleted.
Issued: December 21, 2016
2015
2015-01Accounting Standards Update No. 2015-01—Income Statement—Extraordinary and Unusual Items (Subtopic 225-20)225
The objective of this Update is to simplify the income statement presentation requirements in Subtopic 225-20 by eliminating the concept of extraordinary items. Extraordinary items are events and transactions that are distinguished by their unusual nature and by the infrequency of their occurrence. Eliminating the extraordinary classification simplifies income statement presentation by altogether removing the concept of extraordinary items from consideration.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2014-220—Income Statement—Extraordinary Items (Subtopic 225-20), which has been deleted.
Issued: January 9, 2015
2015-02Accounting Standards Update No. 2015-02—Consolidation (Topic 810)810
The amendments in this Update affect reporting entities that are required to evaluate whether they should consolidate certain legal entities. All legal entities are subject to reevaluation under the revised consolidation model. Specifically, the amendments:
- 1Modify the evaluation of whether limited partnerships and similar legal entities are variable interest entities (VIEs) or voting interest entities
- 2Eliminate the presumption that a general partner should consolidate a limited partnership
- 3Affect the consolidation analysis of reporting entities that are involved with VIEs, particularly those that have fee arrangements and related party relationships
- 4Provide a scope exception from consolidation guidance for reporting entities with interests in legal entities that are required to comply with or operate in accordance with requirements that are similar to those in Rule 2a-7 of the Investment Company Act of 1940 for registered money market funds.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2011-220—Consolidation (Topic 810), which has been deleted.
Issued: February 18, 2015
2015-03Accounting Standards Update No. 2015-03—Interest—Imputation of Interest (Subtopic 835-30)835
To simplify presentation of debt issuance costs, the amendments in this Update would require that debt issuance costs be presented in the balance sheet as a direct deduction from the carrying amount of debt liability, consistent with debt discounts or premiums. The recognition and measurement guidance for debt issuance costs would not be affected by the amendments in this Update.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2014-250—Interest—Imputation of Interest (Subtopic 835-30), which has been deleted.
Issued: April 7, 2015
2015-04Accounting Standards Update No. 2015-04—Compensation—Retirement Benefits (Topic 715)715
The amendments in this Update would provide a practical expedient for employers with fiscal year-ends that do not fall on a month-end by permitting those employers to measure defined benefit plan assets and obligations as of the month-end that is closest to the entity's fiscal year-end.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2014-260—Compensation—Retirement Benefits (Topic 715), which has been deleted.
Issued: April 15, 2015
2015-05Accounting Standards Update No. 2015-05—Intangibles—Goodwill and Other—Internal-Use Software (Subtopic 350-40)350
The objective of the amendments in this Update is to address the concerns of stakeholders that the lack of guidance about a customer's accounting for fees in a cloud computing arrangement leads to unnecessary cost and complexity when evaluating the accounting for those fees, as well as some diversity in practice. The amendments in this Update will help entities evaluate the accounting for fees paid by a customer in a cloud computing arrangement by providing guidance as to whether an arrangement includes the sale or license of software.
The amendments in this Update will help entities evaluate the accounting for fees paid by a customer in a cloud computing arrangement by providing guidance as to whether an arrangement includes the sale or license of software.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2014-230—Intangibles—Goodwill and Other—Internal-Use Software (Subtopic 350-40), which has been deleted.
Issued: April 15, 2015
2015-06Accounting Standards Update No. 2015-06—Earnings Per Share (Topic 260)260
Under Topic 260, Earnings Per Share, master limited partnerships (MLPs) apply the two-class method to calculate earnings per unit (EPU) because the general partner, limited partners, and incentive distribution rights holders each participate differently in the distribution of available cash. When a general partner transfers (or “drops down”) net assets to a master limited partnership and that transaction is accounted for as a transaction between entities under common control, the statements of operations of the master limited partnership are adjusted retrospectively to reflect the dropdown transaction as if it occurred on the earliest date during which the entities were under common control.
The amendments in this Update specify that for purposes of calculating historical EPU under the two-class method, the earnings (losses) of a transferred business before the date of a dropdown transaction should be allocated entirely to the general partner interest, and previously reported EPU of the limited partners would not change as a result of a dropdown transaction. Qualitative disclosures about how the rights to the earnings (losses) differ before and after the dropdown transaction occurs also are required.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update EITF-14A—Earnings Per Share—Effects on Historical Earnings per Unit of Master Limited Partnership Dropdown Transactions (Topic 260), which has been deleted.
Issued: April 30, 2015
2015-07Accounting Standards Update No. 2015-07—Fair Value Measurement (Topic 820)820
Topic 820, Fair Value Measurement, permits a reporting entity, as a practical expedient, to measure the fair value of certain investments using the net asset value per share of the investment. Currently, investments valued using the practical expedient are categorized within the fair value hierarchy on the basis of whether the investment is redeemable with the investee at net asset value on the measurement date, never redeemable with the investee at net asset value, or redeemable with the investee at net asset value at a future date.
To address the diversity in practice related to how certain investments measured at net asset value with future redemption dates are categorized, the amendments in this Update remove the requirement to categorize investments for which fair values are measured using the net asset value per share practical expedient. It also limits disclosures to investments for which the entity has elected to measure the fair value using the practical expedient.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update EITF-14B—Fair Value Measurement—Disclosures for Investments in Certain Entities that Calculate Net Asset Value per Share (or Its Equivalent) (Topic 820), which has been deleted.
Issued: May 1, 2015
2015-08Accounting Standards Update No. 2015-08—Business Combinations (Topic 805)805
This Accounting Standards Update amends various SEC paragraphs pursuant to the issuance of Staff Accounting Bulletin No. 115.
Issued: May 8, 2015
2015-09Accounting Standards Update No. 2015-09—Financial Services—Insurance (Topic 944)944
The objectives of the amendments in this Update are to increase transparency of significant estimates made in measuring the liability for unpaid claims and claim adjustment expenses, improve comparability through consistently disclosed information, and provide financial statements users with information to facilitate analysis of the amount, timing, and uncertainty of cash flows arising from contracts issued by insurance entities and the development of loss reserve estimates.
Issued: May 21, 2015
2015-10Accounting Standards Update No. 2015-10—Technical Corrections and Improvements
The amendments in this Update cover a wide range of Topics in the Codification. The amendments in this Update represent changes to make minor corrections or minor improvements to the Codification that are not expected to have a significant effect on current accounting practice or create a significant administrative cost to most entities.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2014-240—Technical Corrections and Improvements, which has been deleted.
Issued: June 12, 2015
2015-11Accounting Standards Update No. 2015-11—Inventory (Topic 330)330
Topic 330, Inventory, currently requires an entity to measure inventory at the lower of cost or market. Market could be replacement cost, net realizable value, or net realizable value less an approximately normal profit margin.
The amendments in this Update require an entity to measure inventory within the scope of this Update at the lower of cost and net realizable value. Subsequent measurement is unchanged for inventory measured using last-in, first-out (LIFO) or the retail inventory method.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2014-210—Inventory (Topic 330), which has been deleted.
Issued: July 22, 2015
2015-12Accounting Standards Update No. 2015-12—Plan Accounting: Defined Benefit Pension Plans (Topic 960), Defined Contribution Pension Plans (Topic 962), Health and Welfare Benefit Plans (Topic 965): (Part I) Fully Benefit-Responsive Investment Contracts, (Part II) Plan Investment Disclosures, (Part III) Measurement Date Practical Expedient960962965
This Update reduces complexity in employee benefit plan accounting, which is consistent with the FASB's Simplification initiative.
Part I: Fully Benefit-Responsive Investment Contracts
Topics 962 and 965 on employee benefit plan accounting require fully benefit-responsive investment contracts to be measured at contract value. Those Topics also require an adjustment to reconcile contract value to fair value, when these measures differ, on the face of the plan financial statements.
The amendments in Part I of this Update designate contract value as the only required measure for fully benefit-responsive investment contracts, which maintains the relevant information while reducing the cost and complexity of reporting for fully benefit-responsive investment contracts.
Part II: Plan Investment Disclosures
As new disclosure requirements have been issued or amended, employee benefit plan financial statements have been affected. Specifically, the interaction between Topic 820, Fair Value Measurement, and Topics 960, 962, and 965 on employee benefit plan accounting sometimes requires aggregation, or organization of similar investment information, in multiple ways.
The objective of Part II of this Update is to simplify and make more effective the investment disclosure requirements under Topic 820 and under Topics 960, 962, and 965 for employee benefit plans.
Part III: Measurement Date Practical Expedient
The objective of Part III of this Update is to reduce complexity in employee benefit plan accounting by providing a practical expedient that permits plans to measure investments and investment-related accounts as of a month-end date that is closest to the plan's fiscal year-end, when the fiscal period does not coincide with month-end.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update EITF-15C—Plan Accounting: Defined Benefit Pension Plans (Topic 960), Defined Contribution Pension Plans (Topic 962), Health and Welfare Benefit Plans (Topic 965), which has been deleted.
Issued: July 31, 2015
2015-13Accounting Standards Update No. 2015-13—Derivatives and Hedging (Topic 815)815
Topic 815, Derivatives and Hedging, requires that a derivative contract be recognized at fair value unless the contract qualifies for a scope exception. The amendments in this Update clarify that the use of locational marginal pricing by an independent system operator to determine the transmission charge (or credit) does not constitute net settlement of a contract for the purchase or sale of electricity on a forward basis that necessitates transmission through, or delivery to a location within, a nodal energy market.
The amendments in this Update clarify that the use of locational marginal pricing by an independent system operator to determine the transmission charge (or credit) does not constitute net settlement of a contract for the purchase or sale of electricity on a forward basis that necessitates transmission through, or delivery to a location within, a nodal energy market. Consequently, the use of locational marginal pricing by the independent system operator does not cause that contract to fail to meet the physical delivery criterion of the normal purchases and normal sales scope exception.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update EITF-15A—Derivatives and Hedging—Application of the Normal Purchases and Normal Sales Scope Exception to Certain Electricity Contracts within Nodal Energy Markets (Topic 815), which has been deleted.
For more information, see the following:
Issued: August 10, 2015
2015-14Accounting Standards Update No. 2015-14—Revenue From Contracts With Customers (Topic 606)606
On May 28, 2014, the FASB issued Accounting Standards Update No. 2014-09, Revenue from Contracts with Customers (Topic 606), with an effective date for annual reporting periods beginning after December 15, 2016, including interim periods within that reporting period, for public business entities, certain not-for-profit entities, and certain employee benefit plans. The effective date for all other entities was for annual reporting periods beginning after December 15, 2017, and interim periods within annual periods beginning after December 15, 2018.
The amendments in this Update defer the effective date of Update 2014-09. Public business entities, certain not-for-profit entities, and certain employee benefit plans should apply the guidance in Update 2014-09 to annual reporting periods beginning after December 15, 2017, including interim reporting periods within that reporting period. Earlier application is permitted only as of annual reporting periods beginning after December 15, 2016, including interim reporting periods within that reporting period.
All other entities should apply the guidance in Update 2014-09 to annual reporting periods beginning after December 15, 2018, and interim reporting periods within annual reporting periods beginning after December 15, 2019. Earlier application is permitted only as of an annual reporting period beginning after December 15, 2016, including interim reporting periods within that reporting period, or an annual reporting period beginning after December 15, 2016, and interim reporting periods within annual reporting periods beginning one year after the annual reporting period in which an entity first applies the guidance in Update 2014-09.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2015-240—Revenue From Contracts With Customers (Topic 606), which has been deleted.
For more information, see the following:
Issued: August 12, 2015
2015-15Accounting Standards Update No. 2015-15—Imputation of Interest (Subtopic 835-30)835
This Accounting Standards Update adds SEC paragraphs pursuant to the SEC Staff Announcement at the June 18, 2015 Emerging Issues Task Force (EITF) meeting about the presentation and subsequent measurement of debt issuance costs associated with line-of-credit arrangements.
For more information, see the following:
Issued: August 18, 2015
2015-16Accounting Standards Update No. 2015-16—Business Combinations (Topic 805)805
Topic 805 requires that an acquirer retrospectively adjust provisional amounts recognized in a business combination, during the measurement period. To simplify the accounting for adjustments made to provisional amounts, the amendments in the Update require that the acquirer recognize adjustments to provisional amounts that are identified during the measurement period in the reporting period in which the adjustment amount is determined. The acquirer is required to also record, in the same period's financial statements, the effect on earnings of changes in depreciation, amortization, or other income effects, if any, as a result of the change to the provisional amounts, calculated as if the accounting had been completed at the acquisition date. In addition an entity is required to present separately on the face of the income statement or disclose in the notes to the financial statements the portion of the amount recorded in current-period earnings by line item that would have been recorded in previous reporting periods if the adjustment to the provisional amounts had been recognized as of the acquisition date.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2015-260—Business Combinations (Topic 805), which has been deleted.
For more information, see the following:
Issued: September 25, 2015
2015-17Accounting Standards Update No. 2015-17—Income Taxes (Topic 740)740
Topic 740, Income Taxes, requires an entity to separate deferred income tax liabilities and assets into current and noncurrent amounts in a classified statement of financial position. Deferred tax liabilities and assets are classified as current or noncurrent based on the classification of the related asset or liability for financial reporting. Deferred tax liabilities and assets that are not related to an asset or liability for financial reporting are classified according to the expected reversal date of the temporary difference.
To simplify the presentation of deferred income taxes, the amendments in this Update require that deferred income tax liabilities and assets be classified as noncurrent in a classified statement of financial position.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2015-210—Income Taxes (Topic 740).
For more information, see the following:
Issued: November 20, 2015
2014
2014-01Accounting Standards Update No. 2014-01—Investments (Topic 323)323
The amendments in this Update provide guidance on accounting for investments by a reporting entity in flow-through limited liability entities that manage or invest in affordable housing projects that qualify for the low-income housing tax credit. The amendments permit reporting entities to make an accounting policy election to account for their investments in qualified affordable housing projects using the proportional amortization method if certain conditions are met.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update EITF-13B—Investments—Equity Method and Joint Ventures (Topic 323), which has been deleted.
Issued: January 15, 2014
2014-02Accounting Standards Update No. 2014-02—Intangibles—Goodwill and Other (Topic 350)350
The objective of this Update is to address the concerns of private company stakeholders that the benefits of the current accounting for goodwill do not justify the related costs. The amendments in this Update provide guidance about an accounting alternative for the subsequent measurement of goodwill.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update PCC-13-01B—Intangibles—Goodwill and Other (Topic 350), which has been deleted.
Issued: January 16, 2014
2014-03Accounting Standards Update No. 2014-03—Derivatives and Hedging (Topic 815)815
The objective of the amendments in this Update is to address the concerns of private company stakeholders by providing an additional hedge accounting alternative within Topic 815 for certain types of swaps that are entered into by a private company for the purpose of economically converting variable-rate interest payments into fixed-rate payments. This additional hedge accounting alternative, the simplified hedge accounting approach, acts as a practical expedient to qualify for cash flow hedge accounting under Topic 815 if certain conditions are met.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update PCC-13-03—Derivatives and Hedging (Topic 815), which has been deleted.
Issued: January 16, 2014
2014-04Accounting Standards Update No. 2014-04—Receivables—Troubled Debt Restructurings by Creditors (Subtopic 310-40)310
The amendments in this Update clarifying when an in substance repossession or foreclosure occurs, that is, when a creditor should be considered to have received physical possession of residential real estate property collateralizing a consumer mortgage loan such that the loan receivable should be derecognized and the real estate property recognized.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update EITF-13E—Receivables—Troubled Debt Restructurings by Creditors (Subtopic 310-40), which has been deleted.
Issued: January 17, 2014
2014-05Accounting Standards Update No. 2014-05—Service Concession Arrangements (Topic 853)853
The amendments in this Update provide guidance on accounting for service concession arrangements. A service concession arrangement is an arrangement between a public-sector entity grantor and an operating entity under which the operating entity operates the grantor's infrastructure (for example, airports, roads, and bridges).
The amendments in this Update specify that an operating entity should not account for a service concession arrangement within the scope of this Update as a lease in accordance with Topic 840, Leases. The amendments also specify that the infrastructure used in a service concession arrangement should not be recognized as property, plant, and equipment of the operating entity. The amendments apply to an operating entity of a service concession arrangement entered into with a public-sector entity grantor when the grantor controls the services that the operating entity must provide with the infrastructure, and through ownership, any residual interest in the infrastructure at the end of the term of the arrangement.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update EITF-12H—Service Concession Arrangements (Topic 853), which has been deleted.
Issued: January 23, 2014
2014-06Accounting Standards Update No. 2014-06—Technical Corrections and Improvements Related to Glossary Terms
The amendments in this Update relate to glossary terms and cover a wide range of Topics in the Codification. The amendments in this Update represent changes to clarify the Master Glossary of the Codification, consolidate multiple instances of the same term into a single definition, or make minor improvements to the Master Glossary that are not expected to have a significant effect on current accounting practice or create a significant administrative cost to most entities. Additionally, the amendments will make the Master Glossary easier to understand, as well as reduce the number of terms appearing in the Master Glossary.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2013-240—Technical Corrections and Improvements Related to Glossary Terms, which has been deleted.
Issued: March 14, 2014
2014-07Accounting Standards Update No. 2014-07—Consolidation (Topic 810)810
The amendments in this Update permit a private company lessee (the reporting entity) to elect an alternative not to apply VIE guidance to a lessor entity under common control when certain conditions are met.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update PCC-13-02—Consolidation (Topic 810), which has been deleted.
Issued: March 20, 2014
2014-08Accounting Standards Update No. 2014-08—Presentation of Financial Statements (Topic 205) and Property, Plant, and Equipment (Topic 360)205360
The amendments in this Update change the criteria for reporting discontinued operations for all public and nonpublic entities. The amendments also require new disclosures about discontinued operations and disposals of components of an entity that do not qualify for discontinued operations reporting.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2013-230—Presentation of Financial Statements (Topic 205), which has been deleted.
Issued: April 10, 2014
2014-09Accounting Standards Update No. 2014-09—Revenue from Contracts with Customers (Topic 606)606
The amendments in this Update create Topic 606, Revenue from Contracts with Customers, and supersede the revenue recognition requirements in Topic 605, Revenue Recognition, including most industry-specific revenue recognition guidance throughout the Industry Topics of the Codification. In addition, the amendments supersede the cost guidance in Subtopic 605-35, Revenue Recognition—Construction-Type and Production-Type Contracts, and create new Subtopic 340-40, Other Assets and Deferred Costs—Contracts with Customers. In summary, the core principle of Topic 606 is that an entity recognizes revenue to depict the transfer of promised goods or services to customers in an amount that reflects the consideration to which the entity expects to be entitled in exchange for those goods or services.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2011-230—Revenue Recognition (Topic 605) and Proposed Accounting Standards Update 2011-250—Revenue Recognition (Topic 605): Codification Amendments, both of which have been deleted.
Accounting Standards Update 2014-09
Section A (PDF)—Summary and Amendments That Create Revenue from Contracts with Customers (Topic 606) and Other Assets and Deferred Costs—Contracts with Customers (Subtopic 340-40)
Section B (PDF)—Conforming Amendments to Other Topics and Subtopics in the Codification and Status Tables
Section C (PDF)—Background Information and Basis for Conclusions
Issued: May 28, 2014
2014-10Accounting Standards Update No. 2014-10—Development Stage Entities (Topic 915)915
The amendments in this Update remove the definition of a development stage entity from Topic 915, thereby removing the distinction between development stage entities and other reporting entities from U.S. GAAP. In addition, the amendments eliminate the requirements for development stage entities to (1) present inception-to-date information on the statements of income, cash flows, and shareholder's equity, (2) label the financial statements as those of a development stage entity, (3) disclose a description of the development stage activities in which the entity is engaged, and (4) disclose in the first year in which the entity is no longer a development stage entity that in prior years it had been in the development stage.
The amendments also clarify that the guidance in Topic 275, Risks and Uncertainties, is applicable to entities that have not commenced planned principal operations. An illustration has been added to Topic 275 to illustrate how an entity that has not commenced planned principal operations may comply with the disclosure required by paragraph 275-10-50-2.
Finally, the amendments also remove paragraph 810-10-15-16. Paragraph 810-10-15-16 states that a development stage entity does not meet the condition in paragraph 810-10-15-14(a) to be a variable interest entity (VIE) if (1) the entity can demonstrate that the equity invested in the legal entity is sufficient to permit it to finance the activities it is currently engaged in and (2) the entity's governing documents and contractual arrangements allow additional equity investments. Under the amendments, all entities within the scope of the Variable Interest Entities Subsections of Subtopic 810-10, Consolidation—Overall, would be required to evaluate whether the total equity investment at risk is sufficient using the guidance provided in paragraphs 810-10-25-45 through 25-47, which requires both qualitative and quantitative evaluations.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2013-320—Development Stage Entities (Topic 915), which has been deleted.
Issued: June 10, 2014
2014-11Accounting Standards Update No. 2014-11—Transfers and Servicing (Topic 860)860
The amendments in this Update require that repurchase-to-maturity transactions be accounted for as secured borrowings consistent with the accounting for other repurchase agreements. In addition, the amendments require separate accounting for a transfer of a financial asset executed contemporaneously with a repurchase agreement with the same counterparty (a repurchase financing), which will result in secured borrowing accounting for the repurchase agreement. The amendments require an entity to disclose information about transfers accounted for as sales in transactions that are economically similar to repurchase agreements, in which the transferor retains substantially all of the exposure to the economic return on the transferred financial asset throughout the term of the transaction. In addition the amendments require disclosure of the types of collateral pledged in repurchase agreements, securities lending transactions, and repurchase-to-maturity transactions and the tenor of those transactions.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2013-210—Transfers and Servicing (Topic 860), which has been deleted.
Issued: June 12, 2014
2014-12Accounting Standards Update No. 2014-12—Compensation—Stock Compensation (Topic 718)718
Some share-based payment awards that require a specific performance target to be achieved before the employee can benefit from the award, also require an employee to render service until the performance target is achieved. In some cases, the terms of an award may provide that the performance target could be achieved after an employee completes the requisite service period. That is, the employee would be entitled to benefit from the award regardless of whether the employee is rendering service on the date the performance target is achieved. Some entities account for those performance targets as performance conditions that affect the vesting of the award and, therefore, do not reflect the performance target in the estimate of the grant-date fair value. Others treat them as nonvesting conditions that affect the grant-date fair value of the award.
The amendments apply to reporting entities that grant their employees share-based payments in which the terms of the award provide that a performance target can be achieved after the requisite service period.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update EITF-13D—Compensation—Stock Compensation (Topic 718): Accounting for Share-Based Payments When the Terms of an Award Provide That a Performance Target Could Be Achieved after the Requisite Service Period, which has been deleted.
Issued: June 19, 2014
2014-13Accounting Standards Update No. 2014-13—Consolidation (Topic 810)810
Topic 810 requires a reporting entity to consolidate a collateralized financing entity if it is the primary beneficiary of that collateralized financing entity. A collateralized financing entity is a variable interest entity that holds financial assets and issues beneficial interests in those financial assets. The beneficial interests have recourse only to the related financial assets of the collateralized financing entity and are classified as financial liabilities. Upon initial consolidation, many elect or are required to account for the financial assets and financial liabilities of the consolidated collateralized financing entity at fair value. The fair value of a collateralized financing entity's financial assets may differ from the fair value of its financial liabilities even though the financial liabilities have recourse only to the financial assets. Diversity in practice has developed in the accounting for that measurement difference in both initial consolidation and subsequent measurement of the fair values of the assets and the liabilities of a collateralized financing entity. This Update addresses that measurement difference.
The amendments would apply to reporting entities that are required to consolidate a collateralized financing entity under the Variable Interest Entity Subsections of Subtopic 810-10.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update EITF-12R—Consolidation—Measuring the Financial Liabilities of a Consolidated Collateralized Financing Entity (Topic 810), which has been deleted.
Issued: August 5, 2014
2014-14Accounting Standards Update No. 2014-14—Receivables—Troubled Debt Restructuring by Creditors (Subtopic 310-40)310
Under certain government-sponsored loan guarantee programs, such as those offered by the Federal Housing Administration (FHA) and the Department of Veterans Affairs (VA), qualifying creditors can extend mortgage loans to borrowers with a guarantee that entitles the creditor to recover all or a portion of the unpaid principal balance from the government if the borrower defaults.
The objective of this Update is to reduce diversity in practice by addressing the classification of foreclosed mortgage loans that are fully or partially guaranteed under government programs. Currently, some creditors reclassify those loans to real estate as with other foreclosed loans that do not have guarantees; others reclassify the loans to other receivables.
The amendments affect creditors that hold government-guaranteed mortgage loans, including those guaranteed by the FHA and the VA.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update EITF-13F—Receivables—Troubled Debt Restructurings by Creditors (Subtopic 310-40): Classification of Certain Government-Guaranteed Residential Mortgage Loans upon Foreclosure, which has been deleted.
Issued: August 8, 2014
2014-15Accounting Standards Update No. 2014-15—Presentation of Financial Statements—Going Concern (Subtopic 205-40)205
The Update provides U.S. GAAP guidance on management's responsibility in evaluating whether there is substantial doubt about a company's ability to continue as a going concern and about related footnote disclosures. For each reporting period, management will be required to evaluate whether there are conditions or events that raise substantial doubt about a company's ability to continue as a going concern within one year from the date the financial statements are issued.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2013-300—Presentation of Financial Statements (Topic 205): Disclosure of Uncertainties about an Entity's Going Concern Presumption, which has been deleted.
Issued: August 27, 2014
2014-16Accounting Standards Update No. 2014-16—Derivatives and Hedging (Topic 815)815
Certain classes of shares include features that entitle the holders to preferences and rights (such as conversion rights, redemption rights, voting powers, and liquidation and dividend payment preferences) over the other shareholders. Shares that include embedded derivative features are referred to as hybrid financial instruments, which must be separated from the host contract and accounted for as a derivative if certain criteria are met under Subtopic 815-10.
One criterion requires evaluating whether the nature of the host contract is more akin to debt or to equity and whether the economic characteristics and risks of the embedded derivative feature are “clearly and closely related” to the host contract. In making that evaluation, an issuer or investor may consider all terms and features in a hybrid financial instrument including the embedded derivative feature that is being evaluated for separate accounting or may consider all terms and features in the hybrid financial instrument except for the embedded derivative feature that is being evaluated for separate accounting. The use of different methods can result in different accounting outcomes for economically similar hybrid financial instruments.
Additionally, there is diversity in practice with respect to the consideration of redemption features in relation to other features when determining whether the nature of a host contract is more akin to debt or to equity.
The amendments apply to all reporting entities that are issuers of, or investors in, hybrid financial instruments that are issued in the form of a share.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update EITF-13G—Derivatives and Hedging—Determining Whether the Host Contract in a Hybrid Financial Instrument Issued in the Form of a Share Is More Akin to Debt or to Equity (Topic 815), which has been deleted.
Issued: November 3, 2014
2014-17Accounting Standards Update No. 2014-17—Business Combinations (Topic 805)805
The objective of this Update is to provide guidance for determining whether and at what threshold an acquiree (acquired entity) that is a business or nonprofit activity can reflect the acquirer's accounting and reporting basis (pushdown accounting) in its separate financial statements.
Paragraphs 805-50-S99-1 through S99-4 of the Codification provide limited guidance for SEC registrants for determining whether and when a new accounting and reporting basis should be established in an acquiree's separate financial statements. However, because diversity in practice exists with respect to the application of pushdown accounting among entities that are not SEC registrants, the amendments provide guidance for entities that are SEC registrants and for those that are not.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update EITF-12F—Business Combinations—Pushdown Accounting (Topic 805), which has been deleted.
Issued: November 18, 2014
2014-18Accounting Standards Update No. 2014-18—Business Combinations (Topic 805)805
The objective of the amendments in this Update is to address the concerns of private company stakeholders that the benefits of the current accounting for identifiable intangible assets acquired in a business combination do not justify the related costs. The amendments provide guidance about an accounting alternative for recognizing or otherwise considering the fair value of identifiable intangible assets acquired as a result of certain specified transactions, including business combinations.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update PCC-13-01A—Business Combinations (Topic 805), which has been deleted.
Issued: December 23, 2014
2013
2013-01Accounting Standards Update No. 2013-01—Balance Sheet (Topic 210)210
The objective of this Update is to clarify that the scope of Accounting Standards Update No. 2011-11, Disclosures about Offsetting Assets and Liabilities, would apply to derivatives including bifurcated embedded derivatives, repurchase agreements and reverse repurchase agreements, and securities borrowing and securities lending transactions that are either offset in accordance with Section 210-20-45 or Section 815-10-45 or are subject to a master netting arrangement or similar agreement.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2012-250—Balance Sheet (Topic 210) which has been deleted.
Issued: January 31, 2013
2013-02Accounting Standards Update No. 2013-02—Other Comprehensive Income (Topic 220)220
The amendments in this Update supersede and replace the presentation requirements for reclassifications out of accumulated other comprehensive income in ASUs 2011-05 (issued in June 2011) and 2011-12 (issued in December 2011) for all public and private organizations. The amendments would require an entity to provide additional information about reclassifications out of accumulated other comprehensive income.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2012-240—Comprehensive Income (Topic 220) which has been deleted.
Issued: February 5, 2013
2013-03Accounting Standards Update No. 2013-03—Financial Instruments (Topic 825)825
The amendment in the Update clarifies the scope and applicability of a disclosure exemption that resulted from the issuance of Accounting Standards Update No. 2011-04, Fair Value Measurement (Topic 820): Amendments to Achieve Common Fair Value Measurement and Disclosure Requirements in U.S. GAAP and IFRSs. The amendment clarifies that the requirement to disclose "the level of the fair value hierarchy within which the fair value measurements are categorized in their entirety (Level 1, 2, or 3)" does not apply to nonpublic entities for items that are not measured at fair value in the statement of financial position, but for which fair value is disclosed.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2013-200—Financial Instruments (Topic 825) which has been deleted.
Issued: February 7, 2013
2013-04Accounting Standards Update No. 2013-04—Liabilities (Topic 405)405
The amendments in this Update provide guidance for the recognition, measurement, and disclosure of obligations resulting from joint and several liability arrangements for which the total amount of the obligation within the scope of this Update is fixed at the reporting date, except for obligations addressed within existing guidance in U.S. GAAP. The guidance requires an entity to measure those obligations as the sum of the amount the reporting entity agreed to pay on the basis of its arrangement among its co-obligors and any additional amount the reporting entity expects to pay on behalf of its co-obligors. The guidance in this Update also requires an entity to disclose the nature and amount of the obligation as well as other information about those obligations.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update EITF12D—Liabilities (Topic 405) which has been deleted.
Issued: February 28, 2013
2013-05Accounting Standards Update No. 2013-05—Foreign Currency Matters (Topic 830)830
The amendments in this Update resolve the diversity in practice about whether Subtopic 810-10, Consolidation—Overall, or Subtopic 830-30, Foreign Currency Matters—Translation of Financial Statements, applies to the release of the cumulative translation adjustment into net income when a parent either sells a part or all of its investment in a foreign entity or no longer holds a controlling financial interest in a subsidiary or group of assets that is a nonprofit activity or a business (other than a sale of in substance real estate or conveyance of oil and gas mineral rights) within a foreign entity. In addition, the amendments in this Update resolve the diversity in practice for the treatment of business combinations achieved in stages (sometimes also referred to as step acquisitions) involving a foreign entity.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update EITF11Ar—Foreign Currency Matters (Topic 830), which has been deleted.
Issued: March 4, 2013
2013-06Accounting Standards Update No. 2013-06—Not-for-Profit Entities (Topic 958)958
The objective of this Update is to address the diversity in practice about what guidance not-for-profit entities should apply for recognizing and measuring personnel services received from an affiliate, that is, a party that directly or indirectly through one or more intermediaries, controls, is controlled by, or is under common control with the recipient not-for-profit entity.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update EITF-12B—Not-for-Profit Entities (Topic 958), which has been deleted.
Issued: April 19, 2013
2013-07Accounting Standards Update No. 2013-07—Presentation of Financial Statements (Topic 205)205
The objective of this Update is to clarify when an entity should apply the liquidation basis of accounting and to provide principles for the measurement of assets and liabilities under the liquidation basis of accounting, as well as any required disclosures.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2012-210—Presentation of Financial Statements (Topic 205), which has been deleted.
Issued: April 22, 2013
2013-08Accounting Standards Update No. 2013-08—Investment Companies (Topic 946)946
The amendments in this Update change the approach to determining whether an entity is an investment company within the scope of Topic 946 and provide comprehensive implementation guidance for that assessment. The amendments also modify measurement and disclosure requirements for investment companies within the scope of Topic 946.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2011-200—Financial Services—Investment Companies (Topic 946), which has been deleted.
Issued: June 7, 2013
2013-09Accounting Standards Update No. 2013-09—Fair Value Measurements (Topic 820)820
The amendments in this Update defer indefinitely the effective date of certain quantitative disclosures contained in FASB Accounting Standards Update No. 2011-04, Fair Value Measurement (Topic 820): Amendments to Achieve Common Fair Value Measurement and Disclosure Requirements in U.S. GAAP and IFRSs, for investments held by a nonpublic employee benefit plan in its plan sponsor's own nonpublic entity equity securities, including equity securities of its plan sponsor's nonpublic affiliated entities. The amendments in this Update do not defer the effective date for those certain quantitative disclosures for other nonpublic entity equity securities held in the nonpublic employee benefit plan or any qualitative disclosures.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2013-260—Fair Value Measurement (Topic 820), which has been deleted.
Issued: July 8, 2013
2013-10Accounting Standards Update No. 2013-10—Derivatives and Hedging (Topic 815)815
The amendments in this Update permit the Fed Funds Effective Swap Rate (also referred to as the Overnight Index Swap Rate) to be used as a U.S. benchmark interest rate for hedge accounting purposes under Topic 815, in addition to interest rates on direct Treasury obligations of the U.S. government and the London Interbank Offered Rate. The amendments also remove the restriction on using different benchmark rates for similar hedges.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update EITF-13A—Derivatives and Hedging (Topic 815), which has been deleted.
Issued: July 17, 2013
2013-11Accounting Standards Update No. 2013-11—Income Taxes (Topic 740)740
The amendments in this Update provide guidance on the financial statement presentation of an unrecognized tax benefit when a net operating loss carryforward, similar tax loss, or tax credit carryforward exists.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update EITF-13C—Income Taxes (Topic 740), which has been deleted.
Issued: July 18, 2013
2013-12Accounting Standards Update No. 2013-12—Definition of a Public Business Entity
The purposes of the Update are to (a) amend the Master Glossary to include one definition of a public business entity for use in U.S. generally accepted accounting principles and (b) identify the types of organizations that would be excluded from the scope of the Private Company Decision-Making Framework: A Guide for Evaluating Financial Accounting and Reporting for Private Companies once it is finalized. This Update will not affect existing requirements.
The definition of a public business entity will be used by the FASB, the Private Company Council, and the Emerging Issues Task Force in specifying the scope of future financial accounting and reporting guidance.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update 2013-310—Definition of a Public Business Entity, which has been deleted.
Issued: December 23, 2013
2012
2012-01Accounting Standards Update No. 2012-01—Health Care Entities (Topic 954)954
The objective of this Update is to clarify the reporting for refundable advance fees received by continuing care retirement communities.
Issued: July 24, 2012
2012-02Accounting Standards Update No. 2012-02—Intangibles—Goodwill and Other (Topic 350)350
The amendments in this Update will allow an entity to first assess qualitative factors to determine whether it is necessary to perform a quantitative impairment test. Under these amendments, an entity would not be required to calculate the fair value of an indefinite-lived intangible asset unless the entity determines, based on qualitative assessment, that it is not more likely than not, the indefinite-lived intangible asset is impaired. The amendments include a number of events and circumstances for an entity to consider in conducting the qualitative assessment.
Issued: July 27, 2012
2012-03Accounting Standards Update No. 2012-03—Technical Amendments and Corrections to SEC Sections
This Accounting Standards Update amends various SEC paragraphs pursuant to SAB 114, SEC Release No. 33-9250, and ASU 2010-22, which amend or rescind portions of certain SAB Topics.
Issued: August 27, 2012
2012-04Accounting Standards Update No. 2012-04—Technical Corrections and Improvements
The amendments in this Update make technical corrections, clarifications, and limited-scope improvements to various Topics throughout the Codification.
Issued: October 1, 2012
2012-05Accounting Standards Update No. 2012-05—Statement of Cash Flows (Topic 230)230
This Update addresses how cash receipts arising from the sale of certain donated financial assets, such as securities, should be classified in the statement of cash flows of not-for-profit entities (NFPs). Some NFPs classify those cash receipts as investing cash inflows, while other entities classify them as either operating cash inflows or financing cash inflows, consistent with their treatment of inflows arising from cash contributions. The objective of this Update is for an NFP to classify cash receipts from the sale of donated financial assets consistently with cash donations received in the statement of cash flows if those cash receipts were from the sale of donated financial assets that upon receipt were directed without the NFP imposing any limitations for sale and were converted nearly immediately into cash.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update EITF-12A—Statement of Cash Flows (Topic 230) which has been deleted.
Issued: October 22, 2012
2012-06Accounting Standards Update No. 2012-06—Business Combinations (Topic 805)805
Accounting for a business combination requires that at each subsequent reporting date, an acquirer measure an indemnification asset on the same basis as the indemnified liability or asset, subject to any contractual limitations on its amount, and for an indemnification asset that is not subsequently measured at its fair value, management's assessment of the collectibility of the indemnification asset. This Update addresses the diversity in practice about how to interpret the terms on the same basis and contractual limitations when subsequently measuring an indemnification asset recognized in a government-assisted (Federal Deposit Insurance Corporation or National Credit Union Administration) acquisition of a financial institution that includes a loss-sharing agreement (indemnification agreement).
This Accounting Standards Update is the final version of Proposed Accounting Standards Update EITF-12C—Business Combinations (Topic 805) which has been deleted.
Issued: October 23, 2012
2012-07Accounting Standards Update No. 2012-07—Entertainment—Films (Topic 926)926
Topic 926, Entertainment—Films, requires that if evidence of a possible need for a write-down of unamortized film costs occurs after the date of the balance sheet but before the financial statements are issued, a rebuttable presumption exists that the conditions leading to the writeoff existed at the balance sheet date. Topic 926 requires that those conditions be incorporated into the fair value measurement used in the impairment test as of the balance sheet date as if they were known with certainty at that date, unless an entity can demonstrate that those conditions did not exist at that date. Questions have arisen about the apparent conflict between the guidance in Topic 926 and the guidance in Topic 820, Fair Value Measurement. Specifically, the fair value guidance in Topic 820 requires calculation of an exit price under current market conditions at the measurement date. That exit price may be calculated under conditions of uncertainty because the cash flows used were estimates rather than known amounts. In contrast, Topic 926 requires that an entity's fair value analysis performed as of a period end date reflect those results that become known after the measurement date to the extent that an entity cannot overcome the rebuttable presumption. This Update aligns the guidance on fair value measurements in the impairment test of unamortized film costs with the guidance on fair value measurements in other instances within U.S. generally accepted accounting principles.
This Accounting Standards Update is the final version of Proposed Accounting Standards Update EITF-12E—Entertainment—Films (Topic 926) which has been deleted.
Issued: October 24, 2012
2011
2011-01Accounting Standards Update No. 2011-01—Receivables (Topic 310)310
The amendments in this Update temporarily delay the effective date of the disclosures about troubled debt restructurings in Accounting Standards Update No. 2010-20, Receivables (Topic 310): Disclosures about the Credit Quality of Financing Receivables and the Allowance for Credit Losses for public entities. The delay is intended to allow the Board time to complete its deliberations on what constitutes a troubled debt restructuring. The effective date of the new disclosures about troubled debt restructurings for public entities and the guidance for determining what constitutes a troubled debt restructuring will then be coordinated.
Issued: January 20, 2011
2011-02Accounting Standards Update No. 2011-02—Receivables (Topic 310)310
The amendments in this Update would provide additional guidance to assist creditors in determining whether a restructuring of a receivable meets the criteria to be considered a troubled debt restructuring.
Issued: April 5, 2011
2011-03Accounting Standards Update No. 2011-03—Transfers and Servicing (Topic 860)860
The amendments in this Update remove from the assessment of effective control (1) the criterion requiring the transferor to have the ability to repurchase or redeem the financial assets on substantially the agreed terms, even in the event of default by the transferee, and (2) the collateral maintenance implementation guidance related to that criterion.
Issued: April 29, 2011
2011-04Accounting Standards Update No. 2011-04—Fair Value Measurement (Topic 820)820
The amendments in this Update generally represent clarifications of Topic 820, but also include some instances where a particular principle or requirement for measuring fair value or disclosing information about fair value measurements has changed. This Update results in common principles and requirements for measuring fair value and for disclosing information about fair value measurements in accordance with U.S. GAAP and IFRSs.
Issued: May 12, 2011
2011-05Accounting Standards Update No. 2011-05—Comprehensive Income (Topic 220)220
Under the amendments to Topic 220, Comprehensive Income, in this Update, an entity has the option to present the total of comprehensive income, the components of net income, and the components of other comprehensive income either in a single continuous statement of comprehensive income or in two separate but consecutive statements. In both choices, an entity is required to present each component of net income along with total net income, each component of other comprehensive income along with a total for other comprehensive income, and a total amount for comprehensive income. This Update eliminates the option to present the components of other comprehensive income as part of the statement of changes in stockholders' equity. The amendments in this Update do not change the items that must be reported in other comprehensive income or when an item of other comprehensive income must be reclassified to net income.
Issued: June 16, 2011
2011-06Accounting Standards Update No. 2011-06—Other Expenses (Topic 720)720
The objective of this Update is to address questions about how health insurers should recognize and classify in their income statements fees mandated by the Patient Protection and Affordable Care Act as amended by the Health Care and Education Reconciliation Act (the Acts). The Acts impose an annual fee on health insurers for each calendar year beginning on or after January 1, 2014. For reporting entities that are subject to the fee imposed on health insurers mandated by the Acts, the amendments in this Update specify that the liability for the fee should be estimated and recorded in full once the entity provides qualifying health insurance in the applicable calendar year in which the fee is payable with a corresponding deferred cost that is amortized to expense using a straight-line method of allocation unless another method better allocates the fee over the calendar year that it is payable.
Issued: July 21, 2011
2011-07Accounting Standards Update No. 2011-07—Health Care Entities (Topic 954)954
The objective of this Update is to provide financial statement users with greater transparency about a health care entity's net patient service revenue, which is sometimes grossed-up and recognized at the time the services are rendered regardless of whether the entity expects to collect that amount, and the related allowance for doubtful accounts. This Update provides information to assist financial statement users in assessing an entity's sources of net patient service revenue and related changes in its allowance for doubtful accounts. The amendments require health care entities that recognize significant amounts of patient service revenue at the time the services are rendered even though they do not assess the patient's ability to pay to present the provision for bad debts related to patient service revenue as a deduction from patient service revenue (net of contractual allowances and discounts) on their statement of operations.
Issued: July 25, 2011
2011-08Accounting Standards Update No. 2011-08—Intangibles—Goodwill and Other (Topic 350)350
The amendments in this Update will allow an entity to first assess qualitative factors to determine whether it is necessary to perform the two-step quantitative goodwill impairment test. Under these amendments, an entity would not be required to calculate the fair value of a reporting unit unless the entity determines, based on a qualitative assessment, that it is more likely than not that its fair value is less than its carrying amount. The amendments include a number of events and circumstances for an entity to consider in conducting the qualitative assessment.
Issued: September 15, 2011
2011-09Accounting Standards Update No. 2011-09—Compensation—Retirement Benefits—Multiemployer Plans (Subtopic 715-80)715
The amendments in this Update require additional disclosures about an employer's participation in a multiemployer plan.
Issued: September 21, 2011
2011-10Accounting Standards Update No. 2011-10—Property, Plant, and Equipment (Topic 360)360
The objective of the amendments in this Update is to resolve the diversity in practice about whether the guidance in Subtopic 360-20, Property, Plant, and Equipment—Real Estate Sales, applies to a parent that ceases to have a controlling financial interest (as described in Subtopic 810-10, Consolidation—Overall) in a subsidiary that is in substance real estate as a result of default on the subsidiary's nonrecourse debt. This Update does not address whether the guidance in Subtopic 360-20 would apply to other circumstances when a parent ceases to have a controlling financial interest in a subsidiary that is in substance real estate.
Issued: December 14, 2011
2011-11Accounting Standards Update No. 2011-11—Balance Sheet (Topic 210)210
The objective of this Update is to provide enhanced disclosures that will enable users of its financial statements to evaluate the effect or potential effect of netting arrangements on an entity's financial position. This includes the effect or potential effect of rights of setoff associated with an entity's recognized assets and recognized liabilities within the scope of this Update. The amendments require enhanced disclosures by requiring improved information about financial instruments and derivative instruments that are either (1) offset in accordance with either Section 210-20-45 or Section 815-10-45 or (2) subject to an enforceable master netting arrangement or similar agreement, irrespective of whether they are offset in accordance with either Section 210-20-45 or Section 815-10-45.
Issued: December 16, 2011
2011-12Accounting Standards Update No. 2011-12—Comprehensive Income (Topic 220)220
The amendments in this Update supersede certain pending paragraphs in Accounting Standards Update No. 2011-05, Comprehensive Income (Topic 220): Presentation of Comprehensive Income, to effectively defer only those changes in Update 2011-05 that relate to the presentation of reclassification adjustments out of accumulated other comprehensive income. The amendments will be temporary to allow the Board time to redeliberate the presentation requirements for reclassifications out of accumulated other comprehensive income for annual and interim financial statements for public, private, and non-profit entities.
Issued: December 23, 2011
2010
2010-01Accounting Standards Update No. 2010-01—Equity (Topic 505)505
The amendments in this Update clarify that the stock portion of a distribution to shareholders that allows them to elect to receive cash or stock with a potential limitation on the total amount of cash that all shareholders can elect to receive in the aggregate is considered a share issuance that is reflected in EPS prospectively and is not a stock dividend for purposes of applying Topics 505 and 260 (Equity and Earnings Per Share).
Issued: January 5, 2010
2010-02Accounting Standards Update No. 2010-02—Consolidation (Topic 810)810
This update provides amendments to Subtopic 810-10 and related guidance within U.S. GAAP to clarify the scope of the decrease in ownership provisions of the Subtopic and related guidance. The amendments in this Update also clarify that the decrease in ownership guidance does not apply to certain transactions even if they involve businesses.
Issued: January 6, 2010
2010-03Accounting Standards Update No. 2010-03—Extractive Activities—Oil and Gas (Topic 932)932
The objective of the amendments included in this Update is to align the oil and gas reserve estimation and disclosure requirements of Extractive Activities—Oil and Gas (Topic 932) with the requirements in the Securities and Exchange Commission's final rule, Modernization of the Oil and Gas Reporting Requirements (the Final Rule). The Final Rule was issued on December 31, 2008.
Issued: January 6, 2010
2010-04Accounting Standards Update No. 2010-04—Accounting for Various Topics
This Accounting Standards Update represents technical corrections to SEC guidance in various Topics.
Issued: January 15, 2010
2010-05Accounting Standards Update No. 2010-05—Compensation - Stock Compensation (Topic 718)718
This Accounting Standards Update codifies EITF Topic D-110, Escrowed Share Arrangements and the Presumption of Compensation, from the June 18, 2009 EITF meeting.
Issued: January 15, 2010
2010-06Accounting Standards Update No. 2010-06—Fair Value Measurements and Disclosures (Topic 820)820
This update provides amendments to Topic 820 that will provide more robust disclosures about (1) the different classes of assets and liabilites measured at fair value, (2) the valuation techniques and inputs used, (3) the activity in Level 3 fair value measurements, and (4) the transfers between Levels 1, 2, and 3.
Issued: January 21, 2010
2010-07Accounting Standards Update No. 2010-07—Not-for-Profit Entities (Topic 958)958
This Accounting Standards Update amends the Accounting Standards Codification for the issuance of FASB Statement No. 164, Not-for-Profit Entities: Mergers and Acquisitions. The amendments in this Accounting Standards Update provide guidance on accounting for combinations of not-for-profit entities. Those transactions or other events include mergers of two or more not-for-profit entities and acquisitions by a not-for-profit entity that result in its initially recognizing another not-for-profit entity, a business, or a nonprofit activity in its financial statements.
Issued: January 28, 2010
2010-08Accounting Standards Update No. 2010-08—Technical Corrections to Various Topics
From time to time, the Board reviews its standards to determine if any provisions in U.S. generally accepted accounting principles (GAAP) are outdated, contain inconsistencies, or need clarifications to reflect the Board's original intent. The amendments in this Update eliminate those inconsistencies and outdated provisions and provide the needed clarifications. The related changes to U.S. GAAP are generally nonsubstantive in nature.
Issued: February 2, 2010
2010-09Accounting Standards Update No. 2010-09—Subsequent Events (Topic 855)855
This Update addresses both the interaction of the requirements of Topic 855, Subsequent Events, with the SEC's reporting requirements and the intended breadth of the reissuance disclosures provision related to subsequent events (paragraph 855-10-50-4). The amendments in this Update have the potential to change reporting by both private and public entities, however, the nature of the change may vary depending on facts and circumstances.
Issued: February 24, 2010
2010-10Accounting Standards Update No. 2010-10—Consolidation (Topic 810)810
The objective of this Update is to defer the effective date of the amendments to the consolidation requirements made by FASB Statement 167 to a reporting entity's interest in certain types of entities and clarify other aspects of the Statement 167 amendments. As a result of the deferral, a reporting entity will not be required to apply the Statement 167 amendments to the Subtopic 810-10 consolidation requirements to its interest in an entity that meets the criteria to qualify for the deferral. This Update also clarifies how a related party's interests in an entity should be considered when evaluating the criteria for determining whether a decision maker or service provider fee represents a variable interest. In addition, the Update also clarifies that a quantitative calculation should not be the sole basis for evaluating whether a decision maker's or service provider's fee is a variable interest.
Issued: February 25, 2010
2010-11Accounting Standards Update No. 2010-11—Derivatives and Hedging (Topic 815)815
This Update clarifies the type of embedded credit derivative that is exempt from embedded derivative bifurcation requirements. Only one form of embedded credit derivative qualifies for the exemption—one that is related only to the subordination of one financial instrument to another. As a result, entities that have contracts containing an embedded credit derivative feature in a form other than such subordination may need to separately account for the embedded credit derivative feature.
Issued: March 5, 2010
2010-12Accounting Standards Update No. 2010-12—Income Taxes (Topic 740)740
This Update codifies an SEC Staff Announcement relating to accounting for the Health Care and Education Reconciliation Act of 2010 and the Patient Protection and Affordable Care Act.
Issued: April 14, 2010
2010-13Accounting Standards Update No. 2010-13—Compensation—Stock Compensation (Topic 718)718
This Update addresses the classification of a share-based payment award with an exercise price denominated in the currency of a market in which the underlying equity security trades. Topic 718 is amended to clarify that a share-based payment award with an exercise price denominated in the currency of a market in which a substantial portion of the entity's equity securities trades shall not be considered to contain a market, performance, or service condition. Therefore, such an award is not to be classified as a liability if it otherwise qualifies as equity classification.
Issued: April 16, 2010
2010-14Accounting Standards Update No. 2010-14—Accounting for Extractive Activities - Oil & Gas
This Accounting Standards Update amends paragraph 932-10-S99-1 due to SEC Release No. 33-8995 [FR 78], Modernization of Oil and Gas Reporting.
Issued: April 20, 2010
2010-15Accounting Standards Update No. 2010-15—Financial Services—Insurance (Topic 944)944
This Update clarifies that an insurance entity should not consider any separate account interests held for the benefit of policy holders in an investment to be the insurer's interests and should not combine those interests with its general account interest in the same investment when assessing the investment for consolidation, unless the separate account interests are held for the benefit of a related party policy holder as defined in the Variable Interest Entities Subsections of Subtopic 810-10 and those Subsections require the consideration of related parties. This Update also amends Subtopic 944-80 to clarify that for the purpose of evaluating whether the retention of specialized accounting for investments in consolidation is appropriate, a separate account arrangement should be considered a subsidiary. The amendments do not require an insurer to consolidate an investment in which a separate account holds a controlling financial interest if the investment is not or would not be consolidated in the standalone financial statements of the separate account. The amendments also provide guidance on how an insurer should consolidate an investment fund in situations in which the insurer concludes that consolidation is required.
Issued: April 21, 2010
2010-16Accounting Standards Update No. 2010-16—Entertainment—Casinos (Topic 924)924
This Update clarifies that an entity should not accrue a casino jackpot liability (or portions thereof) before the jackpot is won if the entity can avoid paying that jackpot. Jackpots should be accrued and charged to revenue when an entity has the obligation to pay the jackpot. The guidance under Topic 924 applies to both base and progressive jackpots.
Issued: April 26, 2010
2010-17Accounting Standards Update No. 2010-17—Revenue Recognition—Milestone Method (Topic 605)605
This Update provides guidance on defining a milestone under Topic 605 and determining when it may be appropriate to apply the milestone method of revenue recognition for research or development transactions. Consideration that is contingent on achievement of a milestone in its entirety may be recognized as revenue in the period in which the milestone is achieved only if the milestone is judged to meet certain criteria to be considered substantive. Milestones should be considered substantive in their entirety and may not be bifurcated. An arrangement may contain both substantive and nonsubstantive milestones that should be evaluated individually.
Issued: April 28, 2010
2010-18Accounting Standards Update No. 2010-18—Receivables (Topic 310)310
This Update clarifies that modifications of loans that are accounted for within a pool under Subtopic 310-30, which provides guidance on accounting for acquired loans that have evidence of credit deterioration upon acquisition, do not result in the removal of those loans from the pool even if the modification would otherwise be considered a troubled debt restructuring. An entity will continue to be required to consider whether the pool of assets in which the loan is included is impaired if expected cash flows for the pool change. The amendments do not affect the accounting for loans under the scope of Subtopic 310-30 that are not accounted for within pools. Loans accounted for individually under Subtopic 310-30 continue to be subject to the troubled debt restructuring accounting provisions within Subtopic 310-40.
Issued: April 29, 2010
2010-19Accounting Standards Update No. 2010-19—Foreign Currency (Topic 830)830
The purpose of this Update is to codify the SEC Staff Announcement made at the March 18, 2010 meeting of the FASB Emerging Issues Task Force (EITF) by the SEC Observer to the EITF. The Staff Announcement provides the SEC staff's view on certain foreign currency issues related to investments in Venezuela.
Issued: May 11, 2010
2010-20Accounting Standards Update No. 2010-20—Receivables (Topic 310)310
This Update amends Topic 310 to improve the disclosures that an entity provides about the credit quality of its financing receivables and the related allowance for credit losses. As a result of these amendments, an entity is required to disaggregate by portfolio segment or class certain existing disclosures and provide certain new disclosures about its financing receivables and related allowance for credit losses.
Issued: July 21, 2010
2010-21Accounting Standards Update No. 2010-21—Accounting for Technical Amendments to Various SEC Rules and Schedules
This Accounting Standards Update amends various SEC paragraphs pursuant to the issuance of Release No. 33-9026: Technical Amendments to Rules, Forms, Schedules and Codification of Financial Reporting Policies.
Issued: August 2, 2010
2010-22Accounting Standards Update No. 2010-22—Accounting for Various Topics
This Accounting Standards Update amends various SEC paragraphs based on external comments received and the issuance of SAB 112, which amends or rescinds portions of certain SAB topics.
Issued: August 19, 2010
2010-23Accounting Standards Update No. 2010-23—Health Care Entities (Topic 954)954
This Update addresses the diversity in the accounting for charity care disclosures, which some entities determine on the basis of a cost measurement, while others use a revenue measurement. The amendments to Topic 954 require that the measurement of charity care for disclosure purposes be based on the direct and indirect costs of providing the charity care.
Issued: August 26, 2010
2010-24Accounting Standards Update No. 2010-24—Health Care Entities (Topic 954)954
This Update addresses the diversity in the accounting for medical malpractice and similar liabilities and their related anticipated insurance recoveries by health care entities that mostly have netted insurance recoveries against the accrued liability, although some have presented the anticipated insurance recovery and the liability on a gross basis. The amendments to Topic 954 clarify that a health care entity should not net insurance recoveries against a related claim liability; the amount of the claim liability should be determined without consideration of insurance recoveries.
Issued: August 27, 2010
2010-25Accounting Standards Update No. 2010-25—Plan Accounting—Defined Contribution Pension Plans (Topic 962)962
The amendments in this Update require that participant loans be classified as notes receivable from participants, which are segregated from plan investments and measured at their unpaid principal balance plus any accrued but unpaid interest.
Issued: September 28, 2010
2010-26Accounting Standards Update No. 2010-26—Financial Services—Insurance (Topic 944)944
The amendments in this Update specify that certain costs incurred in the successful acquisition of new and renewal contracts should be capitalized. Those costs include incremental direct costs of contract acquisition that result directly from and are essential to the contract transaction(s) and would not have been incurred by the insurance entity had the contract transaction(s) not occurred. Additionally, advertising costs are only to be capitalized as deferred acquisition costs if the capitalization criteria for direct-response advertising in Subtopic 340-20 are met.
All other acquisition-related costs—including costs incurred by the insurer for soliciting potential customers, market research, training, administration, unsuccessful acquisition or renewal efforts, and product development—should be charged to expense as incurred. Administrative costs, rent, depreciation, occupancy, equipment, and all other general overhead costs are considered indirect costs and should also be charged to expense as incurred.
Issued: October 13, 2010
2010-27Accounting Standards Update No. 2010-27—Other Expenses (Topic 720)720
The objective of this Update is to address questions concerning how pharmaceutical manufacturers should recognize and classify in their income statements fees mandated by the Patient Protection and Affordable Care Act as amended by the Health Care and Education Reconciliation Act (the Acts). The Acts impose an annual fee on the pharmaceutical manufacturing industry for each calendar year beginning on or after January 1, 2011. For reporting entities that are subject to the pharmaceutical fee mandated by the Acts, the amendments in this Update specify that the liability for the fee should be estimated and recorded in full upon the first qualifying sale with a corresponding deferred cost that is amortized to expense using a straight-line method of allocation unless another method better allocates the fee over the calendar year that it is payable.
Issued: December 16, 2010
2010-28Accounting Standards Update No. 2010-28—Intangibles—Goodwill and Other (Topic 350)350
The amendments in this Update affect all entities that have recognized goodwill and have one or more reporting units whose carrying amount for purposes of performing Step 1 of the goodwill impairment test is zero or negative. The amendments in this Update modify Step 1 so that for those reporting units, an entity is required to perform Step 2 of the goodwill impairment test if it is more likely than not that a goodwill impairment exists. In determining whether it is more likely than not that a goodwill impairment exists, an entity should consider whether there are any adverse qualitative factors indicating that an impairment may exist. The qualitative factors are consistent with existing guidance, which requires that goodwill of a reporting unit be tested for impairment between annual tests if an event occurs or circumstances change that would more likely than not reduce the fair value of a reporting unit below its carrying amount.
Issued: December 17, 2010
2010-29Accounting Standards Update No. 2010-29—Business Combinations (Topic 805)805
The objective of this Update is to address diversity in practice about the interpretation of the pro forma revenue and earnings disclosure requirements for business combinations.
The amendments in this Update specify that if a public entity presents comparative financial statements, the entity should disclose revenue and earnings of the combined entity as though the business combination(s) that occurred during the current year had occurred as of the beginning of the comparable prior annual reporting period only. The amendments also expand the supplemental pro forma disclosures to include a description of the nature and amount of material, nonrecurring pro forma adjustments directly attributable to the business combination included in the reported pro forma revenue and earnings.
The amendments affect any public entity as defined by Topic 805 that enters into business combinations that are material on an individual or aggregate basis.
Issued: December 21, 2010
2009
2009-01Accounting Standards Update No. 2009-01—Generally Accepted Accounting Principles (Topic 105)105
This Accounting Standards Update amends the FASB Accounting Standards Codification for the issuance of FASB Statement No. 168, The FASB Accounting Standards Codification® and the Hierarchy of Generally Accepted Accounting Principles. This Accounting Standards Update includes Statement 168 in its entirety, including the accounting standards update instructions contained in Appendix B of the Statement.
Issued: June 30, 2009
2009-02Accounting Standards Update No. 2009-02—Omnibus Update
This Accounting Standards Update represents technical corrections to various Topics addressing feedback received.
Issued: June 30, 2009
2009-03Accounting Standards Update No. 2009-03—SEC Update
This Codification Update represents technical corrections to various Topics containing SEC Staff Accounting Bulletins to update cross-references to Codification text.
Issued: August 24, 2009
2009-04Accounting Standards Update No. 2009-04—Accounting for Redeemable Equity Instruments
This Accounting Standards Update represents an update to Section 480-10-S99, "Distinguishing Liabilities from Equity," per EITF Topic D-98, "Classification and Measurement of Redeemable Securities."
Issued: August 26, 2009
2009-05Accounting Standards Update No. 2009-05—Fair Value Measurements and Disclosures (Topic 820)820
This Accounting Standards Update amends Subtopic 820-10, Fair Value Measurements and Disclosures > Overall, to provide guidance on the fair value measurement of liabilities.
Issued: August 26, 2009
2009-06Accounting Standards Update No. 2009-06—Income Taxes (Topic 740)740
The Board is issuing this Update to provide additional implementation guidance on accounting for uncertainty in income taxes and to eliminate the disclosures required by paragraph 740-10-50-15(a) through (b) for nonpublic entities.
Issued: September 2, 2009
2009-07Accounting Standards Update No. 2009-07—Accounting for Various Topics
This Codification Update represents technical corrections to various Topics containing SEC guidance based on external comments received.
Issued: September 15, 2009
2009-08Accounting Standards Update No. 2009-08—Earnings Per Share
This Codification Update represents technical corrections to Topic 260-10-S99, Earnings per Share, based on EITF Topic D-53, "Computation of Earnings Per Share for a Period that Includes a Redemption or an Induced Conversion of a Portion of a Class of Preferred Stock" and EITF Topic D-42, "The Effect of the Calculation of Earnings per Share for the Redemption or Induced Conversion of Preferred Stock."
Issued: September 16, 2009
2009-09Accounting Standards Update No. 2009-09—Accounting for Investments—Equity Method and Joint Ventures and Accounting for Equity-Based Payments to Non-Employees
This Accounting Standards Update represents a correction to Section 323-10-S99-4, Accounting by an Investor for Stock-Based Compensation Granted to Employees of an Equity Method Investee. Section 323-10-S99-4 was originally entered into the Codification incorrectly.
Issued: September 17, 2009
2009-10Accounting Standards Update No. 2009-10—Financial Services—Broker and Dealers: Investments—Other
This Accounting Standards Update codifies the Observer comment in paragraph 17 of EITF 02-3, "Issues Involved in Accounting for Derivative Contracts Held for Trading Purposes and Contracts Involved in Energy Trading and Risk Management."
Issued: September 18, 2009
2009-11Accounting Standards Update No. 2009-11—Extractive Activities—Oil and Gas
This Accounting Standards Update represents a technical correction to the SEC Observer comment in EITF 90-22, "Accounting for Gas-Balancing Arrangements."
Issued: September 18, 2009
2009-12Accounting Standards Update No. 2009-12—Fair Value Measurements and Disclosures (Topic 820)820
This Accounting Standards Update amends Subtopic 820-10, Fair Value Measurements and Disclosures > Overall, to provide guidance on the fair value measurement of investments in certain entities that calculate net asset value per share (or its equivalent).
Issued: September 30, 2009
2009-13Accounting Standards Update No. 2009-13—Revenue Recognition (Topic 605)605
The objective of this Update is to address the accounting for multiple-deliverable arrangements to enable vendors to account for products or services (deliverables) separately rather than as a combined unit.
Issued: October 7, 2009
2009-14Accounting Standards Update No. 2009-14—Software (Topic 985)985
The objective of this Update is to address concerns raised by constituents relating to the accounting for revenue arrangements that contain tangible products and software.
Issued: October 7, 2009
2009-15Accounting Standards Update No. 2009-15—Accounting for Own-Share Lending Arrangements in Contemplation of Convertible Debt Issuance or Other Financing
The purpose of this Update is to address the accounting for own-share lending arrangements entered into in contemplation of a convertible debt issuance or other financing.
Issued: October 13, 2009
2009-16Accounting Standards Update No. 2009-16—Transfers and Servicing (Topic 860)860
This Accounting Standards Update amends the FASB Accounting Standards Codification for the issuance of FASB Statement No. 166, Accounting for Transfers of Financial Assets—an amendment of FASB Statement No. 140.
The amendments in this Accounting Standards Update improve financial reporting by eliminating the exceptions for qualifying special-purpose entities from the consolidation guidance and the exception that permitted sale accounting for certain mortgage securitizations when a transferor has not surrendered control over the transferred financial assets. In addition, the amendments require enhanced disclosures about the risks that a transferor continues to be exposed to because of its continuing involvement in transferred financial assets. Comparability and consistency in accounting for transferred financial assets will also be improved through clarifications of the requirements for isolation and limitations on portions of financial assets that are eligible for sale accounting.
Issued: December 23, 2009
2009-17Accounting Standards Update No. 2009-17—Consolidations (Topic 810)810
This Accounting Standards Update amends the FASB Accounting Standards Codification for the issuance of FASB Statement No. 167, Amendments to FASB Interpretation No. 46(R).
The amendments in this Accounting Standards Update replace the quantitative-based risks and rewards calculation for determining which reporting entity, if any, has a controlling financial interest in a variable interest entity with an approach focused on identifying which reporting entity has the power to direct the activities of a variable interest entity that most significantly impact the entity's economic performance and (1) the obligation to absorb losses of the entity or (2) the right to receive benefits from the entity. An approach that is expected to be primarily qualitative will be more effective for identifying which reporting entity has a controlling financial interest in a variable interest entity. The amendments in this Update also require additional disclosures about an reporting entity's involvement in variable interest entities, which will enhance the information provided to users of financial statements.
Issued: December 23, 2009
Proposed & exposure documents
Exposure drafts, proposed ASUs, invitations to comment, and discussion papers.
2026
Proposed Accounting Standards Update 2026-ED100—Compensation—Retirement Benefits—Defined Benefit Plans—Pension (Subtopic 715-30): Discount Rate Used to Measure the Benefit Obligation for Certain Market-Return Cash Balance Plans715
The amendments in this proposed Update specify the discount rate required to be used to measure the benefit obligation for certain market-return cash balance plans.
For more information, see the following:
Issued: June 10, 2026
Comments Due: August 10, 2026
The Exposure Draft identifies the Codification Sections that may be changed upon issuance of the guidance.
Proposed Accounting Standards Update 2026-ED200—Derivatives and Hedging (Topic 815): Targeted Improvements to Accounting for Interest Rate Risk Hedging and Net Investment Hedging815
The amendments in this proposed Update would broaden the application of hedge accounting by removing exceptions or limitations in the general hedge accounting model that related to three discrete hedge accounting issues.
For more information, see the following:
Issued: June 17, 2026
Comments Due: August 17, 2026
The Exposure Draft identifies the Codification Sections that may be changed upon issuance of the guidance.
Proposed Accounting Standards Update 2026-ED400—Statement of Cash Flows (Topic 230): Cash Equivalents—Disclosure Enhancement and Evaluation of Certain Digital Assets230
For all entities that have certain digital assets, the amendments in this proposed Update would illustrate how the definition of cash equivalents applies to those assets.
For all entities that present assets as cash equivalents, the amendments in this proposed Update would require disclosure of the significant components and related amounts of cash equivalents, regardless of whether those assets include digital assets.
For more information, see the following:
Issued: August 18, 2026
Comments Due: November 19, 2026
The Exposure Draft indicates the Codification sections that may be changed upon issuance of the guidance.
Proposed Accounting Standards Update 2026-ED500—Codification Improvements
The amendments in this proposed Update would address suggestions received from stakeholders on the Accounting Standards Codification and make other incremental improvements to generally accepted accounting principles (GAAP). The proposed amendments would make Codification updates for a broad range of Topics arising from technical corrections, unintended application of the Codification, clarifications, and other minor improvements.
For more information, see the following:
Issued: September 2, 2026
Comments Due: November 19, 2026
The Exposure Draft indicates the Codification sections that may be changed upon issuance of the guidance.
2025
Proposed Accounting Standards Update 2025-ED200—Debt—Modifications and Extinguishments (Subtopic 470-50) and Liabilities—Extinguishments of Liabilities (Subtopic 405-20): Accounting for Debt Exchanges405470
The amendments in this proposed Update improve the financial accounting by specifying that an exchange of debt instruments that meets certain requirements should be accounted for by the debtor as the issuance of a new debt obligation and an extinguishment of the existing debt obligation.
For more information, see the following:
Issued: April 30, 2025
Comments Due: May 30, 2025
The Exposure Draft identifies the Codification Sections that may be changed upon issuance of the guidance.
2020
2020-700Proposed Accounting Standards Update 2020-700—Leases (Topic 842): Targeted Improvements842
The amendments in this proposed Update would:
- 1Require lessors to classify and account for a lease with lease payments that are predominantly variable and do not depend on a reference index or a rate as an operating lease. When a lease is classified as operating, the lessor would not recognize a lease receivable, would not derecognize the underlying asset, and, therefore, would not recognize a selling profit or loss.
- 2Provide lessees with the option to make an entity-wide accounting policy election to remeasure lease liabilities for changes in a reference index or a rate affecting future lease payments at the date that those changes take effect.
- 3Exempt entities from applying modification accounting to the remaining lease components within a lease contract for transactions in which one or more lease components are terminated before the end of the lease term and that early termination does not economically affect the remaining lease components.
For more information, see the following:
Issued: October 20, 2020
Comments Due: December 4, 2020
The Exposure Draft identifies the Codification Sections that may be changed upon issuance of this guidance.
2019
2019-300Proposed Accounting Standards Update 2019-300—Business Combinations (Topic 805)—Revenue from Contracts with Customers—Recognizing an Assumed Liability805
The amendments in this proposed Update would provide specific guidance for a business combination on how to apply the recognition principle in Topic 805 to revenue contracts with customers after the acquirer has adopted Topic 606, Revenue from Contracts with Customers. The proposed amendments would require that an acquirer recognize a liability assumed in a business combination from a contract with a customer if that liability represents an unsatisfied performance obligation under Topic 606 for which the acquiree has received consideration (or the amount is due) from the customer.
The proposed Update was issued concurrently with the FASB Invitation to Comment, Measurement and Other Considerations Related to Revenue Contracts with Customers under Topic 805, which addresses the measurement of contract liabilities from revenue contracts with customers acquired in a business combination and other topics related to the accounting for revenue contracts acquired in a business combination.
For more information, see the following:
Issued: February 14, 2019
Comments Due: April 30, 2019
The Exposure Draft identifies the Codification Sections that may be changed upon issuance of this guidance.
2019-500Proposed Accounting Standards Update (Revised) 2019-500—Income Taxes (Topic 740)—Disclosure Framework—Changes to the Disclosure Requirements for Income Taxes (Revision of Exposure Draft Issued July 26, 2016)740
The amendments in this proposed Update would modify the current disclosure requirements for income taxes. The proposed amendments would (1) remove disclosures that no longer are considered cost beneficial or relevant and (2) add disclosure requirements identified as relevant to financial statement users. The Board is issuing the amendments in this proposed Update as part of the disclosure framework project to improve the effectiveness of disclosures in the notes to financial statements by applying concepts in the FASB Concepts Statement No. 8, Conceptual Framework for Financial Reporting—Chapter 8: Notes to Financial Statements.
For more information, see the following:
Issued: March 25, 2019
Comments Due: May 31, 2019
The Exposure Draft identifies the Codification Sections that may be changed upon issuance of this guidance.
2019-780Proposed Accounting Standards Update (Revised) 2019-780—Debt (Topic 470)—Simplifying the Classification of Debt in a Classified Balance Sheet (Current versus Noncurrent)470
Stakeholders have told the Board that the guidance on determining whether debt should be classified as current or noncurrent in a classified balance sheet is overly complex. Topic 470, Debt, includes guidance on various narrow-scope, fact-specific debt transactions. The amendments in this proposed Update would replace the current, fact-specific guidance with an overarching, cohesive principle. The Board expects that the proposed amendments would reduce the cost and complexity for preparers and auditors when determining whether debt should be classified as current or noncurrent in the balance sheet, while providing more consistent and transparent information to financial statement users.
For more information, see the following:
Issued: September 12, 2019
Comments Due: October 28, 2019
The Exposure Draft identifies the Codification Sections that may be changed upon issuance of this guidance.
2019-790Proposed Accounting Standards Update 2019-790—Derivatives and Hedging (Topic 815): Codification Improvements to Hedge Accounting815
The amendments in this proposed Update would clarify certain amendments in Accounting Standards Update 2017-12, Derivatives and Hedging (Topic 815): Targeted Improvements to Accounting for Hedging Activities. The proposed amendments would better align the amendments in Update 2017-12 with the objective articulated in that Update and eliminate the unintended application of certain amendments. Specifically, the amendments in the proposed Update address stakeholders' questions received since the issuance of Update 2017-12 on (a) a change in hedged risk in a cash flow hedge, (b) contractually specified components in cash flow hedges of nonfinancial forecasted transactions, (c) a foreign-currency-denominated debt instrument as a hedging instrument and hedged item, and (d) using the term prepayable under the shortcut method.
For more information, see the following:
Issued: November 12, 2019
Comments Due: January 13, 2020
The Exposure Draft identifies the Codification Sections that may be changed upon issuance of this guidance.
2017
2017-200Proposed Accounting Standards Update 2017-200—Debt (Topic 470)—Simplifying the Classification of Debt in a Classified Balance Sheet (Current versus Noncurrent)470
This proposed Update is intended to improve financial reporting by simplifying guidance used to determine whether debt should be classified as current or noncurrent in a classified balance sheet. It would replace the existing, fact-specific guidance with an overarching, cohesive principle for debt classification that focuses on a borrower's contractual rights and obligations that exist as of the reporting date.
For more information, see the following:
Issued: January 10, 2017
Comments Due: May 5, 2017
The Exposure Draft identifies the Codification Sections that may be changed upon issuance of this guidance.
2017-210Proposed Accounting Standards Update 2017-210—Inventory (Topic 330)—Disclosure Framework—Changes to the Disclosure Requirements for Inventory330
The amendments in this proposed Update would add disclosure requirements for inventory, including changes in inventory that are not related to the ordinary course of manufacturing, purchasing, or selling inventory and disaggregating inventory by major components and measurement bases, among others. Entities that report some or all of their inventory using the retail inventory method (RIM) also would be required to provide qualitative and quantitative information about the critical assumptions used in the calculation of inventory under the RIM. In addition, entities that are subject to disclosing segment information in Topic 280, Segment Reporting, would be required to disclose, in both annual and interim periods, inventory by reportable segment and by component for each reportable segment to the extent that information is regularly provided to the chief operating decision maker.
For more information, see the following:
Issued: January 10, 2017
Comments Due: March 13, 2017
The Exposure Draft identifies the Codification Sections that may be changed upon issuance of this guidance.
2016
2016-270Proposed Accounting Standards Update 2016-270—Income Taxes (Topic 740)—Disclosure Framework—Changes to the Disclosure Requirements for Income Taxes740
The amendments in this proposed Update would modify current disclosure requirements and add additional requirements for income taxes on the basis of the proposed Concepts Statement, Conceptual Framework for Financial Reporting—Chapter 8: Notes to Financial Statements. One disclosure requirement would be eliminated from Topic 740 because it is inconsistent with the guidance in the proposed Concepts Statement.
For more information, see the following:
Issued: July 26, 2016
Comments Due: September 30, 2016
The Exposure Draft identifies the Codification Sections that may be changed upon issuance of this guidance.
2016-350Proposed Accounting Standards Update 2016-350—Technical Correction to Update No. 2016-14, Not-for-Profit Entities (Topic 958): Presentation of Financial Statements of Not-for-Profit Entities—Endowment Reporting958
The proposed Update would clarify the minimum requirements for the reconciliation that an NFP is required to disclose if it has endowment funds, by removing the words “that contain no purpose restrictions.”
For more information, see the following:
Issued: October 27, 2016
Comments Due: November 11, 2016
The Exposure Draft identifies the Codification Sections that may be changed upon issuance of this guidance.
2015
2015-220Proposed Accounting Standards Update 2015-220—Derivatives and Hedging (Topic 815)815
The amendments in this proposed Update would require that an entity disclose (in both interim and annual reporting periods) the carrying amount, measurement attribute, and line item within the balance sheet and the income statement in which each bifurcated embedded derivative and its related host contract are presented.
For more information, see the following:
Issued: February 24, 2015
Comments Due: April 30, 2015
The Exposure Draft identifies the Codification Sections that may be changed upon issuance of this guidance.
2015-250Proposed Accounting Standards Update 2015-250—Revenue from Contracts with Customers (Topic 606)606
The proposed Update would clarify guidance related to performance obligations and licensing contained in the new revenue recognition standard.
The proposed Update includes targeted improvements based on input the Board received from the Transition Resource Group for Revenue Recognition and other stakeholders. The Update seeks to proactively address areas in which diversity in practice potentially could arise, as well as to reduce the cost and complexity of applying certain aspects of the guidance both at implementation and on an ongoing basis.
For more information, see the following:
Issued: May 12, 2015
Comments Due: June 30, 2015
The Exposure Draft identifies the Codification Sections that may be changed upon issuance of this guidance.
2015-280Proposed Accounting Standards Update 2015-280—Investments—Equity Method and Joint Ventures (Topic 323)323
Basis Difference
To simplify the accounting for equity method investments, the Board proposes to eliminate the requirement for an equity method investor to account for the basis difference, which is the difference between the cost of an investment and the investor's proportionate share of the net assets of the investee. Topic 323 currently requires an entity to determine the acquisition date fair value of the identifiable assets and liabilities assumed in the same manner as a business combination. The equity method investor's proportionate share of the difference between the fair value of the investee's identifiable assets and liabilities assumed and the book value of recorded assets and liabilities assumed generally must be accounted for in net income in subsequent periods. The proposed Update would eliminate the requirement for an entity to calculate the total basis difference and attribute the basis difference to its various components as well as remove the need for an entity to track the components of the basis difference (for example, intangible assets, goodwill, and deferred tax liabilities) in what is commonly referred to as memo accounts and account for any resulting amortization.
Increase in the Level of Ownership Interest
To simplify the accounting for equity method investments, the Board proposes to eliminate the requirement that an entity retroactively adopt the equity method of accounting if an investment qualifies for use of the equity method as a result of an increase in the level of ownership.
For more information, see the following:
Issued: June 5, 2015
Comments Due: August 4, 2015
The Exposure Draft identifies the Codification Sections that may be changed upon issuance of this guidance.
2015-310Proposed Accounting Standards Update 2015-310—Notes to Financial Statements (Topic 235)—Assessing Whether Disclosures Are Material235
The amendments in this Update would promote the appropriate use of discretion by reporting entities when assessing disclosure requirements.
For more information, see the following:
Issued: September 24, 2015
Comments Due: December 8, 2015
The Exposure Draft identifies the Codification Sections that may be changed upon issuance of this guidance.
2014
2014-270Proposed Accounting Standards Update 2014-270—Financial Services—Investment Companies (Topic 946)946
To improve existing disclosure requirements, the amendments in this proposed Update would require all feeder funds in a master-feeder arrangement to provide the master fund's financial statements along with its financial statements. The proposed amendments also would expand the scope of the current requirement to disclose certain information about investments held by investee funds that exceed 5 percent of the reporting entity's net assets to include reporting investment companies that are regulated under the Investment Company Act of 1940.
For more information, see the following:
Issued: December 4, 2014
Comments Due: February 17, 2015
The Exposure Draft identifies the Codification Sections that may be changed upon issuance of this guidance.
2013
2013-290Proposed Accounting Standards Update 2013-290—Insurance Contracts (Topic 834)
The main objectives of the guidance in this proposed Update is to increase the decision usefulness of the information about an entity's insurance liabilities, including the nature, amount, timing, and uncertainty of cash flows related to those liabilities, and the related effect on the statement of comprehensive income, and to provide comparability, regardless of the type of entity issuing the contract. The guidance in this proposed Update would require an entity to measure its insurance contracts under one of two measurement models, referred to as the building block approach and the premium allocation approach. The proposed Update would improve convergence of U.S. GAAP and IFRSs by moving towards a more globally comparable standard.
For more information, see the following:
Issued: June 27, 2013
Comments Due: October 25, 2013
The Exposure Draft identifies the Codification Sections that may be changed upon issuance of this guidance.
2012
2012-200Proposed Accounting Standards Update 2012-200—Financial Instruments (Topic 825)825
The objective of this proposed Update is to improve financial reporting about certain risks inherent in financial instruments and how they contribute to broader risks to which the reporting organization is exposed. The proposed Update addresses many stakeholders' concerns about how organizations disclose their exposures to liquidity risk and interest rate risk, two risks that were prominent during the recent financial crisis and that continue to be relevant to reporting organizations on an ongoing basis, and proposes to require expanded and standardized disclosures about these risks.
For more information, see the following:
Issued: June 27, 2012
Comments Due: September 25, 2012
The Exposure Draft identifies the Codification Sections that may be changed upon issuance of this guidance.
2011
2011-210Proposed Accounting Standards Update 2011-210—Real Estate—Investment Property Entities (Topic 973)
The amendments in this proposed Update would provide accounting guidance for an entity that meets the criteria to be an investment property entity.
For more information, see the following:
Issued: October 21, 2011
Comments Due: January 5, 2012
The Exposure Draft identifies the Codification Sections that may be changed upon issuance of this guidance.
Proposed Accounting Standards Update EITF11A—Consolidation (Topic 810)810
The objective of this proposed Update is to resolve the diversity in practice about whether Subtopic 810-10, Consolidation—Overall, or Subtopic 830-30, Foreign Currency Matters—Translation of Financial Statements, applies to the release of the cumulative translation adjustment into earnings when a parent no longer holds a controlling financial interest in a group of assets that is a nonprofit activity or a business (other than a sale of in substance real estate or conveyance of oil and gas mineral rights) within a consolidated foreign entity.
For more information, see the following:
Issued: December 8, 2011
Comments Due: February 6, 2012
The Exposure Draft identifies the Codification Sections that may be changed upon issuance of this guidance.
2008
Exposure Draft 1240-100—Earnings per Share
The FASB is issuing this proposed Statement as part of a joint project with the International Accounting Standards Board (IASB). The FASB and the IASB undertook that project to eliminate differences between FASB Statement No. 128, Earnings per Share, and IAS 33, Earnings per Share, in ways that also would clarify and simplify the earnings per share (EPS) computation. This proposed Statement proposes amendments to Statement 128. The IASB also issued an Exposure Draft proposing amendments to IAS 33. Those proposed amendments, taken together, would improve the comparability of EPS because the denominator used to compute EPS under Statement 128 would be the same as the denominator used to compute EPS under IAS 33, with limited exceptions. Those limited exceptions relate to certain instruments for which the underlying accounting under U.S. generally accepted accounting principles (GAAP) and international financial reporting standards (IFRS) is different.
For more information, see the following:
Issued: August 7, 2008
Comment Deadline: December 5, 2008
The Exposure Draft identifies the Codification Subsections that may be added upon issuance of this guidance.
Exposure Draft 1650-100—Going Concern
This proposed Statement would provide guidance on the preparation of financial statements as a going concern and on management's responsibility to evaluate a reporting entity's ability to continue as a going concern. It also would require certain disclosures when either financial statements are not prepared on a going concern basis or when there is substantial doubt as to an entity's ability to continue as a going concern. Currently, AU Section 341, The Auditor's Consideration of an Entity's Ability to Continue as a Going Concern, of the AICPA Codification of Statements on Auditing Standards contains the guidance about the going concern assessment. The Public Company Accounting Oversight Board (PCAOB) adopted AU Section 341 on an initial, transitional basis and has subsequently amended that interim standard.
For more information, see the following:
Issued: October 9, 2008
Comment Deadline: December 8, 2008
The Exposure Draft identifies the Codification Subsections that may be added upon issuance of this guidance.
Note: On June 3, 2009, the Board decided to broaden the scope of the project. A proposed ASU will be published after Board deliberations.
Proposed FSP FAS 144-d—Amending the Criteria for Reporting a Discontinued Operation
This proposed FASB Staff Position (FSP) would amend the definition of a discontinued operation. It would thus establish when the income effects of a component of an entity would be reported in the discontinued operations section of the income statement under FASB Statement No. 144, Accounting for the Impairment or Disposal of Long-Lived Assets. This proposed FSP also would amend the disclosure requirements of Statement 144 for all components of an entity that either have been disposed of or are classified as held for sale regardless of whether a component of an entity is reported in the income statement as a discontinued operation or within continuing operations.
For more information, see the following:
Issued: September 25, 2008
Comment Deadline: January 23, 2009
Maintenance updates
Editorial and technical corrections that do not change GAAP.
2026
2026 Maintenance Updates
Maintenance Updates provide nonsubstantive corrections to the Codification, such as editorial corrections, various types of link-related changes, and changes to source fragment information (used for Cross Reference and the Printer-Friendly with Sources). On occasion, a maintenance update may include nonsubstantive corrections which are reflected in the relevant Status tables.
| Date | Maintenance Update | Affected Topics/Subtopics | Affected Glossary Terms |
| 07/31/2026 | 2026-08 (PDF) | 270-10 | None |
| 07/16/2026 | 2026-07 (PDF) | None | None |
| 07/02/2026 | 2026-06(roll-off) (PDF) | Various (See Release Notes) | Block of New Insurance Contracts,Formation Date, Goodwill, Guaranteed Minimum Income Benefit, Lock-In Concept, Market Risk Benefit, Net Premiums, Risk of Adverse Deviation |
| 06/01/2026 | 2026-05 (PDF) | None | None |
| 05/01/2026 | 2026-04 (PDF) | None | None |
| 04/03/2026 | 2026-03 (PDF) | None | None |
| 02/27/2026 | 2026-02 (PDF) | Various (See Release Notes) | None |
| 01/30/2026 | 2026-01 (PDF) | Various (See Release Notes) | Nonpublic Entity (definition 4) |
2025
2025 Maintenance Updates
Maintenance Updates provide nonsubstantive corrections to the Codification, such as editorial corrections, various types of link-related changes, and changes to source fragment information (used for Cross Reference and the Printer-Friendly with Sources). On occasion, a maintenance update may include nonsubstantive corrections which are reflected in the relevant Status tables.
| Date | Maintenance Update | Affected Topics/Subtopics | Affected Glossary Terms |
| 11/19/2025 | 2025-08 (PDF) | None | None |
| 07/28/2025 | 2025-07 (PDF) | Various (see release notes) | None |
| 06/30/2025 | 2025-06(roll-off) (PDF) | Various (see release notes) | Beneficial Conversion Feature, Hedged Layer |
| 06/20/2025 | 2025-05 (PDF) | 205-10, 326-20, 805-10, 860-50, and relevant Status tables | None |
| 05/30/2025 | 2025-04 (PDF) | 270-10, 360-10, 360-20, 505-50, 740-10, 810-10, 815-10, 815-40, 840-10, 842-10 | Direct Financing Lease |
| 04/25/2025 | 2025-03 (PDF) | None | None |
| 02/28/2025 | 2025-02 (PDF) | 230-10, 360-20, 470-20, 718-10, 850-10 | None |
| 01/31/2025 | 2025-01 (PDF) | None | None |
2024
2024 Maintenance Updates
Maintenance Updates provide nonsubstantive corrections to the Codification, such as editorial corrections, various types of link-related changes, and changes to source fragment information (used for Cross Reference and the Printer-Friendly with Sources). On occasion, a maintenance update may include nonsubstantive corrections which are reflected in the relevant Status tables.
| Date | Maintenance Update | Affected Topics/Subtopics | Affected Glossary Terms |
| 12/12/2024 | 2024-09 (PDF) | 105-10, 470-20, 815-10 | None |
| 11/08/2024 | 2024-08 (PDF) | 210-20, 274-10, 323-10, 805-10, 946-210, 985-20 | None |
| 09/24/2024 | 2024-07 (PDF) | 220-10, 325-40, 326-20, 350-50, 505-10, 606-10, 805-10, 805-20, 820-10, 840-20, 910-810, 924-10, 932-810, 944-720, 958-10, 958-205, 958-220, 958-605 | None |
| 07/26/2024 | 2024-06 (PDF) | 205-10, 210-20, 310-20, 310-40, 320-10, 740-270, 805-10, 805-20, 805-30, 805-740, 815-10, 815-20, 815-25, 815-30, 825-10, 942-320, 954-805, 958-805 | None |
| 07/03/2024 | 2024-05 (PDF) | 210-20, 323-740, 505-10, 718-10, 805-60, 815-25 | None |
| 06/21/2024 | 2024-04(roll-off) (PDF) | Various (see Release Notes) | Various (see Release Notes) |
| 05/31/2024 | 2024-03 (PDF) | 260-10, 405-50, 810-10, 815-25, 860-10 | Financial Instruments |
| 05/03/2024 | 2024-02 (PDF) | 220-10, 230-10, 280-10, 420-10, 805-10, 805-20, 805-50, 815-20, 860-10, 928-10, 932-235, 954-405 | None |
| 02/15/2024 | 2024-01 (PDF) | 270-10, 280-10, 405-50, 410-30, 460-10, 718-10, 740-10, 740-323, 852-10, 946-325, 954-10 | None |
2023
2023 Maintenance Updates
Maintenance Updates provide nonsubstantive corrections to the Codification, such as editorial corrections, various types of link-related changes, and changes to source fragment information (used for Cross Reference and the Printer-Friendly with Sources). On occasion, a maintenance update may include nonsubstantive corrections which are reflected in the relevant Status tables.
| Date | Maintenance Update | Affected Topics/Subtopics | Affected Glossary Terms |
| 11/20/2023 | 2023-09 (PDF) | 260-10, 718-10, 820-10 | None |
| 09/14/2023 | 2023-08 (PDF) | 205-20, 260-10, 323-10, 450-20, 740-10, 805-10, 815-20, 842-10, 860-30 | None |
| 07/10/2023 | 2023-07(roll-off) (PDF) | Various (see Release Notes) | Various (see Release Notes) |
| 06/19/2023 | 2023-06 (PDF) | None | None |
| 06/06/2023 | 2023-05 (PDF) | 220-10, 235-10, 860-10, 958-605 | None |
| 05/16/2023 | 2023-04 (PDF) | Various (see Release Notes) | None |
| 03/31/2023 | 2023-03 (PDF) | Various (see Release Notes) | Various (see Release Notes) |
| 02/16/2023 | 2023-02 (PDF) | 220-10, 270-10, 718-20, 815-25, 825-10, 944-80, 958-310, 958-605 | None |
| 01/11/2023 | 2023-01 (PDF) | 255-10, 805-20, 810-10, 815-10, 815-20, 815-25, 815-30, 825-10, 860-10, 954-10 | Various (see Release Notes) |
2022
2022 Maintenance Updates
Maintenance Updates provide nonsubstantive corrections to the Codification, such as editorial corrections, various types of link-related changes, and changes to source fragment information (used for Cross Reference and the Printer-Friendly with Sources). On occasion, a maintenance update may include nonsubstantive corrections which are reflected in the relevant Status tables.
| Date | Maintenance Update | Affected Topics/Subtopics | Affected Glossary Terms |
| 12/14/2022 | 2022-07(roll-off) (PDF) | Various (See Release Notes) | Various (See Release Notes) |
| 11/10/2022 | 2022-06 (PDF) | 715-20, 842-10, 958-715 | N/A |
| 10/13/2022 | 2022-05 (PDF) | 350-20, 848-10, 848-20, 848-30, 848-40, 848-50 | Various (See Release Notes) |
| 07/18/2022 | 2022-04 (PDF) | N/A | N/A |
| 07/05/2022 | 2022-03 (PDF) | N/A | N/A |
| 04/04/2022 | 2022-02 (PDF) | N/A | N/A |
| 03/09/2022 | 2022-01 (PDF) | 280-10, 310-20, 320-10, 340-40, 350-20, 350-40, 410-20, 410-30, 480-10, 606-10, 715-20, 715-80, 718-10, 730-10, 805-20, 805-30, 820-10, 860-10, 860-20, 905-10, 905-330, 905-360, 962-205, 970-323, 976-605 | Lease Term; Ordinary Course of Business; Private Company |
2021
2021 Maintenance Updates
Maintenance Updates provide nonsubstantive corrections to the Codification, such as editorial corrections, various types of link-related changes, and changes to source fragment information (used for Cross Reference and the Printer-Friendly with Sources). On occasion, a maintenance update may include nonsubstantive corrections which are reflected in the relevant Status tables.
| Date | Maintenance Update | Affected Topics/Subtopics | Affected Glossary Terms |
| 11/15/2021 | 2021-12 (PDF) | 260-10, 350-20, 820-10, 860-50, 958-325 | N/A |
| 10/26/2021 | 2021-11 (PDF) | N/A | N/A |
| 10/25/2021 | 2021-10 (PDF) | N/A | N/A |
| 08/20/2021 | 2021-09 (PDF) | 230-10, 420-10, 805-50, 815-10, 860-10, 954-210, and relevant Status tables | None |
| 08/19/2021 | 2021-08 (roll-off) (PDF) | Various (See Release Notes) | Various (See Release Notes) |
| 06/04/2021 | 2021-07 (PDF) | N/A | N/A |
| 05/06/2021 | 2021-06 (PDF) | 235-10, 270-10, 944-210 | N/A |
| 03/31/2021 | 2021-05 (PDF) | 350-20 | N/A |
| 03/08/2021 | 2021-04 (PDF) | 321-10, 350-20, 944-40, 958-605 | N/A |
| 02/05/2021 | 2021-03 (PDF) | N/A | N/A |
| 01/19/2021 | 2021-02 (PDF) | 606-10, 610-20, 820-10, 942-825, 954-10, 958-10, 970-323, and relevant Status tables | None |
| 01/11/2021 | 2021-01 (PDF) | 932-10 and relevant Status table | None |
2020
2020 Maintenance Updates
Maintenance Updates provide nonsubstantive corrections to the Codification, such as editorial corrections, various types of link-related changes, and changes to source fragment information (used for Cross Reference and the Printer-Friendly with Sources). On occasion, a maintenance update may include nonsubstantive corrections which are reflected in the relevant Status tables.
| Date | Maintenance Update | Affected Topics/Subtopics | Affected Glossary Terms |
| 11/25/2020 | 2020-18 (PDF) | 220-20, 255-10, 260-10, 272-10, 323-10, 326-30, 605-50, 705-20, 720-20, 810-10, 815-10, 815-15, 815-40, 830-20, 852-10, 860-50, 905-10, 958-30, 958-210, 958-310, 958-720, 958-805, and relevant Status tables | Anticipated Transactions, Cease-Use Date, Cost-Compensation Approach, Derivative Financial Instruments and Derivative Commodity Instruments, Vested Shares |
| 11/06/2020 | 2020-17 (PDF) | Various (see Release Notes) | None |
| 11/02/2020 | 2020-16 (PDF) | 958-720 | Plan Assets |
| 10/08/2020 | 2020-15 (PDF) | Various (see Release Notes) | None |
| 10/01/2020 | 2020-14 (PDF) | 210-10, 360-10 | None |
| 09/08/2020 | 2020-13 (PDF) | 260-10, 924-605, 954-320 | None |
| 08/14/2020 | 2020-12 (PDF) | 932-10, 932-360, 946-10, 946-225, 948-310, 958-205, 958-321 | None |
| 08/12/2020 | 2020-11(roll-off) (PDF) | Various (see Release Notes) | Equity Security (definitions 1 and 2) |
| 07/20/2020 | 2020-10(roll-off) (PDF) | 220-10, 230-10, 330-10, 405-20, 715-20, 715-30, 715-60, 740-10, 805-10, 810-10, 830-230, 853-10, 958-205, 958-220, 958-715, 958-805, 960-30, 960-205, 960-325, 962-10, 962-205, 962-325, 965-205, 965-325, 980-715, 995-740 | Business, Net Periodic Pension Cost, Temporary Difference |
| 07/13/2020 | 2020-09 (PDF) | None | None |
| 07/10/2020 | 2020-08 (PDF) | 470-40 | None |
| 06/05/2020 | 2020-07 (PDF) | Various (see Release Notes) | None |
| 06/04/2020 | 2020-06 (PDF) | Various (see Release Notes) | None |
| 05/05/2020 | 2020-05 (PDF) | None | None |
| 04/01/2020 | 2020-04 (PDF) | 260-10, 326-20, 350-20, 470-20, 470-50, 606-10, 958-10 | None |
| 02/24/2020 | 2020-03 (PDF) | Various (see Release Notes) | Credit Derivative |
| 02/19/2020 | 2020-02 (PDF) | 220-10, 250-10, 260-10, 310-10, 320-10, 340-10, 470-50, 480-10, 605-10, 605-15, 606-10, 718-10, 740-10, 845-10, 855-10, 932-10, 932-360, 942-10, 942-310, 944-20, 946-320, 980-10, 980-360, 980-410 | None |
| 01/07/2020 | 2020-01 (PDF) | None | Nonperformance Risk |
2019
2019 Maintenance Updates
Maintenance Updates provide nonsubstantive corrections to the Codification, such as editorial corrections, various types of link-related changes, and changes to source fragment information (used for Cross Reference and the Printer-Friendly with Sources). On occasion, a maintenance update may include nonsubstantive corrections which are reflected in the relevant Status tables.
| Date | Maintenance Update | Affected Topics/Subtopics | Affected Glossary Terms |
| 12/02/2019 | 2019-13 (PDF) | 718-10, 815-30, 946-720, 965-205 | N/A |
| 11/27/2019 | 2019-12 (PDF) | N/A | N/A |
| 11/21/2019 | 2019-11 (PDF) | Various (see Release Notes) | N/A |
| 11/21/2019 | 2019-10 (PDF) | Various (see Release Notes) | N/A |
| 10/11/2019 | 2019-09 (PDF) | 805-20, 852-10 | N/A |
| 09/06/2019 | 2019-08 (PDF) | N/A | N/A |
| 08/07/2019 | 2019-07 (PDF) | 260-10, 321-10, 470-20, 606-10, 810-10, 815-40, 855-10, 958-10, 958-220 | None |
| 07/17/2019 | 2019-06 (roll-off) (PDF) | 230-10, 260-10, 323-10, 350-40, 718-10, 718-20, 718-30, 718-40, 718-740, 740-10, 740-20, 740-270, 805-30, 805-740, 810-10, 815-10, 815-15, 815-20, 815-25, 815-30, 825-10, 954-205, 954-210, 954-220, 954-320, 954-805, 958-20, 958-30, 958-205, 958-210, 958-220, 958-310, 958-320, 958-325, 958-360, 958-405, 958-605, 958-715, 958-720, 958-805, 958-810 | Various (see Release Notes) |
| 06/07/2019 | 2019-05 (PDF) | 825-10, 946-10 | N/A |
| 05/02/2019 | 2019-04 (PDF) | 280-10, 326-20, 470-20, 740-270, 805-30, 805-50, 815-10, 815-20, 830-20, 958-605, 985-350 | N/A |
| 04/25/2019 | 2019-03 (PDF) | N/A | N/A |
| 02/04/2019 | 2019-02 (PDF) | 835-30, 842-10, 958-205 | ADC Arrangements |
| 01/08/2019 | 2019-01 (PDF) | 910-10, 910-20, 910-235, 910-310, 910-330, 910-360, and relevant Status tables | None |
2018
2018 Maintenance Updates
Maintenance Updates provide nonsubstantive corrections to the Codification, such as editorial corrections, various types of link-related changes, and changes to source fragment information (used for Cross Reference and the Printer-Friendly with Sources). On occasion, a maintenance update may include nonsubstantive corrections which are reflected in the relevant Status tables.
| Date | Maintenance Update | Affected Topics/Subtopics | Affected Glossary Terms |
| 12/05/2018 | 2018-18 (PDF) | 326-20, 350-20, 350-40, 910-10, 926-20, 944-210 | None |
| 11/08/2018 | 2018-17 (PDF) | 320-10, 321-10, 815-20 | None |
| 11/02/2018 | 2018-16 (PDF) | N/A | N/A |
| 10/29/2018 | 2018-15 (PDF) | N/A | N/A |
| 10/01/2018 | 2018-14 (PDF) | 323-10, 810-10, 910-310, 952-810 | None |
| 09/10/2018 | 2018-13 (PDF) | 718-10, 820-10, 842-10 | Probable |
| 09/10/2018 | 2018-12 (PDF) | 220-10, 420-10, 480-10, 715-20, 718-20, 810-10, 825-10, 830-30, 830-230, 912-310, 946-205, 946-210, 946-220, 958-205, 958-325, 958-720, 985-10, and relevant Status tables | Affiliate |
| 07/31/2018 | 2018-11 (PDF) | 320-10, 480-10, 805-740, 815-15, 842-30 | N/A |
| 07/18/2018 | 2018-10 (PDF) | N/A | N/A |
| 07/12/2018 | 2018-09 (PDF) | 820-10 and relevant Status table | None |
| 07/03/2018 | 2018-08 (PDF) | 715-20, 718-10, 718-20, 830-10, 958-805, 958-810 | Contract; Contract Asset; Purchased Financial Assets with Credit Deterioration |
| 06/20/2018 | 2018-07(roll-off) (PDF) | 205-40, 230-10, 270-10, 275-10, 310-40, 323-10, 330-10, 360-10, 360-20, 405-40, 705-10, 712-10, 715-10, 715-20, 715-30, 715-60, 805-10, 805-20, 810-10, 810-20, 810-30, 815-10, 815-15, 820-10, 830-10, 860-20, 860-50, 905-330, 905-360, 905-405, 944-40, 952-10, 952-810, 954-810, 958-805, 958-810, 970-323, 970-810 | Various (see Release Notes) |
| 06/01/2018 | 2018-06 (PDF) | 815-20, 958-720 | Collections |
| 04/02/2018 | 2018-05 (PDF) | 220-20, 325-30, 350-30, 718-10, 740-10, 805-10, 805-740, 810-10, 815-15, 825-10, 958-30, 958-720 | Infrequency of Occurrence; Unusual Nature |
| 03/05/2018 | 2018-04 (PDF) | 321-10 | None |
| 02/13/2018 | 2018-03 (PDF) | 210-20, 305-10, 350-30, 350-50, 815-10, 842-10, 942-210, 942-220, 942-305, 946-210, 946-305, 954-210, 954-305 | None |
| 02/02/2018 | 2018-02 (PDF) | 275-10, 321-10, 325-30, 410-20, 450-20, 805-10, 810-10, 842-10, 860-10, 860-50, 942-405, 958-205, 958-321, 958-805, and relevant Status tables | Primary Beneficiary |
| 01/04/2018 | 2018-01 (PDF) | 210-10, 220-10, 250-10, 270-10, 280-10, 310-40, 323-10, 323-740, 470-10, 830-30, 852-10, 860-10, 942-220, 944-220, 946-220, 980-10 | None |
2017
2017 Maintenance Updates
Maintenance Updates provide nonsubstantive corrections to the Codification, such as editorial corrections, various types of link-related changes, and changes to source fragment information (used for Cross Reference and the Printer-Friendly with Sources). On occasion, a maintenance update may include nonsubstantive corrections which are reflected in the relevant Status tables.
| Date | Maintenance Update | Affected Topics/Subtopics | Affected Glossary Terms |
| 12/22/2017 | 2017-21 (PDF) | 210-20, 305-10, 942-210, 942-305, 946-210, 946-305, 954-210, 954-305, and relevant Status tables | Cash, Cash Equivalents, Donor-Imposed Restriction |
| 11/30/2017 | 2017-20 (PDF) | 210-10, 250-10, 260-10, 270-10, 280-10, 320-10, 420-10, 450-30, 460-10, 470-10, 605-35, 715-60, 718-10, 840-40, 912-20, 912-605, 940-325, 954-10, 954-205, 954-310, 954-320, 954-815, 958-20, 958-30, 958-205, 958-320, 958-321, 958-325, 958-360, 958-605, 958-715, 958-720, 958-810, 980-10, 980-360 | None |
| 11/15/2017 | 2017-19 (PDF) | 220-10, 220-20, 220-30, 225-10, 225-20, 225-30, 470-60, 505-30, 605-40, 610-30, 830-30, 852-10, 912-220, 912-225, 932-220, 932-225, 942-220, 942-225, 944-220, 944-225, 944-360, 946-220, 946-225, 954-220, 954-225, 958-220, 958-225, 980-20, and relevant Status tables | Various (see Release Notes) |
| 10/27/2017 | 2017-18 (PDF) | 860-10, 930-810, 952-10 | None |
| 10/26/2017 | 2017-17(roll-off) (PDF) | 310-10, 310-40, 323-740, 350-40, 835-30 | None |
| 10/05/2017 | 2017-16 (PDF) | 323-10, 470-50, 830-10, 860-10, 860-50 | None |
| 09/25/2017 | 2017-15 (PDF) | None | None |
| 09/13/2017 | 2017-14 (PDF) | 815-20, and relevant Status table | None |
| 09/06/2017 | 2017-13 (PDF) | 250-10, 606-10, 715-20, 815-20, 815-25, 815-30, 946-225 | None |
| 08/28/2017 | 2017-12 (PDF) | 815-20 | None |
| 07/28/2017 | 2017-11 (PDF) | 323-10, 470-20, 810-10, 932-810, 944-605, 958-605, 958-810 | None |
| 07/05/2017 | 2017-10(roll-off) (PDF) | 105-10, 205-10, 205-20, 220-10, 225-10, 225-20, 225-30, 230-10, 250-10, 260-10, 270-10, 274-10, 280-10, 310-10, 320-10, 323-10, 325-40, 360-10, 410-30, 420-10, 470-20, 470-30, 470-50, 505-60, 715-20, 715-30, 718-10, 718-40, 718-740, 740-10, 740-20, 740-30, 740-270, 810-10, 815-10, 815-30, 820-10, 825-10, 830-10, 830-20, 830-30, 852-10, 860-10, 860-20, 860-30, 930-715, 942-740, 944-30, 944-740, 944-805, 954-225, 958-205, 958-225, 958-810, 960-30, 960-325, 962-10, 962-205, 962-325, 965-20, 965-205, 965-325, 980-20, 980-605 | Various (see Release Notes) |
| 05/30/2017 | 2017-09 (PDF) | 850-10, 952-10, 952-440, 952-720, and relevant Status tables | None |
| 05/01/2017 | 2017-08 (PDF) | 606-10, and relevant Status table | None |
| 04/28/2017 | 2017-07 (PDF) | 274-10, 815-20, 958-605 | None |
| 04/07/2017 | 2017-06 (PDF) | 105-10, 205-20, 230-10, 270-10, 310-10, 310-40, 321-10, 323-10, 323-740, 326-10, 326-20, 330-10, 340-40, 350-20, 350-40, 360-10, 470-20, 606-10, 715-20, 718-10, 718-40, 740-10, 805-10, 805-740, 810-10, 815-15, 815-20, 820-10, 825-10, 835-30, 842-10, 860-10, 942-230, 944-40, 948-10, 948-720, 958-205, 958-225, 958-810, and relevant Status tables | Permanent Investor, Public Business Entity |
| 03/31/2017 | 2017-05 (PDF) | 323-10, 610-20, 805-30, 958-605, 958-715 | None |
| 03/06/2017 | 2017-04 (PDF) | 350-20 and relevant Status table | None |
| 03/03/2017 | 2017-03 (PDF) | 323-740, 606-10, 805-740, 808-10, 810-10, 815-20, 840-10, 840-40, 912-450, 912-605, 958-605, 958-720, 974-840, 985-605 | Various (see Release Notes) |
| 01/31/2017 | 2017-02 (PDF) | 260-10, 480-10, 505-50, 718-10, 718-20, 815-10, 835-20, 924-10, 954-10, 960-205 | None |
| 01/03/2017 | 2017-01 (PDF) | 280-10, 350-20, 470-10, 715-60, 718-20, 805-10, 820-10, 852-10, 958-205, 980-715 | None |
2016
2016 Maintenance Updates
Maintenance Updates provide nonsubstantive corrections to the Codification, such as editorial corrections, various types of link-related changes, and changes to source fragment information (used for Cross Reference and the Printer-Friendly with Sources). On occasion, a maintenance update may include nonsubstantive corrections which are reflected in the relevant Status tables.
| Date | Maintenance Update | Affected Topics/Subtopics | Affected Glossary Terms |
| 11/30/2016 | 2016-20 (PDF) | 323-10, 326-30, 470-10, 718-20, 853-10, 915-10, 970-323, 980-715 | None |
| 11/03/2016 | 2016-19 (PDF) | 260-10, 350-20, 718-10 | None |
| 10/14/2016 | 2016-18 (PDF) | 105-10, 205-20, 310-30, 321-10, 606-10, 718-10, 718-20, 740-10, 810-10, 815-30, 825-10, 932-360, 944-20, 944-30, 944-40 | None |
| 09/02/2016 | 2016-17 (PDF) | 205-30, 360-20, and relevant Status tables | None |
| 08/31/2016 | 2016-16 (PDF) | 260-10, 326-10, 470-10, 718-10, 718-20, 718-30, 740-10, 805-20, 815-10, 815-20, 815-30, 944-30, 958-210 | Debt Security, Term Endowment |
| 08/11/2016 | 2016-15 (PDF) | None | None |
| 07/29/2016 | 2016-14 (PDF) | All XBRL Sections (Section 75) | None |
| 07/08/2016 | 2016-13 (PDF) | 310-10, 310-40, 740-10, 810-10, 815-20, 815-30, 944-20, 944-30, 954-225 | None |
| 07/08/2016 | 2016-12(roll-off) (PDF) | 220-10, 405-40, 805-10, 810-10, 830-30 | None |
| 06/27/2016 | 2016-11 (PDF) | 205-20, 205-40, 220-10, 235-10, 310-20, 340-20, 360-20, 470-10, 505-10, 715-30, 805-10, 805-20, 810-10, 815-10, 840-10, 840-20, 840-30, 852-10, 860-20, 860-30, 912-275, 912-310, 912-405, 942-505, 944-605, 944-805, 946-210, 958-205, 962-205, 962-325, 965-205, 980-20, 980-840, and relevant Status tables | Public Business Entity |
| 06/23/2016 | 2016-10(roll-off) (PDF) | 210-20, 230-10, 270-10, 275-10, 310-10, 310-40, 340-10, 360-10, 720-10, 835-20, 740-10, 840-10, 853-10, 915-10, 915-205, 915-210, 915-215, 915-225, 915-230, 915-235, 915-340, 915-605, 915-810, 980-10 | None |
| 06/10/2016 | 2016-09 (PDF) | 610-20, 718-20, 740-10, 815-25, 840-20, 842-10, 958-205, 958-360, 958-605 | Lease Incentive |
| 05/11/2016 | 2016-08 (PDF) | All Glossary Sections (Section 20) | None |
| 04/29/2016 | 2016-07 (PDF) | 230-10, 606-10, 926-20, 944-40, 946-210 | None |
| 04/22/2016 | 2016-06 (PDF) | 205-20, 205-40, 210-20, 220-10, 255-10, 260-10, 310-20, 310-30, 323-740, 340-30, 350-20, 350-40, 480-10, 606-10, 715-20, 718-20, 810-10, 815-30, 815-45, 840-10, 840-40, 944-30, 944-505, 946-10, 946-320, 958-30, 958-605, 965-205, 970-10, 970-323, 970-360, 970-605, 974-323, 974-840, 976-605, 980-340 | Preferred Stock Subject to Mandatory Redemption Requirements or Whose Redemption is Outside the Control of the Issuer, Preferred Stocks Which Are Not Redeemable or Are Redeemable Solely at the Option of the Issuer |
| 04/12/2016 | 2016-05 (PDF) | 275-10, 470-20, 805-10, 810-10, 845-10, 860-20, 946-205, 958-205, 958-320, 980-10, and relevant Status tables | None |
| 04/07/2016 | 2016-04 (PDF) | 270-10, 320-10, 350-20, 460-10, 470-10, 470-20, 610-20, 715-20, 815-20, 942-230, 944-605, 958-320 | None |
| 03/02/2016 | 2016-03 (PDF) | 205-40, 320-10, 718-10, 815-25, 815-30, 842-10, 860-10, 926-855 | None |
| 01/08/2016 | 2016-02 (PDF) | 320-10, 323-10, 470-20, 815-20, 825-10 | None |
| 01/05/2016 | 2016-01(roll-off) (PDF) | 205-10, 205-30, 852-10, 942-810, 954-10, 954-225, 958-605, 958-720, 960-40, 962-40, 965-40 | Liquidation, Statement of Changes in Net Assets in Liquidation, Statement of Net Assets in Liquidation |
2015
2015 Maintenance Updates
Maintenance Updates provide nonsubstantive corrections to the Codification, such as editorial corrections, various types of link-related changes, and changes to source fragment information (used for Cross Reference and the Printer-Friendly with Sources). On occasion, a maintenance update may include nonsubstantive corrections which are reflected in the relevant Status tables.
| Date | Maintenance Update | Affected Topics/Subtopics | Affected Glossary Terms |
| 11/06/2015 | 2015-18 (PDF) | 325-30, 440-10, 460-10, 715-20, 815-20, 825-10, 960-30, 960-205, 962-325 | None |
| 10/01/2015 | 2015-17 (PDF) | 505-50, 958-605 | None |
| 09/02/2015 | 2015-16 (PDF) | 320-10, 805-20, 810-10, 820-10, 942-210 | None |
| 08/12/2015 | 2015-15 (PDF) | Various (See Release Notes) | None |
| 08/07/2015 | 2015-14 (PDF) | 230-10, 255-10, 310-10, 320-10, 325-30, 718-10, 718-740, 805-50, 810-10, 815-10, 825-10, 840-10, 932-360 | Take-or-Pay Contracts |
| 07/02/2015 | 2015-13 (PDF) | 230-10, 310-10, 350-20, 715-60, 718-740, 815-20, 820-10 | None |
| 06/26/2015 | 2015-12(roll-off) (PDF) | 105-10, 220-10, 230-10, 270-10, 323-10, 340-10, 350-30, 360-20, 805-50, 810-10, 815-40, 820-10, 855-10, 926-20, 926-855, 946-10, 946-20, 946-320, 946-323, 946-325, 946-810, 954-430, 962-325, 965-20, 965-205, 965-320, 965-325, 965-360 | Investment Company, Pushdown Accounting |
| 06/19/2015 | 2015-11 (PDF) | 310-10, 320-10, 323-10, 460-10, 470-40, 740-10, 820-10, 840-10, 860-30, 958-320, 958-720, 965-205, and relevant Status tables | None |
| 06/16/2015 | 2015-10 (PDF) | 944-40 | None |
| 06/05/2015 | 2015-09 (PDF) | 715-20, 718-20, 740-20, 810-10, 958-225 | None |
| 05/28/2015 | 2015-08 (PDF) | Various (See Release Notes) | None |
| 05/01/2015 | 2015-07 (PDF) | 718-20, 805-10, 958-210, 958-715 | None |
| 04/07/2015 | 2015-06 (PDF) | 325-30, 606-10, 810-10, 860-10, 954-210, 958-20, 958-320 | None |
| 03/20/2015 | 2015-05 (PDF) | 325-30, 505-30, 606-10, 718-40, 810-10, 840-10, 958-20, 958-30, 958-210, 958-360, 958-605 | None |
| 03/13/2015 | 2015-04 (PDF) | Various (See Release Notes) | None |
| 02/09/2015 | 2015-03 (PDF) | 225-10 | None |
| 02/05/2015 | 2015-02 (PDF) | 815-10, 815-20, 845-10, 932-605, 946-210, 954-305 | Exchange |
| 01/07/2015 | 2015-01 (PDF) | 605-50 | None |
2014
2014 Maintenance Updates
Maintenance Updates provide nonsubstantive corrections to the Codification, such as editorial corrections, various types of link-related changes, and changes to source fragment information (used for Cross Reference and the Printer-Friendly with Sources). On occasion, a maintenance update may include nonsubstantive corrections which are reflected in the relevant Status tables.
| Date | Maintenance Update | Affected Topics/Subtopics | Affected Glossary Terms |
| 12/17/2014 | 2014-26(roll-off) (PDF) | 230-10, 958-230 | None |
| 12/05/2014 | 2014-25 (PDF) | 280-10, 715-20, 946-10, 946-210 | None |
| 11/18/2014 | 2014-24 (PDF) | 805-50 | None |
| 11/03/2014 | 2014-23 (PDF) | 715-20 and relevant Status table | None |
| 10/31/2014 | 2014-22 (PDF) | 350-10, 810-10, 860-30 | None |
| 10/03/2014 | 2014-21 (PDF) | 310-30, 310-40, 325-40, 805-10, 805-20, 958-320, 958-605 | None |
| 09/29/2014 | 2014-20 (PDF) | 105-10, 220-10, 230-10, 250-10, 280-10, 350-10, 360-20, 405-10, 405-40, 440-10, 460-10, 470-40, 715-20, 805-10, 810-10, 815-10, 815-15, 815-20, 815-25, 815-35, 820-10, 830-30, 860-10, 860-50, 932-360, 954-430, 954-605, 954-805, 954-815, 958-805, 972-360, and relevant Status tables | Various (see Release Notes) |
| 09/05/2014 | 2014-19 (PDF) | 718-10, 830-10, 860-30 | None |
| 08/01/2014 | 2014-18 (PDF) | 860-10, 944-605, 960-325 | None |
| 07/16/2014 | 2014-17 (PDF) | None | None |
| 07/02/2014 | 2014-16(roll-off) (PDF) | 210-20, 270-10, 405-30, 720-50, 805-20, 815-10, 815-20 | Fed Funds Effective Swap Rate (or Overnight Index Swap Rate) |
| 06/30/2014 | 2014-15 (PDF) | 325-30, 730-20, 815-10, 815-20, 815-25, 815-30, 830-10, 860-20, 932-10, 942-10, 942-405, 942-720 | Comprehensive Income, Net Income, Other Comprehensive Income |
| 06/06/2014 | 2014-14 (PDF) | 220-10, 360-10, 470-20, 505-50, 606-10, 715-60, 815-40, 835-30, 860-10, 946-605, 978-310 | None |
| 05/29/2014 | 2014-13 (PDF) | 606-10 | None |
| 05/27/2014 | 2014-12 (PDF) | 840-20 | None |
| 05/19/2014 | 2014-11 (PDF) | None | None |
| 04/14/2014 | 2014-10 (PDF) | 210-20, 860-30 | None |
| 03/31/2014 | 2014-09 (PDF) | 715-30, 815-15, 958-205 | Various (see Release Notes) |
| 03/26/2014 | 2014-08 (PDF) | 944-325, 944-405, 944-470, 944-805, 946-10, 946-20, 946-605, 946-830, 954-450, 954-720, 958-205, 958-210, 958-320, 958-325, 958-720, 960-10, 960-20, 960-30, 960-40, 960-205, 960-310, 960-325, 960-360, 962-10, 962-40, 962-205, 962-325, 965-10, 965-20, 965-30, 965-40, 965-205, 965-310, 965-325, 965-360, 970-340, 970-360, 972-10, 976-10, 978-10, 978-230, 978-310, 978-330, 978-340, 978-605, 978-720, 978-810, 978-840, 980-715 | None |
| 03/17/2014 | 2014-07 (PDF) | 325-30, 730-20, 815-10, 815-20, 815-25, 815-30, 830-10, 860-20, 932-10, 942-10, 942-405, 942-720, and relevant Status tables | Various (see Release Notes) |
| 03/14/2014 | 2014-06 (PDF) | None | None |
| 03/07/2014 | 2014-05 (PDF) | 205-20, 280-10, 360-10, 845-10, 926-20, 940-10, 946-320, 978-330 | None |
| 02/20/2014 | 2014-04 (PDF) | All Sections 75 (XBRL Elements) | None |
| 01/31/2014 | 2014-03 (PDF) | 310-40, 323-10, 323-740, 350-20, 715-60, 960-30, 965-30 | None |
| 01/21/2014 | 2014-02 (PDF) | 323-740 | None |
| 01/06/2014 | 2014-01 (PDF) | 323-10, 972-740 | None |
2013
2013 Maintenance Updates
Maintenance Updates provide nonsubstantive corrections to the Codification, such as editorial corrections, various types of link-related changes, and changes to source fragment information (used for Cross Reference and the Printer-Friendly with Sources).
| Date | Maintenance Update | Affected Topics/Subtopics | Affected Glossary Terms |
| 12/06/2013 | 2013-16 (PDF) | 340-10, 340-20, 460-10, 470-40, 505-10, 815-10, 840-30, 905-205, 905-325, 905-405, 905-505, 905-605, 910-10, 946-605, 965-205 | None |
| 10/31/2013 | 2013-15 (PDF) | 210-20, 860-10, 980-605 | None |
| 09/04/2013 | 2013-14 (PDF) | 954-225 | None |
| 07/31/2013 | 2013-13 (PDF) | 255-10, 360-20, 410-30, 805-20, 810-10, 815-10, 815-15, 820-10, 860-10 | None |
| 07/18/2013 | 2013-12 (PDF) | None | None |
| 07/09/2013 | 2013-11 (PDF) | 815-10, 820-10 | None |
| 07/01/2013 | 2013-10 (PDF) | 210-20, 220-10, 350-10, 820-10, 840-30, 860-10, 944-10 | None |
| 06/25/2013 | 2013-09 (PDF) | 205-20, 225-20, 323-30, 325-30, 470-60, 480-10, 718-740, 720-20, 815-25, 820-10, 908-360, 942-505, 944-50, 944-310, 960-10, 962-10, 965-10, 974-810, 980-10, 980-715 | None |
| 06/17/2013 | 2013-08(roll-off) (PDF) | 205-10, 220-10, 270-10, 310-10, 310-40, 323-10, 350-20, 505-10, 715-20, 715-30, 715-80, 805-10, 805-20, 810-10, 815-20, 815-30, 820-10, 825-10, 860-10, 926-605, 944-30, 944-720, 954-310, 954-605, 954-815, 958-30, 958-310, 958-605, 958-805 | Various (see Release Notes) |
| 05/31/2013 | 2013-07 (PDF) | 340-30, 410-30, 715-60, 815-40, 825-10 | None |
| 05/03/2013 | 2013-06A (PDF) | None | None |
| 05/03/2013 | 2013-06 (PDF) | 205-10, 255-10, 323-10, 460-10, 715-60, 720-20, 815-10, 815-15, 825-10, 840-30, 840-40, 926-20, 940, 942-505, 946-320, 962-325 | None |
| 03/29/2013 | 2013-05 (PDF) | 270-10, 310-10, 310-20, 815-15, 946-320 | None |
| 03/01/2013 | 2013-04 (PDF) | 255-10, 270-10, 310-10, 330-10, 360-20, 460-10, 470-20, 715-80, 740-270, 805-20, 810-10, 815-15, 820-10, 978-605 | Reacquisition Price of Debt |
| 02/15/2013 | 2013-03 (PDF) | 210-20, 220-10, 410-20, 715-20, 805-740, 820-10, 830-230, 835-30, 860-20, 942-230, 944-30, 944-40, 944-805, 985-605 | None |
| 02/01/2013 | 2013-02 (PDF) | 360-20, 410-20, 715-20, 805-40, 805-740, 820-10, 830-230, 835-30, 860-10, 860-20, 942-230, 944-30, 944-805, 946-320, 985-605 | None |
| 01/09/2013 | 2013-01 (PDF) | 715-30, 715-60, 805-40, 805-740, 810-10, 810-30, 815-10, 815-15, 815-20, 815-25, 815-30, 820-10, 825-10, 852-10, 932-235, 944-235, 944-310, 944-605, 944-805, 946-20, 946-235, 958-30, 958-205, 958-225, 958-360, 958-605, 958-715, 958-810, 965-205, 978-605, 980-715, 980-740, 985-605, 985-845 | Various (see Release Notes) |
2012
2012 Maintenance Updates
Maintenance Updates provide nonsubstantive corrections to the Codification, such as editorial corrections, various types of link-related changes, and changes to source fragment information (used for Cross Reference and the Printer-Friendly with Sources).
| Date | Maintenance Update | Affected Topics/Subtopics | Affected Glossary Terms |
| 12/11/2012 | 2012-15 (PDF) | 255-10, 260-10, 274-10, 310-10, 310-30, 325-30, 340-20, 340-30, 360-20, 440-10, 505-60, 605-15, 715-20, 715-30, 715-60, 715-80, 718-10, 718-20, 718-40, 718-50, 720-20, 740-10, 740-20, 740-270, 805-20, 820-10, 926-20 | None |
| 11/07/2012 | 2012-14 (PDF) | 105-10, 310-40, 720-20, 810-10, 815-10, 820-10, 825-20, 835-20 | Nongovernmental Entity, Nonpublic Entity (1st definition) |
| 10/03/2012 | 2012-13 (PDF) | 225-10, 350-20, 605-15, 730-20, 970-720 | None |
| 09/04/2012 | 2012-12 (PDF) | 310-30, 360-20, 740-10, 954-605 | None |
| 08/17/2012 | 2012-11 (PDF) | 310-10, 310-20, 310-30, 350-20, 360-20, 410-20, 470-20 | None |
| 08/09/2012 | 2012-10 (PDF) | 205-10, 220-10, 255-10, 260-10, 825-10, 830-230, 835-20, 840-30, 852-10, 958-205, 960-205 | None |
| 08/03/2012 | 2012-09 (PDF) | 320-10, 815-10, 815-40 | None |
| 06/29/2012 | 2012-08 (PDF) | 310-10, 350-30, 470-20, 815-15, 820-10, 946-205, 946-210, 958-605, 958-720, 958-805, 962-310 | None |
| 06/18/2012 | 2012-07(roll-off) (PDF) | 270-10, 310-10, 310-40, 450-20, 715-20, 718-10, 805-10, 820-10, 840-30, 924-605, 944-80, 954-450, 954-605, 954-720, 958-805 | Various (see Release Notes) |
| 05/31/2012 | 2012-06 (PDF) | 810-10, 860-10, 860-20, 944-825 | None |
| 05/01/2012 | 2012-05 (PDF) | 210-20, 470-10, 605-45, 825-10, 958-230, 958-720 | Lock-Box Arrangement |
| 03/30/2012 | 2012-04 (PDF) | 323-10, 340-10, 470-10, 815-30 | None |
| 02/01/2012 | 2012-03 (PDF) | 605-20, 805-30, 810-10, 860-10, 860-40, 958-205, 985-605 | None |
| 01/30/2012 | 2012-02 (PDF) | None | None |
| 01/09/2012 | 2012-01 (PDF) | 210-20, 605-20, 605-35, 605-45, 605-50, 715-20, 715-30, 715-60, 718-30, 720-20, 730-20, 740-10, 805-10, 805-20, 840-40, 905-360, 908-350, 908-360, 912-405, 912-605, 926-10, 926-20, 926-430, 932-10, 946-10, 952-10, 954-430, 958-605, 958-720, 970-605 | Various (see Release Notes) |
2011
2011 Maintenance Updates
Maintenance Updates provide nonsubstantive corrections to the Codification, such as editorial corrections, various types of link-related changes, and changes to source fragment information (used for Cross Reference and the Printer-Friendly with Sources).
| Date | Maintenance Update | Affected Topics/Subtopics | Affected Glossary Terms |
| 12/13/2011 | 2011-20(roll-off) (PDF) | 605-10, 605-25, 605-28, 985-605 | Milestone |
| 12/02/2011 | 2011-19 (PDF) | 205-10, 205-20, 220-10, 250-10, 255-10, 260-10, 270-10, 274-10, 275-10, 280-10, 310-10, 310-20, 320-10, 323-10, 325-40, 330-10, 340-20, 350-10, 350-20, 350-30, 350-50, 360-10, 360-20, 410-30, 420-10, 440-10, 460-10, 470-10, 505-50, 718-10, 740-20, 740-270, 805-20, 810-10, 810-20, 810-30, 815-10, 860-20, 860-30, 905-605, 932-235, 954-225, 954-440, 954-470 | Related Parties |
| 11/16/2011 | 2011-18 (PDF) | Various | Various (see Release Notes) |
| 11/14/2011 | 2011-17 (PDF) | Various | Various (see Release Notes) |
| 11/01/2011 | 2011-16 (PDF) | 220-10, 325-20, 715-80, 720-20, 810-10, 815-10, 820-10, 860-20, 946-10, 958-20 | N/A |
| 10/03/2011 | 2011-15 (PDF) | 480-10, 840-10, 845-10, 946-10, 958-205, 958-310, 962-205 | N/A |
| 9/12/2011 | 2011-14 (PDF) | Various | N/A |
| 9/01/2011 | 2011-13 (PDF) | 360-20, 715-20, 805-50, 815-20, 860-20, 944-30, 954-815 | N/A |
| 8/01/2011 | 2011-12 (PDF) | 715-20, 720-25, 805-10, 820-10, 840-40, 860-10, 944-20 | Various (see Release Notes) |
| 7/14/2011 | 2011-11(roll-off) (PDF) | 720-50, 932-10, 932-235, 932-360, 962-310, 962-325 | Various (see Release Notes) |
| 6/30/2011 | 2011-10 (PDF) | 220-10, 310-10, 360-10, 470-10, 810-10, 860-10, 860-50, 942-505, 954-815 | N/A |
| 6/20/2011 | 2011-09(roll-off) (PDF) | 260-10, 270-10, 323-10, 350-10, 350-20, 350-30, 420-10, 460-10, 470-20, 805-10, 805-30, 805-50, 805-740, 810-10, 815-15, 815-20, 820-10, 830-10, 840-10, 840-30, 845-10, 954-10, 954-225, 954-805, 958-10, 958-805 | Various (see Release Notes) |
| 6/01/2011 | 2011-08 (PDF) | 325-40, 405-20, 410-30, 715-20, 715-30, 715-60, 810-10, 815-20, 820-10, 840-10, 860-10, 958-30, 958-325, 958-720, 958-810 | N/A |
| 5/18/2011 | 2011-07(roll-off) (PDF) | 310-10, 310-30, 310-40, 320-10, 325-40, 405-20, 460-10, 470-50, 810-10, 815-20, 820-10, 860-10, 860-20, 860-30, 860-40, 860-50, 948-310 | Various (see Release Notes) |
| 5/02/2011 | 2011-06 (PDF) | 320-10, 715-60, 718-20, 810-20, 815-10, 815-15, 840-20, 840-30, 860-10, 942-505, 946-205, 970-323, 978-720 | Fully Eligible Plan Participants |
| 4/15/2011 | 2011-05 (PDF) | Various | N/A |
| 3/31/2011 | 2011-04 (PDF) | 105-10, 912-210 | N/A |
| 3/15/2011 | 2011-03(roll-off) (PDF) | 310-10, 310-30, 310-40, 815-10, 815-15 | Embedded Credit Derivative |
| 2/28/2011 | 2011-02 (PDF) | 815-40, 820-10, 840-30 | N/A |
| 1/31/2011 | 2011-01 (PDF) | 210-20, 470-20, 815-15, 944-30 | N/A |
2010
2010 Maintenance Updates
Maintenance Updates provide nonsubstantive corrections to the Codification, such as editorial corrections, various types of link-related changes, and changes to source fragment information (used for Cross Reference and the Printer-Friendly with Sources).
| Date | Maintenance Update | Affected Topics/Subtopics | Affected Glossary Terms |
| 12/22/2010 | 2010-24 (PDF) | 350-30 | N/A |
| 12/15/2010 | 2010-23(roll-off) (PDF) | 855-10 | N/A |
| 11/30/2010 | 2010-22 (PDF) | 958-720 | N/A |
| 10/29/2010 | 2010-21 (PDF) | 310-10, 460-10, 605-35, 740-10, 810-10. | N/A |
| 9/21/2010 | 2010-20 (PDF) | Various | N/A |
| 8/30/2010 | 2010-19 (PDF) | 310-10, 310-20, 715-20, 815-30, 845-10, 860-10, 912-605, 942-310, 942-320, 958-30. | N/A |
| 8/17/2010 | 2010-18 (PDF) | None | N/A |
| 7/30/2010 | 2010-17 (PDF) | 220-10, 310-10, 320-10, 350-40, 715-80, 825-10, 942-320, 942-405, 958-30. | Collaborative Arrangement |
| 7/15/2010 | 2010-16(roll-off) (PDF) | None | Various (see Release Notes) |
| 7/06/2010 | 2010-15 (PDF) | None | N/A |
| 7/06/2010 | 2010-14 (PDF) | 210-20, 230-10, 260-10, 310-10, 350-30, 470-20, 605-25, 805-20, 810-10, 815-10, 815-40, 820-10, 825-10, 830-20, 860-10, 860-20, 942-320, 944-80, 954-10, 954-805 | Forecasted Transaction, Present Value |
| 7/01/2010 | 2010-13(roll-off) (PDF) | 220-10, 225-20, 260-10, 275-10, 310-30, 310-40, 323-10, 323-30, 350-10, 350-20, 350-30, 410-30, 420-10, 450-10, 460-10, 470-20, 470-60, 480-10, 505-10, 505-20, 715-20, 718-10, 730-10, 730-20, 740-10, 740-20, 805-10, 805-20, 805-30, 805-40, 805-50, 805-740, 808-10, 810-10, 810-30, 815-10, 815-15, 815-20, 815-40, 820-10, 825-10, 830-20, 830-30, 840-10, 840-30, 845-10, 852-10, 852-740, 942-505, 944-10, 944-20, 944-30, 944-40, 944-50, 944-310, 944-605, 944-805, 954-810, 958-810, 974-810, 985-20 | Various (see Release Notes) |
| 5/27/2010 | 2010-12 (PDF) | 260-10, 810-10, 815-10, 820-10, 860-10, 958-30, 958-360, 958-805 | N/A |
| 5/25/2010 | 2010-11 (PDF) | Various | N/A |
| 5/20/2010 | 2010-10(rolloff) (PDF) | 820-10, 860-10 | Consolidated Affiliate |
| 5/13/2010 | 2010-09 (PDF) | None | N/A |
| 4/30/2010 | 2010-08 (PDF) | 205-20, 230-10, 815-10, 815-15, 815-20, 820-10, 932-10, 944-80, 980-715 | Developed Oil and Gas Reserves, Undeveloped Oil and Gas Reserves |
| 4/13/2010 | 2010-07(rolloff) (PDF) | 220-10, 270-10, 310-30, 320-10, 325-20, 325-40, 360-20, 470-20, 715-30, 715-60, 718-740, 730-20, 815-10, 815-20, 815-25, 815-30, 815-35, 820-10, 825-10, 830-30, 860-10, 942-320, 944-310, 944-325, 944-360, 954-810, 954-815, 958-205, 958-320, 958-715, 958-810, 958-840 | Amortized Cost Basis, Cost Basis, Publicly Traded Company |
| 3/31/2010 | 2010-06 (PDF) | 470-50, 820-10, 954-605, 958-810, 974-10 | N/A |
| 3/23/2010 | 2010-05(rolloff) (PDF) | 310-10, 310-40, 325-40, 360-20, 405-20, 460-10, 470-20, 715-20, 715-30, 715-60, 718-740, 730-10, 730-20, 810-10, 815-10, 815-20, 820-10, 860-10, 860-20, 860-30, 860-50, 958-205, 958-715 | Various (see Release Notes) |
| 3/08/2010 | 2010-04 (PDF) | 860-10, 958-225 | Public Entity, Transferred Financial Assets |
| 2/26/2010 | 2010-03 (PDF) | 310-10, 320-10, 360-20, 470-20, 605-15, 810-10, 815-15, 820-10, 835-20, 908-710, 942-505, 954-805, 958-205 | Trading |
| 1/29/2010 | 2010-02 (PDF) | 210-20, 310-10, 320-10, 810-10, 860-20, 926-605, 958-205, 958-210, 958-225, 958-810 | N/A |
| 1/08/2010 | 2010-01 (PDF) | 323-10, 505-20, 805-10, 810-10, 845-10, 932-10, 932-235 | Various (see Release Notes) |
2009
2009 Maintenance Updates
Maintenance Updates provide nonsubstantive corrections to the Codification, such as editorial corrections, various types of link-related changes, and changes to source fragment information (used for Cross Reference and the Printer-Friendly with Sources).
| Date | Maintenance Update | Affected Topics/Subtopics | Affected Glossary Terms |
| 12/30/2009 | 2009-27 (PDF) | 250-10, 260-10, 460-10, 470-10, 480-10, 605-25, 605-35, 715-20, 805-10, 805-20, 815-10, 820-10, 825-10, 855-10, 860-10, 860-20, 860-40, 860-50, 958-810, 985-605 | Derivative Instrument, Derivative Financial Instrument |
| 11/23/2009 | 2009-26 (PDF) | 220-10, 260-10, 470-20, 980-250 | N/A |
Other codification pages
Notices, archived sections, and other pages referenced from the codification text.
2025
Invitation to Comment 2025-ITC100—Agenda Consultation
The purpose of this Invitation to Comment (ITC) is to solicit broad stakeholder feedback about the future standard-setting agenda of the Financial Accounting Standards Board (FASB).
Issued: January 3, 2025
Comments Due: June 30, 2025
2024
Invitation to Comment 2024-ITC100—Financial Key Performance Indicators for Business Entities
The purpose of the Invitation to Comment (ITC) is to solicit broad stakeholder feedback that will inform the Board as it considers whether to add a project on Financial KPIs to its technical agenda and, if added, to determine the objective and scope of the project.
For more information, see the following:
Issued: November 14, 2024
Comments Due: April 30, 2025
Invitation to Comment 2024-ITC200—Recognition of Intangibles
The purpose of this Invitation to Comment (ITC) is to solicit stakeholder feedback on whether the Board should pursue standard setting on intangibles.
For more information, see the following:
Issued: December 19, 2024
Comments Due: May 30, 2025
2023
Proposed Statement of Financial Accounting Concepts—Concepts Statement 8—Conceptual Framework of Financial Reporting—Chapter 6: Measurement
The Exposure Draft, Conceptual Framework for Financial Reporting: Chapter 6: Measurement, sets forth concepts on how items recognized in financial statements should be measured and provides guidance on when a specific measurement system should be applied.
For more information, see the following:
Issued: December 21, 2023
Comments Due: March 20, 2024
2022
Invitation to Comment 2022-002—Accounting for Government Grants by Business Entities—Potential Incorporation of IAS 20, Accounting for Government Grants and Disclosure of Government Assistance, into Generally Accepted Accounting Principles
The purpose of the Invitation to Comment (ITC) is to solicit broad stakeholder feedback on the recognition, measurement, and presentation requirements of IAS 20, Accounting for Government Grants and Disclosure of Government Assistance. Specifically, the FASB staff would like to understand whether the requirements of IAS 20 as it relates to the accounting for government grants represent a workable solution for improving generally accepted accounting principles (GAAP) in the U.S. financial reporting environment for business entities.
Issued: June 13, 2022
Comments Due: September 12, 2022
Proposed Statement of Financial Accounting Concepts No. 8—Conceptual Framework for Financial Reporting—Chapter 2: The Reporting Entity
The exposure draft, Conceptual Framework for Financial Reporting: Chapter 2: The Reporting Entity, describes a reporting entity and its features.
For more information, see the following:
Issued: October 18, 2022
Comments Due: January 16, 2023
Proposed Statement of Financial Accounting Concepts—Concepts Statement 8—Conceptual Framework of Financial Reporting—Chapter 5: Recognition and Derecognition
The exposure draft, Conceptual Framework for Financial Reporting: Chapter 5: Recognition and Derecognition, sets forth recognition and derecognition criteria and guidance on when an item should be incorporated into and removed from financial statements.
For more information, see the following:
Issued: November 22, 2022
Comments Due: February 20, 2023
2021
Invitation to Comment 2021-004—Agenda Consultation
The purpose of this Invitation to Comment (ITC) is to solicit broad stakeholder feedback about the future standard-setting agenda of the Financial Accounting Standards Board (FASB). The feedback on this ITC is essential in ensuring that the FASB continues to allocate its finite resources to achievable standard-setting projects that fulfill its primary mission of improving financial accounting and reporting standards and addressing topics that are of the highest priority to its stakeholders. The Board will consider the feedback received in response to this ITC before making decisions about potential changes to its agenda. Those decisions include which topics, if any, should be added to the FASB's agenda (and in what order) and whether the current agenda projects remain a priority to stakeholders or could be reimagined.
Issued: June 24, 2021
Comments Due: September 22, 2021
2020
Proposed Statement of Financial Accounting Concepts—Concepts Statement 8—Conceptual Framework for Financial Reporting—Chapter 4: Elements of Financial Statements
The Exposure Draft, Conceptual Framework for Financial Reporting: Chapter 4: Elements of Financial Statements, identifies elements of financial statements that could be appropriate for recognition in the financial statements and relevant to the users of those financial statements.
For more information, see the following:
Issued: July 16, 2020
Comments Due: November 13, 2020
2019
Invitation to Comment 2019-200—Measurement and Other Topics Related to Revenue Contracts with Customers under Topic 805805
The purpose of this Invitation to Comment (ITC) is to solicit feedback about measurement and other topics related to revenue contracts with customers under Topic 805, Business Combinations, that were identified by the Emerging Issues Task Force (EITF) during its consideration of EITF Issue No. 18-A, “Recognition under Topic 805 for an Assumed Liability in a Revenue Contract” (Issue 18-A). The FASB requests feedback about the following:
- 1Payment terms and their effect on the subsequent amount of revenue recognized by an acquirer
- 2Costs to fulfill a performance obligation in measuring the fair value of a contract liability for a revenue contract.
The ITC was issued concurrently with the related proposed Accounting Standards Update, Business Combinations (Topic 805): Revenue from Contracts with Customers—Recognizing an Assumed Liability, which resulted from decisions reached by the EITF on Issue 18-A.
For more information, see the following:
Issued: February 14, 2019
Comments Due: April 30, 2019
Invitation to Comment 2019-720—Identifiable Intangible Assets and Subsequent Accounting for Goodwill
The objective of this Invitation to Comment (ITC) is to identify whether a cost benefit issue exists for public business entities that warrant standard setting, and if there are viable cost-effective solutions. It is a staff document which includes considerations for improving the decision-usefulness of the information and rebalancing the cost benefit factors. Sections of the ITC discuss goodwill amortization, goodwill impairment testing, and disclosure considerations. The ITC also discusses potential approaches for modifying the recognition of intangible assets in a business combination.
For more information, see the following:
Issued: July 9, 2019
Comments Due: October 7, 2019
2016
Invitation to Comment 2016-290-Agenda Consultation
The purpose of this Invitation to Comment (ITC) is to solicit feedback about the financial reporting issues that the Financial Accounting Standards Board (FASB) should consider adding to its agenda. The FASB requests feedback about the following:
- 1Are the financial reporting issues described in this ITC areas for which there is potential for significant improvement?
- 2What is the priority of addressing each issue?
- 3What approach should the FASB take to address each issue?
- 4Are there other major areas of financial reporting not described in this ITC that the FASB should consider adding to its agenda?
The FASB would like broad stakeholder feedback before it makes decisions about which issues, if any, should be added to the agenda and in what order.
For more information, see the following:
Issued: August 4, 2016
Comments Due: October 17, 2016
Proposed Statement of Financial Accounting Concepts—Concepts Statement 8—Conceptual Framework for Financial Reporting—Chapter 7: Presentation
The Exposure Draft, Conceptual Framework for Financial Reporting: Chapter 7: Presentation, describes proposed concepts related to how recognized items should be presented in a financial statement. This chapter will become a basis for the Board when creating presentation requirements in future standards.
For more information, see the following:
Issued: August 11, 2016
Comments Due: November 9, 2016
2015
Proposed Amendments to Statement of Financial Accounting Concepts No. 8—Conceptual Framework for Financial Reporting—Chapter 3: Qualitative Characteristics of Useful Financial Information
The amendments are being proposed to ensure that the materiality concepts discussed are consistent with the legal concept of materiality.
For more information, see the following:
Issued: September 24, 2015
Comments Due: December 8, 2015
2014
Proposed Statement of Financial Accounting Concepts—Conceptual Framework for Financial Reporting—Chapter 8: Notes to Financial Statements
This exposure draft contains a proposed chapter of the FASB's Conceptual Framework that would become a basis for the Board when evaluating existing disclosure requirements and creating disclosure requirements in the future.
For more information, see the following:
Issued: March 4, 2014
Comments Due: July 14, 2014
2013
Discussion Paper 2013-250—Private Company Decision-Making Framework
This Invitation to Comment has as its ultimate objective to assist the Board and the PCC in developing a guide for the Board and the PCC to use in determining whether and in what circumstances to provide alternative recognition, measurement, disclosure, display, effective date, or transition guidance for private companies reporting under U.S. GAAP.
For more information, see the following:
Issued: April 15, 2013
Comments Due: June 21, 2013
2012
Discussion Paper 2012-220—Disclosure Framework
This Invitation to Comment solicits input on the development of a disclosure framework that promotes consistent decisions about disclosure requirements by the Board and the appropriate exercise of discretion by reporting entities. It also asks for feedback on several other issues intended to improve the effectiveness of disclosure.
For more information, see the following:
Issued: July 12, 2012
Comments Due: November 16, 2012
Discussion Paper 2012-230—Private Company Decision-Making Framework
The purpose of this Invitation to Comment is to gather input from interested stakeholders about the appropriateness, completeness, and cost effectiveness of the draft decision-making framework. The ultimate objective of the project that this Invitation to Comment is a part of is to develop a decision-making framework for the FASB and the PCC to use in determining whether and in what circumstances to adjust recognition, measurement, disclosure, display (presentation), effective date, or transition requirements for private companies reporting under U.S. generally accepted accounting principles (GAAP).
For more information, see the following:
Issued: July 31, 2012
Comments Due: October 31, 2012
2011
Discussion Paper 2011-175—Selected Issues about Hedge Accounting
This Invitation to Comment solicits input on the IASB's proposed revisions to hedge accounting in IAS 39, Financial Instruments: Recognition and Measurement, to assist the FASB as it continues its deliberations to improve and simplify its hedge accounting guidance.
For more information, see the following:
Issued: February 9, 2011
Comments Due: April 25, 2011
Supplementary Document 2011-150—Accounting for Financial Instruments and Revisions to the Accounting for Derivative Instruments and Hedging Activities—Impairment
This supplementary document presents an impairment model that the both the FASB and IASB believe will enable them to satisfy at least part of their individual objectives for impairment accounting while achieving a common solution to impairment.
For more information, see the following:
Issued: January 31, 2011
Comments Due: April 1, 2011
2010
Discussion Paper 1870-100—Preliminary Views on Insurance Contracts
The purpose of the Discussion Paper is to summarize key aspects of the International Accounting Standards Board's (IASB) recent proposals in its Exposure Draft, Insurance Contracts, and to compare those proposals to:
- aAlternative preliminary views of the Board
- bCurrent guidance in Topic 944, Financial Services—Insurance, of the FASB Accounting Standards Codification®.
For more information, see the following:
Issued: September 17, 2010
Comments Due: December 15, 2010
Discussion Paper 1890-100—Effective Dates and Transition Methods
This Discussion Paper has been issued to solicit information from stakeholders about the time and effort that will be involved in adapting to several anticipated new accounting and reporting standards and when those standards should become effective. The FASB will use that information to develop an implementation plan for those new standards that helps stakeholders manage the pace and cost of change.
For more information, see the following:
Issued: October 19, 2010
Comments Due: January 31, 2011
Undated
About the Codification—Notice to Constituents
Welcome to the Financial Accounting Standards Board (FASB) Accounting Standards Codification® (Codification).
The Codification is the single source of authoritative nongovernmental U.S. generally accepted accounting principles (US GAAP). The Codification is effective for interim and annual periods ending after September 15, 2009. All previous level (a)-(d) US GAAP standards issued by a standard setter are superseded. Level (a)-(d) US GAAP refers to the previous accounting hierarchy. All other accounting literature not included in the Codification is nonauthoritative. See Codification Topic 105, Generally Accepted Accounting Principles, for additional details.
The Codification is the result of a major 5-year project involving more than 200 people from multiple entities. The Codification structure is significantly different from the structure of previous accounting standards. The Notice to Constituents provides information that will help in obtaining a good understanding of the Codification structure, content, style and history.
Acquisition, Development, and Construction Costs
This Subsection does not address the accounting for costs incurred for acquisitions of property that will be used in the entity's own operations, other than for sale or rental.
Paragraphs provides guidance on how to distinguish between internal and external costs. The capitalization provisions of this Section for preacquisition costs apply to internally generated costs.
Payments to obtain an option to acquire real property shall be capitalized as incurred. All other costs related to a property that are incurred before the entity acquires the property, or before the entity obtains an option to acquire it, shall be capitalized if all of the following conditions are met and otherwise shall be charged to expense as incurred:
- a The costs are directly identifiable with the specific property.
- b The costs would be capitalized if the property were already acquired.
- c Acquisition of the property or of an option to acquire the property is probable (that is, likely to occur). This condition requires that the prospective purchaser is actively seeking to acquire the property and has the ability to finance or obtain financing for the acquisition and that there is no indication that the property is not available for sale.
Capitalized preacquisition costs either:
- a Shall be included as project costs upon the acquisition of the property
- b To the extent not recoverable by the sale of the options, plans, and so forth, shall be charged to expense when it is probable that the property will not be acquired.
The view that all internal costs of identifying and acquiring commercial properties should be deferred and, in some manner, capitalized as part of the cost of successful property acquisitions is not appropriate.
Internal costs of preacquisition activities incurred in connection with the acquisition of a property that will be classified as nonoperating at the date of acquisition that are directly identifiable with the acquired property and that were incurred subsequent to the time that acquisition of that specific property was considered probable (that is, likely to occur) shall be capitalized as part of the cost of that acquisition.
Paragraph 970-340-25-17 is also applicable in situations in which the acquired property is partially operating and partially nonoperating.
Costs incurred on real estate for property taxes and insurance shall be capitalized as property cost only during periods in which activities necessary to get the property ready for its intended use are in progress. The phrase activities necessary to get the property ready for its intended use are in progress is used here with the same meaning as it has for interest capitalization in paragraphs and 835-20-25-8. Costs incurred for such items after the property is substantially complete and ready for its intended use shall be charged to expense as incurred. The phrase substantially complete and ready for its intended use is used here with the same meaning as it has for interest capitalization in paragraph 835-20-25-5.
Accounting for costs of amenities shall be based on management's plans for the amenities in accordance with the following:
- a If an amenity is to be sold or transferred in connection with the sale of individual units, costs in excess of anticipated proceeds shall be allocated as common costs because the amenity is clearly associated with the development and sale of the project. The common costs include expected future operating costs to be borne by the developer until they are assumed by buyers of units in a project.
- b If an amenity is to be sold separately or retained by the developer, capitalizable costs of the amenity in excess of its estimated fair value as of the expected date of its substantial physical completion shall be allocated as common costs. For the purpose of determining the amount to be capitalized as common costs, the amount of cost previously allocated to the amenity shall not be revised after the amenity is substantially completed and available for use. A later sale of the amenity at more or less than its estimated fair value as of the date of substantial physical completion, less any accumulated depreciation, results in a gain or loss that shall be included in net income in the period in which the sale occurs.
Costs of amenities shall be allocated among land parcels benefited and for which development is probable. A land parcel may be considered to be an individual lot or unit, an amenity, or a phase. The fair value of a parcel is affected by its physical characteristics, its highest and best use, and the time and cost required for the buyer to make such use of the property considering access, development plans, zoning restrictions, and market absorption factors.
Before an amenity is substantially completed and available for use, operating income (or loss) of the amenity shall be included as a reduction of (or an addition to) common costs. When an amenity to be sold separately or retained by the developer is substantially completed and available for use, current operating income and expenses of the amenity shall be included in current operating results.
Incremental revenues from incidental operations in excess of incremental costs of incidental operations shall be accounted for as a reduction of capitalized project costs. Incremental costs in excess of incremental revenue shall be charged to expense as incurred, because the incidental operations did not achieve the objective of reducing the costs of developing the property for its intended use.
Costs incurred to sell real estate projects shall be evaluated for capitalization in accordance with paragraphs .
- a
- b
If costs incurred to rent real estate projects, other than initial direct costs, under operating leases or direct financing leases are related to and their recovery is reasonably expected from future rental operations, they shall be capitalized. Examples are costs of model units and their furnishings, rental facilities, semipermanent signs, grand openings, and unused rental brochures. Costs that do not meet the criteria for capitalization shall be expensed as incurred, for example, rental overhead. Initial direct costs are defined in Topic 842 and the accounting for initial direct costs is prescribed in that Topic.
If portions of a rental project are substantially completed and occupied by tenants or held available for occupancy and other portions have not yet reached that stage, the substantially completed portions shall be accounted for as a separate project. Costs incurred shall be allocated between the portions under construction and the portions substantially completed and held available for occupancy.
When a real estate project is substantially completed and held available for occupancy:
- a Rental operating costs shall be charged to expense when incurred.
- b All carrying costs (such as real estate taxes) shall be charged to expense when incurred, depreciation on the cost of the project shall be provided.
- c Costs to rent the project shall be amortized in accordance with paragraph 970-340-35-2.
A real estate project shall be considered substantially completed and held available for occupancy upon completion of tenant improvements by the developer but no later than one year from cessation of major construction activity (as distinguished from activities such as routine maintenance and cleanup).
Overall Guidance
This Subtopic follows the same Scope and Scope Exceptions as outlined in the Overall Subtopic, see Section 944-10-15, with specific instrument qualifications noted below.
The guidance in this Subtopic applies to all financial instruments, including investment contracts. For a guidance on identifying investment contracts, see the discussion beginning in paragraph 944-20-15-16.
The Reinsurance Contracts Subsections of this Subtopic follow the same Scope and Scope Exceptions as outlined in the General Subsection of this Section, with specific instrument qualifications noted below.
The guidance in the Reinsurance Contracts Subsections of this Subtopic applies only to reinsurance contracts. For guidance on identifying a reinsurance contract, see the Reinsurance Contracts Subsection of Section 944-20-15.
Overall Guidance
This Subtopic follows the same Scope and Scope Exceptions as outlined in the Overall Subtopic, see Section 944-10-15, with specific entity exceptions noted below.
The guidance in this Subtopic does not apply to mortgage guaranty insurance entities.
The Short-Duration Contracts Subsections of this Subtopic follow the same Scope and Scope Exceptions as outlined in the General Subsection of this Section, with specific instrument exceptions noted below.
The guidance in the Short-Duration Contracts Subsections of this Subtopic applies only to short-duration contracts. See the Short-Duration Contracts Subsection of Section 944-20-15 for a discussion of what constitutes a short-duration contract.
The Long-Duration Contracts Subsections of this Subtopic follow the same Scope and Scope Exceptions as outlined in the General Subsection of this Section, with specific instrument exceptions noted below.
The guidance in the Long-Duration Contracts Subsections of this Subtopic applies only to long-duration contracts. See the Long-Duration Contracts Subsection of Section 944-20-15 for a discussion of what constitutes a long-duration contract.
The Reinsurance Contracts Subsections of this Subtopic follow the same Scope and Scope Exceptions as outlined in the General Subsection of this Section, with specific instrument exceptions noted below.
The guidance in the Reinsurance Contracts Subsections of this Subtopic applies only to reinsurance contracts. See the Reinsurance Contracts Subsection of Section 944-20-15 for a discussion of what constitutes a reinsurance contract.
The guidance in the Financial Guarantee Insurance Contracts Subsections of this Subtopic applies only to financial guarantee insurance contracts (which include financial guarantee reinsurance contracts).
Page 2147479835
The disclosures in paragraphs apply to the intangible assets recognized pursuant to paragraph 944-805-25-3.
An insurance entity shall disclose all of the following:
- aThe nature and terms of a demutualization or formation of a mutual insurance holding entity
- bThe basis of presentation and terms of operation of the closed block
- cA general description of all of the following:
- 1The method of emergence of earnings from the closed block
- 2Presentation of assets and liabilities of the closed block
- 3The policyholder dividend obligation.
- 1
An insurance entity that has formed a closed block shall disclose both of the following:
- aA general description of the closed block, including all of the following:
- 1The purpose of the closed block
- 2The types of insurance policies included
- 3The nature of the cash flows that increase and decrease the amount of closed block assets and liabilities
- 4An indication of the continuing responsibility of the insurance entity to support the payment of contractual benefits, including the results of premium sufficiency or deficiency determined in accordance with paragraphs
- 5The nature of expenses charged to the closed block operations.
- 1
- bSummarized financial data of the closed block as of, or for periods ending on the date of, the financial statements presented, which shall include, at a minimum, all of the following:
- 1The carrying amounts for the major types of invested assets of the closed block
- 2Future policy benefits and policyholders' account balances
- 3Policyholder dividend obligation
- 4Premiums
- 5Net investment income
- 6Realized investment gains and losses
- 7Policyholder benefits
- 8Policyholder dividends
- 9The amount of maximum future earnings remaining to inure to the benefit of stockholders from the assets and liabilities of the closed block
- 10An analysis of the changes in the policyholder dividend obligation.
- 1
Disclosures that typically would be required by the preceding paragraph for the various specific elements included in the closed block need not be made separately for the closed block if the nature of the information for the closed block would not differ significantly from that already included for the reporting entity as a whole. For example, it is not necessary to show a separate schedule of contractual maturities of closed block fixed maturity securities if the relative composition of contractual maturities is similar to those of the reporting entity taken as a whole. However, if the relative maturities of the closed block fixed maturities securities differ from those of the reporting entity taken as a whole, separate disclosures shall be made.
Page 2147480428
This Section, which is an integral part of the requirements of this Subtopic, provides general guidance to be used in distinguishing contributions from exchange transactions, including membership dues and agency transactions.
The following diagram illustrates the process for determining whether a transfer of assets to a recipient is a contribution, an exchange transaction, or another type of transaction and whether a contribution is conditional. The diagram also illustrates whether there is an associated donor restriction with a contribution.
-
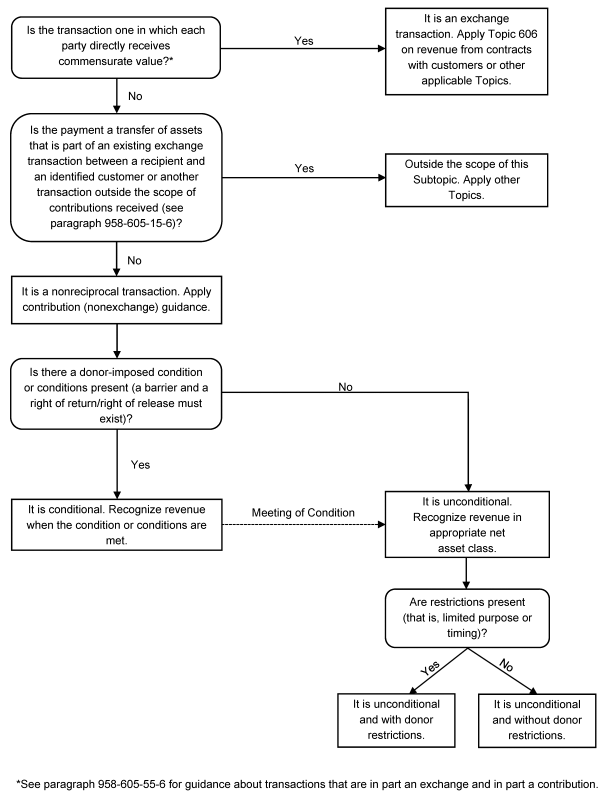 Is the transaction one in which each party directly receives commensurate value? It is an exchange transaction. Apply Topic 606 on revenue from contracts with customers or other applicable Topics. Is the payment a transfer of assets that is part of an existing exchange transaction between a recipient and an identified customer or another transaction outside the scope of contributions received (see paragraph 958-605-15-6)? Outside the scope of this Subtopic. Apply other Topics. It is a nonreciprocal transaction. Apply contribution (nonexchange) guidance. Is there a donor-imposed condition or conditions present (a barrier and a right of return/right of release must exist)? It is conditional. Recognize revenue when the condition or conditions are met. It is unconditional. Recognize revenue in appropriate net asset class. Are restrictions present (that is, limited purpose or timing)? It is unconditional and with donor restrictions. It is unconditional and without donor restrictions.
The accounting and reporting of grants, membership dues, and sponsorships is determined by the underlying substance of the transaction. Those terms are broadly used to refer not only to contributions but also to assets transferred in exchange transactions. A grant, sponsorship, or membership may be entirely a contribution, entirely an exchange, or a combination of the two; therefore, care must be taken in evaluating each grant, sponsorship, or membership agreement. In addition, those resource transfers may also have the characteristics of agency transactions.
The implementation guidance is organized as follows:
- aDistinguishing contributions from exchange transactions (see paragraphs )
- bDistinguishing the contribution portion of membership dues (see paragraphs )
- cDistinguishing contributions from agency transactions (see paragraph 958-605-55-13).
The guidance in this Subtopic about distinguishing between contributions and exchange transactions applies to both a resource provider (for example, a corporate foundation, a corporation, or a not-for-profit entity [NFP]) and a recipient.
Foundations, business entities, and other types of entities may provide resources to NFPs or business entities under programs referred to as grants, awards, or sponsorships. Those asset transfers are contributions if the resource providers do not receive commensurate value in exchange for the assets transferred or if the value received by the resource providers is incidental to the potential public benefit from using the assets transferred. A grant made by a resource provider to an NFP would likely be a contribution if the activity specified by the grant is to be planned and carried out by the NFP and the NFP has the right to the benefits of carrying out the activity. If, however, the grant is made by a resource provider that provides materials to be tested in the activity and that retains the right to any patents or other results of the activity, the grant would likely be an exchange transaction. A careful assessment of the characteristics of the transaction, from the perspectives of both the resource provider and the recipient, is necessary to determine whether a contribution has occurred.
For example, a resource provider may sponsor research and development activities at a research university and retain proprietary rights or other privileges, such as patents, copyrights, or advance and exclusive knowledge of the research outcomes. The research outcomes may be intangible, uncertain, or difficult to measure, and may be perceived by the university as a sacrifice of little or no value; however, their value often is commensurate with the value that a resource provider expects in exchange. Similarly, a resource provider may sponsor research and development activities and specify the protocol of the testing so the research outcomes are particularly valuable to the resource provider. Those transactions are not contributions if their potential public benefits are secondary to the potential proprietary benefits to the resource providers.
Moreover, a single transaction may be in part an exchange and in part a contribution. For example, if a donor transfers a building to an entity at a price significantly lower than its fair value and no unstated rights or privileges are involved, the transaction is in part an exchange of assets and in part a contribution to be accounted for as required by the Contributions Received Subsections of this Subtopic. See paragraphs for premiums provided to donors and Example 4 (paragraphs ) for direct benefits provided to donors at special events.
Example 1 (see paragraph 958-30-55-2) and paragraphs 958-605-55-13A through 55-14I illustrate the need to assess the relevant facts and circumstances to distinguish between the receipt of resources in an exchange and the receipt of resources in a contribution.
The term members is used broadly by some NFPs to refer to their donors and by other NFPs to refer to individuals or other entities that pay dues in exchange for a defined set of benefits. Some NFPs receive dues from their members. These transfers often have elements of both a contribution and an exchange transaction because members receive tangible or intangible benefits from their membership in the NFP. Usually, the determination of whether membership dues are contributions rests on whether the value received by the member is commensurate with the dues paid.
For example, if an NFP has annual dues of $100 and the only benefit members receive is a monthly newsletter with a fair value of $25, $25 of the dues are received in an exchange transaction and should be recognized as revenue as the earnings process is completed and $75 of the dues are a contribution. (See paragraph 958-605-25-1 for recognition of the exchange portion of membership dues. See the Contributions Received Subsections of this Subtopic for the reporting of the contribution portion.)
Member benefits generally have value regardless of how often (or whether) the benefits are used. For example, most would agree that a health club membership is an exchange transaction, even if the member stops using the facilities before the completion of the membership period. It may be difficult, however, to measure the benefits members receive and to determine whether the value of those benefits is approximately equal to the dues paid by the members.
The following table contains a list of indicators that may be helpful in determining whether membership dues are contributions, exchange transactions, or a combination of both. Depending on the facts and circumstances, some indicators may be more significant than others; however, no single indicator is determinative of the classification of a particular transaction.
- Indicators Useful for Determining the Contribution and Exchange Portions of Membership Dues
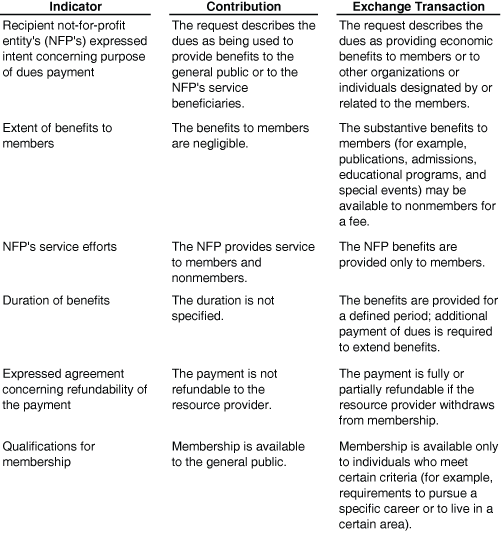 Indicator Contribution Exchange Transaction Recipient not-for-profit entity's (NFP's) expressed intent concerning purpose of dues payment The request describes the dues as being used to provide benefits to the general public or to the NFP's service beneficiaries. The request describes the dues as providing economic benefits to members or to other organizations or individuals designated by or related to the members. Extent of benefits to members The benefits to members are negligible. "The substantive benefits to members (for example, publications, admissions, educational programs, and special events) may be available to nonmembers for a fee." NFP's service efforts The NFP provides service to members and nonmembers. The NFP benefits are provided only to members. Duration of benefits The duration is not specified. The benefits are provided for a defined period; additional payment of dues is required to extend benefits. Expressed agreement concerning refundability of the payment The payment is not refundable to the resource provider. The payment is fully or partially refundable if the resource provider withdraws from membership. Qualifications for membership Membership is available to the general public. "Membership is available only to individuals who meet certain criteria (for example, requirements to pursue a specific career or to live in a certain area)."
A transfer of assets may appear to be a contribution if a donor uses a recipient entity as its intermediary, agent, or trustee to transfer assets to a third-party donee, particularly if the recipient entity indirectly achieves its mission by disbursing the assets. Although the transaction between the donor and the donee may be a contribution, the transfer of assets from the donor is not a contribution received by the recipient entity, and the transfer of assets to the donee is not a contribution made by the recipient entity. (See the Transfers of Assets to a Not-for-Profit Entity or Charitable Trust that Raises or Holds Contributions for Others Subsection of this Section for implementation guidance on and illustrations of agency transactions.)
Examples 1 through 5 illustrate the guidance in Section 958-605-15 for determining whether a transaction is an exchange or a contribution. The analysis in each Example is not intended to represent the only manner in which the guidance could be applied, and the Examples are not intended to apply to only a specific illustration. Although some aspects of the Examples may be present in actual fact patterns, all relevant facts and circumstances of a particular fact pattern should be evaluated when applying the guidance in this Subtopic. The guidance in these Examples about distinguishing between contributions and exchange transactions applies to both a resource provider (for example, a corporate foundation, a corporation, or an NFP) and a recipient.
Not-for-Profit Entity A (NFP A) is a large research university with a cancer research center. NFP A regularly conducts research to discover more effective methods of treating cancer and often receives contributions to support its efforts. NFP A receives resources from a pharmaceutical entity to finance the costs of a clinical trial of an experimental cancer drug the pharmaceutical entity developed. The pharmaceutical entity specifies the protocol of the testing, including the number of participants to be tested, the dosages to be administered, and the frequency and nature of follow-up examinations. The pharmaceutical entity requires a detailed report of the test outcome within two months of the test's conclusion. Additionally, the rights to the results of the study belong to the pharmaceutical entity.
Because the results of the clinical trial have particular commercial value for the pharmaceutical entity, the pharmaceutical entity is receiving commensurate value as the resource provider. Therefore, the receipt of the resources is not a contribution received by NFP A, nor is the disbursement of the resources a contribution made by the pharmaceutical entity. See paragraph 958-605-15-5A.
Student L is enrolled at University A. Student L's total tuition charged for the semester is $30,000. Student L received a grant in the amount of $2,000 to use toward the tuition fee, which is paid directly by the grantor to University A.
The grant was awarded to Student L, not to University A. University A entered into an exchange transaction with Student L and accounts for the $30,000 of revenue in accordance with the guidance in the appropriate Subtopic. The $2,000 grant does not create additional revenue but, rather, serves as a partial payment against the $30,000 due to University A. Student L is an identified customer of University A who is receiving the benefit from the grant transaction. See paragraph 958-605-15-6(e).
Patient R is a patient at Hospital B. The total amount due for services rendered is $10,000. Patient R has Medicare, and it covers $8,000 of the services, which is paid directly by the government to Hospital B. Hospital B bills Patient R for $2,000.
Medicare is a form of insurance. Hospital B has a contract with a customer (Patient R) and determines that the $10,000 should be accounted for as an exchange transaction in accordance with the guidance in the appropriate Topic. The Medicare payment of $8,000 and Patient R's payment of $2,000 serve as a payment source for services rendered in the amount of $10,000 owed to Hospital B. The payment to Hospital B relates to an existing exchange transaction between Hospital B and an identified customer (Patient R). See paragraph 958-605-15-6(e).
The local government provided funding to NFP C to perform a research study on the benefits of a longer school year. The agreement requires NFP C to plan the study, perform the research, and summarize and submit the research to the local government. The local government retains all rights to the study.
NFP C concludes that this is a procurement arrangement in which commensurate value is being exchanged between two parties and that it should follow the relevant guidance for exchange transactions. NFP C is to perform a research study for the local government and turn over a summary of the study's findings to the local government. The local government retains the rights to the study. See paragraph 958-605-15-5A(c).
University D applied for and was awarded a grant from the federal government. University D must follow the rules and regulations established by the Office of Management and Budget of the federal government and the federal awarding agency. University D is required to incur qualifying expenses to be entitled to the assets. Any unspent money during the grant period is forfeited, and University D is required to return any advanced funding that does not have related qualifying expenses. University D also is required to submit a summary of research findings to the federal government, but University D retains the rights to the findings and has permission to publish the findings if it desires.
University D concludes that this grant is not a transaction in which there is commensurate value being exchanged. The federal government, as the resource provider, does not receive direct commensurate value in exchange for the assets provided to University D because University D retains all rights to the research and findings. University D and the public receive the primary benefit of any findings, and the federal government receives an indirect benefit because the research and findings serve the general public. Thus, University D determines that this grant should be accounted for under the contribution guidance in this Subtopic. See paragraph 958-605-15-5A(a).
Distinguishing between a condition stipulated by a donor and a restriction on the use of a contribution imposed by a donor may require the exercise of judgment. A donor-imposed condition depends on whether the agreement includes a barrier that must be overcome before a recipient is entitled to the assets transferred or promised. The agreement also must give either the contributor a right of return of the assets it has transferred or the promisor a right of release from its obligation to transfer assets. Donor-imposed conditions should be substantially met by the entity before the receipt of assets (including contributions receivable) is recognized as a contribution. In contrast to donor-imposed conditions, donor-imposed restrictions limit the use of the contribution, but they do not affect whether the recipient is entitled to the contribution.
If donor stipulations do not clearly state whether the right to receive or retain payment or take delivery depends on meeting those stipulations, or if those stipulations are ambiguous, distinguishing a conditional promise to give from an unconditional promise to give may be difficult. If the ambiguity cannot be resolved by reviewing the facts and circumstances surrounding the contribution and communicating with the donor, presume that a promise containing stipulations that are not clearly unconditional is a conditional promise to give. However, if the stipulation is not related to the purpose of the agreement (generally stipulations that are administrative or trivial), that stipulation is not indicative of a barrier (for example, a stipulation that an annual report must be provided by the donee to receive subsequent annual payments on a multiyear promise is not a barrier if the administrative requirement is not related to the purpose of the agreement.)
A challenge (matching) grant is a common form of a conditional promise to give. For example, a resource provider promises to contribute $1 for each $1 of contributions received by a not-for-profit entity (NFP), up to $100,000, over the next 6 months. As contributions are received from other resource providers, the conditions would be met and the promise would become unconditional. For example, if $10,000 is received in the first month from donors, $10,000 of the conditional promise would become unconditional and should be recognized as contribution revenue.
A donor-imposed condition must have both:
- aOne or more barriers that must be overcome before a recipient is entitled to the assets transferred or promised.
- bA right of return to the contributor for assets transferred (or for a reduction, settlement, or cancellation of liabilities) or a right of release of the promisor from its obligation to transfer assets (or to reduce, settle, or cancel liabilities).
It is possible that some agreements that do not contain any barriers could contain either a right of return of assets transferred or a right of release from obligation. For example, some foundations include a right-of-return or a right-of-release-from-obligation clause in their agreements as a matter of policy and standard wording but impose no barriers that must be achieved before a recipient is entitled to the resources. The resources would be considered unconditional, and revenue would be recognized immediately.
Some agreements include multiple requirements that must be overcome before an entity is entitled to transferred assets or a future transfer of assets. An entity must consider facts and circumstances and use judgment to determine which stipulations, if any, of an agreement are deemed to be a barrier or barriers that must be achieved before an entity is entitled to assets.
As described in paragraph 958-605-25-5D, a measurable performance-related barrier or other measurable barrier may be indicative of a donor-imposed condition. Examples of measurable performance-related barriers or other measurable barriers could include:
- aSpecified level of service. An entity is given assets, and the resource provider stipulates that the assets must be used to provide a specific level of service (for example, 1,000 meals per week for a soup kitchen). The barrier that must be overcome before the recipient is entitled to the resources is the specified level of service that must be achieved.
- bSpecific output or outcome. An entity is given assets, entitlement to which is contingent upon producing a specific output or achieving a measurable outcome stemming from the entity's activities (for example, students achieving a minimum standardized test score, a decline in drop-out rates following an entity's educational efforts, and community residents exhibiting a decline in symptoms of malnutrition following an entity's efforts in providing meals).
- cMatching. A resource provider specifies the ratio or amount of a matching contribution. The recipient is not entitled to receive the promised assets until it has met the required match (the barrier or hurdle that must be overcome).
- dOutside event. Agreements may include requirements that are imposed on, and would need to be overcome by, other parties, including the resource provider. A resource provider specifies that a certain outside event needs to occur for the recipient to be entitled to receive the assets (for example, a resource provider promises to contribute a certain amount of assets if the resource provider's net worth reaches a specified level).
As described in paragraph 958-605-25-5D, limited discretion may be indicative of a donor-imposed condition. Limited discretion of the recipient on the conduct of an activity is more specific than a donor-imposed restriction. Restrictions limit the use of a contribution to a specific activity or time but do not necessarily place limitations on how the activity is performed. This indicator focuses on limitations concerning specific requirements about how an activity must be conducted for a recipient to be entitled to the resources. For example, an agreement might specify that the recipient should incur qualifying expenses in compliance with established rules and regulations. This is in contrast to a restriction, which typically places limits only on a specific activity that is being funded and does not affect the extent to which a recipient is entitled to the resources (for example, a requirement that a contribution be used to fund one of an organization's programs).
An indicator noting that a stipulation is related to the purpose of the agreement could be helpful in the context of considering the agreement collectively with the other indicators. If a stipulation is unrelated to the purpose of the agreement (for example, trivial or administrative stipulations), the stipulation would not be indicative of a barrier. If administrative tasks are required that are unrelated to the purpose of the agreement, there most likely would be other requirements that would be more indicative of a barrier that must be overcome before the recipient is entitled to the resources (for example, a specific event or activity to occur). Producing an annual report is a common requirement in contribution agreements; however, the annual report typically is not related to the underlying purpose of the agreement. Generally, a report is administrative in nature and is intended to provide a resource provider with information to confirm that the transferred assets were used in accordance with the purpose of the agreement and is not intended to affect the extent to which the recipient is entitled to the contribution.
A promise to give is a written or oral agreement to contribute cash or other assets to another entity. The Contributions Received Subsections of this Subtopic avoid using the term pledge because that term is used to describe not only promises to give but also plans or intentions to give that are not promises. There are other terms used to describe promises to give such as subscriptions, awards, appropriations, or grants. A communication received from a potential donor must be carefully evaluated to determine if it is a promise to give, since a communication that clearly is not a promise is not recognized in the financial statements.
Pursuant to paragraph 958-605-25-8, to be recognized in financial statements there must be sufficient evidence in the form of verifiable documentation that a promise to give was made and received. That requirement does not preclude recognition of verifiable oral promises, such as those documented by tape recordings, written registers, or other means that permit subsequent verification.
Promises to give services generally involve personal services that, if not explicitly conditional, are often implicitly conditioned upon the future and uncertain availability of specific individuals whose services have been promised.
Certain promises become unconditional in stages because they are dependent on several or a series of conditions—milestones—rather than on a single condition and are recognized in increments as each of the conditions is met. Similarly, other promises are conditioned on promisees' incurring certain qualifying expenses (or costs). Those promises become unconditional and are recognized to the extent that the expenses are incurred. A portion of those contributions should be recognized as revenue as each of those stages is met.
The present value of the future cash flows is one valuation technique for measuring the fair value of contributions arising from unconditional promises to give cash; other valuation techniques also are available, as described in Topic 820. The following table illustrates the use of present value techniques for initial recognition and measurement of unconditional promises to give cash that are expected to be collected one year or more after the financial statement date.
- Initial Recognition of Unconditional Promises to Give Cash
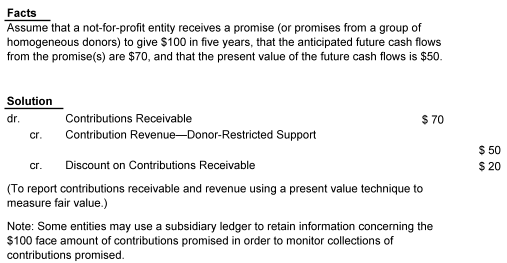 Facts "Assume that a not-for-profit entity receives a promise (or promises from a group of homogeneous donors) to give $100 in five years, that the anticipated future cash flows from the promise(s) are $70, and that the present value of the future cash flows is $50." Solution dr. Contributions Receivable $70 cr. Contribution Revenue—Donor-Restricted Support $50 cr. Discount on Contributions Receivable $20 (To report contributions receivable and revenue using a present value technique to measure fair value.) Note: Some entities may use a subsidiary ledger to retain information concerning the $100 face amount of contributions promised in order to monitor collections of contributions promised.
The use of property, utilities, or advertising time is considered to be forms of contributed assets, rather than contributed services. Pursuant to paragraph 958-605-25-2, an NFP would recognize the fair value of the use of property, utilities, or advertising time as both revenue and expense in the period received and used. Fair value could be estimated by using billing rates normally charged to other customers under similar circumstances. Whether those contributions should be reported is unaffected by whether the NFP could afford to purchase the utilities or facilities at their fair value. If the transaction is an unconditional promise to give electric, telephone, or other utilities for a specified number of periods, the promise should be reported as a contribution receivable and as donor-restricted support that increases net assets with donor restrictions, pursuant to paragraph 958-605-25-8.
Unconditional promises to give the use of long-lived assets (such as a building or other facilities) for a specified number of periods in which the donor retains legal title to the long-lived asset may be received in connection with leases or may be similar to leases but have no lease payments. For example, an NFP may use facilities under a lease agreement that calls for lease payments at amounts below the fair rental value of the property. In circumstances in which an NFP receives an unconditional promise to give for a specified number of periods, the promise should be reported as revenue and as a contribution receivable for the difference between the fair rental value of the property and the stated amount of the lease payments. In other words, if a donor promises that the NFP can use a facility for 10 years, the NFP has received a multiyear promise to give and should report the fair value of that promise as a contribution with a donor-imposed restriction in Year 1. Amounts reported as contributions shall not exceed the fair value of the long-lived asset at the time the NFP receives the unconditional promise to give. The contribution receivable may be described in the financial statements based on the item whose use is being contributed, such as a building, rather than as contributions receivable.
Property and equipment used in exchange transactions (other than lease transactions), such as federal contracts, in which the resource provider retains legal title during the term of the arrangement should be reported as a contribution at fair value at the date received by the NFP only if it is probable that the NFP will be permitted to keep the assets when the arrangement terminates.
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
105-10-65-10Paragraph superseded by Accounting Standards Update No. 2025-12.Contributions are received in several different forms. Most often the item contributed is an asset, but it also can be forgiveness of a liability. The types of assets commonly contributed include cash, marketable securities, land, buildings, use of facilities or utilities, materials and supplies, intangible assets, other goods or services, and unconditional promises to give those items in the future. The Contributions Received Subsection of Section 958-605-30 requires NFPs receiving contributions to recognize them at the fair values of the assets received. However, recognition of contributions of works of art, historical treasures, and similar assets is not required if the donated items are added to collections (see paragraph 958-360-25-1), and recognition of contributions of services is prohibited if the services do meet any of the criteria in paragraph 958-605-25-16.
Examples 1 through 6 (see paragraphs ) provide illustrations on different types of contributed assets, including the following:
- aReal property
- bWorks of art
- cHistorical objects
- dUtilities
- eUse of property
- fInterest in an estate.
Recognition of contributions of services is required for those contributed services received that meet any of the specified conditions of paragraph 958-605-25-16 and is precluded for contributed services that do not. The criterion in paragraph 958-605-25-16(b)requires that recognized services be specialized skills provided by individuals possessing those skills. An individual who receives some training does not necessarily possess a specialized skill. For example, if a volunteer receives some training from an NFP to learn how to help other people learn to read, that volunteer does not possess the specialized skills that a reading teacher possesses.
Examples 7 through 11 (see paragraphs ) provide illustrations on different types of contributed services, including the following:
- aConstruction services
- bTeaching services
- cBoard of trustee services
- dCompanion services
- eFundraising services.
See paragraph 275-10-50-18 for guidance on disclosures about risk concentrations.
Example 12 (see paragraph 958-605-55-69) illustrates the situation in which an NFP relies on specific donors for contributions.
This Example illustrates the application of the recognition and measurement principles of paragraphs 958-605-25-2 and 958-605-30-2.
Mission A, a religious NFP, receives a building (including the land on which it was constructed) as a gift from a local corporation with the understanding that the building will be used principally as an education and training center for Mission A's members or for any other purpose consistent with Mission A's plans.
Mission A would recognize the contributed property as an asset and as support and measure that property at its fair value (see paragraph 958-605-30-2). Information necessary to estimate the fair value of that property could be obtained from various sources, including amounts recently paid for similar properties in the locality, and estimates of its replacement cost adjusted to reflect the price that would be received for the contributed property. This contribution is revenue without donor restrictions because the donated assets may be used for any purpose and the donor did not impose a time restriction.
This Example illustrates the application of the recognition and measurement principles of paragraph 958-605-25-19.
Museum B, which preserves its collections as described in paragraph 958-605-25-19, receives a gift of a valuable painting from a donor. The donor obtained an independent appraisal of the fair value of the painting for tax purposes and furnished a copy to the museum. The museum staff evaluated the painting to determine its authenticity and worthiness for addition to the museum's collection. The staff recommended that the gift be accepted, adding that it was not aware of any evidence contradicting the fair value provided by the donor and the donor's appraiser.
If Museum B capitalizes its collections, Museum B would recognize the fair value of the contributed work of art received as revenue and capitalize it as an asset at its fair value (see paragraph 958-605-25-19). If Museum B does not capitalize its collections, Museum B is precluded from recognizing the contribution (see that paragraph) and would provide the information required by paragraphs 958-360-45-3 and 958-360-45-5.
If Museum B accepted the painting with the donor's understanding that it would be sold rather than added to its collection, Museum B would recognize the contribution of the painting received as revenue without donor restrictions and as an asset at its fair value (see paragraphs 958-605-30-2 and 958-605-45-6).
This Example illustrates the application of the recognition and measurement principles of paragraph 958-605-25-19.
Historical Society C receives several old photographs as a gift from a long-time local resident. The photographs depict a particular area as it was 75 years ago. After evaluating whether the photographs were worthy of addition to the historical society's collection, the staff concluded the photographs should be accepted solely because of their potential historical and educational use; that is, the photographs may be of interest to future researchers, historians, or others interested in studying the area. The photographs are not suitable for display and no alternative use exists.
Regardless of whether Historical Society C capitalizes its collections, Historical Society C would not recognize the contributed photographs as assets because there is major uncertainty about the existence of value and no alternative use exists (see paragraph 958-605-25-4).
This Example illustrates the application of the recognition and measurement principles of paragraphs 958-605-25-2 and 958-605-30-2.
Foundation D operates from a building it owns. The holding company of a local utility has been contributing electricity on a continuous basis subject to the donor's cancellation.
The simultaneous receipt and use of electricity or other utilities is a form of contributed assets and not services. Foundation D would recognize the fair value of the contributed electricity as both revenue and expense in the period it is received and used (see paragraph 958-605-30-2). Foundation D could estimate the fair value of the electricity received by using rates normally charged to a consumer of similar usage requirements.
This Example illustrates the application of the recognition and measurement principles of paragraphs 958-605-25-2 and 958-605-30-2.
Charity E receives the free use of 10,000 square feet of prime office space provided by a local entity. The local entity has informed Charity E that it intends to continue providing the space as long as it is available, and although it expects it would be able to give the charity 30 days advance notice, it may discontinue providing the space at any time. The local entity normally rents similar space for $14 to $16 annually per square foot, the going market rate for office space in the area. Charity E decides to accept this gift—the free use of office space—to conduct its daily central administrative activities.
The simultaneous receipt and use of facilities is a form of contributed assets and not services. Charity E would recognize the fair value of the contributed use of facilities as both revenue and expense in the period it is received and used (see paragraph 958-605-30-2).
If the local entity explicitly and unconditionally promises the use of the facility for a specified period of time (for example, five years), the promise would be an unconditional promise to give. In that case, Charity E would recognize the receipt of the unconditional promise as a receivable and as donor-restricted support at its fair value. The donor would recognize the unconditional promise when made as a payable and an expense at its fair value (see paragraph 720-25-25-1).
This Example illustrates the application of the recognition and measurement principles of paragraphs 958-605-25-2 and 958-605-30-2.
In 19X0, Individual notifies Church F that she has remembered the church in her will and provides a written copy of the will. In 19X5, Individual dies. In 19X6, Individual's last will and testament enters probate and the probate court declares the will valid. The executor informs Church F that the will has been declared valid and that it will receive 10 percent of Individual's estate, after satisfying the estate's liabilities and certain specific bequests. The executor provides an estimate of the estate's assets and liabilities and the expected amount and time for payment of Church F's interest in the estate.
The 19X0 communication between Individual and Church F specified an intention to give. The ability to modify a will at any time prior to death is well established; thus in 19X0 Church F did not receive a promise to give and did not recognize a contribution received. When the probate court declares the will valid, Church F would recognize a receivable and revenue for an unconditional promise to give at the fair value of its interest in the estate (see paragraphs 958-310-35-6, 958-605-30-5, and 958-605-30-6). If the promise to give contained in the valid will was instead conditional based on a barrier that must be overcome for Church F to be entitled to the assets, Church F would recognize the contribution when the condition was substantially met. A conditional promise in a valid will would be disclosed in notes to financial statements (see paragraph 958-310-50-4).
This Example illustrates the application of the recognition and measurement principles of paragraphs 958-605-25-16 and 958-605-30-10.
Institute G decides to construct a building on its property. It obtains the necessary architectural plans and specifications and purchases the necessary continuing architectural services, materials, permits, and so forth at a total cost of $400,000. A local construction entity contributes the necessary labor and equipment. An independent appraisal of the building (exclusive of land), obtained for insurance purposes, estimates its fair value at $725,000.
Institute G would recognize the services contributed by the construction entity because the contributed services received meet the condition in paragraph 958-605-25-16(a) (the services received create or enhance nonfinancial assets) or because the services meet the condition in paragraph 958-605-25-16(b) (the services require specialized skills, are provided by individuals possessing those skills, and would typically need to be purchased if not provided by donation). Contributions of services that create or enhance nonfinancial assets may be measured by referring to either the fair value of the services received or the fair value of the asset or of the asset enhancement resulting from the services (see paragraph 958-605-30-10). In this Example, the fair value of the contributed services received could be determined by subtracting the cost of the purchased services, materials, and permits ($400,000) from the fair value of the asset created ($725,000), which results in contributed services received of $325,000. Alternatively, the amount the construction entity would have charged could be used if more readily available.
If some of the labor did not require specialized skills and was provided by volunteers, those services still would be recognized because they meet the condition in paragraph 958-605-25-16(a).
This Example illustrates the application of the recognition and measurement principles of paragraphs 958-605-25-16 and 958-605-30-10.
Faculty salaries are a major expense of University H. The faculty includes both compensated faculty members (approximately 80 percent) and uncompensated faculty members (approximately 20 percent) who are associated with religious orders and contribute their services to the university. The performance of both compensated and uncompensated faculty members is regularly and similarly evaluated; both must meet the university's standards and both provide services in the same way.
University H would recognize both revenue and expense for the services contributed by the uncompensated faculty members because the contribution meets the condition in paragraph 958-605-25-16(b). Teaching requires specialized skills; the religious personnel are qualified and trained to provide those skills; and University H typically would hire paid instructors if the religious personnel did not donate their services. University H could refer to the salaries it pays similarly qualified compensated faculty members to determine fair value of the services received.
Similarly, if the uncompensated faculty members were given a nominal stipend to help defray certain of their out-of-pocket expenses, University H still would recognize both revenue and expense for the services contributed. The contribution received would be measured at the fair value of the services received less the amount of the nominal stipend paid.
This Example illustrates the application of the recognition and measurement principles of paragraphs 958-605-25-16 and 958-605-30-10.
A member of the board of trustees of Civic Organization I is a lawyer and from time to time in the capacity of a trustee provides advice on general business matters, including questions about business opportunities and risks and ethical, moral, and legal matters. The advice provided on legal matters is provided as a trustee in the role of a trustee, not as a lawyer, and the opinions generally are limited to routine matters. Generally, the lawyer suggests that Civic Organization I seek the opinion of its attorneys on substantive or complex legal questions. All of Civic Organization I's trustees serve without compensation, and most trustees have specialized expertise (for example, a chief executive officer, a minister, a physician, a professor, and a public accountant) that makes their advice valuable to Civic Organization I. The trustee-lawyer also serves without compensation as a trustee for two other charitable organizations.
Civic Organization I would be precluded from recognizing the contributed services it receives from its trustee-lawyer or its other trustees because the services contributed do not meet either of the conditions in paragraph 958-605-25-16. The condition in (a) in that paragraph is not relevant. The trustee-lawyer's services do not meet the condition in (b) in that paragraph because the substantive or complex legal questions that require the specialized skills of a lawyer are referred to Civic Organization I's attorneys or because the advice provided by trustees typically would not be purchased if not provided by donation.
This Example illustrates the application of the recognition and measurement principles of paragraphs 958-605-25-16 and 958-605-30-10.
Hospital J provides short-term inpatient and outpatient care and also provides long-term care for the elderly. As part of the long-term care program, the hospital has organized a program whereby local high school students may contribute a minimum of 10 hours a week, from 3:00 p.m. to 6:00 p.m., to the hospital. These students are assigned various duties, such as visiting and talking with the patients, distributing books and magazines, reading, playing chess, and similar activities. Hospital J does not pay for these services or similar services. The services are accepted as a way of enhancing or supplementing the quality of care and comfort provided to the elderly long-term care patients.
Hospital J would be precluded from recognizing the contributed services because the services contributed do not meet either of the conditions in paragraph 958-605-25-16. The condition in (a) in that paragraph is not relevant. The condition in (b) in that paragraph has not been met because the services the students provide do not require specialized skills nor would they typically need to be purchased if not provided by donation.
This Example illustrates the application of the recognition and measurement principles of paragraphs 958-605-25-16 and 958-605-30-10.
College K conducts an annual fund-raising campaign to solicit contributions from its alumni. In prior years, College K recruited unpaid student volunteers to make phone calls to its alumni. This year, a telemarketing entity, whose president is an alumnus of College K, contributed its services to College K for the annual alumni fundraising campaign. The entity normally provides telemarketing services to a variety of clients on a fee basis. College K provided the entity with a list of 10,000 alumni, several copies of a typed appeal to be read over the phone, and blank contribution forms to record pledges received. The entity contacted most of the 10,000 alumni.
College K would be precluded from recognizing the contributed services of the telemarketing entity. The condition in paragraph 958-605-25-16(a) is not relevant. The condition in paragraph 958-605-25-16(b) has not been met because the services do not require specialized skills or because College K typically would not need to purchase the services if they were not provided by donation. College K normally conducts its campaign with untrained students in a manner similar to the manner used by the telemarketing firm.
This Example illustrates the disclosure requirements of paragraphs 275-10-50-16.
Zebra Zoo is supported by contributions from the public. In the current year, 2 contributors provided 35 percent of Zebra Zoo's combined revenues. The following disclosure is required (see paragraph 275-10-50-16) because the two contributors provided a significant portion of Zebra Zoo's revenues. It is always considered reasonably possible that a customer, grantor, or contributor will be lost in the near term.
- Approximately 35 percent of Zebra Zoo's combined revenues were provided by 2 contributors.
Examples 13 through 21 (paragraphs ) illustrate how an entity might apply certain aspects of the guidance in this Subtopic in determining whether a contribution is conditional (all fact patterns are considered to be contributions or conditional contributions within the scope of this Subtopic). The analysis in each Example is not intended to represent the only manner in which the guidance could be applied, and the Examples are not intended to apply to only a specific illustration. Although some aspects of the Examples may be present in actual fact patterns, all relevant facts and circumstances of a particular fact pattern would need to be evaluated when applying the guidance in this Subtopic (for guidance on release from restrictions, see Section 958-605-45). Some examples are presented from the perspective of a resource provider (for example, an individual, a business corporation, a foundation, or an other NFP), and other examples are presented from the perspective of a resource recipient. The guidance in this Subtopic on determining whether a contribution is conditional applies to both contributions made by a resource provider and contributions received by a recipient.
Many agreements include a requirement that assets must be used for allowable and reasonable qualifying expenses (or costs) that are based on specific requirements of an agreement about the conduct of an activity (for example, in compliance with principles issued by the Office of Management and Budget or other similarly restrictive grant documents) that results in limited discretion by a recipient on the conduct of an activity and, thus, is indicative of a donor-imposed condition. These agreements often are paid on a cost-reimbursement basis that requires a recipient to incur specific qualifying expenses to be entitled to the promised resources. The specific requirements about allowable qualifying expenses are often accompanied by very close cost reporting and monitoring by the resource provider.
Foundation A gives NFP D a grant in the amount of $400,000 to provide specific career training to disabled veterans. The grant requires NFP D to provide training to at least 8,000 disabled veterans during the next fiscal year (2,000 during each quarter), with specific minimum targets that must be met each quarter. Foundation A specifies a right of release from the obligation in the agreement that it will only give NFP D $100,000 each quarter if NFP D demonstrates that those services have been provided to at least 2,000 disabled veterans during the quarter.
Foundation A determines that it should account for this grant as conditional. The agreement contains a right of release from obligation because the resource provider will only transfer assets if NFP D provides training to at least 8,000 disabled veterans during the year (with a minimum requirement of 2,000 disabled veterans per quarter) as specified in the agreement. Foundation A requires NFP D to achieve a specific level of service that would be considered a measurable performance-related barrier (in the form of milestones by specifying 2,000 disabled veterans per quarter). In this Example, NFP D's entitlement to the transferred assets is contingent upon serving at least 2,000 disabled veterans. The likelihood of serving at least 2,000 disabled veterans for the quarter is not a consideration from the perspective of either Foundation A or NFP D when assessing whether the contribution contains a barrier and is deemed conditional.
NFP B is a hospital that has a research program. NFP B receives a $300,000 grant from the federal awarding agency to fund thyroid cancer research. The terms of the grant specify that NFP B must incur certain qualifying expenses (or costs) in compliance with rules and regulations established by the Office of Management and Budget and the federal awarding agency. The grant is paid on a cost-reimbursement basis by NFP B initiating drawdowns of the grant assets. Any unused assets are forfeited, and any unallowed costs that have been drawn down by NFP B are required to be refunded.
NFP B determines that this grant is conditional. The grant agreement limits NFP's discretion as a result of the specific requirements on how NFP B may spend the assets (incurring certain qualifying expenses in accordance with the Office of Management and Budget rules and regulations). The grant also includes a release from the promisor's obligation for unused assets. The requirement to spend the assets on qualifying expenses is a barrier to entitlement because the requirement limits NFP B's discretion about how to use the assets, and the assets would need to be spent on specific items on the basis of the requirements of the agreement (for example, adherence to cost principles) before NFP B is entitled to the assets. This is in contrast to a restriction that typically places limits only on a specific activity that is being funded. NFP B records revenue during the grant period when the barriers have been overcome as it incurs qualifying expenses. The likelihood of incurring qualifying expenses is not a consideration when assessing whether the contribution is deemed conditional.
NFP E is a public charity that performs research on various diseases and allergies, including gluten-related allergies, as part of its overall mission. It receives a $100,000 grant from a foundation to perform research on gluten-related allergies over the next year. The grant agreement includes a right of return as part of the foundation's standard wording and a requirement that at the end of the grant period a report must be filed with the foundation that explains how the assets were spent.
NFP E determines that the grant is not a conditional contribution. The purpose of research on gluten-related allergies results in donor-restricted revenue because the purpose of the grant (working on gluten-free allergies) is narrower than the overall mission of the entity. There are no requirements in the agreement that would indicate that a barrier exists, which must be overcome before the recipient is entitled to the resources. NFP E also determines that the reporting requirement alone is not a barrier because it is an administrative requirement and not related to the purpose of the agreement, which is the actual research. This is an example in which a grant including a right of return could not be considered conditional because the return clause is not coupled with a barrier to be overcome, as determined by NFP E using judgment to assess the indicators of a barrier.
NFP DD is a hospital that received an upfront cash contribution from an individual to perform research on Alzheimer's disease during NFP DD's next fiscal year. The agreement does not include a right of return or a barrier that must be overcome to be entitled to the funds.
NFP DD determines that this contribution is not conditional because it does not include a right of return (or similar language) of the assets that have been transferred upfront. NFP DD concludes that it should recognize the revenue upon receipt of the assets from the individual as donor-restricted because it is required to use the assets for Alzheimer's research, which is narrower than NFP DD's overall mission, during the next fiscal year.
Foundation B receives a grant proposal from an animal rescue facility, NFP F, which requests a 2-year grant in the amount of $500,000 upfront to be used to expand its operations. The agreement indicates that NFP F must expand its facility by at least 5,000 square feet to accommodate additional animals by the end of the 2 years. The grant contains a right of return if the minimum expansion target is not achieved.
Foundation B determines that this grant is conditional. The grant includes a measurable barrier (5,000 additional square feet) that must be achieved by NFP F to be entitled to the assets and a right of return for unused assets or unmet requirements.
NFP G is a university that is conducting a capital campaign to build a new building to house its school of mathematics and to make capital improvements to existing buildings on campus, including a new heating system and an upgraded telephone and computer network. NFP G receives an upfront grant in the amount of $10,000 from a foundation as part of its capital campaign. The agreement contains a right of return requiring that the assets be reimbursed to the resource provider if the assets are not used for the purposes outlined in the capital campaign solicitation materials. The resource provider does not include any specifications in the agreement about how the building should be constructed or on how other improvements should be made.
NFP G determines that this grant is not conditional because the agreement places limits only on the specific activity that is being funded (for example, the assets can be used toward the new building or toward other capital improvements such as the heating system and an upgraded telephone and computer network within existing buildings on campus). The resource provider does not include any specifications about how the building should be constructed, and the agreement only indicates that NFP G must use the grant for the purpose outlined in the capital campaign materials. NFP G recognizes this grant as donor-restricted revenue because it must be used for capital purposes, which is narrower than NFP G's overall mission. This Example illustrates a fact pattern in which a grant can include a right of return and would be deemed a contribution that does not contain a donor-imposed condition because the return clause is not coupled with a barrier to be overcome, as determined by NFP G using judgment to assess the indicators of a barrier.
NFP I is a museum that receives a grant from an individual donor to build a new wing on the existing museum building. The agreement contains a $1 million multiyear promise to give the money to be used for the new wing on the building. The agreement also includes specific building requirements, including square footage and that the new wing must be environmentally friendly with Leadership in Energy and Environmental Design certification. The first installment of the gift will not be paid until NFP I submits architectural designs that meet the building requirements. Additional installments of the grant will be paid in specified increments upon achieving other milestones identified in the grant agreement. If a particular milestone is not achieved, the donor is released from its obligation to make installment payments.
NFP I determines that this agreement is conditional because NFP I is not entitled to the assets until a milestone is met (for example, an architectural plan including square footage and Leadership in Energy and Environmental Design certification). In this example, a milestone is deemed a measurable performance barrier because NFP I's entitlement to the transferred assets is contingent upon the completion of a milestone. In addition, the agreement includes a release of the resource provider's obligation to transfer assets if the stipulations are not met. NFP I recognizes the revenue as the barriers are overcome, which is upon meeting the specific requirements as NFP I builds the new wing. The likelihood of meeting a milestone is not a consideration when assessing whether the contribution is deemed conditional.
NFP J operates as a homeless shelter that provides individuals with temporary accommodations, meals, and counseling. NFP J receives an upfront grant of $75,000 from the city for its meals program. The grant requires NFP J to use the assets to provide at least 5,000 meals to the homeless. The grant contains a right of return for meals not served.
NFP J determines that this grant is conditional because it contains a measurable performance-related barrier (to provide 5,000 meals) and a right of return. NFP J recognizes assets received in advance of satisfying the conditions as a refundable advance liability and will then recognize $75,000 as donor-restricted revenue when at least 5,000 meals are served because the purpose of the grant is narrower than the overall purpose of NFP J. The likelihood of providing the meals is not a consideration when assessing whether the contribution is deemed conditional.
NFP H is a recreational organization that provides various sports programs to children that live in the community. NFP H receives an upfront grant in the amount of $40,000 from a foundation to be used toward its tennis program. Consistent with NFP H's grant proposal, the agreement includes specific guidelines for which NFP H could use the assets (for example, to hire 10 tennis instructors or to provide a summer camp for 9 weeks) but does not specify that NFP H's entitlement to the $40,000 is dependent upon NFP H meeting any of the specific indicated guidelines in the agreement. The grant contains a right of return for funds not spent on the tennis program.
NFP H determines that this grant is not conditional because it does not contain a barrier to overcome to be entitled to the transferred assets. Although the grant agreement contains guidelines for how NFP H could spend the $40,000, the agreement does not specify that entitlement to the transferred assets are dependent upon meeting any of the guidelines. Because the guidelines in the grant agreement were not required to be met to be entitled to the funding, the agreement does not contain a barrier to overcome. NFP H should recognize the revenue upon receipt of the assets as donor restricted because it is required to use the assets for the tennis program, which is narrower than NFP H's overall mission.
This Example illustrates the requirements described in paragraph 958-605-50-1A. Those disclosure requirements are not prescriptive on how the information should be disclosed; therefore, this Example demonstrates two alternative formats. This Example does not illustrate all categories of contributed nonfinancial assets, such as intangible assets. An NFP may be required to include disclosure information about valuation techniques and inputs, including assumptions and judgments that an NFP makes, in addition to those included in this Example, which is consistent with the fair value disclosures required by Topic 820. The valuation language used in this Example is not intended to provide guidance on how contributions of nonfinancial assets should be valued, including whether the principal market (or most advantageous market) disclosed is appropriate in the circumstances. While not illustrated in this Example, there may be additional information about the nature and extent of contributed services, including nonrecognized contributed services, that an entity may disclose in accordance with paragraph 958-605-50-1B.
The following illustration includes a table disclosing the amounts recognized within the statement of activities by category as well as a narrative disclosure about donor-imposed restrictions and valuation techniques and inputs for each category of contributed nonfinancial asset.
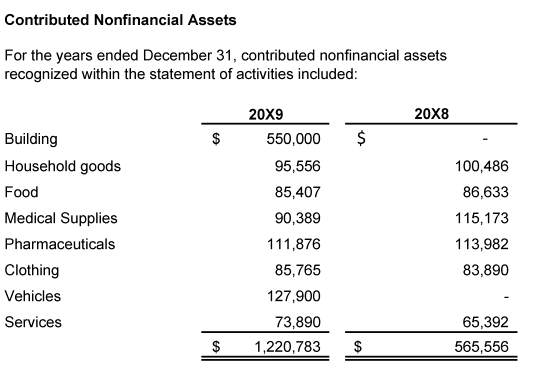 Contributed Nonfinancial Assets "For the years ended December 31, contributed nonfinancial assets recognized within the statement of activities included:" 20X9 20X8 Building Building " $550,000 " $ - Household goods Household goods " 95,556 " " 100,486 " Food Food " 85,407 " " 86,633 " Medical supplies Medical Supplies " 90,389 " " 115,173 " Pharmaceuticals Pharmaceuticals " 111,876 " " 113,982 " Clothing Clothing " 85,765 " " 83,890 " Vehicles Vehicles " 127,900 " - Services Services " 73,890 " " 65,392 " " $1,220,783 " " $565,556 "
- NFP K recognized contributed nonfinancial assets within revenue, including a contributed building, vehicles, household goods, food, medical supplies, pharmaceuticals, clothing, and services. Unless otherwise noted, contributed nonfinancial assets did not have donor-imposed restrictions.
- It is NFP K's policy to sell all contributed vehicles immediately upon receipt at auction or for salvage unless the vehicle is restricted for use in a specific program by the donor. No vehicles received during the period were restricted for use. All vehicles were sold and valued according to the actual cash proceeds on their disposition.
- The contributed building will be used for general and administrative activities. In valuing the contributed building, which is located in Metropolitan Area B, NFP K estimated the fair value on the basis of recent comparable sales prices in Metropolitan Area B's real estate market.
- Contributed food was utilized in the following programs: natural disaster services, domestic community development, and services to community shelters. Contributed household goods were used in domestic community development and services to community shelters. Contributed clothing was used in specific community shelters. Contributed medical supplies were utilized in natural disaster services. In valuing household goods, food, clothing, and medical supplies, NFP K estimated the fair value on the basis of estimates of wholesale values that would be received for selling similar products in the United States.
- Contributed pharmaceuticals were restricted by donors to use outside the United States and were utilized in international health services and natural disaster services. In valuing contributed pharmaceuticals otherwise legally permissible for sale in the United States, NFP K used the Federal Upper Limit based on the weighted average of the most recently reported monthly Average Manufacturer Prices (AMP) that approximate wholesale prices in the United States (that is, the principal market). In valuing pharmaceuticals not legally permissible for sale in the United States (and primarily consumed in developing markets), NFP K used third-party sources representing wholesale exit prices in the developing markets in which the products are approved for sale (that is, the principal markets).
- Contributed services recognized comprise professional services from attorneys advising NFP K on various administrative legal matters. Contributed services are valued and are reported at the estimated fair value in the financial statements based on current rates for similar legal services.
The following table illustrates the disclosures in paragraph 958-605-55-70V for each category of contributed nonfinancial asset. It includes both amounts and narrative disclosure. For illustrative purposes, only one year is presented.
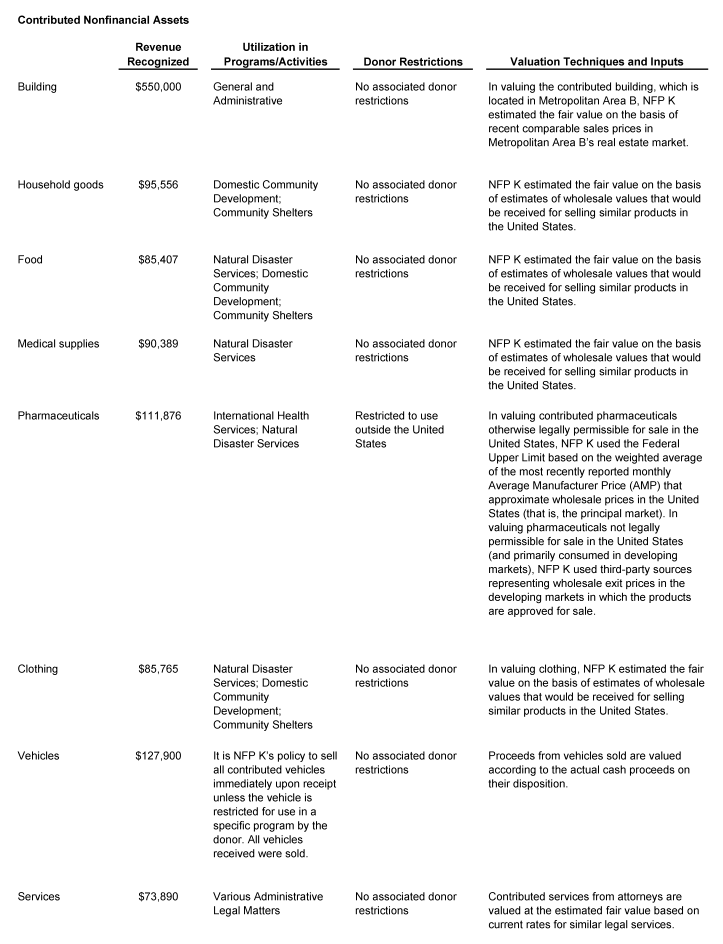 Contributed Nonfinancial Assets "Revenue Recognized" Utilization in Programs/Activities Donor Restrictions Valuation Techniques and Inputs Building "$550,000" General and Administrative No associated donor restrictions "In valuing the contributed building, which is located in Metropolitan Area B, NFP K estimated the fair value on the basis of recent comparable sales prices in Metropolitan Area B's real estate market. " Household goods "$95,556" Domestic Community Development; Community Shelters No associated donor restrictions NFP K estimated the fair value on the basis of estimates of wholesale values that would be received for selling similar products in the United States. Food "$85,407" Natural Disaster Services; Domestic Community Development; Community Shelters No associated donor restrictions NFP K estimated the fair value on the basis of estimates of wholesale values that would be received for selling similar products in the United States. Medical supplies "$90,389" Natural Disaster Services No associated donor restrictions NFP K estimated the fair value on the basis of estimates of wholesale values that would be received for selling similar products in the United States. Pharmaceuticals "$111,876" International Health Services; Natural Disaster Services Restricted to use outside the United States "In valuing contributed pharmaceuticals otherwise legally permissible for sale in the United States, NFP K used the Federal Upper Limit based on the weighted average of the most recently reported monthly Average Manufacturer Price (AMP), that approximate wholesale prices in the United States (that is, the principal market). In valuing pharmaceuticals not legally permissible for sale in the United States (and primarily consumed in developing markets), NFP K used third-party sources representing wholesale exit prices in the developing markets in which the products are approved for sale." Clothing "$85,765" Natural Disaster Services; Domestic Community Development; Community Shelters No associated donor restrictions "In valuing clothing, NFP K estimated the fair value on the basis of estimates of wholesale values that would be received for selling similar products in the United States. " Vehicles "$127,900" It is NFP K's policy to sell all contributed vehicles immediately upon receipt unless the vehicle is restricted for use in a specific program by the donor. All vehicles received were sold. No associated donor restrictions Proceeds from vehicles sold are valued according to the actual cash proceeds on their disposition. Services "$73,890" Various Administrative legal matters No associated donor restrictions Contributed services from attorneys are valued at the estimated fair value based on current rates for similar legal services.
A transfer of assets may appear to be a contribution when a donor uses an agent, a trustee, or an intermediary to transfer assets to a donee. Receipts of resources as an agent, trustee, or intermediary of a donor are not contributions received to the agent because the recipient of assets who is an agent or trustee has little or no discretion in determining how the assets transferred will be used. For the same reason, deliveries of resources as an agent, trustee, or intermediary of a donor are not contributions made by the agent. Similarly, contributions of services (time, skills, or expertise) between donors and donees that are facilitated by an intermediary are not contributions received or contributions made by the intermediary.
Examples 1 through 11 (see paragraphs ) illustrate the need to assess the relevant facts and circumstances to distinguish between the receipt of resources as a donee and the receipt of resources as an agent, a trustee, or an intermediary organization.
The following flowchart is a visual supplement to the written standards. It should not be interpreted to alter any requirements of the Transfers of Assets to a Not-for-Profit Entity or Charitable Trust that Raises or Holds Contributions for Others Subsections or of Subtopic 958-20, nor should it be considered a substitute for those requirements. The relevant paragraphs of the standards are identified in the parenthetical notes. Examples 1 through 11 (see paragraphs ) illustrate the application of the standards in specific situations.
The diagram depicts the process for determining the appropriate accounting for a transfer of assets from a donor to a recipient entity that accepts the assets and agrees to use those assets on behalf of a beneficiary specified by the donor or transfer those assets, the return on investment of those assets, or both to a beneficiary specified by the donor. (For additional information about how a beneficiary is specified, see paragraphs .) The diagram also depicts the process for determining the appropriate accounting for a transfer from a resource provider that takes place in a similar manner but is not a contribution because the transfer is revocable, repayable, or reciprocal.
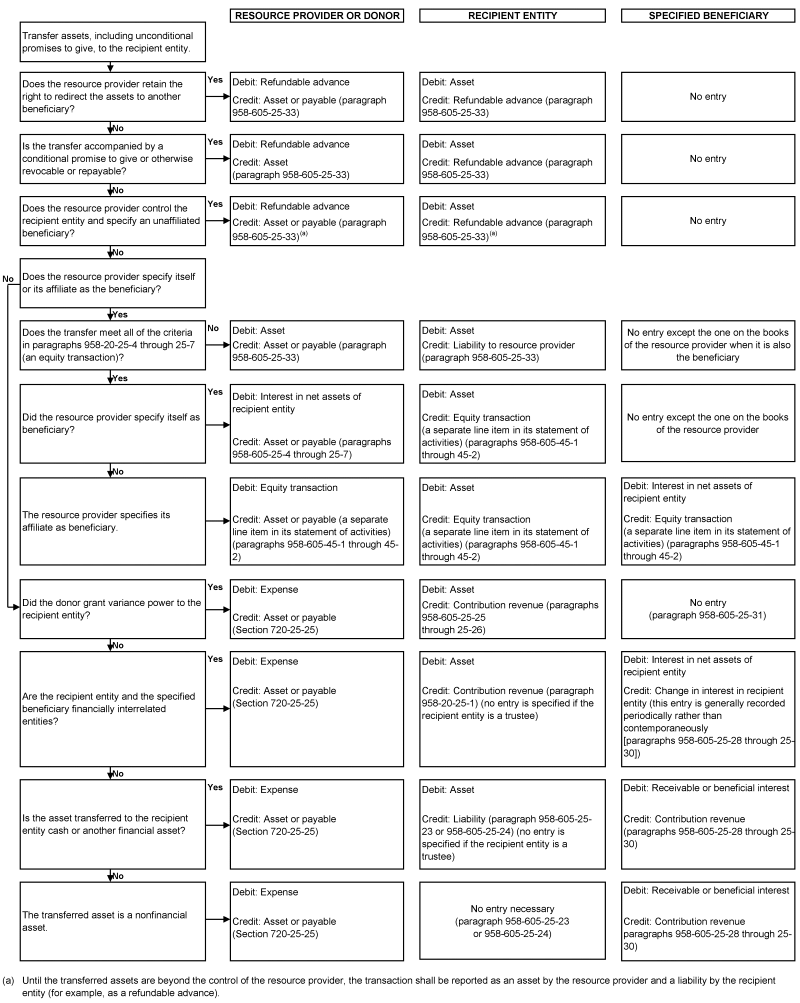 RESOURCE PROVIDER OR DONOR RECIPIENT ENTITY SPECIFIED BENEFICIARY "Transfer assets, including unconditional promises to give, to the recipient entity." Does the resource provider retain the right to redirect the assets to another beneficiary? Yes Debit: Refundable advance Debit: Asset No entry Credit: Asset or payable (paragraph 958-605-25-33) Credit: Refundable advance (paragraph 958-605-25-33) No Is the transfer accompanied by a conditional promise to give or otherwise revocable or repayable? Yes Debit: Refundable advance Debit: Asset No entry "Credit: Asset (paragraph 958-605-25-33)" Credit: Refundable advance (paragraph 958-605-25-33) No Does the resource provider control the recipient entity and specify an unaffiliated beneficiary? Yes Debit: Refundable advance Debit: Asset No entry Credit: Asset or payable (paragraph 958-605-25-33)(a) Credit: Refundable advance (paragraph 958-605-25-33)(a) No " No" Does the resource provider control the recipient entity and specify an unaffiliated beneficiary? Yes Does the transfer meet all of the criteria in paragraphs 958-605-25-4 through 25-7 (an equity transaction)? Yes Debit: Asset Debit: Asset No entry except the one on the books of the resource provider when it is also the beneficiary "Credit: Asset or payable (paragraph 958-605-25-33) " Credit: Liability to resource provider (paragraph 958-605-25-33) Yes Did the resource provider specify itself as beneficiary? Yes Debit: Interest in net assets of recipient entity Debit: Asset No entry except the one on the books of the resource provider "Credit: Equity transaction (a separate line item in its statement of activities) (paragraphs 958-605-45-1 through 45-2)" Credit: Asset or payable (paragraphs 958-605-25-4 through 25-7) No The resource provider specifies its affiliate as beneficiary. Debit: Equity transaction Debit: Asset Debit: Interest in net assets of recipient entity Credit: Credit: Asset or payable (a separate line item in its statement of activities) (paragraphs 958-605-45-1 through 45-2) "Credit: Equity transaction (a separate line item in its statement of activities) (paragraphs 958-605-45-1 through 45-2)" "Credit: Equity transaction (a separate line item in its statement of activities) (paragraphs 958-605-45-1 through 45-2)" Did the donor grant variance power to the recipient entity? Yes Debit: Expense Debit: Asset "No entry (paragraph 958-605-25-31)" "Credit: Asset or payable (Section 720-25-25)" "Credit: Contribution revenue (paragraphs 958-605-25-25 through 25-26)" No Are the recipient entity and the specified beneficiary financially interrelated entities? Yes Debit: Expense Debit: Asset Debit: Interest in net assets of recipient entity "Credit: Asset or payable (Section 720-25-25)" Credit: Contribution revenue (paragraph 958-20-25-1) (no entry is specified if the recipient entity is a trustee) "Credit: Change in interest in recipient entity (this entry is generally recorded periodically rather than contemporaneously [paragraphs 958-605-25-28 through 25-30])" No Is the asset transferred to the recipient entity cash or another financial asset? Yes Debit: Expense Debit: Asset Debit: Receivable or beneficial interest "Credit: Asset or payable (Section 720-25-25)" Credit: Liability (paragraph 958-605-25-23 or 958-605-25-24) (no entry is specified if the recipient entity is a trustee) Credit: Contribution revenue (paragraphs 958-605-25-28 through 25-30) No The transferred asset is a nonfinancial asset. Debit: Expense "No entry necessary (paragraph 958-605-25-23 or 958-605-25-24)" Debit: Receivable or beneficial interest "Credit: Asset or payable (Section 720-25-25)" Credit: Contribution revenue paragraphs 958-605-25-28 through 25-30) (a) "Until the transferred assets are beyond the control of the resource provider, the transaction shall be reported as an asset by the resource provider and a liability by the recipient entity (for example, as a refundable advance)."
Discretion to determine the timing of the distribution to the specified beneficiary, by itself, does not give the recipient entity discretion sufficient to recognize a contribution. That limited discretion is not sufficient. The ability to choose a payment date does not relieve an entity from its obligation to pay.
A recipient entity has discretion sufficient to recognize a contribution received if it can choose the beneficiaries of the assets. For example, if a recipient receives cash that it must disburse to any who meet guidelines specified by a resource provider or return the cash, those receipts may be deposits held by the recipient as an agent rather than contributions received as a donee. Similarly, if a recipient receives cash that it must disburse to individuals identified by a resource provider or return the cash, neither the receipt nor the disbursement is a contribution for the agent, trustee, or intermediary. In contrast, if a resource provider allows the recipient to establish, define, and carry out the programs that disburse the cash, products, or services to the recipient's beneficiaries, the recipient generally is involved in receiving and making contributions.
Thus, if a donor uses broad generalizations to describe beneficiaries or to indicate a field of interest, such as Midwestern flood victims, homeless individuals, or teenaged children, the recipient entity has the ability to choose the beneficiaries of the assets and is a donee. Similarly, the recipient entity has the ability to choose the beneficiaries if neither the language used by the donor nor the representations of the recipient entity cause the donor to believe that it can direct the gift to a specified beneficiary. For example, a recipient entity might request that a donor indicate a not-for-profit entity (NFP) that best serves the needs of the community and tell the donor that the information will be considered by the allocation committee when it makes its distributions to NFPs in the community. If that request is conveyed in a manner that leads a donor to reasonably conclude that its role is merely to propose a possible allocation, the recipient entity has the discretion to choose the beneficiary of the assets.
Conversely, if that request is conveyed in a manner that creates a donor's reasonable expectation that the gift will be used for the benefit of or will be transferred to the indicated beneficiary, the recipient entity does not have discretion to choose the beneficiary unless the donor explicitly grants variance power. (See the following paragraph and paragraph 958-605-25-25.) A donor may specify the beneficiary by name, by stating that all entities that meet a set of donor-defined criteria are beneficiaries, or by actions surrounding the transfer that make clear the identity of the beneficiary, such as by responding to a request from a recipient entity that exists to raise assets for the beneficiary.
A recipient entity may obtain the power to redirect the use of assets transferred to it through various means, including standard provisions in donor-choice forms or explicit donor stipulation in gift instruments. For example, a community foundation may obtain the unilateral power to redirect the use of assets transferred to them through explicit reference to the variance power granted to them by donors in written gift instruments. The variance power may be explicitly referred to in the terms of the gift instrument and further explained in the community foundation's declaration of trust, articles of incorporation, or governing instruments.
This Example illustrates the guidance in paragraphs . Not-for-Profit Entity A (NFP A) receives relief supplies from Individual with instructions to deliver the supplies to specified third-party beneficiaries. NFP A accepts responsibility for delivering those supplies because it has a distribution network and a mutual interest in serving the needs of the specified beneficiaries. NFP A has no discretion in determining the parties to be benefited; it must deliver the resources to the specified beneficiaries. Receipt of those goods is not a contribution received to NFP A, nor is the delivery of those goods to the beneficiaries a contribution made by NFP A. Rather, a contribution of goods is made by Individual and received by the third-party beneficiaries.
This Example illustrates the guidance in paragraph 958-605-25-23. Not-for-Profit Entity B (NFP B) develops and maintains a list of lawyers and law firms that are interested in providing services without charge to charitable organizations and certain individuals. NFP B encourages individuals in need of free legal services to contact NFP B for referral to lawyers in the individual's community that may be willing to serve them. The decision about whether and how to serve a specific individual rests with the lawyer. Under those circumstances, NFP B merely acts as an intermediary in bringing together a willing donor and donee. The free legal services are not a contribution received by NFP B.
This Example illustrates the guidance in paragraphs .
Federated Fundraising Organization D provides three choices to donors in its annual workplace campaign. Donors can give without restriction, direct their gifts to one of four community needs identified by Federated Fundraising Organization D, or specify that their gifts be transferred to an NFP of their choice. The campaign literature informs donors that if they choose to specify an NFP to which their gift should be transferred, the NFP must be a social welfare organization within the community that has tax-exempt status under Internal Revenue Code Section 501(c)(3). The campaign literature also provides a schedule of the administrative fees that will be deducted from all gifts that are to be transferred to the donor's chosen beneficiary.
Federated Fundraising Organization D would recognize the following transactions:
- aIt would recognize the fair values of the gifts without donor restrictions as contribution revenue that increases net assets without donor restrictions.
- bIt would recognize the fair values of the gifts targeted to the four specified community needs as contribution revenue that increases net assets with donor restrictions.
- cIt would recognize the fair values of gifts that are to be transferred to beneficiaries chosen by the donors as increases in its assets and as liabilities to those specified beneficiaries (see paragraph 958-605-25-24).
- dIt would recognize as revenue the administrative fees withheld from amounts to be transferred to the donors' chosen beneficiary.
The beneficiaries chosen by the donors would recognize the fair value of the transferred assets as contribution revenue in accordance with the provisions of paragraph 958-605-45-6 for unconditional promises to give. Thus, the revenue would increase net assets with donor restrictions or net assets without donor restrictions, depending on the existence or absence of donor-imposed restrictions. For example, if a donor specified that the transferred assets must be maintained in perpetuity, the revenue would increase net assets with donor restrictions. However, if the donor specified that the transferred assets are for current-period use, the revenue would increase net assets without donor restrictions. In accordance with paragraph 958-220-45-14, the beneficiaries would report the gross amounts of the gifts as contribution revenue and the administrative fees withheld by Federated Fundraising Organization D as expenses. The net amount would be recognized as a receivable (see paragraph 958-605-25-28).
Instead of conducting the campaign as described in this Example, Federated Fundraising Organization D's campaign literature, including the form that donors use to specify a beneficiary, clearly states that if donors choose to give and specify a beneficiary, the allocation committee has the authority to redirect their gifts if the committee perceives needs elsewhere in the community that are greater. By giving under those terms, donors explicitly grant Federated Fundraising Organization D variance power. Thus, Federated Fundraising Organization D would recognize as contribution revenue without donor-imposed restrictions (see paragraph 958-605-25-25), and the specified beneficiaries would be precluded from recognizing their potential for future distributions from the assets (see paragraph 958-605-25-31).
This Example illustrates the guidance in paragraphs .
The governing board of City Botanical Society E decides to raise funds to build an endowment. The governing board signs an agreement to establish a fund at Community Foundation F. Community Foundation F and City Botanical Society E are not financially interrelated entities. City Botanical Society E solicits gifts to the fund. The campaign materials inform donors that the endowment will be owned and held by Community Foundation F. The materials explain that the gifts will be invested and that the return from their investment will be distributed to City Botanical Society E, subject to Community Foundation F's spending policy and to Community Foundation F's right to redirect the return to another beneficiary without the approval of the donor, City Botanical Society E, or any other party if distributions to City Botanical Society E become unnecessary, impossible, or inconsistent with the needs of the community. The donor-response card also clearly describes Community Foundation F's right to redirect the return of the fund. The campaign materials indicate that donors should send their contributions to Community Foundation F using a preaddressed envelope included for that purpose.
Community Foundation F would recognize the fair value of gifts received as assets and as contribution revenue. The donors explicitly granted variance power by using a donor-response card that clearly states that gifts are subject to Community Foundation F's unilateral power to redirect the return to another beneficiary (see paragraph 958-605-25-25).
City Botanical Society E is precluded from recognizing its potential rights to the assets held by Community Foundation F because the donors explicitly granted variance power (see paragraph 958-605-25-31). City Botanical Society E would recognize only its annual grants from Community Foundation F as contributions.
Whether a donor intended to make a contribution to Community Foundation F may not be clear if the donor responds to the campaign materials by sending a contribution and the donor-response card directly to City Botanical Society E. City Botanical Society E could resolve the ambiguity by a review of the facts and circumstances surrounding the gift, communications with the donor, or both. If it is ultimately determined that the donor intended to make a gift to the fund owned and held by Community Foundation F and to explicitly grant variance power, City Botanical Society E would be an agent responsible for transferring that gift to Community Foundation F (see paragraph 958-605-25-24).
This Example illustrates the guidance in paragraph 958-605-25-23.
Local Church G transfers cash to Seminary H and instructs Seminary H to use the money to grant a scholarship to Individual, who is a parishioner of Local Church G.
Seminary H would recognize the cash and a liability to Individual in the same amount because it merely is facilitating the cash transfer from Local Church G to Individual (see paragraph 958-605-25-23).
This Example illustrates the guidance in paragraph 958-605-15-9.
Individual transfers assets to National Bank J to establish an irrevocable charitable trust for the sole benefit of Museum I. National Bank J will serve as trustee. Individual sets forth in the trust agreement the policies that direct the economic activities of the trust. The trust term is five years. Each year, the income received on the investments of the trust will be distributed to Museum I. At the end of Year 5, the corpus of the trust (original assets and net appreciation on those assets) will be paid to Museum I.
The Contribution Received Subsections of this Subtopic do not establish standards for the trustee, National Bank J (see paragraph 958-605-15-9). Because Museum I is unable to influence the operating or financial decisions of the trustee, Museum I and National Bank are not financially interrelated entities. Therefore, Museum I would recognize its asset (a beneficial interest in the trust) and contribution revenue that increases net assets with donor restrictions (see paragraph 958-605-35-3). Museum I would measure its beneficial interest at fair value. That value generally can be measured by the fair value of the assets contributed to the trust.
This Example illustrates the guidance in paragraph 958-20-15-2.
Some foundations and associations raise contributions for a large number of unaffiliated NFPs, often referred to as member organizations. By virtue of their numbers, those member organizations generally do not individually influence the operating and financial decisions of the foundation (or association). Thus, any one member organization and the foundation (or association) are not financially interrelated entities (see paragraph 958-20-15-2[a]). Because the entities are not financially interrelated, the foundation (or association) recognizes a liability if a donor to the foundation (or association) specifies that the gift should be transferred to a particular member organization (see paragraph 958-605-25-4). The specified member organization would recognize a receivable and contribution revenue that increases net assets with donor restrictions or net assets without donor restrictions, depending on the existence or absence of donor-imposed restrictions.
This Example illustrates the guidance in paragraph 958-605-25-4.
Individual transfers a car to Federated Fundraising Organization K and requests that the car be transferred to Local Daycare Center L. Individual specifies that Federated Fundraising Organization K may use the car for one year before transferring it to Local Daycare Center L. Local Daycare Center L is a member organization of Federated Fundraising Organization K, but that status does not confer any ability to actively participate in the policymaking processes of Federated Fundraising Organization K.
Because Federated Fundraising Organization K and Local Daycare Center L are not financially interrelated entities, Federated Fundraising Organization K would recognize the car as an asset and a liability to Local Daycare Center L if its policy were to recognize nonfinancial assets; otherwise, it would recognize neither the nonfinancial assets nor a liability (see paragraph 958-605-25-24).
If, instead of refusing the gift of the use of the car, Federated Fundraising Organization K decides to use it for a year before transferring it to Local Daycare Center L, Federated Fundraising Organization K would recognize the fair value of the gift of one-year's use of the car in accordance with paragraph 958-605-30-2. The use of a car is a contributed asset and not a contributed service.
Local Daycare Center L would recognize a receivable and contribution revenue that increases net assets with donor restrictions (see paragraph 958-605-25-30). It would measure the contribution received at the fair value of the car; however, if Federated Fundraising Organization L chooses to use the car for a year before transferring it, the fair value would be reduced accordingly.
This Example illustrates the guidance in paragraph 958-605-25-33.
Symphony Orchestra M receives a large gift without donor restrictions of securities from Individual. Because it has no investment expertise, Symphony Orchestra M transfers the securities to Community Foundation N to establish an endowment fund. The agreement between Symphony Orchestra M and Community Foundation N states that the transfer is irrevocable and that the transferred assets will not be returned to Symphony Orchestra M. However, Community Foundation N will make annual distributions of the income earned on the endowment fund, subject to Community Foundation N's spending policy. The agreement also permits Community Foundation N to substitute another beneficiary in the place of Symphony Orchestra M if Symphony Orchestra M ceases to exist or if the governing board of Community Foundation N votes that support of Symphony Orchestra M either is no longer necessary or is inconsistent with the needs of the community. (That is, Symphony Orchestra M explicitly grants variance power to Community Foundation N.) The agreement does not permit either entity to appoint members to the other entity's governing board or otherwise participate in the policymaking processes of the other.
Community Foundation N would recognize the fair value of the transferred securities as an increase in investments and a liability to Symphony Orchestra M because Symphony Orchestra M transferred assets to Community Foundation N and specified itself as beneficiary (see paragraph 958-605-25-33(d)). The transfer is not an equity transaction because Community Foundation N and Symphony Orchestra M are not financially interrelated entities (see paragraph 958-20-25-4(b)). Symphony Orchestra M is unable to influence the operating or financial decisions of Community Foundation N (see paragraph 958-20-15-2(a)).
Symphony Orchestra M would recognize the fair value of the gift of securities from Individual as contribution revenue. When it transfers the securities to Community Foundation N, it would recognize the transfer as a decrease in investments and an increase in an asset, for example, as a beneficial interest in assets held by Community Foundation N (see paragraph 958-605-25-33(d)). Also, Symphony Orchestra M would disclose in its financial statements the identity of Community Foundation N, the terms under which Community Foundation N will distribute amounts to Symphony Orchestra M, a description of the variance power granted to Community Foundation N, and the aggregate amount reported in the statement of financial position and how that amount is described (see paragraph 958-605-50-6).
If a resource provider transfers assets to a recipient entity and specifies itself or its affiliate as the beneficiary, a presumption that the transfer is reciprocal, and therefore not a contribution, is necessary even if the resource provider explicitly grants the recipient entity variance power. Thus, Symphony Orchestra M would recognize an asset and Community Foundation N would recognize a liability because the transaction is deemed to be reciprocal. Symphony Orchestra M transfers its securities to Community Foundation N in exchange for future distributions. Community Foundation N, by its acceptance of the transfer, agrees that at the time of the transfer distributions to Symphony Orchestra M are capable of fulfillment and consistent with the foundation's mission. Although the fair value of those future distributions may not be commensurate with the fair value of the securities given up (because Symphony Orchestra M is at risk of cessation of the distributions), the transaction is accounted for as though those values are commensurate. In comparison, the donors to Community Foundation F in Example 5 (see paragraph 958-605-55-88) explicitly grant variance power to Community Foundation F in a nonreciprocal transfer. In that Example, it is clear that the donors have made a contribution because they retain no beneficial interests in the transferred assets. Because the donors in that Example explicitly grant variance power to Community Foundation F, it, rather than City Botanical Society E, is the recipient of that contribution.
This Example illustrates the guidance in paragraph 958-605-25-33.
The governing board of Private Elementary School O creates a foundation to hold and manage the school's investments. It transfers its investment portfolio to the newly created PES Foundation P. An agreement between Private Elementary School O and PES Foundation P allows the school to request distributions from both the original investments and the return on those investments, subject to approval by the governing board of PES Foundation P, which will not be unreasonably withheld. The agreement also permits Private Elementary School O to transfer additional investments in the future.
PES Foundation P would recognize the fair value of the investments as assets and a liability to Private Elementary School O because Private Elementary School O transferred assets to PES Foundation P and specified itself as beneficiary (see paragraph 958-605-25-33[d]). The transfer of assets is not an equity transaction because Private Elementary School O expects repayment of the transferred assets, and thus the transaction does not meet the criterion in paragraph 958-20-25-4(c).
Private Elementary School O would decrease its investments and recognize another asset, for example, a beneficial interest in assets held by PES Foundation P (see paragraph 958-605-25-33[d]). Also, Private Elementary School O would disclose in its financial statements the identity of PES Foundation P, the terms of the agreement under which it can receive future distributions, including the fact that the distributions are not subject to variance power, and the aggregate amount reported in the statement of financial position and how that amount is described (see paragraph 958-605-50-6).
See Subtopic 958-20 if Private Elementary School O and PES Foundation P are financially interrelated entities.
Page 2147480552
If consolidated financial statements are presented, the reporting entity (parent) shall disclose any restrictions made by entities outside of the reporting entity on distributions from the controlled not-for-profit entity (NFP) (subsidiary) to the parent and any resulting unavailability of the net assets of the subsidiary for use by the parent.
If, as described in paragraph 958-810-25-4, an NFP (the reporting entity) controls a related but separate NFP through a form other than majority ownership interest, sole corporate membership, or majority voting interest in the board of the other entity and has an economic interest in that other NFP, the reporting entity shall disclose all of the following information if it does not present consolidated financial statements:
- a Identification of the other NFP and the nature of its relationship with the reporting entity that results in control
- b Summarized financial data of the other NFP, which shall include the following information:
- 1 Total assets, liabilities, net assets, revenue, and expenses
- 2 Resources that are held for the benefit of the reporting entity or that are under its control.
- 1
- c The disclosures required by paragraphs .
The existence of control or an economic interest, but not both, as described in paragraph 958-810-25-5, requires the disclosures in paragraphs . (The existence of an economic interest does not necessarily cause the entities to be related parties. However, the disclosures in those paragraphs are required if an economic interest exists.)
An NFP (parent) that has one or more consolidated subsidiaries with a noncontrolling interest shall provide a schedule of changes in consolidated net assets attributable to the parent and the noncontrolling interest either in notes to the consolidated financial statements or on the face of financial statements, if practicable. That schedule shall reconcile beginning and ending balances of the parent's controlling interest and the noncontrolling interests for each class of net assets for which a noncontrolling interest exists during the reporting period.
The schedule required by the preceding paragraph shall, at a minimum, include:
- a A performance indicator, if the entity is a not-for-profit, business-oriented health care entity (see Section 954-10-15)
- b Amounts of discontinued operations
- c
- d Changes in ownership interests in a subsidiary, including investments by and distributions to noncontrolling interests acting in their capacity as owners, which shall be reported separate from any revenues, expenses, gains, or losses and outside any measure of operations, if reported
- e An aggregate amount of all other changes in net assets without donor restrictions and net assets with donor restrictions for the period.
Paragraph 958-810-55-25 illustrates the required disclosures using a reconciling schedule in notes to the consolidated financial statements.
Page 2147480553
This Subsection provides initial measurement guidance for contributions received, including the following types of contributions:
- aUnconditional promises to give
- bInventory items
- cContributed services
- dGifts in kind.
Contributions received shall be measured at their fair values. Topic 820 establishes a framework for measuring fair value. See the Fair Value Option Subsections of Subtopic 825-10 for guidance about electing at initial recognition to subsequently measure financial instruments and certain other contracts at fair value.
Paragraph 820-10-35-2B states that a fair value measurement takes into account the effect of a restriction on the sale or use of an asset if market participants would take into account the effect of the restriction when pricing the asset. Example 6 (see paragraph 820-10-55-51) illustrates that restrictions that are a characteristic of an asset, and, therefore, would transfer to a market participant, are the only restrictions reflected in fair value. Donor restrictions that are specific to the donee are reflected in the classification of net assets, not in the measurement of fair value.
If present value techniques are used to measure the fair value of unconditional promises to give, the entity shall determine the amount and timing of the future cash flows of unconditional promises to give cash (or, for promises to give noncash assets, the quantity and nature of assets expected to be received). In making that determination, the entity shall consider all the elements in paragraph 820-10-55-5, including the following:
- a When the receivable is expected to be collected
- b The creditworthiness of the other parties
- c The entity's past collection experience
- d The entity's policies concerning the enforcement of promises to give
- e Expectations about possible variations in the amount or timing of the cash flows (that is, the uncertainty inherent in the cash flows)
- f Other factors concerning the receivable's collectibility.
If present value techniques are used to measure fair value, the present value of unconditional promises to give should be measured using a discount rate that is consistent with the general principles for present value measurement discussed in paragraphs . In conformity with paragraph 835-30-25-11, the discount rate shall be determined at the time the unconditional promise to give is initially recognized and shall not be revised subsequently unless the entity has elected to measure the promise to give at fair value in conformity with the Fair Value Option Subsections of Subtopic 825-10.
Unconditional promises to give that are expected to be collected in less than one year may be measured at net realizable value because that amount results in a reasonable estimate of fair value.
If a promise to give has not previously been recognized as contribution revenue because it was conditional, fair value shall be measured when the conditions are met.
A present value technique is one valuation technique for measuring the fair value of an unconditional promise to give noncash assets; other valuation techniques also are available, as described in Topic 820. If present value techniques are used, the fair value of contributions arising from unconditional promises to give noncash assets might be determined based on the present value of the projected fair value of the underlying noncash assets at the date that those assets are expected to be received (that projected fair value is referred to in this Section as the future fair value) and in the quantities that those assets are expected to be received, if the date is one year or more after the financial statement date. Both the likelihood of the promise being fulfilled and the future fair value of those underlying assets, such as the future fair value per share of a promised equity security, should be considered in determining the future amount to be discounted. The quantity, nature, and timing of assets expected to be received, such as the number of shares of a promised equity security, the entity in which those shares represent an equity interest, and when those shares will be received should be considered in determining the likelihood of the promise being fulfilled. In cases in which the future fair value of the underlying asset is difficult to determine, the fair value of an unconditional promise to give noncash assets may be based on the fair value of the underlying asset at the date of initial recognition. No discount for the time value of money shall be reported if an asset's fair value at the date of initial recognition is used to measure the fair value of the contribution.
Inputs for measuring fair value of contributed inventory items may be obtained from published catalogs, vendors, independent appraisals, and other sources. If methods such as estimates, averages, or computational approximations, such as average value per pound or subsequent sales, can reduce the cost of measuring the fair value of inventory, use of those methods is appropriate, provided the methods are applied consistently, and the results of applying those methods are reasonably expected not to be materially different from the results of a detailed measurement of the fair value of contributed inventory.
Contributions of services that create or enhance nonfinancial assets may be measured by referring to either the fair value of the services received or the fair value of the asset or of the asset enhancement resulting from the services. Fair value should be used for the measure regardless of whether the NFP could afford to purchase the services at their fair value.
Gifts in kind that can be used or sold shall be measured at fair value. In determining fair value, entities should consider the quality and quantity of the gifts, as well as any applicable discounts that would have been received by the entity, including discounts based on that quantity if the assets had been acquired in exchange transactions. Fair value would generally not increase when a gift in kind is passed from one entity to another. However, fair value could increase if an entity adds value to the gift, such as by cleaning and packaging the gift. Any increases should be evaluated to determine whether the entity did, in fact, add to the fair value of the assets.
Both the liability and the assets shall be measured at the fair value of the assets received from the donor.
Both the liability and the assets shall be measured at the fair value of the assets received from the donor.
If the beneficiary has an unconditional right to receive all or a portion of the specified cash flows from a charitable trust or other identifiable pool of assets, the beneficiary shall measure that beneficial interest at fair value. The fair value of a perpetual trust held by a third party generally can be measured using the fair value of the assets contributed to the trust, unless facts and circumstances indicate that the fair value of the beneficial interest differs from the fair value of the assets contributed to the trust. If the beneficiary recognizes a receivable pursuant to paragraph 958-605-25-30, the beneficiary shall measure its rights to the assets held by a recipient entity at fair value in accordance with paragraph 958-605-30-2 and paragraphs for unconditional promises to give.
Page 2147480583
Except as provided in paragraphs (related to contributed services, works of art, historical treasures, and similar items), contributions received shall be recognized as revenues or gains in the period received and as assets, decreases of liabilities, or expenses depending on the form of the benefits received. The classification of contributions received as revenues or gains depends on whether the transactions are part of the NFP's ongoing major or central activities (revenues), or are peripheral or incidental to the NFP (gains). A contribution made and a corresponding contribution received generally are recognized by both the donor and the donee at the same time, that is, when made or received, respectively, or if conditional, when the barrier is overcome. The definition of a contribution encompasses both a transfer of cash or other assets to an entity and a reduction, settlement, or cancellation of its liabilities.
After a contribution has been deemed not to contain a donor-imposed condition (see paragraphs ), an entity shall consider whether the contribution includes a donor-imposed restriction, which includes the consideration about how broad or narrow the purpose of the agreement is and whether the resources can be used only after a specified date.
Donor-imposed restrictions place limits on the use of contributed resources and may affect an entity's performance and its ability to provide services. However, limitations on the use of donated resources do not change the fundamental nature of the contribution transaction or conclusions about when to recognize the underlying event.
A major uncertainty about the existence of value may indicate that an item received or given should not be recognized. For example, a gift of clothing or furniture has no value unless it can be utilized in either of the following ways:
- a Used internally by the not-for-profit entity (NFP) or for program purposes
- b Sold by the NFP.
However, contributed tangible property worth accepting generally possesses the common characteristic of all assets—future economic benefit or service potential. The future economic benefit or service potential of a tangible item usually can be obtained by exchanging it for cash or by using it to produce goods or services. Certain forms of contributed resources may be more difficult to measure reliably than others, but the form of the contributed resources alone should not change conclusions about whether to recognize the underlying event.
A donor-imposed condition must have both:
- a One or more barriers that must be overcome before a recipient is entitled to the assets transferred or promised
- b A right of return to the contributor for assets transferred (or for a reduction, settlement, or cancellation of liabilities) or a right of release of the promisor from its obligation to transfer assets (or reduce, settle, or cancel liabilities).
For a donor-imposed condition to exist, it must be determinable from the agreement (or another document referenced in the agreement) that a recipient is only entitled to the transferred assets or a future transfer of assets if it has overcome the barrier. An agreement does not need to include the specific phrase right of return or release from obligation; however, an agreement should be sufficiently clear to be able to support a reasonable conclusion about when a recipient would be entitled to the transfer of assets. In the absence of any apparent indication that a recipient is only entitled to the transferred assets or a future transfer of assets if it has overcome a barrier, the agreement shall not be considered to contain a right of return of assets transferred or a right of release from obligation and shall be deemed a contribution without donor-imposed conditions.
An entity must evaluate the facts and circumstances of an agreement to determine whether a stipulation represents a barrier that must be overcome before the recipient is entitled to the assets transferred or promised. A barrier often places specific requirements on an organization about the use of the transferred assets to be entitled to those assets. A probability assessment about whether the recipient is likely to meet the stipulation is not a factor when determining whether an agreement contains a barrier. In cases of ambiguous donor stipulations, see paragraph 958-605-25-5E.
The following table contains a list of indicators that may be helpful in determining whether an agreement contains a barrier. Depending on the facts and circumstances, some indicators may be more significant than others, and no single indicator shall be determinative. See paragraphs and for implementation guidance and illustrative examples on determining whether a contribution is conditional.
| Indicates a Barrier | |
| Measurable Performance-Related Barrier or Other Measurable Barrier | The agreement includes a measurable performance-related barrier or other measurable barrier. Measurable performance-related barriers or other measurable barriers often are coupled with a time limitation (for example, indicating that the outcomes are to be achieved within a specified time frame). Examples of measurable performance-related barriers include a requirement that indicates that a recipient's entitlement to transferred assets is contingent upon the achievement of any of the following:
Other measurable barriers stipulate that a recipient is entitled to the resources if an identified event occurs (for example, a matching requirement). |
| Limited Discretion by the Recipient on the Conduct of an Activity | The recipient has limited discretion over the manner in which an activity can be conducted. Limited discretion of the recipient is more specific than a donor-imposed restriction. Restrictions limit the use of a contribution to a specific activity or time but do not necessarily place limitations on how the activity is performed. Examples of limited discretion could include a requirement to follow specific guidelines about incurring qualifying expenses, a requirement to hire specific individuals as part of the workforce conducting the activity (such as the hiring of specified employees or an identified professor at a university), and a specific protocol that must be adhered to. |
| Stipulations That Are Related to the Purpose of the Agreement | The stipulations are related to the purpose of the agreement. Examples could include a requirement for (a) a homeless shelter to provide a specified number of meals to the homeless (also an example of a measurable performance-related barrier), (b) an animal shelter to expand its facility to accommodate a specified number of additional animals, and (c) a research report that summarizes the findings from a grant on gluten-related allergies. A stipulation that is unrelated to the purpose of the agreement (for example, administrative and trivial stipulations) is not indicative of a barrier. Administrative and trivial stipulations could include routine reporting such as a requirement to provide (a) an annual report or (b) a report that summarizes the recipient's performance to demonstrate the underlying actions that were taken to meet the barrier(s) specified in the agreement. For example, a report that indicates the number of meals that a homeless shelter provided to the homeless is typically not a stipulation that would contribute to achieving the purpose of the agreement. Rather, the action of providing a specified number of meals to the homeless would meet the stipulation that is required by a recipient to achieve the purpose of the agreement. |
Determining whether a contribution is conditional can be difficult if it contains donor stipulations that do not clearly state whether both:
- a One or more barriers exist
- b The right to receive or retain payment or delivery of the promised assets depends on meeting those barriers.
A transfer of assets that is a conditional contribution shall be accounted for as a refundable advance until the conditions have been substantially met or explicitly waived by the donor.
This Subsection provides additional guidance for the following types of contributed assets:
- aPromises to give
- bContributed services
- cWorks of art, historical treasures, and similar items
- dItems given for use in fundraising.
The recognition guidance in the Contributions Received Subsections depends on whether the promise to give is unconditional or conditional as follows.
Pursuant to paragraph 958-605-25-2, an unconditional promise to give shall be recognized when it is received. However, to be recognized there must be sufficient evidence in the form of verifiable documentation that a promise was made and received.
A communication that does not indicate clearly whether it is a promise is considered an unconditional promise to give if it indicates an unconditional intention to give that is legally enforceable. Legal enforceability refers to the availability of legal remedies, not the intent to use them.
Solicitations for donations that clearly include wording such as information to be used for budget purposes only or that clearly and explicitly allow resource providers to rescind their indications that they will give are intentions to give rather than promises to give and shall not be reported as contributions.
Conditional promises to give, which contain donor-imposed conditions that represent a barrier that must be overcome as well as a right of release from obligation, shall be recognized when the condition or conditions on which they depend are substantially met, that is, when a conditional promise becomes unconditional. Imposing a condition creates a barrier that must be overcome before the recipient is entitled to the assets promised. For example, a promise to contribute cash if a like amount of new gifts is raised from others within 30 days and a provision that the cash will not be transferred if the gifts are not raised impose a condition on which entitlement to a promised gift depends.
A transfer of assets after a conditional promise to give is made and before the conditions are met is the same as a transfer of assets that is a conditional contribution (see paragraph 958-605-25-5F). A change in the original conditions of the agreement between promisor and promisee shall not be implied without an explicit waiver (see paragraph 958-605-35-2).
Absence of a specified time for transfer of cash or other assets, by itself, does not necessarily lead to a determination that a promise to give is ambiguous. If the parties fail to express the time or place of performance and performance is unconditional, performance within a reasonable time after making a promise is an appropriate expectation; similarly, if a promise is conditional, performance within a reasonable time after fulfilling the condition is an appropriate expectation. Promises to give that are silent about payment terms but otherwise are clearly unconditional shall be accounted for as unconditional promises to give.
Contributions of services shall be recognized if the services received meet any of the following criteria:
- a They create or enhance nonfinancial assets.
- b They require specialized skills, are provided by individuals possessing those skills, and would typically need to be purchased if not provided by donation. Services requiring specialized skills are provided by accountants, architects, carpenters, doctors, electricians, lawyers, nurses, plumbers, teachers, and other professionals and craftsmen.
For services received from personnel of an affiliate that directly benefit the recipient NFP and for which the affiliate does not charge the recipient NFP, the guidance in Subtopic 958-720 shall be followed. Charging the recipient NFP means requiring payment from the recipient NFP at least for the approximate amount of the direct personnel costs (for example, compensation and any payroll-related fringe benefits) incurred by the affiliate in providing a service to the recipient NFP or the approximate fair value of that service.
Contributions of works of art, historical treasures, and similar items that are not part of a collection shall be recognized as assets and as revenue or gains in financial statements pursuant to paragraph 958-360-25-2.
An entity need not recognize contributions of works of art, historical treasures, and similar assets if the donated items are added to collections that meet all three of the criteria in the definition of a collection. Contributed collection items shall be recognized as revenues or gains if collections are capitalized and shall not be recognized as revenues or gains if collections are not capitalized. An entity that does not recognize and capitalize its collections or that capitalizes collections prospectively shall disclose the additional information required by paragraphs 958-360-45-3 and 958-360-45-5.
NFPs may also receive items, such as tickets, gift certificates, works of art, and merchandise, that are to be used for fundraising purposes by transferring them to other resource providers (the ultimate resource provider or recipient) during fundraising events. Those gifts in kind can be linked to asset transfers from the original resource providers to the ultimate resource providers (recipients) because they are, in substance, part of the same transaction; those gifts in kind shall be reported as contributions and measured at fair value when originally received by an NFP. The difference between the amount received for those items from the ultimate resource providers (recipients) and the fair value of the gifts in kind when originally contributed to the NFP shall be recognized as adjustments to the original contributions when the items are transferred to the ultimate resource providers (recipients).
This Subsection provides recognition guidance for the following types of recipients of donated assets:
- aIntermediaries
- bAgents
- cSpecified beneficiaries.
It also provides guidance for transfers to a recipient entity that are not recognized as contributions because of any of the following conditions:
- aThe transfer is revocable.
- bThe transfer is repayable.
- cThe transfer is reciprocal.
If an intermediary receives cash or other financial assets, it shall recognize its liability to the specified beneficiary concurrent with its recognition of the assets received from the donor. If an intermediary receives nonfinancial assets, it is permitted, but not required, to recognize its liability and those assets provided that the intermediary reports consistently from period to period and discloses its accounting policy. While not required, a not-for-profit entity (NFP) may choose to present its individual assets and liabilities by net asset class, in which case those assets and liabilities attributable to the agency transaction would be reported in the net assets without donor restrictionsclass.
Except as described in paragraphs 958-605-25-25 and 958-605-25-27, a recipient entity that accepts assets from a donor and agrees to use those assets on behalf of or transfer those assets, the return on investment of those assets, or both to a specified beneficiary is not a donee. It shall recognize its liability to the specified beneficiary concurrent with its recognition of cash or other financial assets received from the donor. Except as described in those paragraphs, a recipient entity that receives nonfinancial assets is permitted, but not required, to recognize its liability and those assets provided that the recipient entity reports consistently from period to period and discloses its accounting policy. Similar to the guidance in paragraph 958-605-25-23, those assets and liabilities would be reported in the net assets without donor restrictions class.
A recipient entity that is directed by a donor to distribute the transferred assets, the return on investment of those assets, or both to a specified unaffiliated beneficiary acts as a donee, rather than an agent, trustee, or intermediary, if the donor explicitly grants the recipient entity variance power—that is, the unilateral power to redirect the use of the transferred assets to another beneficiary.
Although variance power has the appearance of being conditional, the asserted condition is not effective for the following reasons:
- a The condition can be substantially met solely by a declaration of the governing board of the recipient entity that states that a distribution to a specified beneficiary is unnecessary, incapable of fulfillment, or inconsistent with the charitable needs of the community or not-for-profit entities (NFPs) being served.
- b The variance power is unilateral—exercise of the power does not require approval from the donor, beneficiary, or any other interested party.
If a recipient entity and a specified beneficiary are financially interrelated entities and the recipient entity is not a trustee, the recipient entity shall recognize a contribution received when it receives assets (financial or nonfinancial) from the donor that are specified for the beneficiary.
A specified beneficiary shall recognize its rights to the assets (financial or nonfinancial) held by a recipient entity as an asset unless the recipient entity is explicitly granted variance power (see paragraph 958-605-25-25). Those rights are any one of the following:
- a An interest in the net assets of the recipient entity (see paragraph 958-605-25-32)
- b A beneficial interest
- c A receivable.
If the beneficiary has an unconditional right to receive all or a portion of the specified cash flows from a charitable trust or other identifiable pool of assets, the beneficiary shall recognize that beneficial interest.
If the beneficiary's rights are neither an interest in the net assets of the recipient entity (see paragraph 958-605-25-32) nor a beneficial interest (see the preceding paragraph), a beneficiary shall recognize its rights to the assets held by a recipient entity as a receivable and contribution revenue in accordance with paragraphs and 958-605-45-5 for unconditional promises to give.
If the donor explicitly grants a recipient entity variance power, the specified unaffiliated beneficiary shall not recognize its potential for future distributions from the assets held by the recipient entity. Those future distributions, if they occur, shall be recognized as contributions by the specified beneficiary when received or unconditionally promised.
Pursuant to paragraph 958-20-25-2, if the beneficiary and the recipient entity are financially interrelated entities, the beneficiary shall recognize its interest in the net assets of the recipient entity. See Subtopic 958-20 for additional information about transactions involving financially interrelated entities.
A transfer of assets to a recipient entity is not a contribution and shall be accounted for as an asset by the resource provider and as a liability by the recipient entity if any of the following conditions are present:
- a The transfer is subject to the resource provider's unilateral right to redirect the use of the assets to another beneficiary.
- b The transfer is accompanied by the resource provider's conditional promise to give or is otherwise revocable or repayable.
- c
- d The resource provider specifies itself or its affiliate as the beneficiary and the transfer is not an equity transaction (see paragraph 958-20-25-4).
Page 2147482381
Investments in other agricultural cooperatives shall be accounted for at cost, including allocated equities and retains. For this purpose, cost means the amount of any cash investment and the face amount of all written notices of allocation in the form of per-unit retains, capital equity credits, revolving fund certificates, and certificates of equity.
Investments in cooperatives shall be accounted for at cost, including allocated equities and retains.
For patrons, the retains represent investments in the cooperative. Patrons shall record the per-unit retains at face value.