ASC

ASC 220-958

Not-for-Profit Entities

220 Income Statement—Reporting Comprehensive Income

Source downloaded: .Record version 62f2b09f0328. Effective date must be checked in the source.

ASC 220-958 governs the not-for-profit statement of activities — the NFP substitute for a business entity's income statement. It requires the statement to focus on the entity as a whole and report the change in total net assets, the change in net assets with donor restrictions, and the change in net assets without donor restrictions, with revenues, expenses, gains, losses, and reclassifications classified among those net asset classes. It addresses how to report these elements (including gross versus net display, investment return net of investment expenses, and optional intermediate measures of operations), but not when to recognize or how to measure them.

Key points (7)
  • A statement of activities must focus on the entity as a whole and report the change in net assets, the change in net assets with donor restrictions, and the change in net assets without donor restrictions, articulating to net assets in the statement of financial position (220-958-45-1 through 45-2).
  • Revenues are reported as increases in net assets without donor restrictions unless the donor limits use; donor-restricted contributions are donor-restricted support increasing net assets with donor restrictions, though restrictions met in the same period may be reported without donor restrictions if the policy is consistent and disclosed (220-958-45-5 through 45-6; 45-24).
  • Expenses are reported as decreases in net assets without donor restrictions, except investment expenses, which are netted against investment return in the net asset class where the return is reported (220-958-45-7).
  • Gains and losses on investments and other assets increase or decrease net assets without donor restrictions unless restricted by explicit donor stipulation or by law extending donor restrictions (220-958-45-8; 45-22).
  • Reclassifications between net asset classes are required when purposes are fulfilled, restrictions expire with time or death of a split-interest beneficiary, restrictions are removed by donor or court, or a donor imposes new restrictions (220-958-45-13).
  • Revenues and expenses of ongoing major or central activities are generally reported gross; peripheral or incidental transactions (including qualifying special events, netting only direct costs) may be reported net, and non-programmatic investment return must be reported net of external and direct internal investment expenses (220-958-45-14 through 45-19).
  • An intermediate measure of operations is optional but, if presented, must appear in a statement that at minimum reports the change in net assets without donor restrictions, must include impairment losses, exit/disposal costs, and certain long-lived asset gains/losses, must exclude non-service-cost pension components, and its nature must be disclosed if not apparent (220-958-45-10 through 45-12; 220-958-50-1).

For students. This is the NFP analog to the income statement, and exam questions almost always test the two-class net asset model plus the netting rules (investment return net of direct internal and external investment expenses; special events net only if peripheral). A common misunderstanding is thinking an "operating" subtotal is required — it is optional, but if used it triggers content constraints and note disclosure of what "operations" means.

Machine-generated study aid for ASC 220-958. Check the source paragraphs below.

220-958-00Status

Source downloaded: .Record version 94dfd0ffba58. Effective date must be checked in the source.

220-958-00-1
The following table identifies the changes made to this Subtopic.
ParagraphActionAccounting Standards UpdateDate
AffiliateAmendedMaintenance Update 2018-12 (PDF)09/10/2018
AffiliateAddedMaintenance Update 2017-19 (PDF)11/15/2017
AgentAddedMaintenance Update 2017-19 (PDF)11/15/2017
Bankruptcy CodeAddedMaintenance Update 2017-19 (PDF)11/15/2017
Board-Designated Endowment FundAddedMaintenance Update 2017-19 (PDF)11/15/2017
Chapter 11AddedMaintenance Update 2017-19 (PDF)11/15/2017
Conditional ContributionAddedAccounting Standards Update No. 2018-0806/21/2018
ContributionAmendedAccounting Standards Update No. 2018-0806/21/2018
ContributionAddedMaintenance Update 2017-19 (PDF)11/15/2017
Disposal GroupAddedMaintenance Update 2017-19 (PDF)11/15/2017
Donor-Imposed ConditionAddedAccounting Standards Update No. 2018-0806/21/2018
Donor-Imposed RestrictionAddedMaintenance Update 2017-19 (PDF)11/15/2017
Donor-Restricted Endowment FundAddedMaintenance Update 2017-19 (PDF)11/15/2017
Donor-Restricted SupportAddedMaintenance Update 2017-19 (PDF)11/15/2017
Endowment FundAddedMaintenance Update 2017-19 (PDF)11/15/2017
Equity TransferAddedMaintenance Update 2017-19 (PDF)11/15/2017
Functional Expense ClassificationAddedMaintenance Update 2017-19 (PDF)11/15/2017
Funds Functioning as EndowmentAddedMaintenance Update 2017-19 (PDF)11/15/2017
Inherent ContributionAddedMaintenance Update 2017-19 (PDF)11/15/2017
IntermediaryAddedMaintenance Update 2017-19 (PDF)11/15/2017
Lead InterestAddedMaintenance Update 2017-19 (PDF)11/15/2017
Natural Expense ClassificationAmendedAccounting Standards Update No. 2024-0311/04/2024
Natural Expense ClassificationAddedMaintenance Update 2017-19 (PDF)11/15/2017
Net AssetsAddedMaintenance Update 2017-19 (PDF)11/15/2017
Net Assets with Donor RestrictionsAddedMaintenance Update 2017-19 (PDF)11/15/2017
Net Assets without Donor RestrictionsAddedMaintenance Update 2017-19 (PDF)11/15/2017
Not-for-Profit EntityAddedMaintenance Update 2017-19 (PDF)11/15/2017
Permanently Restricted Net AssetsSupersededAccounting Standards Update No. 2016-1408/18/2016
Permanently Restricted Net AssetsAddedMaintenance Update 2017-19 (PDF)11/15/2017
Programmatic InvestingAddedMaintenance Update 2017-19 (PDF)11/15/2017
Promise to GiveAddedAccounting Standards Update No. 2018-0806/21/2018
ReclassificationSupersededAccounting Standards Update No. 2016-1408/18/2016
ReclassificationAddedMaintenance Update 2017-19 (PDF)11/15/2017
Reclassification of Net AssetsAddedMaintenance Update 2017-19 (PDF)11/15/2017
Remainder InterestAddedMaintenance Update 2017-19 (PDF)11/15/2017
Restricted SupportSupersededAccounting Standards Update No. 2016-1408/18/2016
Restricted SupportAddedMaintenance Update 2017-19 (PDF)11/15/2017
Spending RateAddedMaintenance Update 2017-19 (PDF)11/15/2017
Split-Interest AgreementAddedMaintenance Update 2017-19 (PDF)11/15/2017
StipulationAddedMaintenance Update 2017-19 (PDF)11/15/2017
Temporarily Restricted Net AssetsSupersededAccounting Standards Update No. 2016-1408/18/2016
Temporarily Restricted Net AssetsAddedMaintenance Update 2017-19 (PDF)11/15/2017
Total ReturnAddedMaintenance Update 2017-19 (PDF)11/15/2017
TrusteeAddedMaintenance Update 2017-19 (PDF)11/15/2017
Unrestricted Net AssetsSupersededAccounting Standards Update No. 2016-1408/18/2016
Unrestricted Net AssetsAddedMaintenance Update 2017-19 (PDF)11/15/2017
Unrestricted SupportSupersededAccounting Standards Update No. 2016-1408/18/2016
Unrestricted SupportAddedMaintenance Update 2017-19 (PDF)11/15/2017
Variance PowerAddedMaintenance Update 2017-19 (PDF)11/15/2017
AddedMaintenance Update 2017-19 (PDF)11/15/2017
958-220-15-1AddedMaintenance Update 2017-19 (PDF)11/15/2017
958-220-15-2AddedMaintenance Update 2017-19 (PDF)11/15/2017
AddedMaintenance Update 2017-19 (PDF)11/15/2017
958-220-45-7AmendedAccounting Standards Update No. 2020-1010/29/2020
958-220-45-9AmendedAccounting Standards Update No. 2025-1212/17/2025
958-220-45-21AmendedAccounting Standards Update No. 2020-1010/29/2020
958-220-45-31AddedAccounting Standards Update No. 2020-0709/17/2020
958-220-50-1AddedMaintenance Update 2017-19 (PDF)11/15/2017
AddedMaintenance Update 2017-19 (PDF)11/15/2017

220-958-05Overview and Background

Source downloaded: .Record version f87c23b37943. Effective date must be checked in the source.

220-958-05-1
This Subtopic provides guidance on a statement of activities for not-for-profit entities (NFPs). A statement of activities for NFPs is the financial statement that an NFP issues instead of a business entity's income statement.
220-958-05-2
The primary purpose of a statement of activities is to provide relevant information about all of the following items:
  1. a
    The effects of transactions and other events and circumstances that change the amount and nature of net assets
  2. b
    The relationships of those transactions and other events and circumstances to each other
  3. c
    How the NFP's resources are used in providing various programs or services.
220-958-05-3
The information provided in a statement of activities, used with related disclosures and information in the other financial statements, helps donors, creditors, and others to do all of the following:
  1. a
    Evaluate the NFP's performance during a period
  2. b
    Assess an NFP's service efforts and its ability to continue to provide services
  3. c
    Assess how an NFP's managers have discharged their stewardship responsibilities and other aspects of their performance.

220-958-15Scope and Scope Exceptions

Source downloaded: .Record version 5957437b0bd8. Effective date must be checked in the source.

Overall Guidance

220-958-15-1
This Subtopic follows the same Scope and Scope Exceptions as outlined in the Overall Subtopic, see Section 958-10-15. It addresses how to report revenues, expenses, gains, and losses in financial statements; however, it does not specify when to recognize or how to measure those elements.

Entities

220-958-15-2
The application of this Subtopic by not-for-profit, business-oriented health care entities as described in Section 954-10-05 is subject to additional guidance in Subtopic 954-220.

220-958-45Other Presentation Matters

Source downloaded: .Record version 0e59fe121f51. Effective date must be checked in the source.

Totals and Format

220-958-45-1
A statement of activities provided by a not-for-profit entity (NFP) shall focus on the entity as a whole and shall report the following amounts for the period:
  1. a
    The change in net assets
  2. b
  3. c
  4. d
220-958-45-2
The change in net assets shall articulate to the net assets or equity reported in the statement of financial position and it shall be referred to using a descriptive term such as change in net assets or change in equity.
220-958-45-3
Revenues, expenses, gains, and losses increase or decrease net assets and shall be classified as provided in paragraphs . Reclassification of net assets, such as expirations of donor-imposed restrictions, shall be reported as separate items.

Classification of Revenues, Expenses, Gains, and Losses

220-958-45-4
Information about revenues, expenses, gains, losses, and reclassification of net assets generally is provided by aggregating items that possess similar characteristics into reasonably homogeneous groups.
220-958-45-5
A statement of activities shall report revenues as increases in net assets without donor restrictions unless the use of the assets received is limited by donor-imposed restrictions. For example, fees from rendering services and income from investments generally are without donor restrictions; however, income from donor-restricted perpetual or term endowments generally would increase net assets with donor restrictions.
220-958-45-6
Pursuant to the Contributions Received Subsections of Subtopic 958-605, in the absence of a donor's explicit stipulation or circumstances surrounding the receipt of the contribution that make clear the donor's implicit restriction on use, contributions are reported as revenues or gains without donor restrictions, which increase net assets without donor restrictions. The classification of contributions received as revenues or gains depends on whether the transactions are part of the NFP's ongoing major or central activities (revenues), or are peripheral or incidental to the NFP (gains). Donor-restricted contributions are reported as restricted revenues or gains (donor-restricted support), which increase net assets with donor restrictions. However, donor-restricted contributions whose restrictions are met in the same reporting period may be reported as support in net assets without donor restrictions, provided that an NFP has a similar policy for reporting investment gains and income, reports consistently from period to period, and discloses its accounting policy.
220-958-45-7
A statement of activities shall report expenses as decreases in net assets without donor restrictions, with the exception of investment expenses, which shall be netted against investment return and reported in the net asset class in which the net investment return is reported (see Subtopic 958-720).
220-958-45-8
A statement of activities shall report gains and losses recognized on investments and other assets (or liabilities) as increases or decreases in net assets without donor restrictions unless their use is restricted by explicit donor stipulations or by law that extends donor restrictions. For example, net gains on investment assets, to the extent recognized in financial statements, are reported as increases in net assets without donor restrictions unless their use is restricted by a donor to a specified purpose or future period or by law that extends donor restrictions. See paragraphs for additional guidance about reporting investment gains and losses, and paragraphs 958-205-45-13 through 45-13H for additional guidance about reporting gains and losses on endowment funds. See paragraph 958-310-45-3 for additional guidance about bad debt expenses and losses.

Measure of Operations

220-958-45-9
Classifying revenues, expenses, gains, and losses within classes of net assets does not preclude incorporating additional classifications within a statement of activities. For example, within a class or classes of changes in net assets, an NFP may classify items as follows:
  1. a
    Operating and nonoperating
  2. b
    Expendable and nonexpendable
  3. c
    Recognized and unrecognized
  4. d
    Recurring and nonrecurring
  5. e
    In other ways.
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
105-10-65-10Classifying revenues, expenses, gains, and losses within classes of net assets does not preclude incorporating additional classifications within a statement of activities. For example, within a class or classes of changes in net assets, an NFP may classify items as follows:
  1. a
    Operating and nonoperating
  2. b
    Expendable and nonexpendable
  3. c
  4. d
    Recurring and nonrecurring
  5. e
    In other ways.
220-958-45-10
This Subtopic neither encourages nor discourages those further classifications. However, because terms such as operating income, operating profit, operating surplus, operating deficit, and results of operations are used with different meanings, if an intermediate measure of operations (for example, excess or deficit of operating revenues over expenses) is reported, it shall be in a financial statement that, at a minimum, reports the change in net assets without donor restrictions for the period. Example 1 (see paragraph 958-220-55-5) illustrates a statement of revenues, expenses, and other changes in net assets without donor restrictions that subdivides all transactions and other events and circumstances to make an operating and nonoperating distinction.
220-958-45-11
Some limitations on an NFP's use of an intermediate measure of operations are imposed by other Subtopics. If a subtotal such as income from operations is presented, it shall include the following amounts:
  1. a
    An impairment loss recognized for a long-lived asset (asset group) to be held and used, pursuant to paragraph 360-10-45-4
  2. b
    Costs associated with an exit or disposal activity that does not involve a discontinued operation, pursuant to paragraph 420-10-45-3
  3. c
    A gain or loss recognized on the sale of a long-lived asset (disposal group) that is not a component of an entity that qualifies for discontinued operations treatment, as defined in Subtopic 205-20, and pursuant to paragraph 360-10-45-5.
In addition, the subtotal such as income from operations shall exclude the components of net periodic pension cost and net periodic postretirement benefit cost other than the service cost component, pursuant to paragraph 958-715-45-3.
220-958-45-12
Pursuant to paragraph 958-220-50-1, if an NFP's use of the term operations is not apparent from the details provided on the face of the statement, a note to financial statements shall describe the nature of the reported measure of operations or the items excluded from operations. If an NFP presents internal board designations, appropriations, and similar actions on the face of the financial statements, a note to financial statements shall provide an appropriate disaggregation and description by type of these actions if not provided on the face of the financial statements.

Reclassifications

220-958-45-13
Reclassifications of net assets—that is, simultaneous increases in one net asset class and decreases in another—shall be made if any of the following events occur:
  1. a
    The NFP fulfills the purposes for which the net assets were restricted.
  2. b
    Donor-imposed restrictions expire with the passage of time or with the death of a split-interest agreement beneficiary (if the net assets are not otherwise restricted).
  3. c
    A donor withdraws, or court action removes, previously imposed restrictions.
  4. d
    A donor imposes restrictions on net assets without donor restrictions. For example, a donor may make a restricted contribution that is conditioned on the NFP restricting a stated amount of its net assets without donor restrictions. Such restrictions that are not reversible without donors' consent result in a reclassification of net assets without donor restrictions to net assets with donor restrictions.
See paragraphs for additional information about the expiration of donor-imposed restrictions.

Gross versus Net Reporting of Amounts

220-958-45-14
To help explain the relationships of an NFP's ongoing major or central operations and activities, a statement of activities generally shall report the gross amounts of revenues and expenses. However, investment return (related to total return investing and not programmatic investing) shall be reported net of external and direct internal investment expenses. An NFP may present the amounts of net investment return from portfolios that are managed differently or derived from different sources as separate, appropriately labeled line items on the statement of activities. For example, if an NFP has net investment return generated from operating cash, it may present that return separately from net investment return generated from its endowment. In addition, if appropriately labeled, an NFP may present the amounts of net investment return appropriated for spending separate from net investment return in excess of amounts appropriated for spending.
220-958-45-15
Direct internal investment expenses involve the direct conduct or direct supervision of the strategic and tactical activities involved in generating investment return. These include, but are not limited to, both of the following:
  1. a
    Salaries, benefits, travel, and other costs associated with the officer and staff responsible for the development and execution of investment strategy
  2. b
    Allocable costs associated with internal investment management and supervising, selecting, and monitoring of external investment management firms.
220-958-45-16
Direct internal investment expenses do not include items that are not associated with generating investment return. For example, the costs associated with unitization and other such aspects of endowment management would not be allocated.
220-958-45-17
A statement of activities may report gains and losses as net amounts if they result from peripheral or incidental transactions or from other events and circumstances that may be largely beyond the control of the NFP and its management. Information about their net amounts generally is adequate to understand the NFP's activities. For example, an entity that sells land and buildings no longer needed for its ongoing activities commonly reports that transaction as a net gain or loss, rather than as gross revenues for the sales value and expense for the carrying value of the land and buildings sold. The net amount of those peripheral transactions, used with information in a statement of cash flows, usually is adequate to help assess how an entity uses its resources and how managers discharge their stewardship responsibilities.
220-958-45-18
The frequency of the events and the significance of the gross revenues and expenses distinguish major or central events from peripheral or incidental events. Events are ongoing major and central activities if they are normally part of an NFP's strategy and it normally carries on such activities or if the event's gross revenues or expenses are significant in relation to the NFP's annual budget. Events are peripheral or incidental if they are not an integral part of an NFP's usual activities or if their gross revenues or expenses are not significant in relation to the NFP's annual budget. Accordingly, similar events may be reported differently by different NFPs based on the NFP's overall activities.
220-958-45-19
An NFP may report net amounts for its special events if they result from peripheral or incidental transactions. However, so-called special events can be ongoing and major activities; if so, an NFP shall report the gross revenues and expenses of those activities. Costs netted against receipts from peripheral or incidental special events shall be limited to direct costs. See Example 4 (paragraph 958-220-55-11) for three possible methods of complying with this requirement.

Equity Transfers

220-958-45-20
Equity transfers are reported separately as changes in net assets and do not result in any step-up in basis of the underlying assets transferred. However, a service received from personnel of an affiliate that directly benefits the recipient NFP and for which the affiliate does not charge the recipient NFP may be recorded at the fair value of that service in the circumstances indicated in paragraph 958-720-30-3. Paragraph 958-20-55-2B describes the difference between an equity transfer and an equity transaction. Paragraph 954-220-45-2 provides additional guidance on the reporting of equity transfers for not-for-profit, business-oriented health care entities.
220-958-45-21
The increase in net assets associated with services received from personnel of an affiliate that directly benefit the recipient NFP and for which the affiliate does not charge the recipient NFP shall be reported as an equity transfer, regardless of whether those services are received from personnel of a not-for-profit affiliate or any other affiliate. The corresponding decrease in net assets or the creation or enhancement of an asset resulting from the use of services received from personnel of an affiliate shall be reported similar to how other such expenses or assets are reported. See paragraph 958-720-45-56 for presentation guidance on services received from personnel of an affiliate. Paragraphs provide additional guidance for not-for-profit, business-oriented health care entities.

Reporting Investment Gains, Losses, and Income

220-958-45-22
Pursuant to paragraph 958-220-45-8, gains and losses on investments and dividends, interest, and other investment income shall be reported in the statement of activities as increases or decreases in net assets without donor restrictions unless their use is limited by donor-imposed restrictions or by law that extends donor restrictions, in which case those amounts shall be reported as increases or decreases in net assets with donor restrictions.
220-958-45-24
Gains and investment income that are limited to specific uses by donor-imposed restrictions may be reported as increases in net assets without donor restrictions if the restrictions are met in the same reporting period as the gains and income are recognized, provided that the not-for-profit entity (NFP) has a similar policy for reporting contributions received (see paragraphs ), reports consistently from period to period, and discloses its accounting policy.
220-958-45-25
Pursuant to paragraphs , investment return, other than that which is programmatic in nature, shall be reported net of external and direct internal investment expenses.
220-958-45-26
Gains and losses on the investments of a donor-restricted endowment fund are classified in accordance with paragraphs 958-205-45-13 through 45-13H.

Presentation in a Statement of Activities with an Operating Measure

220-958-45-27
Some NFPs, primarily health care entities, would like to compare their results to business entities in the same industry. An NFP with those comparability concerns may report in a manner similar to business entities by classifying debt securities as available for sale or held to maturity as described in paragraphs and excluding the unrealized gains and losses on those securities (which are recognized in accordance with Subtopic 958-320) from an operating measure within the statement of activities. Not-for-profit, business-oriented health care entities, however, are required to exclude certain gains and losses from a performance measure (see paragraph 954-220-45-9).
220-958-45-28
In general, amounts reported in an NFP's financial statements shall be based on the nature of the underlying transactions rather than on budgetary designations.
220-958-45-29
Amounts of investment return based on budgetary designations may be displayed. However, in accordance with paragraph 958-220-45-14, investment return, other than that which is programmatic in nature, shall be displayed net of external and direct internal investment expenses. Paragraph 958-320-55-7 provides an example of how an NFP could present net investment return.
220-958-45-30
Some NFPs, in managing their endowment funds, use a spending-rate or total return policy. Those policies consider total investment return—investment income (interest, dividends, rents, and so forth) plus net realized and unrealized gains (or minus net losses). Typically, spending-rate or total return policies emphasize the use of prudence and a rational and systematic formula to determine the portion of cumulative investment return that can be used to support operations of the current period and the protection of endowment gifts from a loss of purchasing power as a consideration in determining the formula to be used. Example 1 (see paragraph 958-320-55-4) illustrates a statement of activities and example disclosures of an NFP that uses a spending-rate policy to include only a portion of its investment return in its operating measure.

Contributed Nonfinancial Assets

220-958-45-31
An NFP shall present contributed nonfinancial assets as a separate line item in the statement of activities, apart from contributions of cash and other financial assets, as discussed in paragraph 958-605-45-7A. See paragraph 958-605-50-1A for disclosure requirements for contributed nonfinancial assets.

220-958-50Disclosure

Source downloaded: .Record version 36b77a7d7119. Effective date must be checked in the source.

220-958-50-1
A not-for-profit entity (NFP) shall disclose the following information in the notes to financial statements:
  1. a
    If an NFP's use of the term operations is not apparent from the details provided on the face of the statement of activities, a description of the nature of the reported measure of operations or the items excluded from operations (see Example 5 in paragraph 958-220-55-16 for a case in which this information is apparent on the face of the statement of activities and a case in which this information is disclosed in the notes to the financial statements).
  2. aa
    If an NFP presents internal board designations, appropriations, and similar actions on the face of the financial statements, an appropriate disaggregation and description by type of these actions if not provided on the face of the financial statements (see Example 5 in paragraph 958-220-55-16 for a case in which this information is apparent on the face of the financial statements and a case in which this information is disclosed in the notes to the financial statements).
  3. b
  4. c
    If not provided on the face of the statement of activities or as a separate statement, all expenses in one location. The relationship between functional and natural classification for all expenses shall be presented in an analysis that disaggregates functional expense classifications by their natural expense classifications. Investment expenses that are netted against investment return shall not be included (see paragraph 958-720-45-15).
  5. d
    A qualitative description of the methods used to allocate costs among program and support functions (see paragraph 958-720-50-1).

220-958-55Implementation Guidance and Illustrations

Source downloaded: .Record version d8573673ecf6. Effective date must be checked in the source.

220-958-55-1
This Section, which is an integral part of the requirements of this Subtopic, provides general guidance to be used in the presentation of a statement of activities by a not-for-profit entity (NFP).

Implementation Guidance

220-958-55-2
Entitywide totals are not necessary for individual line items of revenues, expenses, gains, or losses. Information about reasonably homogeneous components of revenues, such as contributions without donor restrictions that are available to support current expenses and donor-restricted contributions that are restricted to acquiring land and buildings, generally is more meaningful than the aggregated total of those components.
220-958-55-3
Disaggregated information that permits users of financial information to relate components of revenues to components of expenses also is often preferable to information provided by their aggregated amounts. For example, information that permits analysis of the levels of revenues from tuition in relation to expenses for instruction and other academic services and of revenues from room and board fees in relation to expenses for housing and food services generally is more meaningful than totals of aggregated items of revenues, such as student tuition and fees, or aggregated items of expenses, such as salaries, heat, electricity, or supplies. Those who prepare financial statements generally are best able to make judgments about the extent to which financial statements or notes to financial statements should provide disaggregated information about various items of revenues or expenses and this Subtopic need not limit those judgments.

Illustrations

220-958-55-4
In addition to the following illustrations, guidance in paragraphs illustrates three formats of statements of activities. Paragraph 958-205-55-5 provides the facts and transactions that are reflected in those illustrative statements.
220-958-55-5
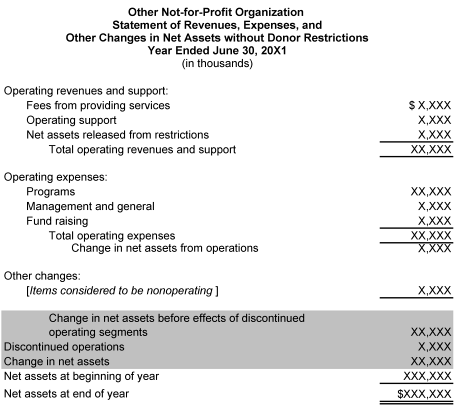
This Example illustrates a statement of revenues, expenses, and other changes in net assets without donor restrictions that subdivides all transactions and other events and circumstances to make an operating and nonoperating distinction pursuant to paragraphs . This Example uses part 1 of 2 of Format C in paragraph 958-205-55-15 to show a measure of operations—change in net assets without donor restrictions from operations.
220-958-55-6
The shaded areas depict the constraints imposed by this Subtopic and by generally accepted accounting principles (GAAP) to report appropriately labeled subtotals for changes in classes of net assets before the effects of discontinued operating segments, if any. The unshaded areas depict areas within the statement for which there is latitude to sequence and classify items of revenues and expenses. Other formats also may be used. For example, the single-statement Format B approach of paragraph 958-205-55-14 may be helpful in describing an NFP's ongoing major or central operations if that NFP's view of operating activities includes receiving donor-restricted revenues from contributions and investment income.
  • Other Not-for-Profit Organization " Statement of Revenues, Expenses, and" Other Changes in Net Assets without Donor Restrictions " Year Ended June 30, 20X1" (in thousands) Operating revenues and support: Fees from providing services "$ X,XXX" Operating support "X,XXX" Net assets released from restrictions " X,XXX" Total operating revenues and support "XX,XXX" Operating expenses: Programs "XX,XXX" Management and general "X,XXX" Fund raising " X,XXX" Total operating expenses " XX,XXX" Change in net assets from operations "X,XXX" Other changes: [Items considered to be nonoperating] "X,XXX" Change in net assets before effects of discontinued operating segments "XX,XXX" Discontinued operations "X,XXX" Change in net assets "XX,XXX" Net assets at beginning of year "XXX,XXX" Net assets at end of year "$XXX,XXX"
220-958-55-7
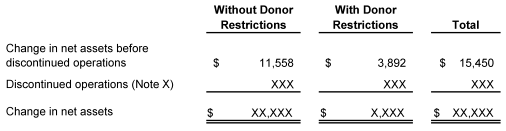
This Example illustrates the application of paragraph 958-205-45-5, as generally accepted accounting principles (GAAP) requires the display of an appropriately labeled subtotal for change in a class of net assets before the effects of a discontinued operation (see paragraph 205-20-45-1A). For instance, using the columnar format, a statement of activities would report the effects of a discontinued operation as follows.
  • Without Donor Restrictions With Donor Restrictions Total Change in net assets before discontinued operations " $11,558 " " $3,892 " " $15,450 " Discontinued operations (Note X) XXX XXX XXX Change in net assets " $ XX,XXX " " $ X,XXX " " $ XX,XXX "
220-958-55-8
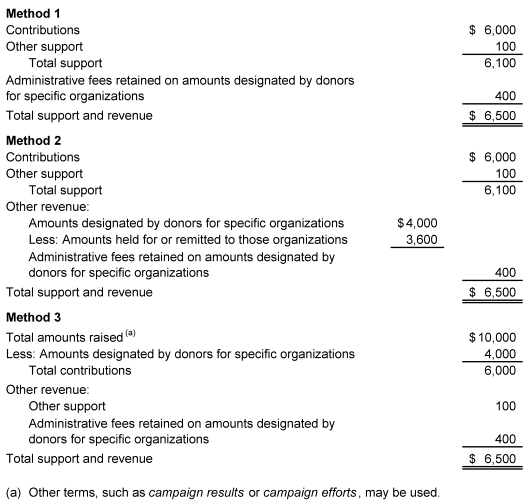
This Example provides three possible methods of displaying fundraising efforts in the revenue section of the statement of activities, while still conforming to the requirements of paragraph 958-605-45-10. Methods 2 and 3 display the total amounts raised.
220-958-55-9
Entity A raises $6,000 of contributions, $100 of other support, and $4,000 accounted for as agent, trustee, or intermediary transactions because donors have specified beneficiaries without granting variance power. Of the $4,000 accounted for as agent, trustee, or intermediary transactions, Entity A pays out $3,600 to specified beneficiaries and retains $400 as its administrative fee.
220-958-55-10
Each of the methods reports Entity A's revenues ($6,500) in a way that is both easily understood by users of the financial statements and representationally faithful.
  • Method 1 Contributions " $6,000 " Other support 100 Total support " 6,100 " Administrative fees retained on amounts designated by donors for specific organizations 400 Total support and revenue " $6,500 " Method 2 Contributions " $6,000 " Other support 100 Total support " 6,100 " Other revenue: Amounts designated by donors for specific organizations " $4,000 " Less: Amounts held for or remitted to those organizations " 3,600 " Administrative fees retained on amounts designated by donors for specific organizations 400 Total support and revenue " $6,500 " Method 3 Total amounts raised (a) " $10,000 " Less: Amounts designated by donors for specific organizations " 4,000 " Total contributions " 6,000 " Other revenue: Other support 100 Administrative fees retained on amounts designated by donors for specific organizations 400 Total support and revenue " $6,500 " (a) "Other terms, such as campaign results or campaign efforts, may be used."
220-958-55-11
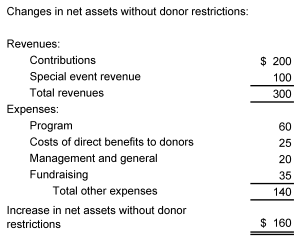
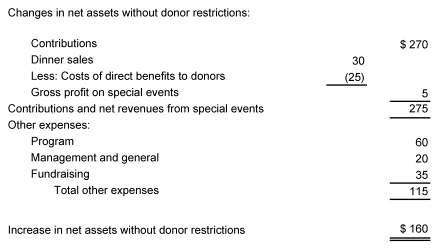
This Example illustrates the guidance in paragraph 958-220-45-19. It provides three possible methods to display in the statement of activities a special event that is an ongoing and major activity.
220-958-55-12
Cases A, B, and C share the following assumptions:
  1. a
    Not-for-Profit Entity B (NFP B) has a special event that is an ongoing and major activity with ticket revenue of $100.
  2. b
    The activity does not meet the audience criterion in paragraphs , and, therefore, all costs of the activity, other than the direct donor benefits, should be reported as fundraising.
  3. c
    The event includes a dinner that costs NFP B $25 and that has a fair value of $30.
  4. d
    In addition, NFP B incurs other direct costs of the event of $15 in connection with promoting and conducting the event, including incremental direct costs incurred in transactions with independent third parties and the payroll and payroll-related costs for the activities of employees who are directly associated with, and devote time to, the event. These other direct costs have been included in fundraising expenses. The other direct costs are unrelated to the direct benefits to donors and, accordingly, should not be included as costs of benefits to donors. The other direct costs include $5 that otherwise might be considered management and general costs if they had been incurred in a different activity, and fundraising costs of $10.
  5. e
    In addition, NFP B has all of the following transactions, which are unrelated to the special event:
    1. 1
      Contributions without donor restrictions of $200
    2. 2
      Program expenses of $60
    3. 3
      Management and general expenses of $20
    4. 4
      Fundraising expenses of $20.
220-958-55-13
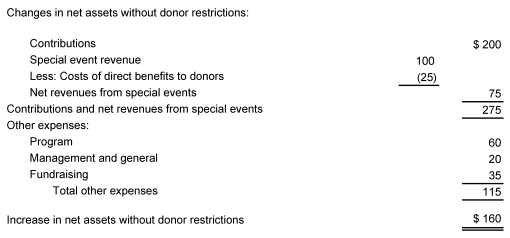
NFP B may report the gross revenues of special events and other fundraising activities with the cost of direct benefits to donors (meals and facilities rental) displayed as a line item deducted from the special event revenues, as follows:
  • Changes in net assets without donor restrictions: Contributions $200 Special event revenue 100 Less: Costs of direct benefits to donors (25) Net revenues from special events 75 Contributions and net revenues from special events 275 Other expenses: Program 60 Management and general 20 Fundraising 35 Total other expenses 115 Increase in net assets without donor restrictions $160
220-958-55-14
NFP B may report the gross revenues of special events and other fundraising activities with the cost of direct benefits to donors (meals and facilities rental) displayed in the same section of the statement of activities as are other programs or supporting services and allocated, if necessary, among those various functions, as follows:
  • Changes in net assets without donor restrictions: Revenues: Contributions $200 Special event revenue 100 Total revenues 300 Expenses: Program 60 Costs of direct benefits to donors 25 Management and general 20 Fundraising 35 Total other expenses 140 Increase in net assets without donor restrictions $160
220-958-55-15
NFP B may report the gross revenue from special events and other fundraising activities as part exchange (for the fair value the participant received) and part contribution (for the excess of the payment over that fair value), as follows:
  • Changes in net assets without donor restrictions: Contributions $270 Dinner sales 30 Less: Costs of direct benefits to donors (25) Gross profit on special events 5 Contributions and net revenues from special events 275 Other expenses: Program 60 Management and general 20 Fundraising 35 Total other expenses 115 Increase in net assets without donor restrictions $160
220-958-55-16
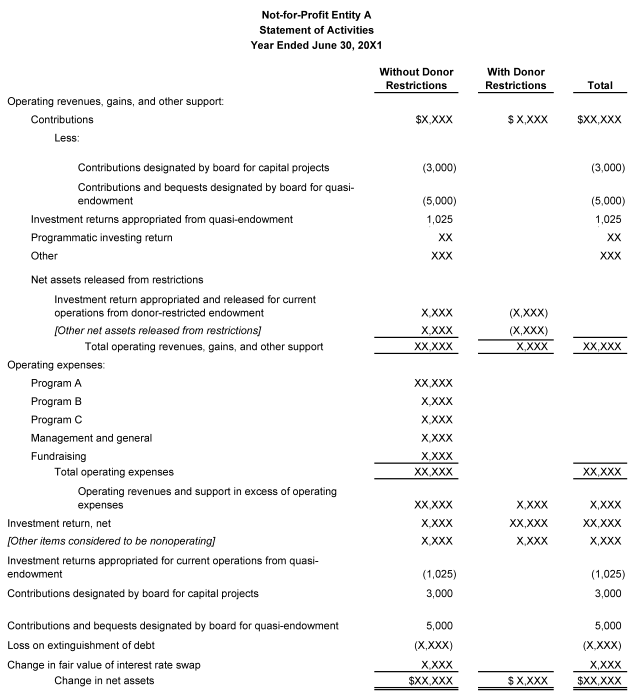
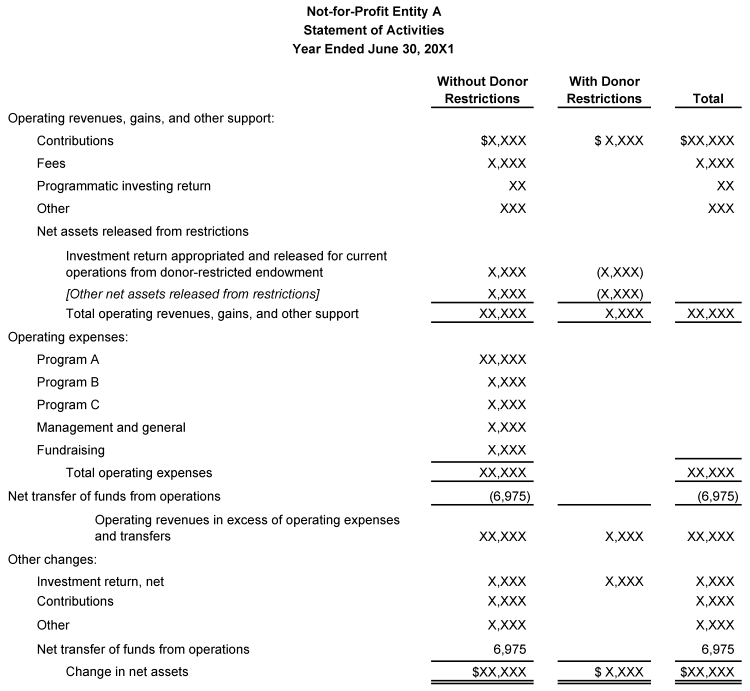
This Example illustrates the disclosures required in accordance with paragraph 958-220-50-1(a) through (aa) if an entity elects to present a measure of operations. It provides a case in which the disclosures are apparent on the face of the statement of activities and a case in which the disclosures are provided in the notes to the financial statements. There are multiple ways in which an NFP could present this information. The cases provided are two alternatives presented for illustration purposes.
220-958-55-17
The following Case is an example of a statement of activities of Not-for-Profit Entity A (NFP A) in which the disclosures required in paragraph 958-220-50-1(a) through (aa) are apparent from the details provided on the face of the statement of activities. This Case illustrates one way in which an NFP can present governing board actions on a statement of activities and is not meant to be prescriptive of a specific format.
  • Not-for-Profit Entity A Statement of Activities "Year Ended June 30, 20X1" Without Donor Restrictions With Donor Restrictions Total "Operating revenues, gains, and other support:" Contributions " $X,XXX " " $ X,XXX " " $XX,XXX " Less: Contributions designated by board for capital projects " (3,000)" " (3,000)" Contributions and bequests designated by board for quasi-endowment " (5,000)" " (5,000)" Investment returns appropriated from quasi-endowment " 1,025 " " 1,025 " Fees " X,XXX " " X,XXX " Programmatic investing return XX XX Other XXX XXX Net assets released from restrictions Investment return appropriated and released for current operations from donor-restricted endowment " X,XXX " " (X,XXX) " [Other net assets released from restrictions] " X,XXX " " (X,XXX) " "Total operating revenues, gains, and other support" " XX,XXX " " X,XXX " " XX,XXX " Operating expenses: Program A " XX,XXX " Program B " X,XXX " Program C " X,XXX " Management and general " X,XXX " Fundraising " X,XXX " Total operating expenses " XX,XXX " " XX,XXX " Operating revenues and support in excess of operating expenses " XX,XXX " " X,XXX " " X,XXX " "Investment return, net" " X,XXX " " XX,XXX " " XX,XXX " [Other items considered to be nonoperating] " X,XXX " " X,XXX " " X,XXX " Investment returns appropriated for current operations from quasi-endowment " (1,025)" " (1,025)" Contributions designated by board for capital projects " 3,000 " " 3,000 " Contributions and bequests designated by board for quasi-endowment " 5,000 " " 5,000 " Loss on extinguishment of debt " (X,XXX) " " (X,XXX) " Change in fair value of interest rate swap " X,XXX " " X,XXX " Change in net assets " $XX,XXX " " $ X,XXX " " $XX,XXX "
220-958-55-18
The following Case is an example of a statement of activities of NFP A in which the disclosures required in paragraph 958-220-50-1(a) through (aa) are not apparent from the details provided on the face of the statement of activities.
  • Not-for-Profit Entity A Statement of Activities "Year Ended June 30, 20X1" Without Donor Restrictions With Donor Restrictions Total "Operating revenues, gains, and other support:" Contributions " $X,XXX " " $ X,XXX " " $XX,XXX " Fees " X,XXX " " X,XXX " Programmatic investing return XX XX Other XXX XXX Net assets released from restrictions Investment return appropriated and released for current operations from donor-restricted endowment " X,XXX " " (X,XXX) " [Other net assets released from restrictions] " X,XXX " " (X,XXX) " "Total operating revenues, gains, and other support" " XX,XXX " " X,XXX " " XX,XXX " Operating expenses: Program A " XX,XXX " Program B " X,XXX " Program C " X,XXX " Management and general " X,XXX " Fundraising " X,XXX " Total operating expenses " XX,XXX " " XX,XXX " Net transfer of funds from operations " (6,975)" " (6,975)" Operating revenues in excess of operating expenses and transfers " XX,XXX " " X,XXX " " XX,XXX " Other changes: "Investment return, net" " X,XXX " " X,XXX " " X,XXX " Contributions " X,XXX " " X,XXX " Other " X,XXX " " X,XXX " Net transfer of funds to operations " 6,975 " " 6,975 " Change in net assets " $XX,XXX " " $ X,XXX " " $XX,XXX "
220-958-55-19
NFP A would add the following illustrative text to its note to financial statements that describes the nature of the reported measure of operations or the items excluded from operations and provides an appropriate disaggregation and description by type of internal board designations, appropriations, and similar actions.
  • Measure of Operations
  • NFP A's operating revenues in excess of expenses and transfers include all operating revenues and expenses that are an integral part of its programs and supporting activities, net assets released from donor restrictions to support operating expenditures, and transfers from Board-designated and other nonoperating funds to support current operating activities. The measure of operations includes support for operating activities from both donor-restricted net assets and net assets without donor restrictions designated for long-term investment (the donor-restricted and quasi-endowment) according to NFP A's spending policy, which is detailed in Note X. The measure of operations excludes investment return in excess of (less than) amounts made available for current support, gains and losses on extinguishment of debt, and changes in fair value of the interest rate swap. Included in the line items net transfer of funds to operations and net transfer of funds from operations is investment return appropriated from quasi-endowment to operations of $1,025, contributions designated by the Board of Trustees for capital projects from operations of $3,000, and contributions and bequests designated by the Board of Trustees for quasi-endowment from operations of $5,000.
220-958-55-20
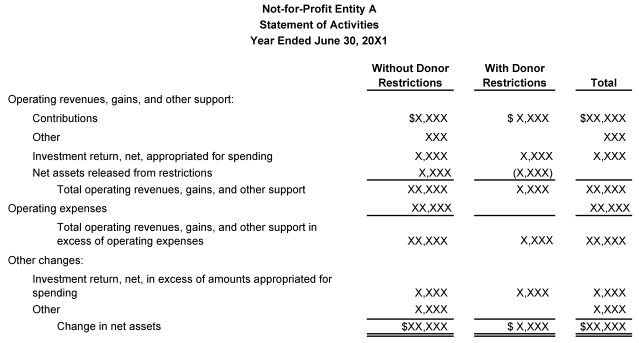
The following is an Example of a statement of activities in which NFP A presents net investment return in separate, appropriately labeled line items in accordance with paragraph 958-220-45-14. In this Example, NFP A presents net investment return in two separate line items to distinguish net investment return appropriated for current operations from net investment return for use in future periods. There may be other cases in which an NFP may present net investment return in separate line items in accordance with paragraph 958-220-45-14.
  • Not-for-Profit Entity A Statement of Activities "Year Ended June 30, 20X1" Without Donor Restrictions With Donor Restrictions Total "Operating revenues, gains, and other support:" Contributions " $X,XXX " " $ X,XXX " " $XX,XXX " Other XXX XXX "Investment return, net, appropriated for spending" " X,XXX " "X,XXX" " X,XXX " Net assets released from restrictions "X,XXX" "(X,XXX)" "Total operating revenues, gains, and other support" " XX,XXX " " X,XXX " " XX,XXX " Operating expenses "XX,XXX" "XX,XXX" "Total operating revenues, gains, and other support in excess of operating expenses" " XX,XXX " "X,XXX" " XX,XXX " Other changes: "Investment return, net, in excess of amounts appropriated for spending" " X,XXX " " X,XXX " " X,XXX " Other " X,XXX " " X,XXX " Change in net assets " $XX,XXX " " $ X,XXX " " $XX,XXX "

Related subtopics