ASC 320-958
Not-for-Profit Entities
320 Investments—Debt Securities
Source downloaded: .Record version d242df77f1bd. Effective date must be checked in the source.
This Subtopic (codified as 958-320) governs how not-for-profit entities account for investments in debt securities and sets disclosure rules for most NFP investments. The core rule is simple and different from the business-entity model: all debt securities held by an NFP are carried at fair value in the statement of financial position, with no held-to-maturity, trading, or available-for-sale classification. Purchased securities are initially measured at acquisition cost (excluding brokerage and other transaction fees); contributed securities and those received in agency transactions are initially measured at fair value.
Key points (7)
- All investments in debt securities held by an NFP, including mortgage-backed securities, shall be measured at fair value in the statement of financial position (320-958-35-1; 320-958-15-2).
- Initial measurement is acquisition cost excluding brokerage and other transaction fees if purchased, and fair value if received as a contribution or through an agency transaction (320-958-30-1).
- A debt security acquired by contribution is recognized as an asset and as revenue or gain in the period received (320-958-25-1, citing 958-605-25-2).
- If the NFP holds the investment as an agent with little or no discretion over how income and gains and losses will be used, the acquisition and subsequent activity are reported as agency transactions—changes in assets and liabilities, not changes in net assets (320-958-25-3; 320-958-35-3).
- Scope excludes equity-method investments and consolidated subsidiaries (958-810-15-4), derivatives under Topic 815, short sales, and investments held by a financially interrelated entity (Subtopic 958-20) (320-958-15-4); an embedded derivative does not remove the host contract from scope (320-958-15-5).
- An entity does not look through the legal form of its investment to the investee's underlying securities—a limited partnership interest meeting the definition of an equity security stays an equity security even if the partnership holds mostly debt securities (320-958-15-6).
- Disclosures: aggregate carrying amount of investments by major type for each statement of financial position presented (320-958-50-2), and the nature and carrying amount of each investment or group representing a significant concentration of market risk for the most recent period (320-958-50-3).
For students. Exam trap: students carry over the 320-10 three-bucket model (trading/AFS/HTM) to NFPs—there is none; every debt security an NFP holds is at fair value, with return reported in the statement of activities per 958-220-45-22 through 45-30. The second common miss is the no-look-through rule in 320-958-15-6, which classifies a partnership interest by its own form, not by the investee's underlying assets.
Machine-generated study aid for ASC 320-958. Check the source paragraphs below.
320-958-00Status
Source downloaded: .Record version 3ed5e6ddce47. Effective date must be checked in the source.
320-958-05Overview and Background
Source downloaded: .Record version a8142aeee05c. Effective date must be checked in the source.
- aFinancially Interrelated Entities
- bInvestments—Debt Securities
- bbInvestments—Equity Securities
- cInvestments—Other
- dConsolidation.
320-958-15Scope and Scope Exceptions
Source downloaded: .Record version 6a52fcceec1b. Effective date must be checked in the source.
Overall Guidance
Health Care Entities
Instruments
- a
- b
- a An investment in equity securities that is accounted for under the equity method in accordance with paragraph 958-810-15-4 or in accordance with Subtopic 958-321.
- b An investment in a subsidiary that is consolidated in accordance with paragraph 958-810-15-4 or .
- c An investment in a derivative instrument that is subject to the requirements of Topic 815. That is, an investment in an option on securities shall be accounted for under the requirements of Subtopic 815-10 if the option meets the definition of a derivative instrument, including the criteria for net settlement in paragraph 815-10-15-99.
- d Short sales of securities (sales of securities that the seller does not own at the time of sale), because they are obligations to deliver securities, not investments. Short sale obligations are addressed in the guidance for certain industries (see paragraph 940-320-35-1 with respect to broker-dealers and paragraph 942-405-35-1 with respect to depository institutions). For guidance on evaluating whether a short sale transaction involves a derivative instrument, see paragraph 815-10-55-57.
- e Investments held by a financially interrelated entity. See Subtopic 958-20 for reporting interests in the net assets of a financially interrelated entity.
Other Considerations
320-958-25Recognition
Source downloaded: .Record version d1c5326f2f04. Effective date must be checked in the source.
320-958-30Initial Measurement
Source downloaded: .Record version 130cfa9c6cf0. Effective date must be checked in the source.
320-958-35Subsequent Measurement
Source downloaded: .Record version 92b7be4e7baa. Effective date must be checked in the source.
Investments Held As an Agent
320-958-45Other Presentation Matters
Source downloaded: .Record version a3bad936cf67. Effective date must be checked in the source.
320-958-50Disclosure
Source downloaded: .Record version 1e68f8d81503. Effective date must be checked in the source.
320-958-55Implementation Guidance and Illustrations
Source downloaded: .Record version ec8023c0825d. Effective date must be checked in the source.
Implementation Guidance
- a U.S. Treasury securities
- b U.S. government agency securities
- c Municipal securities
- d Corporate bonds
- e Convertible debt
- f Commercial paper
- g All securitized debt instruments, such as collateralized mortgage obligations and real estate mortgage investment conduits
- h Interest-only and principal-only strips
- i Preferred stock that by its terms either must be redeemed by the issuing entity or is redeemable at the option of the investor
- j A collateralized mortgage obligation (or other instrument) that is issued in equity form but is required to be accounted for as a nonequity instrument regardless of how that instrument is classified (that is, whether equity or debt) in the issuer's statement of financial position.
- a Option contracts
- b Financial futures contracts
- c Forward contracts
- d Lease contracts
- e Swap contracts
- f Receivables that do not meet the definition of security and, thus, are not debt securities, for example:
- 1 Trade accounts receivable arising from sales on credit
- 2 Loans receivable arising from consumer, commercial, and real estate lending activities of financial institutions and not-for-profit entities (NFPs).
However, if those receivables have been securitized, they would meet the definition of a security, and thus be a debt security. Paragraph 320-10-55-3 explains that, even if a loan could readily be converted into a security, the loan is not a debt security until it has been securitized. - 1
Illustrations
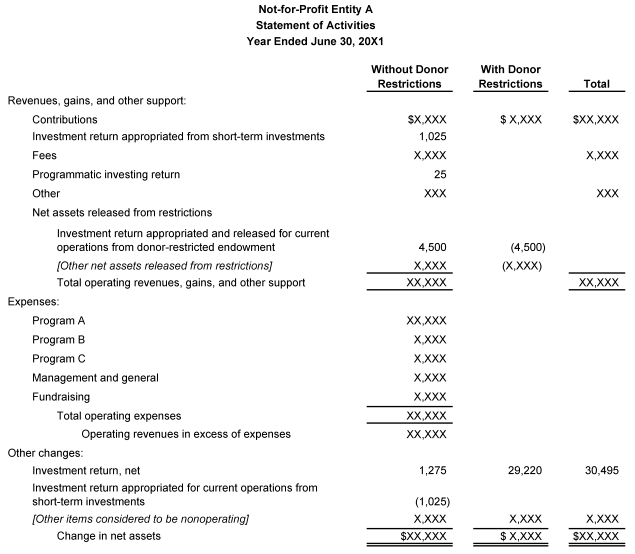
- aNot-for-Profit Entity A (NFP A) invests cash in excess of daily requirements in short-term investments; during the year, those investments earned $1,275.
- bMost long-term investments of NFP A's endowments are held in an investment pool, which earned income of $11,270 and had net gains of $15,450.
- cCertain endowments are separately invested because of donors' requirements. The investments of those endowments earned income of $1,000 and increased in value by $1,500.
- d
- eNFP A released from restrictions the full amount of net assets with donor restrictions that were appropriated from the donor-restricted endowment fund ($4,500) because the entity spent the funds for the required purpose.
- fNFP A's governing board appropriated for expenditure $1,025 from its short-term investments.
- gNFP A had $25 of gross programmatic investing income. The expenses related to the programmatic activity are included in operating expenses.
-
 Not-for-Profit Entity A Statement of Activities "Year Ended June 30, 20X1" Without Donor Restrictions With Donor Restrictions Total "Revenues, gains, and other support:" Contributions " $X,XXX " " $ X,XXX " " $XX,XXX " Investment return appropriated from short-term investments " 1,025 " Fees " X,XXX " " X,XXX " Programmatic investing return 25 Other XXX XXX Net assets released from restrictions Investment return appropriated and released for current operations from donor-restricted endowment " 4,500 " " (4,500)" [Other net assets released from restrictions] " X,XXX " " (X,XXX) " "Total operating revenues, gains, and other support" " XX,XXX " " XX,XXX " Expenses: Program A " XX,XXX " Program B " X,XXX " Program C " X,XXX " Management and general " X,XXX " Fundraising " X,XXX " Total operating expenses " XX,XXX " Operating revenues in excess of expenses " XX,XXX " Other changes: "Investment return, net" " 1,275 " " 29,220 " " 30,495 " Investment return appropriated for current operations from short-term investments " (1,025)" [Other items considered to be nonoperating] " X,XXX " " X,XXX " " X,XXX " Change in net assets " $XX,XXX " " $ X,XXX " " $XX,XXX "
- The board of trustees designates only a portion of NFP A's cumulative investment return for support of current operations; the remainder is retained to support operations of future years and to offset potential market declines. The amount computed and appropriated under the endowment spending policy of the investment pool and the amount appropriated from the investment return associated with the short-term investments are used to support current operations.
-
 20X1 Quoted Prices in Active Markets Significant Other Observable Inputs Significant Unobservable Inputs Measured at Net Asset Value (Level I) (Level II) (Level III) 20X1 Total Investments Cash equivalents held by investment managers " $19,366 " " $19,366 " U.S. common and preferred stocks " 61,190 " " 61,190 " International common and preferred stocks " 71,973 " " 71,973 " Fixed income " $40,920 " " 40,920 " Equity funds " 20,210 " " $10,093 " " $10,068 " " 40,371 " - Hedge funds " 26,248 " " 26,248 " - Private equity " 39,090 " " 39,090 " - Real estate " 33,520 " " 33,520 " Pooled endowment Pooled endowment " 172,739 " " 40,920 " " 43,613 " " 75,406 " " 332,678 " Split-interest agreements U.S. common and preferred stocks " 12,970 " " 12,970 " Fixed income " 6,635 " " 6,635 " Total investments " $185,709 " " $47,555 " " $43,613 " " $75,406 " " $352,283 "
320-958-60Relationships
Source downloaded: .Record version ef316feac463. Effective date must be checked in the source.
Derivatives and Hedging
Related subtopics
- 325-958 Not-for-Profit EntitiesInvestments—Other
- 321-958 Not-for-Profit EntitiesInvestments—Equity Securities
- 220-958 Not-for-Profit EntitiesIncome Statement—Reporting Comprehensive Income
- 205-958 Not-for-Profit EntitiesPresentation of Financial Statements
- 210-958 Not-for-Profit EntitiesBalance Sheet
- 220-954 Health Care EntitiesIncome Statement—Reporting Comprehensive Income