ASC 405-942
Financial Services—Depository and Lending
405 Liabilities
Source downloaded: .Record version 366213912088. Effective date must be checked in the source.
This Subtopic governs how depository and lending institutions recognize, measure, present, and disclose deposit liabilities and short-sale obligations. Deposit liabilities are recognized when deposits are received (not when funds are collected), with deposit float recorded as both an asset and a liability, and credit unions must present member share/savings accounts unequivocally as liabilities. Short sales ("securities sold, not yet purchased") are reported as liabilities measured at fair value through income, with interest on short positions accrued as interest expense.
Key points (7)
- Obligations incurred in short sales are reported as liabilities, generally called securities sold, not yet purchased (405-942-25-1), with additional guidance in 815-10-55-57.
- Short-sale obligations are subsequently measured at fair value through the income statement at each reporting date with interest accrued as interest expense (405-942-35-1); the fair value adjustment is classified with gains and losses on securities (405-942-45-1).
- A deposit liability is recognized when deposits are received, not when the institution collects the funds; deposit float (checks in process of collection, not available for withdrawal) is recorded as both an asset and a liability, and deposits are not recorded based solely on collections (405-942-25-3).
- Credit unions and corporate credit unions must report all member deposit accounts, including member shares, unequivocally as liabilities on the statement of financial condition (405-942-25-4; 405-942-55-1).
- Credit union statements of financial condition must either present deposit/savings accounts as the first item in the liabilities and equity section or include them within a captioned total-liabilities subtotal; an unclassified presentation showing savings accounts last before retained earnings is unacceptable (405-942-45-3; 405-942-55-2).
- Interest on member accounts (commonly called dividends) is reported as expense in the statement of income, and interest payable to members is included as a liability (405-942-45-4).
- Required deposit disclosures include aggregate time deposits (including CDs) at or above the insured limit, instruments pledged as collateral for deposits not otherwise disclosed under Topic 860, demand deposits reclassified as loans such as overdrafts, and deposits received on terms other than those available in the normal course of business (405-942-50-1).
For students. Two traps: deposits become liabilities when received, not when the check clears (float sits on both sides of the balance sheet), and credit union "shares"/savings accounts are liabilities despite the equity-sounding label and the "dividend" terminology used for interest paid on them.
Machine-generated study aid for ASC 405-942. Check the source paragraphs below.
405-942-00Status
Source downloaded: .Record version d158c4e68e1f. Effective date must be checked in the source.
| Paragraph | Action | Accounting Standards Update | Date |
| 942-405-50-1 | Amended | Maintenance Update 2018-02 (PDF) | 02/02/2018 |
| 942-405-50-1 | Amended | Maintenance Update 2014-07 (PDF) | 03/17/2014 |
405-942-05Overview and Background
Source downloaded: .Record version e8c876a6bad9. Effective date must be checked in the source.
405-942-15Scope and Scope Exceptions
Source downloaded: .Record version 6dfba4cafa02. Effective date must be checked in the source.
Overall Guidance
405-942-25Recognition
Source downloaded: .Record version 613eba49205b. Effective date must be checked in the source.
Short Sales of Securities
Deposits
Member Deposits
405-942-35Subsequent Measurement
Source downloaded: .Record version 4ec2f820be2d. Effective date must be checked in the source.
Short Sales of Securities
405-942-45Other Presentation Matters
Source downloaded: .Record version 0b3e9ec3c03c. Effective date must be checked in the source.
Short Sales of Securities
Redeemable Preferred Stock Dividends
Member Deposits
- aPresent deposit accounts as the first item in the liabilities and equity section
- bInclude deposit accounts within a captioned subtotal for total liabilities.
405-942-50Disclosure
Source downloaded: .Record version c070bef8ec47. Effective date must be checked in the source.
Deposits
- aThe aggregate amount of time deposit accounts (including certificates of deposit) in denominations that meet or exceed the insured limit at the balance sheet date
- bSecurities, mortgage loans, or other financial instruments that serve as collateral for deposits, that are otherwise not disclosed under Topic 860
- cThe aggregate amount of any demand deposits that have been reclassified as loan balances, such as overdrafts, at the balance-sheet date
- dDeposits that are received on terms other than those available in the normal course of business.
405-942-55Implementation Guidance and Illustrations
Source downloaded: .Record version 5045bdf37962. Effective date must be checked in the source.
Implementation Guidance
- a Present savings accounts as the first item in the liabilities and equity section
- b Include savings accounts within a captioned subtotal for total liabilities.
Illustrations
- Sample Credit Union
- Statements of Financial Condition
- December 31, 19X2 and 19X1
-
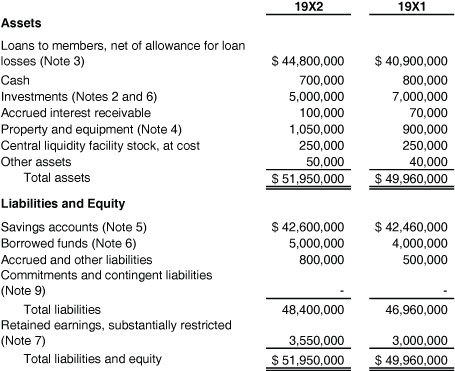 19X2 19X1 Assets "Loans to members, net of allowance for loan losses (Note 3)" " $44,800,000 " " $40,900,000 " Cash " 700,000 " " 800,000 " Investments (Notes 2 and 6) " 5,000,000 " " 7,000,000 " Accrued interest receivable " 100,000 " " 70,000 " Property and equipment (Note 4) " 1,050,000 " " 900,000 " "Central liquidity facility stock, at cost" " 250,000 " " 250,000 " Other assets " 50,000 " " 40,000 " Total assets " $51,950,000 " " $49,960,000 " Liabilities and Equity Savings accounts (Note 5) " $42,600,000 " " $42,460,000 " Borrowed funds (Note 6) " 5,000,000 " " 4,000,000 " Accrued and other liabilities " 800,000 " " 500,000 " Commitments and contingent liabilities (Note 9) - - Total liabilities " 48,400,000 " " 46,960,000 " "Retained earnings, substantially restricted (Note 7)" " 3,550,000 " " 3,000,000 " Total liabilities and equity " $51,950,000 " " $49,960,000 "
- The accompanying notes are an integral part of these financial statements. [For purposes of these illustrations, the notes to financial statements have not been included in this or the following Example.]
- Sample Credit Union
- Statements of Financial Condition
- December 31, 19X2 and 19X1
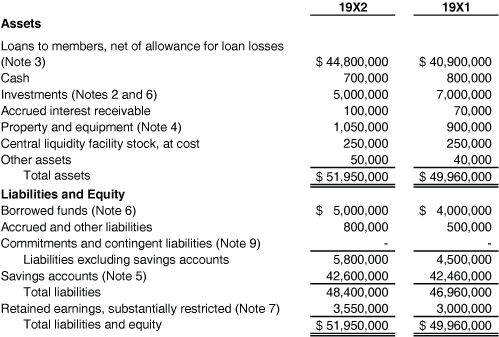 19X2 19X1 Assets "Loans to members, net of allowance for loan losses (Note 3)" " $44,800,000 " " $40,900,000 " Cash " 700,000 " " 800,000 " Investments (Notes 2 and 6) " 5,000,000 " " 7,000,000 " Accrued interest receivable " 100,000 " " 70,000 " Property and equipment (Note 4) " 1,050,000 " " 900,000 " "Central liquidity facility stock, at cost" " 250,000 " " 250,000 " Other assets " 50,000 " " 40,000 " Total assets " $51,950,000 " " $49,960,000 " Liabilities and Equity Borrowed funds (Note 6) " $5,000,000 " " $4,000,000 " Accrued and other liabilities " 800,000 " " 500,000 " Commitments and contingent liabilities (Note 9) - - Liabilities excluding savings accounts " 5,800,000 " " 4,500,000 " Savings accounts (Note 5) " 42,600,000 " " 42,460,000 " Total liabilities " 48,400,000 " " 46,960,000 " "Retained earnings, substantially restricted (Note 7)" " 3,550,000 " " 3,000,000 " Total liabilities and equity " $51,950,000 " " $49,960,000 "
- The accompanying notes are an integral part of these financial statements.
Related subtopics
- 470-942 Financial Services—Depository and LendingDebt
- 210-942 Financial Services—Depository and LendingBalance Sheet
- 505-942 Financial Services—Depository and LendingEquity
- 405-946 Financial Services—Investment CompaniesLiabilities
- 825-942 Financial Services—Depository and LendingFinancial Instruments
- 860-30 Secured Borrowing and CollateralTransfers and Servicing