ASC 405-926
Entertainment—Films
405 Liabilities
Source downloaded: .Record version 9b3fb6efddb8. Effective date must be checked in the source.
ASC 405-926 governs how film production and distribution entities accrue participation costs — amounts owed to third parties such as actors and writers — and costs of insignificant post-release changes to a film. Participation costs are accrued using the individual-film-forecast-computation method (current period actual revenue over estimated remaining unrecognized ultimate revenue at the beginning of the fiscal year), but only when it is probable an entity will sacrifice assets to settle the obligation, and never for less than amounts currently payable. If the recorded participation liability exceeds estimated unpaid ultimate participation costs, the excess reduces unamortized film costs first, then goes to income.
Key points (7)
- Participation costs are accrued using the individual-film-forecast-computation method, applying the fraction of current period actual revenue over estimated remaining unrecognized ultimate revenue as of the beginning of the fiscal year to unaccrued ultimate participation costs (405-926-25-1).
- A participation liability is accrued only if it is probable there will be a sacrifice of assets to settle the obligation, and accrued participation costs at each balance sheet date shall not be less than amounts the entity is obligated to pay as of that date (405-926-25-2).
- Accrual begins when the film is released and the entity begins recognizing revenue from that film, and continues on fully amortized films as revenue is recognized (405-926-25-3; 405-926-25-5).
- Estimates of unaccrued ultimate participation costs must use assumptions consistent with the entity's estimates of film costs, exploitation costs, and ultimate revenue, as limited by 926-20-35-5 and 926-20-35-11 (405-926-25-4).
- Costs expected for changes to a film that are not significant under a licensing arrangement are accrued and charged to expense if revenue recognition begins before the costs are incurred (405-926-25-6).
- Any recognized participation liability in excess of estimated unpaid ultimate participation costs is reduced with an offsetting credit to unamortized film costs, and only the remainder beyond unamortized film costs is credited to income (405-926-35-1; Example 1 at 926-405-55-1).
- Disclose the amount of accrued participation liabilities expected to be paid during the upcoming operating cycle and the methods of accounting for participation costs (405-926-50-1; 405-926-50-2).
For students. The classic trap is treating participation costs as ratably expensed or as payable-based; instead they follow the same revenue-based forecast ratio as film cost amortization, floored at amounts currently due. Also remember the excess-liability reversal cascades to unamortized film costs first — income only after film costs are exhausted.
Machine-generated study aid for ASC 405-926. Check the source paragraphs below.
405-926-00Status
Source downloaded: .Record version ebfc208af5ca. Effective date must be checked in the source.
| Paragraph | Action | Accounting Standards Update | Date |
| Revenue | Superseded | Accounting Standards Update No. 2014-09 | 05/28/2014 |
| Significant Changes | Superseded | Accounting Standards Update No. 2019-02 | 03/06/2019 |
| Significant Changes to a Film | Added | Accounting Standards Update No. 2019-02 | 03/06/2019 |
| 926-405-25-1 | Amended | Accounting Standards Update No. 2014-09 | 05/28/2014 |
| 926-405-55-2 | Amended | Accounting Standards Update No. 2014-09 | 05/28/2014 |
| 926-405-55-3 | Amended | Accounting Standards Update No. 2014-09 | 05/28/2014 |
| 926-405-55-5 | Amended | Accounting Standards Update No. 2014-09 | 05/28/2014 |
| 926-405-55-6 | Amended | Accounting Standards Update No. 2014-09 | 05/28/2014 |
405-926-05Overview and Background
Source downloaded: .Record version 2ebf58d12325. Effective date must be checked in the source.
405-926-15Scope and Scope Exceptions
Source downloaded: .Record version 3af41b65a01d. Effective date must be checked in the source.
Overall Guidance
405-926-25Recognition
Source downloaded: .Record version 60828de462cd. Effective date must be checked in the source.
Participation Costs
Costs Incurred for Insignificant Changes to a Film
405-926-35Subsequent Measurement
Source downloaded: .Record version c0186a825a2b. Effective date must be checked in the source.
Ultimate Participation Costs
405-926-50Disclosure
Source downloaded: .Record version def930361671. Effective date must be checked in the source.
Accrued Participation Liabilities
Participation Costs
405-926-55Implementation Guidance and Illustrations
Source downloaded: .Record version 1c6f88fbf151. Effective date must be checked in the source.
Illustrations
- a Film cost: $50,000
- b Estimated ultimate revenue:
- 1 Year 1: $100,000
- 2 Year 2: $80,000.
- 1
- c Actual revenue recognized:
- 1 In Year 1: $60,000
- 2 In Year 2: $10,000.
- 1
- d Estimated ultimate participation costs:
- 1 Year 1: $10,000
- 2 Year 2: $0.
- 1
- e For Year 1, film cost amortization was $30,000, and participation costs accrued were $6,000.
-
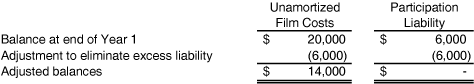 Unamortized Film Costs Participation Liability Balance at end of Year 1 " $20,000 " " $6,000 " Adjustment to eliminate excess liability " (6,000)" " (6,000)" Adjusted balances " $14,000 " $-
- $10,000 recognized revenue/$20,000 remaining ultimate revenue x $14,000 unamortized film costs = $7,000
- The $20,000 remaining ultimate revenue is computed as follows: Year 2 revised ultimate revenue of $80,000 minus cumulative prior recognized revenue of $60,000.
- The $14,000 unamortized film costs is computed as follows: Film cost of $50,000 minus cumulative prior amortization of $30,000 and minus the excess participation liability adjustment of $6,000.
- $10,000 recognized revenue/$20,000 remaining ultimate revenue x $0 remaining ultimate participation costs = $0
- The $20,000 remaining ultimate revenue is computed as follows: Year 2 revised ultimate revenue of $80,000 minus cumulative prior recognized revenue of $60,000.
- Estimated ultimate participation costs were reduced to $0 in Year 2; accordingly, the excess liability was reversed and no further accruals are required.