ASC 350-920
Entertainment—Broadcasters
350 Intangibles—Goodwill and Other
Source downloaded: .Record version 97c143bb5100. Effective date must be checked in the source.
This Subtopic tells a broadcaster (licensee) how to account for rights acquired under a license agreement for program material: when to recognize the asset and related liability, at what amounts to record them, and how to amortize and test them for impairment. The core rule is that the license is treated as a purchase of a right or group of rights, recognized when the license period begins and three cost/acceptance/availability conditions are met, then amortized based on estimated future showings and carried at the lower of unamortized cost or fair value. It also governs accounting for terminated network affiliation agreements.
Key points (7)
- A broadcaster shall account for a program license agreement and any exhibition rights acquired as a purchase of a right or group of rights (350-920-25-1).
- An asset and liability are reported when the license period begins and all three conditions are met: cost of each program is known or reasonably determinable, the material has been accepted by the licensee, and the program is available for its first showing or telecast (350-920-25-2).
- Capitalized cost is measured under one of the methods in 920-405-30-1 and allocated to individual programs in a package based on relative value to the broadcaster; the asset is reported at the lower of unamortized cost or fair value on a program-by-program, series, package, or daypart basis (350-920-30-1 through 30-3).
- Amortization is based on the estimated number of future showings, except licenses for unlimited showings of cartoons and similar programs, which may be amortized over the agreement period; feature programs are amortized program-by-program and series as a series, with an accelerated method if the first showing is more valuable (350-920-35-1 through 35-2).
- A license agreement that is part of a film group is tested for impairment under 926-20-35-12 and 926-20-35-12B; otherwise under 920-350-35-3, and a writeoff from unamortized cost to fair value establishes a new cost basis (350-920-35-2A, 35-3).
- On termination of a network affiliation agreement not immediately replaced, the unamortized balance is charged to expense; if immediately replaced, a loss is recognized only to the extent unamortized cost exceeds the fair value of the new affiliation, and no gain is recognized (350-920-40-1).
- Required disclosures include amortization and impairment methods and units of account, aggregate amortization expense and its income statement caption, and the portion of capitalized license costs expected to be amortized in each of the next three operating cycles (350-920-50-1 through 50-4).
For students. Watch the recognition trigger: the licensee capitalizes the full asset and liability when the license period begins and the program is available for its first telecast — not as installment payments are made — and the fee is owed whether or not the rights are ever exercised. A common misunderstanding is treating these agreements as executory contracts or leases rather than as a purchase of rights.
Machine-generated study aid for ASC 350-920. Check the source paragraphs below.
350-920-00Status
Source downloaded: .Record version c095fa018f18. Effective date must be checked in the source.
| Paragraph | Action | Accounting Standards Update | Date |
| Films | Added | Accounting Standards Update No. 2019-02 | 03/06/2019 |
| Film Group | Added | Accounting Standards Update No. 2019-02 | 03/06/2019 |
| 920-350-30-3 | Amended | Accounting Standards Update No. 2019-02 | 03/06/2019 |
| 920-350-35-1 | Amended | Accounting Standards Update No. 2019-02 | 03/06/2019 |
| 920-350-35-2A | Added | Accounting Standards Update No. 2019-02 | 03/06/2019 |
| 920-350-35-3 | Amended | Accounting Standards Update No. 2019-02 | 03/06/2019 |
| 920-350-45-1 | Amended | Accounting Standards Update No. 2019-02 | 03/06/2019 |
| Added | Accounting Standards Update No. 2019-02 | 03/06/2019 | |
| 920-350-50-2 | Amended | Accounting Standards Update No. 2024-03 | 11/04/2024 |
| 920-350-50-4 | Amended | Accounting Standards Update No. 2024-03 | 11/04/2024 |
350-920-05Overview and Background
Source downloaded: .Record version ea7b23aa0f8f. Effective date must be checked in the source.
- aWhen to recognize the asset acquired under such license agreements in the financial statements
- bAt what amounts to record the asset
- cAmortization of the capitalized amounts recorded.
350-920-15Scope and Scope Exceptions
Source downloaded: .Record version 3ff2d13b5b4d. Effective date must be checked in the source.
Overall Guidance
350-920-25Recognition
Source downloaded: .Record version 7abe88e883d3. Effective date must be checked in the source.
License Agreements for Program Material—Exhibition Rights
- aThe cost of each program is known or reasonably determinable.
- bThe program material has been accepted by the licensee in accordance with the conditions of the license agreement.
- cThe program is available for its first showing or telecast. Except when a conflicting license prevents usage by the licensee, restrictions under the same license agreement or another license agreement with the same licensor on the timing of subsequent showings shall not affect this availability condition.
350-920-30Initial Measurement
Source downloaded: .Record version 11c5617c7baf. Effective date must be checked in the source.
License Agreements for Program Material
350-920-35Subsequent Measurement
Source downloaded: .Record version 957929ed1f08. Effective date must be checked in the source.
License Agreements for Program Material—Amortization
License Agreements for Program Material—Valuation
350-920-40Derecognition
Source downloaded: .Record version 8db74d1df7d0. Effective date must be checked in the source.
Termination of a Network Affiliation Agreement
350-920-45Other Presentation Matters
Source downloaded: .Record version 254ed49ad89b. Effective date must be checked in the source.
License Agreements for Program Material
Network Affiliation Agreements
350-920-50Disclosure
Source downloaded: .Record version 4113084b1ec6. Effective date must be checked in the source.
License Agreements for Program Material
- aThe method or method(s) used in computing amortization
- bFor impairment, a description of the unit(s) of account used for impairment testing and the method(s) used for determining fair value.
- aThe aggregate amortization expense for the period
- bThe caption in the income statement where the amortization is recorded.
- aThe aggregate amortization expense for the period
- bThe caption in the income statement where the amortization is recorded.
- aA description of the facts and circumstances leading to the impairment
- bThe amount of impairment losses
- cThe caption in the income statement where the impairment losses are recorded
- dIf applicable, the segment(s) under Topic 280 where the impairment losses are recorded.
- aA description of the facts and circumstances leading to the impairment
- bThe amount of impairment losses
- cThe caption in the income statement where the impairment losses are recorded
- dIf applicable, the segment(s) under Topic 280 where the impairment losses are recorded.
350-920-55Implementation Guidance and Illustrations
Source downloaded: .Record version 9df24a0d6d8d. Effective date must be checked in the source.
Illustrations
- a End of Fiscal Year—December 31
- b Contract Execution Date—July 31, 19X1
- c Number of Films and Telecasts Permitted—four films, two telecasts each
- d Payment Schedule—$1,000,000 at contract execution date, $6,000,000 on January 1, 19X2, 19X3, and 19X4
- e Appropriate Interest Rate for Imputation of Interest—12 percent per year
- f Fees, License Periods, and Film Availability Dates.
-
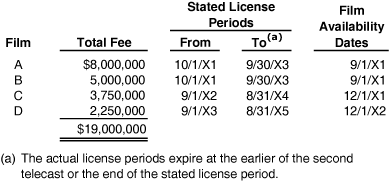 Stated License Periods Film Availability Dates Film Total Fee From To(a) A "$8,000,000" 10/1/X1 9/30/X3 9/1/X1 B "5,000,000" 10/1/X1 9/30/X3 9/1/X1 C "3,750,000" 9/1/X2 8/31/X4 12/1/X1 D "2,250,000" 9/1/X3 8/31/X5 12/1/X2 "$19,000,000" (a) The actual license periods expire at the earlier of the second telecast or the end of the stated license period.
-
- g Telecast Dates and Revenues.
-
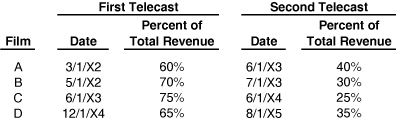 First Telecast Second Telecast Film Date Percent of Total Revenue Date Percent of Total Revenue A 3/1/X2 60% 6/1/X3 40% B 5/1/X2 70% 7/1/X3 30% C 6/1/X3 75% 6/1/X4 25% D 12/1/X4 65% 8/1/X5 35%
-
-
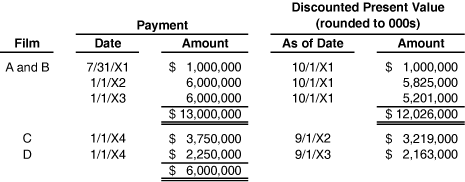 Payment Discounted Present Value (rounded to 000s) Film Date Amount As of Date Amount A and B 7/31/X1 " $1,000,000 " 10/1/X1 " $1,000,000 " 1/1/X2 " 6,000,000 " 10/1/X1 " 5,825,000 " 1/1/X3 " 6,000,000 " 10/1/X1 " 5,201,000 " " $13,000,000 " " $12,026,000 " C 1/1/X4 " $3,750,000 " 9/1/X2 " $3,219,000 " D 1/1/X4 " $2,250,000 " 9/1/X3 " $2,163,000 " " $6,000,000 "
-
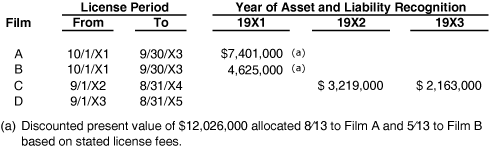 License Period Year of Asset and Liability Recognition Film From To 19X1 19X2 19X3 A 10/1/X1 9/30/X3 " $7,401,000 " ( a) B 10/1/X1 9/30/X3 " 4,625,000 " ( a) C 9/1/X2 8/31/X4 " $3,219,000 " " $2,163,000 " D 9/1/X3 8/31/X5 (a) "Discounted present value of $12,026,000 allocated 8/13 to film A and 5/13 to film B based on stated license fees."
-
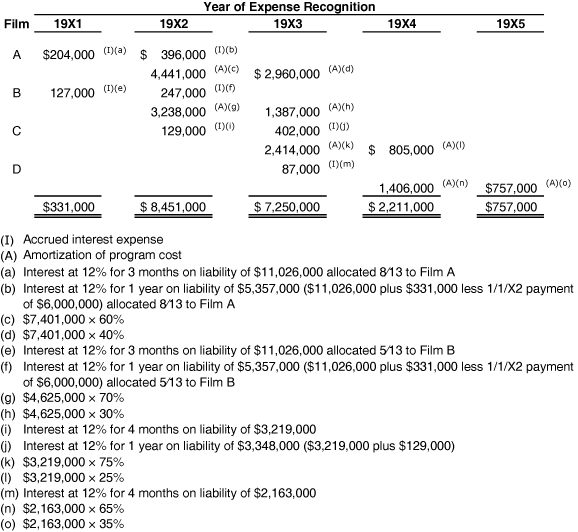 Year of Expense Recognition Film 19X1 19X2 19X3 19X4 19X5 A " $204,000 " (I) (a) " $396,000 " (I) (b) " 4,441,000 " (A) (c) " $2,960,000 " (A) (d) B " 127,000 " (I) (e) " 247,000 " (I) (f) " 3,238,000 " (A) (g) " 1,387,000 " (A) (h) C " 129,000 " (I) (i) " 402,000 " (I) (j) " 2,414,000 " (A) (k) " $805,000 " (A) (l) D " 87,000 " (I) (m) " 1,406,000 " (A) (n) " $757,000 " (A) (o) " $331,000 " " $8,451,000 " " $7,250,000 " " $2,211,000 " " $757,000 " (I) Accrued interest expense (A) Amortization of program cost (a) "Interest at 12% for 3 months on liability of $11,026,000 allocated 8/13 to Film A" (b) "Interest at 12% for 1 year on liability of $5,357,000 ($11,026,000 plus $331,000 less 1/1/X2 payment of $6,000,000) allocated 8/13 to Film A" (c) "$7,401,000 × 60%" (d) "$7,401,000 × 40%" (e) "Interest at 12% for 3 months on liability of $11,026,000 allocated 5/13 to Film B" (f) "Interest at 12% for 1 year on liability of $5,357,000 ($11,026,000 plus $331,000 less 1/1/X2 payment of $6,000,000) allocated 5/13 to Film B" (g) "$4,625,000 × 70%" (h) "$4,625,000 × 30%" (i) "Interest at 12% for 4 months on liability of $3,219,000" (j) "Interest at 12% for 1 year on liability of $3,348,000 ($3,219,000 plus $129,000)" (k) "$3,219,000 × 75%" (l) "$3,219,000 × 25%" (m) "Interest at 12% for 4 months on liability of $2,163,000" (n) "$2,163,000 × 65%" (o) "$2,163,000 × 35%"
-
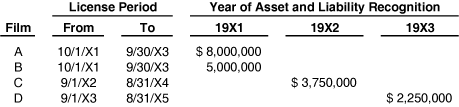 License Period Year of Asset and Liability Recognition Film From To 19X1 19X2 19X3 A 10/1/X1 9/30/X3 " $8,000,000 " B 10/1/X1 9/30/X3 " 5,000,000 " C 9/1/X2 8/31/X4 " $3,750,000 " D 9/1/X3 8/31/X5 " $2,250,000 "
-
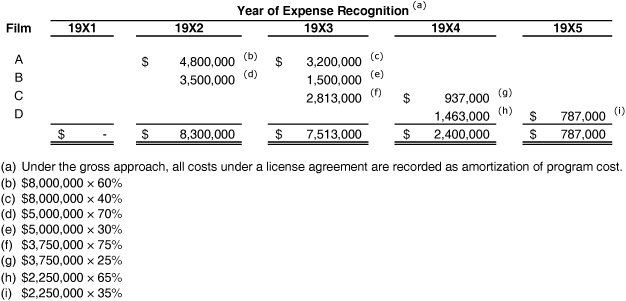 Year of Expense Recognition (a) Film 19X1 19X2 19X3 19X4 19X5 A " $4,800,000 " (b) " $3,200,000 " (c) B " 3,500,000 " (d) " 1,500,000 " (e) C " 2,813,000 " (f) " $937,000 " (g) D " 1,463,000 " (h) " $787,000 " (i) $- " $8,300,000 " " $7,513,000 " " $2,400,000 " " $787,000 " (a) "Under the gross approach, all costs under a license agreement are recorded as amortization of program cost." (b) "$8,000,000 × 60%" (c) "$8,000,000 × 40%" (d) "$5,000,000 × 70%" (e) "$5,000,000 × 30%" (f) "$3,750,000 × 75%" (g) "$3,750,000 × 25%" (h) "$2,250,000 × 65%" (i) "$2,250,000 × 35%"