ASC

ASC 220-40

Expense Disaggregation Disclosures

220 Income Statement—Reporting Comprehensive Income

Source downloaded: .Record version 17978e4c08b8. Effective date must be checked in the source.

ASC 220-40 (added by ASU 2024-03) requires public business entities to disaggregate, in a tabular note disclosure, each "relevant expense caption" presented on the face of the income statement in continuing operations into prescribed natural expense categories: purchases of inventory, employee compensation, depreciation, intangible asset amortization, and DD&A of oil-and-gas/other depletion (220-40-50-6). Other GAAP-required expense, gain, and loss items must be pulled into the same table (220-40-50-21 through 50-22), expense reimbursements must be addressed (50-26 through 50-29), and any residual must be shown as "other items" with a qualitative description of its composition (50-30). Entities must also disclose total selling expenses and, annually, how they define selling expenses (50-35 through 50-36).

Key points (7)
  • Scope is limited to public business entities; private companies, not-for-profit entities, and employee benefit plans under Topics 960, 962, and 965 are excluded (220-40-15-2 through 15-3), and only continuing operations expenses are covered (220-40-50-2).
  • A relevant expense caption is an income statement caption in continuing operations containing any category listed in 220-40-50-6; a caption consisting entirely of one such category needs no further disclosure, and equity method earnings/losses are never a relevant expense caption (220-40-50-12 through 50-13).
  • The required tabular categories are purchases of inventory (Topic 330 amounts only, excluding amounts from business combinations, joint venture formations, and initial VIE consolidations), employee compensation (separately showing one-time termination benefits), depreciation, intangible asset amortization, and oil-and-gas DD&A or other depletion (220-40-50-6 through 50-7, 50-11).
  • For captions containing Topic 330 inventory amounts, an entity elects either the cost-incurred basis (requiring additional 'changes in inventories' and 'other adjustments and reconciling items' captions) or the expense-incurred basis, applied consistently to all categories (220-40-50-31 through 50-34).
  • Listed items in 220-40-50-21 must be shown by relevant expense caption in the same table; items in 220-40-50-22 (e.g., warranty expense, operating lease cost, credit loss provision) are included only if recognized entirely within a single relevant expense caption, and their mere presence does not make a caption relevant (220-40-50-24).
  • Each relevant expense caption must show an 'other items' residual equal to the caption total less the separately disclosed amounts, with qualitative descriptions of its composition based on natural expense classification (220-40-50-30).
  • Estimates or reasonable approximations are permitted (220-40-50-1, 220-40-55-2), practical expedients exist under 50-19 and 50-20, and changes in display require disclosure of the reason and recasting of prior periods unless impracticable without being a Topic 250 accounting principle change (220-40-50-3 through 50-5).

For students. This is a pure disclosure standard—it changes nothing about recognition or measurement and does not require any change to the face of the income statement. The most common misunderstanding is thinking every expense caption must be disaggregated: only captions that actually contain one of the five categories in 220-40-50-6 are "relevant," and items in 220-40-50-21 through 50-22 never make a caption relevant by themselves.

Machine-generated study aid for ASC 220-40. Check the source paragraphs below.

220-40-00Status

Source downloaded: .Record version 9f5629c90c99. Effective date must be checked in the source.

220-40-00-1
The following table identifies the changes made to this Subtopic.
ParagraphActionAccounting Standards UpdateDate
Accretion ExpenseAddedAccounting Standards Update No. 2024-0311/04/2024
AcquireeAddedAccounting Standards Update No. 2024-0311/04/2024
AcquirerAmendedAccounting Standards Update No. 2025-0305/12/2025
AcquirerAddedAccounting Standards Update No. 2024-0311/04/2024
Acquisition by a Not-for-Profit EntityAddedAccounting Standards Update No. 2024-0311/04/2024
Acquisition CostsAddedAccounting Standards Update No. 2024-0311/04/2024
Asset Retirement ObligationAddedAccounting Standards Update No. 2024-0311/04/2024
BusinessAddedAccounting Standards Update No. 2024-0311/04/2024
Business CombinationAddedAccounting Standards Update No. 2024-0311/04/2024
Commencement Date of the Lease (Commencement Date)AddedAccounting Standards Update No. 2024-0311/04/2024
ContractAddedAccounting Standards Update No. 2024-0311/04/2024
Corporate Joint VentureAddedAccounting Standards Update No. 2024-0311/04/2024
CustomerAddedAccounting Standards Update No. 2024-0311/04/2024
Defined Benefit PlanAddedAccounting Standards Update No. 2024-0311/04/2024
Defined Contribution PlanAddedAccounting Standards Update No. 2024-0311/04/2024
Derivative InstrumentAddedAccounting Standards Update No. 2024-0311/04/2024
Direct Financing LeaseAddedAccounting Standards Update No. 2024-0311/04/2024
Employee (2nd def.)AddedAccounting Standards Update No. 2024-0311/04/2024
Employee CompensationAddedAccounting Standards Update No. 2024-0311/04/2024
Employee Stock Ownership PlanAddedAccounting Standards Update No. 2024-0311/04/2024
Environmental CreditAddedAccounting Standards Update No. 2026-0205/19/2026
Environmental Credit ObligationAddedAccounting Standards Update No. 2026-0205/19/2026
ExchangeAddedAccounting Standards Update No. 2025-1012/04/2025
Fair Value (2nd def.)AddedAccounting Standards Update No. 2025-1012/04/2025
Film CostsAddedAccounting Standards Update No. 2024-0311/04/2024
Finance LeaseAddedAccounting Standards Update No. 2024-0311/04/2024
Financial AssetAddedAccounting Standards Update No. 2026-0205/19/2026
Government GrantAddedAccounting Standards Update No. 2025-1012/04/2025
Hosting ArrangementAddedAccounting Standards Update No. 2024-0311/04/2024
ImpairmentAddedAccounting Standards Update No. 2024-0311/04/2024
Inactive EmployeesAddedAccounting Standards Update No. 2024-0311/04/2024
Income TaxesAddedAccounting Standards Update No. 2026-0205/19/2026
Intangible AssetsAddedAccounting Standards Update No. 2024-0311/04/2024
InventoryAddedAccounting Standards Update No. 2024-0311/04/2024
Joint VentureAddedAccounting Standards Update No. 2024-0311/04/2024
LeaseAddedAccounting Standards Update No. 2024-0311/04/2024
Lease TermAddedAccounting Standards Update No. 2024-0311/04/2024
Legal EntityAddedAccounting Standards Update No. 2024-0311/04/2024
LesseeAddedAccounting Standards Update No. 2024-0311/04/2024
LessorAddedAccounting Standards Update No. 2024-0311/04/2024
License AgreementAddedAccounting Standards Update No. 2024-0311/04/2024
Loss ContingencyAddedAccounting Standards Update No. 2024-0311/04/2024
Monetary AssetsAddedAccounting Standards Update No. 2025-1012/04/2025
Multiemployer PlanAddedAccounting Standards Update No. 2024-0311/04/2024
Natural Expense ClassificationAddedAccounting Standards Update No. 2024-0311/04/2024
Nonreciprocal Transfer (1st def.)AddedAccounting Standards Update No. 2026-0205/19/2026
Nonretirement Postemployment BenefitsAddedAccounting Standards Update No. 2024-0311/04/2024
Not-for-Profit EntityAddedAccounting Standards Update No. 2024-0311/04/2024
Oil- and Gas-Producing ActivitiesAddedAccounting Standards Update No. 2024-0311/04/2024
One-Time Employee Termination BenefitsAddedAccounting Standards Update No. 2024-0311/04/2024
Operating LeaseAddedAccounting Standards Update No. 2024-0311/04/2024
Other Postemployment BenefitsAddedAccounting Standards Update No. 2024-0311/04/2024
Pension BenefitsAddedAccounting Standards Update No. 2024-0311/04/2024
Postretirement BenefitsAddedAccounting Standards Update No. 2024-0311/04/2024
Private CompanyAddedAccounting Standards Update No. 2024-0311/04/2024
Public Business EntityAddedAccounting Standards Update No. 2024-0311/04/2024
ReinsuranceAddedAccounting Standards Update No. 2024-0311/04/2024
Right-of-Use AssetAddedAccounting Standards Update No. 2024-0311/04/2024
Sales-Type LeaseAddedAccounting Standards Update No. 2024-0311/04/2024
Security (2nd def.)AddedAccounting Standards Update No. 2024-0311/04/2024
Service Cost (Component of Net Periodic Pension Cost)AddedAccounting Standards Update No. 2024-0311/04/2024
Service Cost (Component of Net Periodic Postretirement Benefit Cost)AddedAccounting Standards Update No. 2024-0311/04/2024
Share-Based Payment ArrangementsAddedAccounting Standards Update No. 2024-0311/04/2024
Short-Term LeaseAddedAccounting Standards Update No. 2024-0311/04/2024
SubsidiaryAddedAccounting Standards Update No. 2024-0311/04/2024
Termination BenefitsAddedAccounting Standards Update No. 2024-0311/04/2024
Transaction Gain or LossAddedAccounting Standards Update No. 2024-0311/04/2024
Troubled Debt RestructuringAddedAccounting Standards Update No. 2024-0311/04/2024
Underlying AssetAddedAccounting Standards Update No. 2024-0311/04/2024
Underwriting RiskAddedAccounting Standards Update No. 2024-0311/04/2024
Variable Interest EntityAddedAccounting Standards Update No. 2024-0311/04/2024
WarrantyAddedAccounting Standards Update No. 2024-0311/04/2024
220-40-05-1AddedAccounting Standards Update No. 2024-0311/04/2024
AddedAccounting Standards Update No. 2024-0311/04/2024
220-40-50-21AmendedAccounting Standards Update No. 2026-0205/19/2026
220-40-50-21AmendedAccounting Standards Update No. 2025-1012/04/2025
AddedAccounting Standards Update No. 2024-0311/04/2024
220-40-65-1AmendedAccounting Standards Update No. 2025-0101/06/2025
220-40-65-1AddedAccounting Standards Update No. 2024-0311/04/2024

220-40-05Overview and Background

Source downloaded: .Record version 98f88f13ba69. Effective date must be checked in the source.

220-40-05-1
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1This Subtopic provides guidance on the disaggregation disclosure requirements for certain expense captions presented on the face of an entity’s income statement. This Subtopic also provides guidance on the disclosure of selling expenses.

220-40-15Scope and Scope Exceptions

Source downloaded: .Record version b3a371160dc7. Effective date must be checked in the source.

Overall Guidance

220-40-15-1
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1This Subtopic has its own discrete scope, which is separate and distinct from the pervasive scope for this Topic as outlined in Section 220-10-15.

Entities

220-40-15-2
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1The guidance in this Subtopic applies to all public business entities.
220-40-15-3
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1The guidance in this Subtopic does not apply to the following entities:
  1. a
  2. b
  3. c
    Employee benefit plans within the scope of any of the following Topics:
    1. 1
      Plan Accounting—Defined Benefit Pension Plans (Topic 960)
    2. 2
      Plan Accounting—Defined Contribution Pension Plans (Topic 962)
    3. 3
      Plan Accounting—Health and Welfare Benefit Plans (Topic 965).

220-40-50Disclosure

Source downloaded: .Record version 9a4e5781d215. Effective date must be checked in the source.

Overall Guidance

220-40-50-1
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1The objective of the disclosure requirements in this Section is to provide disaggregated information about a public business entity’s expenses to help investors:
  1. a
    Better understand the entity’s performance
  2. b
    Better assess the entity’s prospects for future cash flows
  3. c
    Compare an entity’s performance over time and with that of other entities.
In addition, the disclosure requirements are intended to provide information about the relative proportion and trends of each category of expense identified in paragraph 220-40-50-6 in relation to the corresponding income statement expense caption amount in order to meet the overall objective described above. An entity shall consider the level of detail necessary to satisfy the disclosure objective and specific requirements of this Subtopic. An entity may use estimates or other methods that produce a reasonable approximation of the amounts required to be disclosed by this Subtopic.
220-40-50-2
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1This Section includes the following (all of which apply only to expenses in continuing operations):
  1. a
    Required expense categories to be disclosed, identification of relevant expense captions, and practical expedients (see paragraphs )
  2. b
    Tabular integration of other disclosure requirements (see paragraphs )
  3. c
    Disclosure of expense reimbursements included in a relevant expense caption (see paragraphs )
  4. d
    An amount and qualitative description of the composition of other items remaining in relevant expense captions (see paragraph 220-40-50-30)
  5. e
    Disclosure of the disaggregation of relevant expense captions that contain amounts within the scope of Topic 330 on inventory (see paragraphs )
  6. f
    Requirements related to selling expenses (see paragraphs ).
220-40-50-3
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1The requirements in this Section apply to interim and annual reporting periods, except for the requirement to disclose how an entity defines selling expenses (see paragraph 220-40-50-36), which only applies to annual reporting periods (or interim reporting periods if the definition is changed). An entity is required to include the disclosures listed in paragraphs in a tabular format disclosure for interim reporting purposes only if the disclosure requirements referenced in those paragraphs are required in interim reporting periods by the guidance in other Topics.
220-40-50-4
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1The disclosure requirements in this Section shall be applied consistently for all periods presented. If an entity changes its display of the disclosure requirements in the current reporting period as a result of a change in the election of an alternative or a change in a definition of a disclosure in this Section, the entity shall:
  1. a
    Disclose the reason for the change in the period of the change (in the interim and annual reporting periods affected by the change)
  2. b
    Recast the prior periods presented for comparative purposes, except for the requirements in paragraphs , unless it is impracticable to do so. If it is impracticable to do so, the entity shall disclose that fact and explain why it is impracticable to recast prior periods.
Changes described in this paragraph do not represent a change in accounting principle in accordance with Topic 250 on accounting changes and error corrections.
220-40-50-5
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1
Some entities provide condensed statements for interim reporting periods and, therefore, present different expense captions on their income statements at annual and interim reporting periods. For an entity that provides condensed statements for interim reporting periods, the guidance in paragraph 220-40-50-4 is applicable in instances in which an entity changes its display of the disclosure requirements for the current interim reporting period compared with the prior interim reporting period or in instances in which the entity changes its display of the disclosure requirements for the current annual reporting period compared with the prior annual reporting period.
220-40-50-6
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1For interim and annual reporting periods, an entity shall disaggregate, in a tabular format disclosure in the notes to financial statements, all relevant expense captions (see paragraphs for guidance on identifying relevant expense captions) presented on the face of the income statement in continuing operations into the following expense categories:
  1. a
    Purchases of inventory (see paragraph 220-40-50-7)
  2. b
    Employee compensation (disclosing separately any one-time employee termination benefits, if applicable, see paragraph 220-40-50-21(e))
  3. c
    Depreciation (for separate requirement to disclose depreciation expense for the period in total, see paragraph 360-10-50-1(a))
  4. d
    Intangible asset amortization (for separate requirement to disclose intangible asset amortization expense for the period in total, see paragraph 350-30-50-2(a)(2))
  5. e
    Depreciation, depletion, and amortization of capitalized acquisition, exploration, and development costs recognized as part of oil- and gas-producing activities (see Subtopic 932-360 on extractive activities—oil and gas—property, plant, and equipment) or other amounts of depletion expense (see paragraph 220-40-50-11).
220-40-50-7
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1Purchases of inventory shall include only amounts within the scope of Topic 330 or within the scope of an Industry Subtopic in Topic 330 (collectively, Topic 330) but shall not include (regardless of the basis selected in paragraph 220-40-50-31) the amounts recognized from any of the following:
  1. a
    A business combination within the scope of Subtopic 805-10 on business combinations
  2. b
    A joint venture formation within the scope of Subtopic 805-60 on joint venture formations
  3. c
    The initial consolidation of a variable interest entity that is not a business combination within the scope of Subtopic 810-10 on consolidation.
Amounts excluded by this paragraph shall be included in the other items category, unless separately disclosed voluntarily (see paragraph 220-40-50-30). See paragraphs for additional requirements for the disaggregation of relevant expense captions that contain amounts within the scope of Topic 330.
220-40-50-8
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1When applying the guidance in paragraph 220-40-50-6(b), an entity may elect, but is not required, to include amounts attributable to other transactions entered into for the benefit of employees (for example, the provision of subsidized goods or services) in employee compensation. For interim and annual reporting periods, an entity that includes other transactions entered into for the benefit of employees as part of employee compensation shall disclose both that those transactions have been included and a description of those transactions.
220-40-50-9
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1The amounts provided for depreciation in accordance with paragraph 220-40-50-6(c) and intangible asset amortization in accordance with paragraph 220-40-50-6(d) shall be consistent with the classification of amounts used to satisfy the disclosure requirements for the total depreciation expense and total intangible asset amortization expense disclosures in paragraphs 360-10-50-1(a) and 350-30-50-2(a)(2), respectively, and with the classification of amounts described in paragraph 220-40-50-10.
220-40-50-10
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1Amortization of a right-of-use asset for a finance lease recognized in accordance with paragraphs and amortization of leasehold improvements recognized in accordance with paragraphs shall be disclosed in a manner consistent with how an entity presents depreciation or amortization of similar assets (see paragraph 842-20-45-4(a)). That is, amounts shall be included as part of either depreciation in paragraph 220-40-50-6(c) or intangible asset amortization in paragraph 220-40-50-6(d).
220-40-50-11
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1In determining the amounts to be disclosed in paragraph 220-40-50-6(e), an entity also shall include amounts for depletion expense that are not recognized as part of oil- and gas-producing activities in accordance with Subtopic 932-360 (such as depletion expense recognized by entities within the scope of Topic 930 on mining).
220-40-50-12
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1For the purposes of applying the guidance in this Subtopic, a relevant expense caption is an expense caption presented on the face of the income statement in continuing operations that contains any of the expenses listed in paragraph 220-40-50-6 (including those described in paragraphs ). A relevant expense caption that consists entirely of one expense category listed in paragraph 220-40-50-6 is not subject to the requirements of this Subtopic. For example, if depreciation is a relevant expense caption on the income statement and the caption consists entirely of depreciation in accordance with paragraph 220-40-50-6(c), no additional disclosure is required because the information in the income statement satisfies the disclosure requirements in this Subtopic. In contrast, if the relevant expense caption comprises depreciation and intangible asset amortization, an entity would be required to separately disclose depreciation and intangible asset amortization in accordance with paragraph 220-40-50-6(c) through (d), respectively. Furthermore, in accordance with paragraph 220-40-50-31, when a relevant expense caption contains amounts within the scope of Topic 330, an entity shall apply its chosen basis for disaggregating amounts within the scope of Topic 330 to the expense categories listed in paragraph 220-40-50-6.
220-40-50-13
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1An entity’s share of earnings or losses from investments accounted for under the equity method in accordance with paragraph 323-10-45-1 is not a relevant expense caption for purposes of applying the guidance in this Subtopic. Additionally, an entity is not required to further disaggregate its disclosure of summarized information of results of operations of investments accounted for under the equity method in accordance with paragraph 323-10-50-3(c).
220-40-50-14
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1With the exception of inventory disclosed under the cost-incurred basis described in paragraph 220-40-50-31(a), an entity is not required to further disaggregate costs capitalized as an asset, even if the costs capitalized include the categories listed in paragraph 220-40-50-6. In addition, when an expense amount relates to the derecognition of an asset other than inventory, an entity shall apply the guidance in paragraph 220-40-50-6 based on the nature of the expense at the time that it is recognized in the income statement.
220-40-50-15
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1To illustrate the application of the requirements in paragraph 220-40-50-14, an entity is not required to further disaggregate amortization of costs to fulfill a contract with a customer into the categories required by paragraph 220-40-50-6 (for example, employee compensation). As another example, an entity that capitalizes employee compensation when self-constructing new property, plant, and equipment for internal use is not required to further disaggregate the resulting depreciation into the categories listed in paragraph 220-40-50-6.
220-40-50-16
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1An entity is not required to disaggregate an expense amount into the required expense categories as part of the disclosures required by paragraph 220-40-50-6 if all of the following criteria are met:
  1. a
    The expense relates to an obligation that will be settled in the future and there is uncertainty about the timing of settlement.
  2. b
    The expense relates to an obligation that is based on an estimate of a future expenditure.
  3. c
    The expense is not entirely made up of one required expense category (for example, employee compensation).
An expense that meets the above criteria may be required to be disclosed in the same tabular format if it is listed in paragraphs .
220-40-50-17
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1Examples of expenses that meet the criteria in paragraph 220-40-50-16 include provision for losses on contracts (see Subtopic 605-35 on revenue recognition—construction-type and production-type contracts), claims and claims adjustment expenses, and asset retirement obligations, among others.
220-40-50-18
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1Examples of expenses that do not meet the criteria in paragraph 220-40-50-16 include expense amounts related to accruals for liabilities to pay for goods or services that have been received or supplied but have not been paid or invoiced, including amounts due to employees (for example, amounts relating to accrued bonuses, vacation pay, or pension obligations).
220-40-50-19
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1As a practical expedient, when substantially all of an entity’s income statement expense caption comprises purchases of inventory as described in paragraph 220-40-50-7, the entity is not required to apply the guidance in paragraph 220-40-50-6 to that caption. An entity that applies this practical expedient shall disclose a qualitative description of the composition of the expense caption in interim and annual reporting periods.
220-40-50-20
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1As a practical expedient for determining what amounts are classified as employee compensation in paragraph 220-40-50-6(b), an entity that presents an expense caption for salaries and employee benefits (or a similarly named caption) on the face of its income statement to comply with the requirements in SEC Regulation S-X Rule 210.9-04, Statements of Comprehensive Income (see paragraph 942-220-S99-1), may use the amounts classified as salaries and employee benefits in accordance with SEC Regulation S-X Rule 210.9-04 rather than in accordance with the definition of employee compensation included in this Subtopic.
220-40-50-21
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1An entity shall disclose, in the same tabular format disclosure in which the disclosures required by paragraph 220-40-50-6 are provided, each of the following expenses, gains, and losses and the amount recognized in each relevant expense caption (see paragraphs for guidance on identifying relevant expense captions):
  1. a
    The amount of research and development assets acquired in a transaction other than a business combination and written off (see paragraph 350-30-50-1(c))
  2. b
    Impairment loss recognized related to an intangible asset (see paragraph 350-30-50-3)
  3. c
    Impairment loss of long-lived assets classified as held and used (see paragraph 360-10-50-2)
  4. d
    Gain or loss recognized in accordance with paragraphs and 360-10-40-5 for long-lived assets classified as held for sale or disposed of (see paragraph 360-10-50-3)
  5. e
    Each major type of cost associated with an exit or disposal activity (for example, one-time employee termination benefits, contract termination costs, and other associated costs) (see paragraph 420-10-50-1)
  6. f
    Components of net benefit cost recognized (other than service cost amounts included within employee compensation) (see paragraph 715-20-50-1(h))
  7. g
    Bargain purchase gain recognized in a business combination (see paragraph 805-30-50-1(f))
  8. h
    Any gain or loss recognized upon the deconsolidation of a subsidiary or the derecognition of a group of assets in accordance with paragraph 810-10-40-3A (see paragraph 810-10-50-1B)
  9. i
    Gains and losses on derivative instruments (and nonderivative instruments that are designated and qualify as hedging instruments in accordance with paragraphs 815-20-25-58 and 815-20-25-66) and related hedged items (see paragraph 815-10-50-4A)
  10. j
    Amortization of license agreements for program material (see paragraph 920-350-50-2)
  11. k
    Impairment of license agreements for program material (see paragraph 920-350-50-4)
  12. l
    Amortization of film costs (see paragraph 926-20-50-4A)
  13. m
    Impairment of film costs (see paragraph 926-20-50-4C).
These disclosures shall be included in the tabular format disclosure required by paragraph 220-40-50-6 using the same frequency (that is, whether the disclosure is required at interim and annual reporting periods or only annual reporting periods) as required by the corresponding Topic.
Transition date:(P) December 16, 2028; (N) December 16, 2029Transition guidance:
832-10-65-2An entity shall disclose, in the same tabular format disclosure in which the disclosures required by paragraph 220-40-50-6 are provided, each of the following expenses, gains, and losses and the amount recognized in each relevant expense caption (see paragraphs for guidance on identifying relevant expense captions):
  1. a
    The amount of research and development assets acquired in a transaction other than a business combination and written off (see paragraph 350-30-50-1(c))
  2. b
    Impairment loss recognized related to an intangible asset (see paragraph 350-30-50-3)
  3. c
    Impairment loss of long-lived assets classified as held and used (see paragraph 360-10-50-2)
  4. d
    Gain or loss recognized in accordance with paragraphs and 360-10-40-5 for long-lived assets classified as held for sale or disposed of (see paragraph 360-10-50-3)
  5. e
    Each major type of cost associated with an exit or disposal activity (for example, one-time employee termination benefits, contract termination costs, and other associated costs) (see paragraph 420-10-50-1)
  6. f
    Components of net benefit cost recognized (other than service cost amounts included within employee compensation) (see paragraph 715-20-50-1(h))
  7. g
    Bargain purchase gain recognized in a business combination (see paragraph 805-30-50-1(f))
  8. h
    Any gain or loss recognized upon the deconsolidation of a subsidiary or the derecognition of a group of assets in accordance with paragraph 810-10-40-3A (see paragraph 810-10-50-1B)
  9. i
    Gains and losses on derivative instruments (and nonderivative instruments that are designated and qualify as hedging instruments in accordance with paragraphs 815-20-25-58 and 815-20-25-66) and related hedged items (see paragraph 815-10-50-4A)
  10. j
    Amortization of license agreements for program material (see paragraph 920-350-50-2)
  11. k
    Impairment of license agreements for program material (see paragraph 920-350-50-4)
  12. l
    Amortization of film costs (see paragraph 926-20-50-4A)
  13. m
    Impairment of film costs (see paragraph 926-20-50-4C)
  14. n
    The total amount of a government grant recognized during the reporting period and presented as a deduction from the related expense (see paragraphs 832-10-45-1(b), 832-10-45-3(b), and 832-10-50-3A).
These disclosures shall be included in the tabular format disclosure required by paragraph 220-40-50-6 using the same frequency (that is, whether the disclosure is required at interim and annual reporting periods or only annual reporting periods) as required by the corresponding Topic.
Transition date:(P) December 16, 2027; (N) December 16, 2028Transition guidance:
818-10-65-1An entity shall disclose, in the same tabular format disclosure in which the disclosures required by paragraph 220-40-50-6 are provided, each of the following expenses, gains, and losses and the amount recognized in each relevant expense caption (see paragraphs for guidance on identifying relevant expense captions):
  1. a
    The amount of research and development assets acquired in a transaction other than a business combination and written off (see paragraph 350-30-50-1(c))
  2. b
    Impairment loss recognized related to an intangible asset (see paragraph 350-30-50-3)
  3. c
    Impairment loss of long-lived assets classified as held and used (see paragraph 360-10-50-2)
  4. d
    Gain or loss recognized in accordance with paragraphs and 360-10-40-5 for long-lived assets classified as held for sale or disposed of (see paragraph 360-10-50-3)
  5. e
    Each major type of cost associated with an exit or disposal activity (for example, one-time employee termination benefits, contract termination costs, and other associated costs) (see paragraph 420-10-50-1)
  6. f
    Components of net benefit cost recognized (other than service cost amounts included within employee compensation) (see paragraph 715-20-50-1(h))
  7. g
    Bargain purchase gain recognized in a business combination (see paragraph 805-30-50-1(f))
  8. h
    Any gain or loss recognized upon the deconsolidation of a subsidiary or the derecognition of a group of assets in accordance with paragraph 810-10-40-3A (see paragraph 810-10-50-1B)
  9. i
    Gains and losses on derivative instruments (and nonderivative instruments that are designated and qualify as hedging instruments in accordance with paragraphs 815-20-25-58 and 815-20-25-66) and related hedged items (see paragraph 815-10-50-4A)
  10. j
    Amortization of license agreements for program material (see paragraph 920-350-50-2)
  11. k
    Impairment of license agreements for program material (see paragraph 920-350-50-4)
  12. l
    Amortization of film costs (see paragraph 926-20-50-4A)
  13. m
    Impairment of film costs (see paragraph 926-20-50-4C)
  14. n
    The total amount of a government grant recognized during the reporting period and presented as a deduction from the related expense (see paragraphs 832-10-45-1(b), 832-10-45-3(b), and 832-10-50-3A)
  15. o
    Total expense recognized for environmental credits not initially recognized as an asset in accordance with paragraph 818-20-25-1 or subsequently derecognized in accordance with paragraph 818-20-40-2 (see paragraph 818-20-50-3(a))
  16. p
    Total impairment expense recognized during the reporting period relating to environmental credits (see paragraph 818-20-50-3(b))
  17. q
    Total expense recognized for environmental credit obligation liabilities (see paragraph 818-30-50-3).
These disclosures shall be included in the tabular format disclosure required by paragraph 220-40-50-6 using the same frequency (that is, whether the disclosure is required at interim and annual reporting periods or only annual reporting periods) as required by the corresponding Topic.
220-40-50-22
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1An entity shall disclose, in the same tabular format disclosure in which the disclosures required by paragraph 220-40-50-6 are provided, each of the following amounts if those amounts are included entirely in one expense caption that also is a relevant expense caption (see paragraphs for guidance on identifying relevant expense captions):
  1. a
    Provision for expected credit losses (see paragraphs 326-20-50-13 and 326-30-50-9)
  2. b
    Losses on firm purchase commitments (see paragraph 330-10-50-5)
  3. c
    Amortization expense attributable to the expiration of an insurance or reinsurance coverage provided under a contract that transfers only significant underwriting risk (see paragraph 340-30-50-2)
  4. d
    Amortization of costs to fulfill a contract with a customer (see paragraph 340-40-50-3)
  5. e
    Impairment of costs to fulfill a contract with a customer (see paragraph 340-40-50-3)
  6. f
    Amortization of costs to obtain a contract with a customer (see paragraph 340-40-50-3)
  7. g
    Impairment of costs to obtain a contract with a customer (see paragraph 340-40-50-3)
  8. h
    Amortization of capitalized implementation costs of hosting arrangements that are service contracts (see paragraph 350-40-50-3)
  9. i
  10. j
    Loss contingencies recognized (see paragraph 450-20-50-1)
  11. k
    Warranty expense (the total of expenses recognized related to aggregate changes in the liability for accruals related to product warranties issued during the reporting period and the aggregate changes in the liability for accruals related to preexisting warranties, including adjustments related to changes in estimates) (see paragraph 460-10-50-8)
  12. l
    Expense related to counterparty default in own-share lending arrangements issued in contemplation of convertible debt issuance (see paragraph 470-20-50-2C)
  13. m
    Aggregate gain on restructuring of payables by a debtor with a troubled debt restructuring (see paragraph 470-60-50-1)
  14. n
    Gains and losses upon consolidation of a variable interest entity that is not a business (see paragraph 810-10-50-3)
  15. o
    Foreign currency transaction gains or losses (see paragraph 830-20-50-1)
  16. p
    Operating lease cost (see paragraph 842-20-50-4)
  17. q
    Short-term lease cost (see paragraph 842-20-50-4)
  18. r
    Variable lease cost (see paragraph 842-20-50-4)
  19. s
    Net gain or loss recognized from sale and leaseback transactions (see paragraph 842-20-50-4)
  20. t
    Gains and losses from nonmonetary transactions (see paragraph 845-10-50-1)
  21. u
    Amortization of capitalized acquisition costs (see paragraph 944-30-50-1(c)).
These disclosures shall be included in the tabular format disclosure required by paragraph 220-40-50-6 using the same frequency (that is, whether the disclosure is required at interim and annual reporting periods or only annual reporting periods) as required by the corresponding Topic.
220-40-50-23
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1If there is a change in facts and circumstances that results in an item listed in paragraph 220-40-50-22 changing from being included in one relevant expense caption in the current reporting period and multiple relevant expense captions in a comparative period, or vice versa, an entity shall provide the disclosure required by paragraph 205-10-50-1.
220-40-50-24
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1The presence of the expenses, gains, and losses listed in paragraphs would not cause an expense caption to be a relevant expense caption. An entity only shall include the applicable expenses listed in paragraphs in the tabular format disclosures if an expense caption is a relevant expense caption in accordance with paragraphs .
220-40-50-25
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1To illustrate the application of the requirements in paragraph 220-40-50-22, if cost of sales was a relevant expense caption (because cost of sales includes purchases of inventory described in paragraph 220-40-50-6(a)) and if amortization of costs to fulfill a contract with a customer was recognized entirely in cost of sales and not in multiple expense captions presented on the face of the income statement, then amortization of costs to fulfill a contract with a customer would be required to be included as a separate category in the tabular format disclosure in addition to the categories required by paragraph 220-40-50-6.
220-40-50-26
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1For interim and annual reporting periods, an entity that presents a relevant expense caption that includes amounts that are recorded net of an expense reimbursement related to a cost-sharing or cost-reimbursement arrangement from another entity, in the same tabular format disclosure in which the disclosures required by paragraph 220-40-50-6 are provided, shall either:
  1. a
    Separately disclose the amount of the expense reimbursement
  2. b
    Disclose the amounts of the expense categories required by paragraphs 220-40-50-6 and that are included in the relevant expense caption net of any reimbursement effects.
220-40-50-27
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1For interim and annual reporting periods, an entity shall disclose how expense reimbursements related to a cost-sharing or cost-reimbursement arrangement are included in the tabular format disclosure, as described in paragraph 220-40-50-26.
220-40-50-28
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1For interim and annual reporting periods, an entity that includes an expense reimbursement related to a cost-sharing or cost-reimbursement arrangement to another entity in a relevant expense caption shall separately disclose the amount of that expense reimbursement in the same tabular format disclosure in which the disclosures required by paragraph 220-40-50-6 are provided.
220-40-50-29
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1For interim and annual reporting periods, when applying the guidance in paragraph 220-40-50-26(a) or 220-40-50-28, an entity shall disclose qualitative descriptions of the expense categories (based on their natural expense classification) to which an expense reimbursement relates.
220-40-50-30
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1For interim and annual reporting periods, an entity, in the same tabular format disclosure in which the disclosures required by paragraph 220-40-50-6 are provided, shall disclose for each relevant expense caption an amount for other items. The amount for other items is the difference between the following:
  1. a
    The amount of the relevant expense caption presented on the face of the income statement
  2. b
    The aggregate amount of expense categories separately disclosed in accordance with paragraphs 220-40-50-6, , 220-40-50-26(a), and 220-40-50-28 that are included in the relevant expense caption.
For interim and annual reporting periods, an entity also shall disclose qualitative descriptions of the composition (based on their natural expense classification) of other items. The detail provided in those qualitative disclosures shall be commensurate with the significance of the amounts being described. Notwithstanding that requirement, an entity is not precluded from further disaggregating relevant expense captions before applying the guidance in this paragraph to the remaining other items. Additional voluntary disclosures may be provided inside or outside the tabular disclosure if those disclosures are not combined with the disaggregated expense amounts required by paragraphs 220-40-50-6, , 220-40-50-26(a), and 220-40-50-28.
220-40-50-31
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1The following are two acceptable bases for disclosing the disaggregation of a relevant expense caption that contains expense amounts related to inventory within the scope of Topic 330:
  1. a
    Cost-incurred basis. The amounts disclosed for the disaggregation of a relevant expense caption comprise costs incurred that were capitalized to inventory in accordance with Topic 330 during the current reporting period and any costs incurred that were directly expensed during the current reporting period (including costs that are capitalizable in accordance with Topic 330 but were directly expensed to the income statement). Under this basis, in interim and annual reporting periods, an entity shall disclose an amount for changes in inventories and an amount for other adjustments and reconciling items to reconcile the costs incurred to the total relevant expense caption (see paragraphs ).
  2. b
    Expense-incurred basis. The amounts disclosed for the disaggregation of a relevant expense caption comprise expense amounts related to the derecognition of inventory that was previously capitalized in accordance with Topic 330 and any costs incurred that were directly expensed during the current reporting period (including costs that are capitalizable in accordance with Topic 330 but were directly expensed to the income statement). Under this basis, an entity shall disclose the expense amounts related to the derecognition of inventory based on the natural expense category of the costs when they were initially incurred (for example, the expense from the derecognition of inventory may relate to purchases of inventory and employee compensation incurred in prior periods).
In many cases, an entity’s chosen basis will result in disclosed amounts that are different than if the entity had chosen the alternative basis. An entity’s chosen basis should be applied consistently to all expense categories listed in paragraph 220-40-50-6.
220-40-50-32
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1When the amounts disclosed in accordance with paragraph 220-40-50-6 include costs incurred that were capitalized to inventory in accordance with Topic 330 during the reporting period (because an entity has applied the cost-incurred basis in paragraph 220-40-50-31(a)), those amounts often will not equal the amounts expensed as incurred during the reporting period. If the amount of expense recognized and the amount of costs incurred in the current reporting period are not equal, then an entity shall disclose in interim and annual reporting periods a category for the changes in inventories balances to reconcile the costs incurred (which shall include costs capitalized to inventory and costs expensed during the reporting period) to expenses recognized. The amount disclosed for changes in inventories in the current reporting period shall equal the difference between the amount of inventory included on the balance sheet at the end of the prior reporting period and the amount of inventory included on the balance sheet at the end of the current reporting period. As described in paragraph 220-40-50-33, a separate category that comprises any other adjustments and reconciling items shall be provided to reconcile costs incurred to expenses recognized during the reporting period.
220-40-50-33
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1In addition to the changes in inventories category described in paragraph 220-40-50-32, for interim and annual reporting periods, under the cost-incurred basis (see paragraph 220-40-50-31(a)), an entity shall disclose the amount of other adjustments and reconciling items that include (to the extent not disclosed in a separate caption) other amounts that are necessary to reconcile costs incurred to expenses recognized. For example, those items would include, if applicable:
  1. a
    The amount of inventory derecognized during the period that is not recognized as an expense (for example, inventory derecognized as part of derecognition transactions within the scope of Subtopic 810-10 on consolidation)
  2. b
    The amount attributable to differences in the foreign currency exchange rates used to translate costs incurred, the beginning balance of inventory, and the ending balance of inventory in accordance with Subtopic 830-30 on foreign currency matters—translation of financial statements.
220-40-50-34
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1Consistent with the requirements in paragraph 220-40-50-30, for interim and annual reporting periods, an entity shall qualitatively describe the nature of amounts (based on their natural expense classification when applicable) included in other adjustments and reconciling items in accordance with paragraph 220-40-50-33.
220-40-50-35
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1For interim and annual reporting periods, an entity shall disclose, in the notes to financial statements, the total selling expenses recognized in continuing operations.
220-40-50-36
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1An entity shall make its own determination of what constitutes a selling expense. An entity’s definition of selling expenses shall include only items that are presented as expenses in the income statement. An entity shall disclose how it defines the term selling expenses in annual reporting periods (or in interim reporting periods if the definition is changed).

220-40-55Implementation Guidance and Illustrations

Source downloaded: .Record version e6cb68e02906. Effective date must be checked in the source.

220-40-55-1
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1This Section is an integral part of the requirements of this Subtopic. This Section provides additional guidance and illustrations of the disaggregation of income statement expenses and other disclosures required by paragraphs . The illustrations are intended as examples only and do not represent a required format for the disclosures. Furthermore, there may be incremental disclosure guidance otherwise applicable to an item or amount under other generally accepted accounting principles, which has not been illustrated in this Section. Paragraphs 220-40-50-6, , 220-40-50-26, 220-40-50-28, and require that an entity provide certain disclosures in a tabular format disclosure.

Implementation Guidance

220-40-55-2
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1Application of the guidance in this Subtopic might cause an entity to pursue a degree of detail in recordkeeping and computations that could be burdensome as well as unnecessary to produce a reasonable approximation of the results. Accordingly, an entity may use estimates or other methods that produce a reasonable approximation of the amounts required to be disclosed by this Subtopic.

Illustrations

220-40-55-3
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1This Example illustrates one type of tabular format disclosure that an entity could use to disclose disaggregated expense amounts in accordance with paragraphs . This Example also illustrates the disclosure of selling expenses in accordance with paragraphs .
220-40-55-4
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
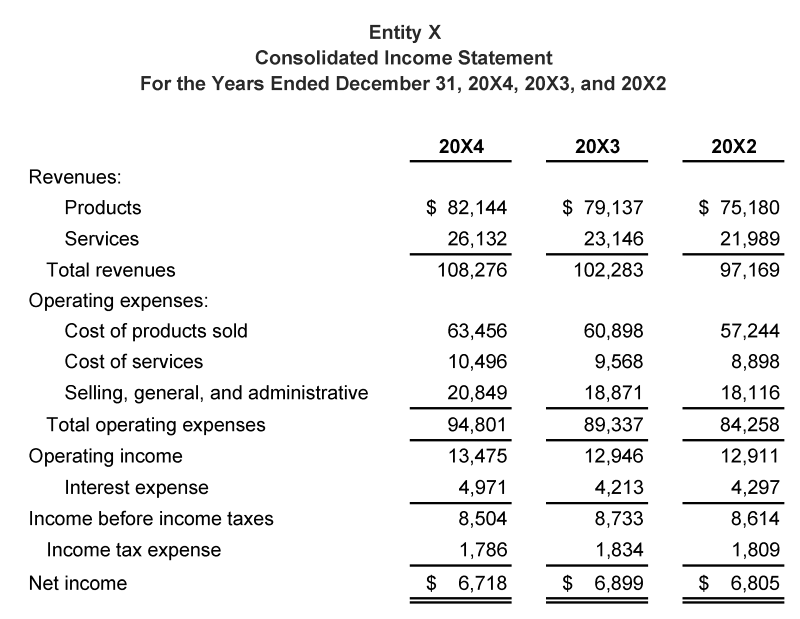
220-40-65-1For the year ended December 31, 20X4, Entity X, which is a manufacturer with significant service operations, presents the following comparative income statement.
  • "Entity X Consolidated Income Statement For the Years Ended December 31, 20X4, 20X3, and 20X2" 20X4 20X3 20X2 Revenues: Products " $82,144 " " $79,137 " " $75,180 " Services "26,132" "23,146" "21,989" Total revenues " 108,276 " " 102,283 " " 97,169 " Operating expenses: Cost of products sold "63,456" "60,898" "57,244" Cost of services " 10,496 " " 9,568 " "8,898" "Selling, general, and administrative" " 20,849 " " 18,871 " "18,116" Total operating expenses " 94,801 " " 89,337 " " 84,258 " Operating income " 13,475 " " 12,946 " " 12,911 " Interest expense "4,971" "4,213" "4,297" Income before income taxes " 8,504 " " 8,733 " " 8,614 " Income tax expense "1,786" "1,834" "1,809" Net income " $6,718 " " $6,899 " " $6,805 "
220-40-55-5
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
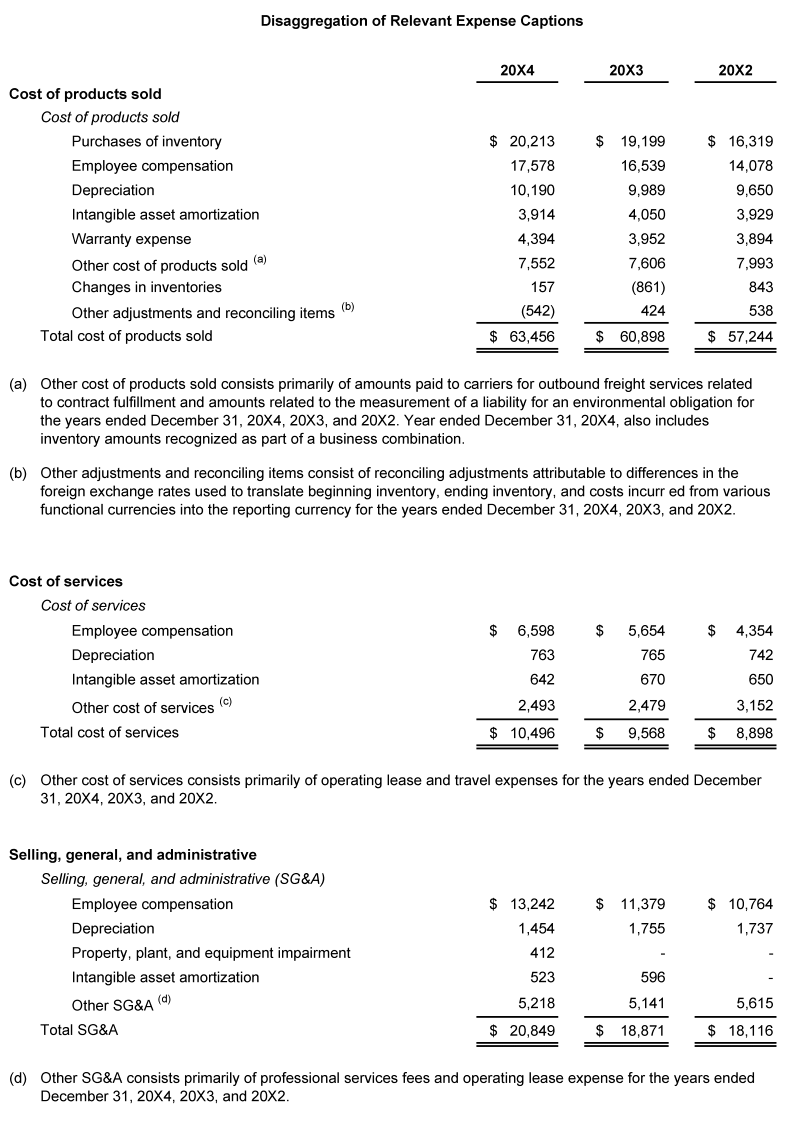
220-40-65-1Entity X provides a disclosure that disaggregates the cost of products sold; cost of services; and selling, general, and administrative expense captions into the categories listed in paragraph 220-40-50-6. Those expense captions were identified as relevant expense captions because those captions contain one or more of the expense categories listed in paragraph 220-40-50-6. Even though Entity X presents other expense captions on the face of its consolidated income statement, such as interest expense and income tax expense, those expense captions do not contain any of the expense categories listed in paragraph 220-40-50-6 (including those described in paragraphs ); therefore, those expense captions do not need to be disaggregated.
220-40-55-6
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1Because cost of products sold contains amounts related to inventory within the scope of Topic 330, Entity X may elect to disclose the amounts under a cost-incurred basis or expense-incurred basis. In this Example, Entity X chooses to disclose the disaggregation of cost of products sold on a cost-incurred basis (that is, the amounts disclosed include costs incurred that were capitalized to inventory during the current reporting period and costs incurred that were directly expensed during the current reporting period) in accordance with paragraph 220-40-50-31(a). Because Entity X discloses the required expense categories using a cost-incurred basis, the entity discloses the changes in inventories caption and the other adjustments and reconciling items caption in accordance with paragraphs . In accordance with paragraph 220-40-50-34, Entity X qualitatively describes the nature of amounts included in other adjustments and reconciling items. If Entity X had instead disclosed the required expense categories on an expense-incurred basis (that is, the amounts disclosed comprise expense amounts related to the derecognition of inventory that was previously capitalized in accordance with Topic 330 and any costs incurred that were directly expensed during the current reporting period) in accordance with paragraph 220-40-50-31(b), then the changes in inventories caption and the other adjustments and reconciling items caption would not be necessary in the disaggregation disclosure.
220-40-55-7
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1Entity X also recognizes impairment of property, plant, and equipment classified as held and used in selling, general, and administrative expenses and, therefore, includes that impairment as a separate category in the tabular format disclosure in accordance with paragraph 220-40-50-21(c).
220-40-55-8
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1Entity X recognizes expenses associated with warranty accruals entirely within cost of products sold and, therefore, includes warranty expense as a separate category in accordance with paragraph 220-40-50-22(k).
220-40-55-9
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1Entity X recognizes operating lease costs in both cost of services and selling, general, and administrative expenses. Therefore, in accordance with paragraph 220-40-50-22, Entity X is not required to separately disclose the amounts of cost of services and selling, general, and administrative expenses that are attributable to operating lease cost. Instead, those expenses are included in the amount for other items for each relevant expense caption in accordance with paragraph 220-40-50-30.
220-40-55-10
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1Entity X recognizes amounts related to the initial recognition and subsequent measurement of a liability for an environmental obligation in cost of products sold (see Subtopic 410-30 on asset retirement and environmental obligations). In accordance with paragraph 220-40-50-16, Entity X is not required to disaggregate that amount into the expense categories listed in paragraph 220-40-50-6. Instead, that expense is included in the amount for other items in accordance with paragraph 220-40-50-30.
220-40-55-11
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1Entity X provides the following disclosure.
  • Disaggregation of Relevant Expense Captions Cost of products sold Cost of products sold 20X4 20X3 20X2 Purchases of inventory " $20,213 " " $19,199 " " $16,319 " Employee compensation "17,578" "16,539" "14,078" Depreciation " 10,190 " " 9,989 " " 9,650 " Intangible asset amortization "3,914" "4,050" "3,929" Warranty expense " 4,394 " " 3,952 " " 3,894 " Other cost of products sold (a) "7,552" "7,606" "7,993" Changes in inventories 157 (861) 843 Other adjustments and reconciling items (b) (542) 424 538 Total cost of products sold " $63,456 " " $60,898 " " $57,244 " TRUE TRUE TRUE (a) "Other cost of products sold consists primarily of amounts paid to carriers for outbound freight services related to contract fulfillment and amounts related to the measurement of a liability for an environmental obligation for the years ended December 31, 20X4, 20X3, and 20X2. Year ended December 31, 20X4, also includes inventory amounts recognized as part of a business combination." (b) "Other adjustments and reconciling items consist of reconciling adjustments attributable to differences in the foreign exchange rates used to translate beginning inventory, ending inventory, and costs incurred from various functional currencies into the reporting currency for the years ended December 31, 20X4, 20X3, and 20X2. " Cost of services Cost of services Employee compensation " $6,598 " " $5,654 " " $4,354 " Depreciation 763 765 742 Intangible asset amortization 642 670 650 Other cost of services (c) "2,493" "2,479" "3,152" Total cost of services " $10,496 " " $9,568 " " $8,898 " (c) "Other cost of services consists primarily of operating lease and travel expenses for the years ended December 31, 20X4, 20X3, and 20X2." "Selling, general, and administrative" "Selling, general, and administrative (SG&A)" Employee compensation " $13,242 " " $11,379 " " $10,764 " Depreciation " 1,454 " " 1,755 " " 1,737 " "Property, plant, and equipment impairment" 412 - - Intangible asset amortization 523 596 - Other SG&A (d) "5,218" "5,141" "5,615" Total SG&A " $20,849 " " $18,871 " " $18,116 " (d) "Other SG&A consists primarily of professional services fees and operating lease expense for the years ended December 31, 20X4, 20X3, and 20X2."
220-40-55-12
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1In addition to the tabular format disclosure illustrated in paragraph 220-40-55-11, Entity X also must disclose its selling expenses and how it defines selling expenses in accordance with paragraphs .
  • Selling Expenses
  • During the years ended December 31, 20X4, 20X3, and 20X2, selling expenses were $13,425, $12,123, and $11,585, respectively. The entity’s selling expenses include those expenses related to marketing and promotional activities and client relationship management.
220-40-55-13
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1This Example illustrates one type of tabular format disclosure that an entity could use to disclose disaggregated expense amounts in accordance with paragraphs . This Example also illustrates the disclosure of selling expenses in accordance with paragraphs .
220-40-55-14
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
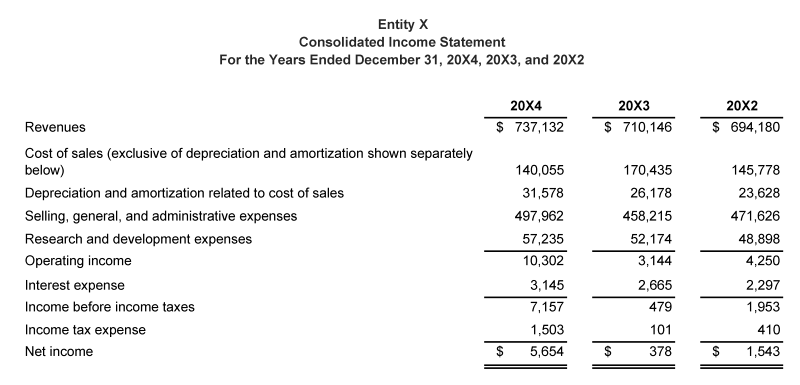
220-40-65-1For the year ended December 31, 20X4, Entity X, which is a services provider, presents the following comparative income statement.
  • "Entity X Consolidated Income Statement For the Years Ended December 31, 20X4, 20X3, and 20X2" 20X4 20X3 20X2 Revenues " $737,132 " " $710,146 " " $694,180 " Cost of sales (exclusive of depreciation and amortization shown separately below) "140,055" "170,435" "145,778" Depreciation and amortization related to cost of sales " 31,578 " " 26,178 " "23,628" "Selling, general, and administrative expenses" " 497,962 " " 458,215 " " 471,626 " Research and development expenses " 57,235 " " 52,174 " "48,898" Operating income " 10,302 " " 3,144 " " 4,250 " Interest expense "3,145" "2,665" "2,297" Income before income taxes " 7,157 " 479 " 1,953 " Income tax expense "1,503" 101 410 Net income " $5,654 " $378 " $1,543 "
220-40-55-15
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1Entity X provides a disclosure that disaggregates the cost of sales; depreciation and amortization; selling, general, and administrative expenses; and research and development expenses captions into the categories listed in paragraph 220-40-50-6. Those expense captions were identified as relevant expense captions because those captions contain one or more of the expense categories listed in paragraph 220-40-50-6. Even though Entity X presents other expense captions on the face of its consolidated income statement, such as interest expense and income tax expense, those expense captions do not contain any of the expense categories listed in paragraph 220-40-50-6 (including those described in paragraphs ); therefore, those expense captions do not need to be disaggregated.
220-40-55-16
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
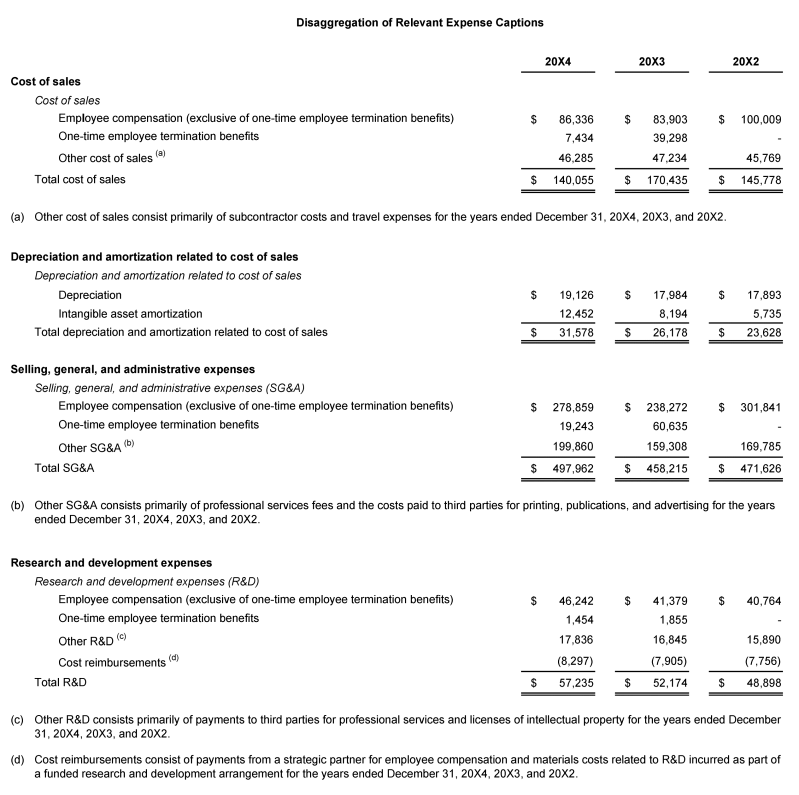
220-40-65-1Entity X also recognizes one-time employee termination benefits in cost of sales; selling, general, and administrative expenses; and research and development expenses and, therefore, includes this amount as a separate category in the tabular format disclosure in accordance with paragraph 220-40-50-21. Paragraph 220-40-50-21(e) requires that an entity disclose the amount of each major type of cost associated with an exit or disposal activity (for example, one-time employee termination benefits) that is recognized in each relevant expense caption in the same tabular format in which the disclosures required by paragraph 220-40-50-6 are provided. Because one-time employee termination benefits are a form of employee compensation, Entity X discloses that its employee compensation category excludes one-time employee termination benefits because one-time employee termination benefits are disclosed as a separate category.
220-40-55-17
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1Entity X has a funded research and development cost-sharing arrangement with a strategic partner. Entity X recognizes an expense reimbursement from the strategic partner in research and development expenses and, in accordance with paragraph 220-40-50-26(a), elects to separately disclose the amount of that expense reimbursement. If Entity X had elected to present a relevant expense caption net of an expense reimbursement from another entity, it would have been required to disclose the amount of the expense categories that are included in each relevant expense caption. Additionally, in accordance with paragraph 220-40-50-29, Entity X qualitatively describes the expense categories to which the reimbursement relates.
220-40-55-18
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1Entity X provides the following disclosure.
  • Disaggregation of Relevant Expense Captions Cost of sales Cost of sales 20X4 20X3 20X2 Employee compensation (exclusive of one-time employee termination benefits) " $86,336 " " $83,903 " " $100,009 " One-time employee termination benefits " 7,434 " " 39,298 " - Other cost of sales (a) "46,285" "47,234" "45,769" Total cost of sales " $140,055 " " $170,435 " " $145,778 " (a) "Other cost of sales consist primarily of subcontractor costs and travel expenses for the years ended December 31, 20X4, 20X3, and 20X2." Depreciation and amortization related to cost of sales Depreciation and amortization related to cost of sales Depreciation " $19,126 " " $17,984 " " $17,893 " Intangible asset amortization " 12,452 " " 8,194 " " 5,735 " Total depreciation and amortization related to cost of sales " $31,578 " " $26,178 " " $23,628 " "Selling, general, and administrative expenses" "Selling, general, and administrative expenses (SG&A)" Employee compensation (exclusive of one-time employee termination benefits) " $278,859 " " $238,272 " " $301,841 " One-time employee termination benefits " 19,243 " " 60,635 " - Other SG&A (b) "199,860" "159,308" "169,785" Total SG&A " $497,962 " " $458,215 " " $471,626 " (b) "Other SG&A consists primarily of professional services fees and the costs paid to third parties for printing, publications, and advertising for the years ended December 31, 20X4, 20X3, and 20X2." Research and development expenses Research and development expenses (R&D) Employee compensation (exclusive of one-time employee termination benefits) " $46,242 " " $41,379 " " $40,764 " One-time employee termination benefits " 1,454 " " 1,855 " - Other R&D (c) "17,836" "16,845" "15,890" Cost reimbursements (d) "(8,297)" "(7,905)" "(7,756)" Total R&D " $57,235 " " $52,174 " " $48,898 " (c) "Other R&D consists primarily of payments to third parties for professional services and licenses of intellectual property for the years ended December 31, 20X4, 20X3, and 20X2." (d) "Cost reimbursements consist of payments from a strategic partner for employee compensation and materials costs related to R&D incurred as part of a funded research and development arrangement for the years ended December 31, 20X4, 20X3, and 20X2."
220-40-55-19
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1In addition to the tabular format disclosure illustrated in paragraph 220-40-55-18, Entity X also must disclose its selling expenses and how it defines selling expenses in accordance with paragraphs .
  • Selling Expenses
  • During the years ended December 31, 20X4, 20X3, and 20X2, selling expenses were $224,536, $223,493, and $231,892, respectively. The entity’s selling expenses include those expenses related to advertising and certain customer acquisition-related costs.
220-40-55-20
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1This Example illustrates one type of tabular format disclosure that an entity could use to disclose disaggregated expense amounts in accordance with paragraphs . This Example also illustrates the disclosure of selling expenses in accordance with paragraphs .
220-40-55-21
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
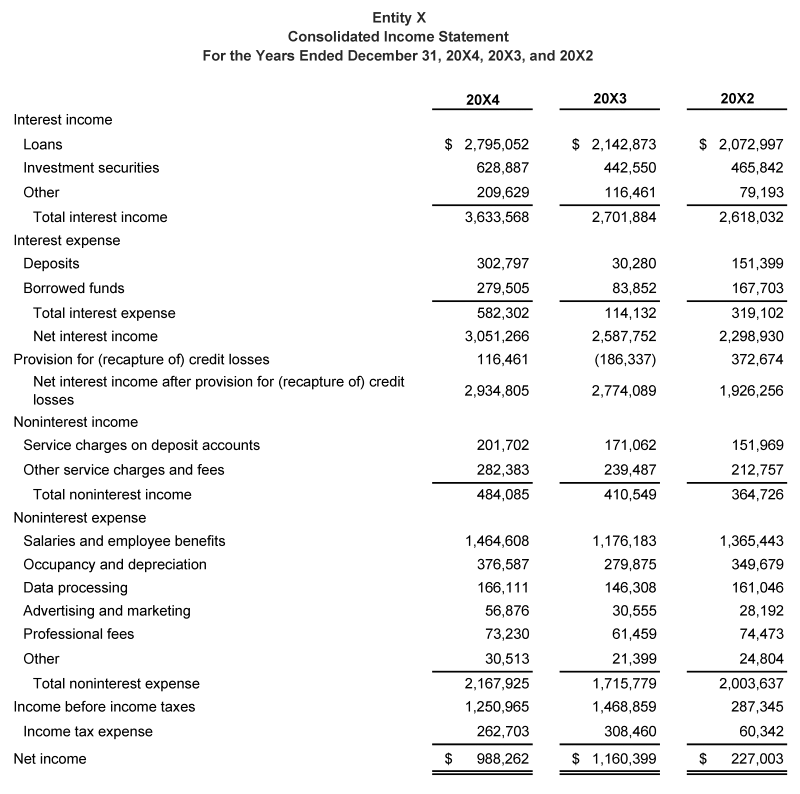
220-40-65-1For the year ended December 31, 20X4, Entity X, which is a bank, presents the following comparative income statement.
  • "Entity X Consolidated Income Statement For the Years Ended December 31, 20X4, 20X3, and 20X2" 20X4 20X3 20X2 Interest income Loans " $2,795,052 " " $2,142,873 " " $2,072,997 " Investment securities " 628,887 " " 442,550 " " 465,842 " Other "209,629" "116,461" "79,193" Total interest income "3,633,568" "2,701,884" "2,618,032" Interest expense Deposits " 302,797 " " 30,280 " " 151,399 " Borrowed funds "279,505" "83,852" "167,703" Total interest expense "582,302" "114,132" "319,102" Net interest income "3,051,266" "2,587,752" "2,298,930" Provision for (recapture of) credit losses " 116,461 " " (186,337)" " 372,674 " Net interest income after provision for (recapture of) credit losses " 2,934,805 " " 2,774,089 " " 1,926,256 " Noninterest income Service charges on deposit accounts "201,702" "171,062" "151,969" Other service charges and fees "282,383" "239,487" "212,757" Total noninterest income "484,085" "410,549" "364,726" Noninterest expense Salaries and employee benefits "1,464,608" "1,176,183" "1,365,443" Occupancy and depreciation "376,587" "279,875" "349,679" Data processing "166,111" "146,308" "161,046" Advertising and marketing "56,876" "30,555" "28,192" Professional fees "73,230" "61,459" "74,473" Other "30,513" "21,399" "24,804" Total noninterest expense "2,167,925" "1,715,779" "2,003,637" Income before income taxes " 1,250,965 " " 1,468,859 " " 287,345 " Income tax expense "262,703" "308,460" "60,342" Net income " $988,262 " " $1,160,399 " " $227,003 "
220-40-55-22
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
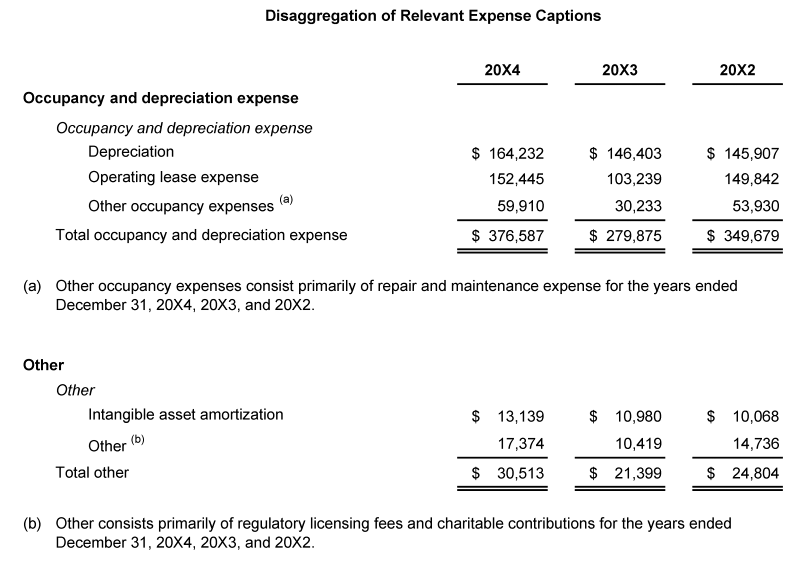
220-40-65-1Entity X provides a disclosure that disaggregates the occupancy and depreciation expense and other expense captions into the categories listed in paragraph 220-40-50-6. Those expense captions were identified as relevant expense captions because those captions contain one or more of the expense categories listed in paragraph 220-40-50-6. In this Example, even though Entity X also presents separate expense captions on the face of its consolidated income statement for interest expense, provision for (recapture of) credit losses, data processing, advertising and marketing, professional fees, and income tax expense, those expense captions do not contain any of the expense categories listed in paragraph 220-40-50-6 (including those described in paragraphs ); therefore, those expense captions do not need to be further disaggregated. Entity X applies the practical expedient for employee compensation described in paragraph 220-40-50-20 and elects to not repeat the amount presented on the face of the income statement in the notes to financial statements.
220-40-55-23
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1Entity X recognizes operating lease cost entirely within occupancy and depreciation expense and, therefore, includes operating lease cost as a separate category in accordance with paragraph 220-40-50-22(p).
220-40-55-24
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1Entity X provides the following disclosure.
  • Disaggregation of Relevant Expense Captions Occupancy and depreciation expense Occupancy and depreciation expense 20X4 20X3 20X2 Depreciation " $164,232 " " $146,403 " " $145,907 " Operating lease expense " 152,445 " " 103,239 " " 149,842 " Other occupancy expenses (a) "59,910" "30,233" "53,930" Total occupancy and depreciation expense " $376,587 " " $279,875 " " $349,679 " (a) "Other occupancy expenses consist primarily of repair and maintenance expense for the years ended December 31, 20X4, 20X3, and 20X2." Other Other Intangible asset amortization " $13,139 " " $10,980 " " $10,068 " Other (b) "17,374" "10,419" "14,736" Total other " $30,513 " " $21,399 " " $24,804 " (b) "Other consists primarily of regulatory licensing fees and charitable contributions for the years ended December 31, 20X4, 20X3, and 20X2."
220-40-55-25
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
220-40-65-1In addition to the tabular format disclosure illustrated in paragraph 220-40-55-24, Entity X also must disclose its selling expenses and how it defines selling expenses in accordance with paragraphs .
  • Selling Expenses
  • During the years ended December 31, 20X4, 20X3, and 20X2, the entity defined selling expenses to be the same as its advertising and marketing expenses, which are presented on the face of its consolidated income statement. The entity’s advertising and marketing expenses include costs incurred for advertising, market research, and business development.

220-40-65Transition and Open Effective Date Information

Source downloaded: .Record version 703e23cf4715. Effective date must be checked in the source.

220-40-65-1
Accounting Standards Update 2024-03
2028-06-13
2026-12-16
2027-12-16
2026-12-16
2027-12-16
2026-12-16
2027-12-16
2026-12-16
2027-12-16
2026-12-16
2027-12-16
2026-12-16
2027-12-16
2026-12-16
2027-12-16
The following represents the transition and effective date information related to Accounting Standards Updates No. 2024-03, Income Statement—Reporting Comprehensive Income—Expense Disaggregation Disclosures (Subtopic 220-40): Disaggregation of Income Statement Expenses, and No. 2025-01, Income Statement—Reporting Comprehensive Income—Expense Disaggregation Disclosures (Subtopic 220-40): Clarifying the Effective Date:
Effective date and early adoption
  1. a
    The pending content that links to this paragraph shall be effective for public business entities for annual reporting periods beginning after December 15, 2026, and interim reporting periods within annual reporting periods beginning after December 15, 2027. Early adoption is permitted.
Transition method
  1. b
    A public business entity shall apply the pending content that links to this paragraph prospectively to financial statements issued for reporting periods beginning after the effective date of the pending content that links to this paragraph. The disclosures required by the pending content that links to this paragraph do not need to be included in financial statements for reporting periods beginning before the effective date that are being presented for comparative purposes with financial statements issued for periods after the effective date.
  2. c
    A public business entity may elect to apply the pending content that links to this paragraph retrospectively to any or all prior periods presented in the financial statements. If applied to financial statements for periods beginning before the effective date, those disclosures shall be prepared and presented in accordance with this Subtopic.

Related subtopics