ASC 818-30
Environmental Credit Obligations
818 Environmental Credits and Environmental Credit Obligations
Source downloaded: .Record version 82f948f9e1ec. Effective date must be checked in the source.
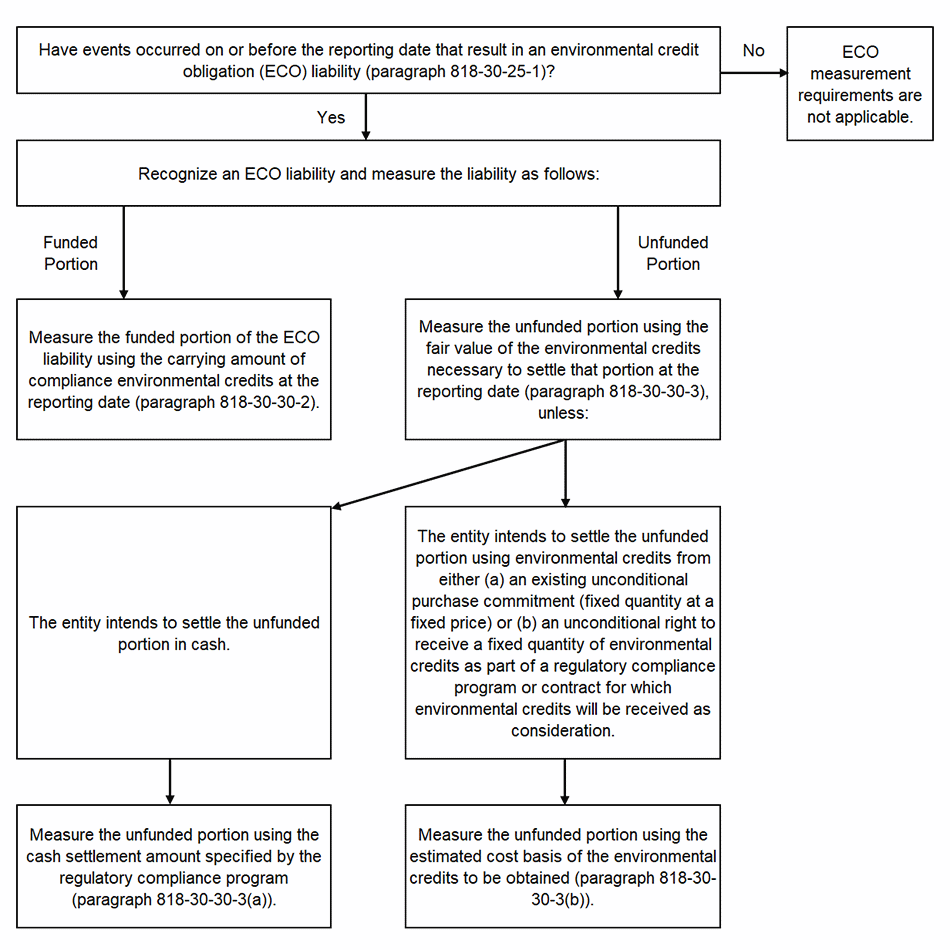
ASC 818-30 governs when and how an entity recognizes, measures, presents, and discloses an environmental credit obligation — a liability to remit environmental credits (e.g., emissions allowances, renewable energy certificates) under a regulatory compliance program. A liability is recognized when events on or before the reporting date would require remitting credits assuming the reporting date were the end of the compliance period (818-30-25-1). The liability is split into a funded portion, measured at the carrying amount of compliance environmental credits on hand under Subtopic 818-20 costing methods (818-30-30-2), and an unfunded portion, measured at fair value of the needed credits unless the entity intends to settle in cash or with credits from an unconditional commitment or right (818-30-30-3).
Key points (7)
- Recognize a liability when events occurring on or before the reporting date result in an environmental credit obligation, determined as if the reporting date were the end of the regulatory compliance period, even if the compliance period ends later (818-30-25-1).
- Costs of the obligation are recognized in earnings or, if appropriate, capitalized as part of another asset under another Topic (818-30-25-1; presentation of changes and derecognition gains/losses must be consistent, 818-30-45-3 through 45-4).
- Apply Subtopic 818-20's recognition and measurement to the credits first; the funded portion is measured using the carrying amount of compliance environmental credits expected to be derecognized, using the same costing method (FIFO, average cost, etc.) applied under 818-20-35-2 (818-30-30-1 through 30-2).
- Noncompliance credits, credits never recognized as assets (818-20-25-1), and previously derecognized credits (818-20-40-2) are excluded from the funded portion, and only credits held at the reporting date count (818-30-30-2; 818-30-55-5).
- The unfunded portion is measured at the fair value of credits needed at the reporting date, unless the entity intends to settle in cash (then the program's cash settlement amount) or with credits from an existing unconditional purchase commitment or unconditional right (then the estimated cost basis, which may differ from the contract price) (818-30-30-3).
- Expected future activities that could increase, reduce, or eliminate the obligation may not be considered in measurement (818-30-30-4; 818-30-55-16); a right is not unconditional if contingent on future performance such as continuing to operate in the jurisdiction (818-30-55-7).
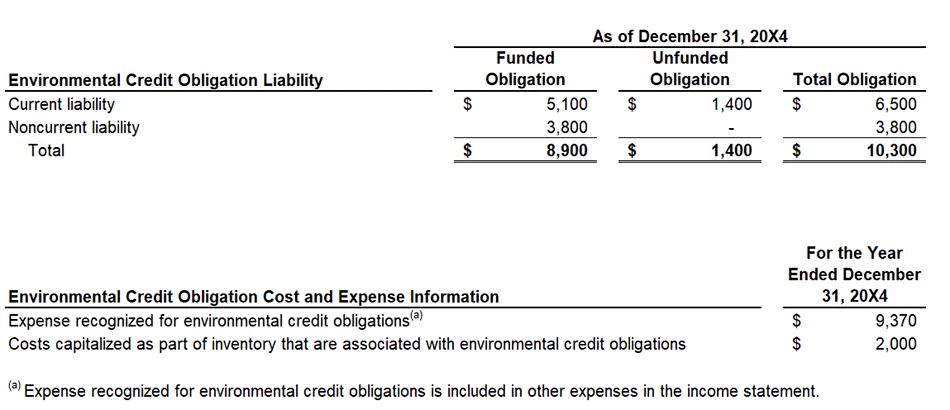
- Present obligation liabilities separately from compliance environmental credit assets, classified current/noncurrent (818-30-45-1 through 45-2); derecognize under Subtopic 405-20 (818-30-40-1); annual disclosures include program activities and settlement terms, unfunded measurement approach, funded/unfunded current and noncurrent amounts, total expense and income statement line, and capitalized amounts (818-30-50-1 through 50-4).
For students. The signature rule is the "as if the reporting date were the end of the compliance period" test: you measure the obligation on facts existing now and ignore forecast emissions or future fuel-efficient sales that might wipe it out. A common error is netting the credit asset against the obligation or measuring the whole liability at fair value — the funded portion carries the credits' historical carrying amount, and only the shortfall is fair valued (or measured at the cash settlement amount or committed cost basis).
Machine-generated study aid for ASC 818-30. Check the source paragraphs below.
818-30-00Status
Source downloaded: .Record version cd3be17c7e70. Effective date must be checked in the source.
818-30-05Overview and Background
Source downloaded: .Record version 7580a7eea3c9. Effective date must be checked in the source.
818-30-15Scope and Scope Exceptions
Source downloaded: .Record version 2b29cb19da4e. Effective date must be checked in the source.
818-30-25Recognition
Source downloaded: .Record version d7bf96a341fb. Effective date must be checked in the source.
818-30-30Initial Measurement
Source downloaded: .Record version 354e9239087e. Effective date must be checked in the source.
- a
- bEnvironmental credits that were never recognized as assets in accordance with paragraph 818-20-25-1
- cEnvironmental credits that were previously derecognized in accordance with paragraph 818-20-40-2.
- aCash. An entity that intends to settle the unfunded portion by remitting cash shall measure the unfunded portion using the cash settlement amount specified by the regulatory compliance program.
- bEnvironmental credits that will be received before the settlement of the liability from either an existing unconditional purchase commitment for a fixed quantity of environmental credits at a fixed price or an unconditional right to receive a fixed quantity of environmental credits as part of a regulatory compliance program or contract for which environmental credits will be received as consideration. For purposes of applying the requirements in this paragraph, an unconditional right exists when an entity has satisfied all performance requirements of the regulatory compliance program or contract necessary to receive environmental credits as of the reporting date. An entity that intends to settle the unfunded portion using environmental credits from those unconditional commitments or rights shall measure the unfunded portion using the estimated cost basis of the environmental credits to be obtained (which may differ from the fixed price per the contract).
818-30-35Subsequent Measurement
Source downloaded: .Record version dce19a0d22f9. Effective date must be checked in the source.
818-30-40Derecognition
Source downloaded: .Record version fb841651f3bb. Effective date must be checked in the source.
818-30-45Other Presentation Matters
Source downloaded: .Record version 2d2cee378289. Effective date must be checked in the source.
Balance Sheet
Income Statement
818-30-50Disclosure
Source downloaded: .Record version 47afdc0a8c22. Effective date must be checked in the source.
- aThe activities or events that result in environmental credit obligation liabilities under those programs, including the nature and timing of settlement provisions
- bThe accounting policies used to account for the environmental credit obligations in accordance with Topic 235 on notes to financial statements
- cHow the unfunded portion of an environmental credit obligation liability is measured in accordance with paragraph 818-30-30-3
- dSignificant estimates and judgments used in applying the guidance.
- aThe funded portion of an environmental credit obligation liability
- bThe unfunded portion of an environmental credit obligation liability.
- aThe total costs associated with environmental credit obligation liabilities that are capitalized in the carrying amount of another asset during the reporting period in accordance with another Topic
- bA description of the other asset.
818-30-55Implementation Guidance and Illustrations
Source downloaded: .Record version 8cc605d3d88a. Effective date must be checked in the source.
Implementation Guidance
Illustrations
Related subtopics
- 818-20 Environmental CreditsEnvironmental Credits and Environmental Credit Obligations
- 818-10 OverallEnvironmental Credits and Environmental Credit Obligations
- 410-20 Asset Retirement ObligationsAsset Retirement and Environmental Obligations
- 410-980 Regulated OperationsAsset Retirement and Environmental Obligations
- 715-980 Regulated OperationsCompensation—Retirement Benefits
- 205-20 Discontinued OperationsPresentation of Financial Statements