ASC

ASC 715-980

Regulated Operations

715 Compensation—Retirement Benefits

Source downloaded: .Record version e30c5398aa49. Effective date must be checked in the source.

ASC 715-980 tells rate-regulated entities how to account for the difference between net periodic pension cost (715-30) or net periodic postretirement benefit cost (715-60) and the amounts of those costs allowed for rate-making purposes. The regulator's actions create a regulatory asset (deferred cost whose recovery is probable) or a liability (unearned revenue collected for future costs), which changes only the timing of expense recognition, not the underlying 715-30/715-60 measurement. Deferral of 715-60 costs as a regulatory asset is permitted only if strict criteria about the rate order, five-year phase-in, roughly 20-year deferral-recovery period, and non-increasing rate escalation are met.

Key points (7)
  • The difference between net periodic pension cost under Subtopic 715-30 and pension cost allowed for rate-making purposes is recognized as an asset or liability created by the actions of the regulator; those actions change only the timing of expense recognition (715-980-25-1).
  • An employer with regulated operations must apply 715-30 for financial reporting even if a different method is used to determine allowable pension cost for rate-making purposes (715-980-55-2); the difference is an asset if 980-340-25-1 criteria are met or a liability if the 980-405-25-1(b) situation exists (715-980-55-4).
  • No regulatory asset for 715-60 costs may be recorded for a continuing plan if the regulator continues to include other postretirement benefit costs in rates on a pay-as-you-go basis (715-980-25-4).
  • For a continuing plan, a regulatory asset for the 715-60 vs. rate-recovery difference is recognized only if recovery of future revenue at least equal to the deferred cost is probable and all four criteria of 715-980-25-5(b) are met: an enabling rate order/policy statement, inclusion of annual 715-60 costs in rates within about five years of adoption, a combined deferral-recovery period not exceeding about 20 years, and scheduled rate increases that do not escalate year over year.
  • For discontinued plans (no current service cost), a regulatory asset is recorded if it is probable that future revenue at least equal to the deferred 715-60 costs will be recovered in rates within about 20 years after adoption, and pay-as-you-go rate recovery may continue (715-980-25-7).
  • If the 715-980-25-5 criteria are not met initially but are met later, the regulatory asset is recognized in the period the criteria are met (715-980-25-8).
  • A regulator cannot eliminate a liability it did not impose, so the requirement to recognize a plan's underfunded status as a liability under 715-30-25-1 through 25-2 is unaffected by regulation (715-980-55-7); disclosure must describe the regulatory treatment, pending regulatory action, deferred 715-60 costs at the balance sheet date, and the expected recovery period (715-980-50-1).

For students. This is a narrow utility-industry overlay: the pension/OPEB expense in the income statement is still the 715-30/715-60 amount, and the regulator's actions only shift timing via a regulatory asset or unearned-revenue liability. The common misunderstanding is thinking rate-regulated entities may report the rate-making pension cost as their expense, or that a regulator's pay-as-you-go treatment can eliminate the recognized underfunded status of the plan.

Machine-generated study aid for ASC 715-980. Check the source paragraphs below.

715-980-00Status

Source downloaded: .Record version 90ff48a20886. Effective date must be checked in the source.

715-980-05Overview and Background

Source downloaded: .Record version e3e373ca9a59. Effective date must be checked in the source.

715-980-05-1
This Subtopic provides guidance for compensation related to pension costs and other postretirement benefit costs for entities with regulated operations.

Postretirement Pension Cost

715-980-05-2
This Subtopic provides guidance for the difference between net periodic pension cost as defined in Subtopic 715-30 and amounts of pension cost considered for rate-making purposes as an asset or a liability created by the actions of the regulator.

Other Postretirement Benefit Cost

715-980-05-3
This Subtopic provides guidance for the difference between net periodic postretirement benefit cost as defined in Subtopic 715-60 and amounts of postretirement benefit cost considered for rate-making purposes as an asset or a liability created by the actions of the regulator.

715-980-15Scope and Scope Exceptions

Source downloaded: .Record version 76882b100ce6. Effective date must be checked in the source.

Overall Guidance

715-980-15-1
This Subtopic follows the same Scope and Scope Exceptions as outlined in the Overall Subtopic, see Section 980-10-15. Accordingly, the guidance related to the accounting for regulatory assets related to other postretirement benefit costs (see Subtopic 715-60) is for rate-regulated entities that meet the criteria for applying this Topic. In addition, the provisions of paragraphs 715-30-35-7A and 715-60-35-10A shall not change the accounting for regulatory assets related to postretirement pension cost and other postretirement benefit cost for rate-regulated entities.

715-980-25Recognition

Source downloaded: .Record version b5ce7482f7f2. Effective date must be checked in the source.

Postretirement Pension Cost

715-980-25-1
This Subtopic requires that the difference between net periodic pension cost as defined in Subtopic 715-30 and amounts of pension cost considered for rate-making purposes be recognized as an asset or a liability created by the actions of the regulator. Those actions of the regulator change the timing of recognition of net pension cost as an expense; they do not otherwise affect the requirements of that Subtopic.
715-980-25-2
Example 1 (see paragraph 980-715-55-9) illustrates accounting for pensions by an employer with regulated operations.

Other Postretirement Benefit Cost

715-980-25-3
For purposes of this Subtopic, other postretirement benefits refer to all forms of benefits, other than pensions, provided by an employer to retirees.
715-980-25-4
For continuing postretirement benefit plans, a regulatory asset related to Subtopic 715-60 costs shall not be recorded if the regulator continues to include other postretirement benefit costs in rates on a pay-as-you-go basis. The application of this Topic requires that a rate-regulated entity's rates be designed to recover the specific entity's costs of providing the regulated service or product. Accordingly, an entity's cost of providing a regulated service or product includes the costs provided for in Subtopic 715-60.
715-980-25-5
For a continuing postretirement benefit plan a rate-regulated entity shall recognize a regulatory asset for the difference between Subtopic 715-60 costs and other postretirement benefit costs included in the entity's rates if the entity does both of the following:
  1. a
    Determines that it is probable that future revenue in an amount at least equal to the deferred cost (regulatory asset) will be recovered in rates
  2. b
    Meets all of the following criteria:
    1. 1
      The rate-regulated entity's regulator has issued a rate order or issued a policy statement or a generic order applicable to entities within the regulator's jurisdiction that allows both for the deferral of Subtopic 715-60 costs and for the subsequent inclusion of those deferred costs in the entity's rates.
    2. 2
      The annual Subtopic 715-60 costs (including amortization of the transition obligation) will be included in rates within approximately five years from the date of adoption of that Subtopic. The change to full accrual accounting may take place in steps, but the period for deferring additional amounts shall not exceed approximately five years.
    3. 3
      The combined deferral-recovery period authorized by the regulator for the regulatory asset shall not exceed approximately 20 years from the date of adoption of Subtopic 715-60. To the extent that the regulator imposes a deferral-recovery period for those costs provided for in Subtopic 715-60 greater than approximately 20 years, any proportionate amount of such costs not recoverable within approximately 20 years shall not be recognized as a regulatory asset.
    4. 4
      The percentage increase in rates scheduled under the regulatory recovery plan for each future year shall be no greater than the percentage increase in rates scheduled under the plan for each immediately preceding year. This criterion is similar to that required for phase-in plans in paragraph 980-340-25-3(d). Recovery of the regulatory asset in rates on a straight-line basis would meet this criterion.
715-980-25-6
This guidance applies to rate-regulated entities that elect to immediately recognize their postretirement benefit transition obligation under Subtopic 715-60 as well as those entities that elect to delay the recognition of and amortize their postretirement benefit transition obligation in accordance with that Subtopic.
715-980-25-7
For discontinued plans, a regulatory asset related to Subtopic 715-60 costs shall be recorded if it is probable that future revenue in an amount at least equal to any deferred that Subtopic costs will be recovered in rates within approximately 20 years following the adoption of that Subtopic. Rate recovery during that period may continue on a pay-as-you-go basis. For purposes of this guidance, a discontinued plan is one that results in employees not earning additional benefits for future service (that is, one that has no current service costs).
715-980-25-8
If an entity does not initially meet the criteria established in Section 980-715-25 but meets those criteria in a subsequent period, then a regulatory asset related to Subtopic 715-60 costs shall be recognized in the period those criteria are met.

715-980-45Other Presentation Matters

Source downloaded: .Record version 4b53c4e1284c. Effective date must be checked in the source.

715-980-45-1
A rate-regulated entity shall present the amount of net periodic pension cost and net periodic postretirement benefit cost in accordance with the provisions of paragraph 715-20-45-3A.

715-980-50Disclosure

Source downloaded: .Record version db80c11e3ad9. Effective date must be checked in the source.

Regulatory Treatment of Postretirement Benefit Costs

715-980-50-1
A rate-regulated entity shall disclose in its financial statements a description of the regulatory treatment of postretirement benefit costs, the status of any pending regulatory action, the amount of any Subtopic 715-60 costs deferred as a regulatory asset at the balance sheet date, and the period over which the deferred amounts are expected to be recovered in rates.

715-980-55Implementation Guidance and Illustrations

Source downloaded: .Record version 3aabc5d48d3b. Effective date must be checked in the source.

715-980-55-1
All implementation guidance and illustrations assume that the entity meets the criteria of paragraph 980-10-15-2 for the application of this Topic by the entity; thus recovery of any cost is probable if that cost is designated for future recovery by the regulator.

Implementation Guidance

715-980-55-2
An employer with regulated operations shall account for the effects of applying Subtopic 715-30 for financial reporting purposes even if another method of accounting for pensions is used for determining allowable pension cost for rate-making purposes.
715-980-55-3
As indicated in paragraph 980-715-25-1, Subtopic 715-30 applies to employers with regulated operations.
715-980-55-4
If this Subtopic applies to the employer, and the amount of net periodic pension cost determined under the method used for rate-making purposes differs from that determined under Subtopic 715-30, the difference would be either of the following:
  1. a
    An asset if the criteria in paragraph 980-340-25-1 are met
  2. b
    A liability if the situation is as described in paragraph 980-405-25-1(b).
715-980-55-5
Usually, continued use of different methods for rate-making purposes and general-purpose external financial reporting purposes would result in either the criteria in paragraph 980-340-25-1 being met or the situation described in paragraph 980-405-25-1(b). However, if pension cost determined in accordance with Subtopic 715-30 exceeds pension cost determined in accordance with the method used in setting current rates, the criteria in paragraph 980-340-25-1 would not be met if both of the following conditions exist:
  1. a
    It is probable that the regulator soon will accept a change for rate-making purposes so that pension cost is determined in accordance with Subtopic 715-30.
  2. b
    It is not probable that the regulator will provide revenue to recover the excess cost that results from the use of Subtopic 715-30 for financial reporting purposes during the period between the date that the employer adopts that Subtopic and the rate case implementing the change.
715-980-55-6
Similarly, if pension cost determined in accordance with the method used in setting current rates exceeds pension cost determined in accordance with Subtopic 715-30, the situation would not be as described in paragraph 980-405-25-1(b) if it is probable that all of the following conditions exist:
  1. a
    The regulator soon will accept a change for rate-making purposes so that pension cost is determined in accordance with Subtopic 715-30.
  2. b
    The regulator will not hold the employer responsible for the costs that were intended to be recovered by the current rates and that have been deferred by the change in method.
  3. c
    The regulator will provide revenue to recover those same costs when they are eventually recognized under the method required by Subtopic 715-30.
715-980-55-7
Because a regulator cannot eliminate a liability that was not imposed by its actions, the need to recognize the underfunded status of a defined benefit plan as a liability under paragraphs is unaffected by regulation.
715-980-55-8
See Example 1 (paragraphs 980-715-55-9) for the employer's accounting when paragraphs 980-340-25-1 and 980-405-25-1(b) apply.

Illustrations

715-980-55-9
This Example illustrates the guidance for recognition of postretirement pension cost in paragraph 980-715-25-1.
715-980-55-10
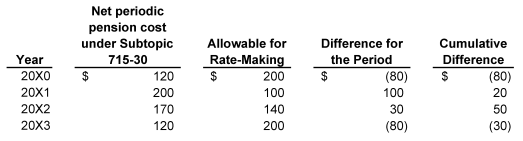
An employer with regulated operations sponsors a defined benefit pension plan that is accounted for pursuant to Subtopic 715-30. To simplify the Example, it is assumed that there are no remaining differences between amounts previously recognized as net periodic pension cost and amounts allowable for rate-making purposes. The employer's determination of net periodic pension cost under that Subtopic, however, differs from that allowable for rate-making purposes in the timing of recognition of net periodic pension cost as an expense. The following schedule shows the amounts under both bases for the years 20X0-20X3.
  • Year Net periodic pension cost under Subtopic 715-20 Allowable for Rate-Making Difference for the Period Cumulative Difference 20X0 $120 $200 $(80) $(80) 20X1 200 100 100 20 20X2 170 140 30 50 20X3 120 200 (80) (30)
715-980-55-11
In 20X0, the amount allowable for rate-making purposes exceeds net periodic pension cost determined under Subtopic 715-30. In that case, paragraph 980-405-25-1(b) requires the amount determined under Subtopic 715-30 ($120) to be recognized as net periodic pension cost in the employer's financial statements.
715-980-55-12
The difference ($80) between net periodic pension cost determined under Subtopic 715-30 ($120) and that allowable for rate-making purposes ($200) is recognized as a liability (unearned revenue) and represents an amount collected or collectible for recovery of future pension cost. When that pension cost is incurred for financial reporting purposes, the liability (unearned revenue) shall be eliminated and revenue shall be recognized.
715-980-55-13
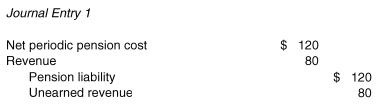
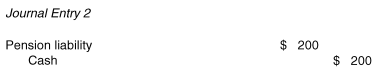
The journal entries to account for the accrual of net periodic pension cost and the contribution made to the pension plan during the year are as follows.
  • Journal Entry 1 Net periodic pension cost $120 Revenue 80 Pension liability $120 Unearned revenue 80
    • To record net periodic pension cost for the period and the liability created by actions of the regulator
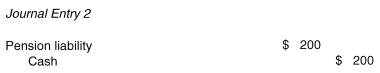
  • Journal Entry 2 Pension liability $200 Cash $200
    • To record contribution to pension plan
715-980-55-14
No modifications of the disclosure required by paragraph 715-20-50-1(h) are required in this case because the accounting required by this Topic does not change the amount of net periodic pension cost recognized under Subtopic 715-30. (See the table in paragraph 980-715-55-10.)
715-980-55-15
In 20X1, the amount allowable for rate-making purposes is less than net periodic pension cost determined under Subtopic 715-30 by $100. Of that amount, $80 was allowable for rate-making purposes in 20X0. Therefore, the 20X0 unearned revenue of $80 is recognized as revenue for 20X1. Paragraph 980-340-25-1 requires the remaining portion of the $100 difference ($20) to be capitalized as an incurred cost for which future recovery is assured by actions of the regulator.
715-980-55-16
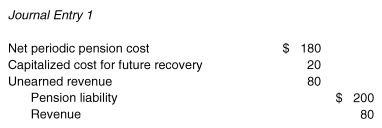
The journal entries to account for the accrual of net periodic pension cost and the contribution made to the pension plan during the year are as follows.
  • Journal Entry 1 Net periodic pension cost $180 Capitalized cost for future recovery 20 Unearned revenue 80 Pension liability $200 Revenue 80
    • To record net periodic pension cost for the period and the asset created by actions of the regulator
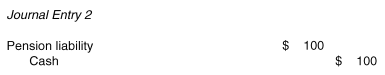
  • Journal Entry 2 Pension liability $100 Cash $100
    • To record contribution to pension plan
715-980-55-17
In this case, the accounting required by this Topic changes the amount of net periodic pension cost that otherwise would have been recognized under Subtopic 715-30 requiring modification of the disclosure required by paragraph 715-20-50-1(h). (See the table in paragraph 980-715-55-10.)
715-980-55-18
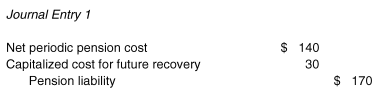
In 20X2, the amount allowable for rate-making purposes is less than net periodic pension cost determined under Subtopic 715-30 by $30. None of that amount was allowable for rate-making purposes in prior years. Paragraph 980-340-25-1 requires the $30 to be capitalized as an incurred cost for which future recovery is assured by actions of the regulator.
715-980-55-19
The journal entries to account for the accrual of net periodic pension cost and the contribution made to the pension plan during the year are as follows.
  • Journal Entry 1 Net periodic pension cost $140 Capitalized cost for future recovery 30 Pension liability $170
    • To record net periodic pension cost for the period and the asset created by actions of the regulator
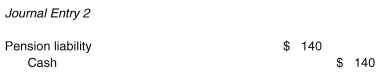
  • Journal Entry 2 Pension liability $140 Cash $140
    • To record contribution to pension plan
715-980-55-20
The situation in 20X2 is similar to that in 20X1, necessitating additional disclosure. (See the table in paragraph 980-715-55-10.)
715-980-55-21
In 20X3, the amount allowable for rate-making purposes exceeds net periodic pension cost determined under Subtopic 715-30 by $80. In prior years (20X1 and 20X2), $50 of that amount was recognized as a capitalized cost.
715-980-55-22
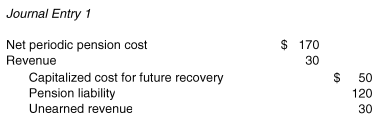
Accordingly, that capitalized cost ($50) is expensed in 20X3. Additionally, paragraph 980-405-25-1 requires recognition of a liability (unearned revenue) equal to the remaining portion ($30) of the amount allowable for rate-making purposes in excess of net periodic pension cost determined under Subtopic 715-30 [($200 - $120) - $50 = $30]. When that pension cost is incurred for financial reporting purposes, the $30 liability (unearned revenue) shall be eliminated and revenue shall be recognized.
715-980-55-23
The journal entries to account for the accrual of net periodic pension cost and the contribution made to the pension plan during the year are as follows.
  • Journal Entry 1 Net periodic pension cost $170 Revenue 30 Capitalized cost for future recovery $50 Pension liability 120 Unearned revenue 30
    • To record net periodic pension cost for the period and the liability created by actions of the regulator
  • Journal Entry 2 Pension liability $200 Cash $200
    • To record contribution to pension plan
715-980-55-24
The situation in 20X3 is similar to that in 20X1 and 20X2, necessitating additional disclosure. (See the table in paragraph 980-715-55-10.)
715-980-55-25
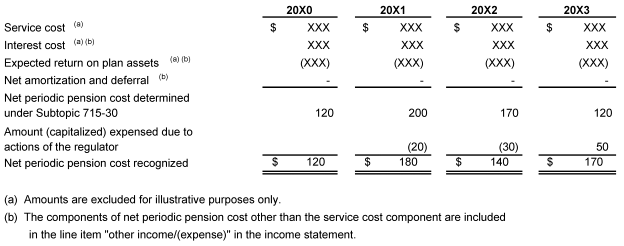
The following illustrates the disclosure of the components of net periodic pension cost for 20X0-20X3. It is assumed that there is no transition asset or obligation remaining in accumulated other comprehensive income and there are no gains or losses for the four-year period.
  • 20X0 20X1 20X2 20X3 Service cost (a) $ XXX $ XXX $ XXX $ XXX Interest cost (a) XXX XXX XXX XXX Actual return on plan assets (a) (XXX) (XXX) (XXX) (XXX) Net amortization and deferral - - - - Net periodic pension cost determined under Subtopic 715-20 120 200 170 120 Amount (capitalized) expensed due to actions of the regulator (20) (30) 50 Net periodic pension cost recognized $120 $180 $140 $170 (a) Amounts are excluded for illustrative purposes only.

Related subtopics