ASC 340-980
Regulated Operations
340 Other Assets and Deferred Costs
Source downloaded: .Record version 8f6ef81835a3. Effective date must be checked in the source.
This subtopic governs when a rate-regulated entity may capitalize incurred costs as regulatory assets (deferred costs) and, in particular, how to account for phase-in plans — rate-making arrangements that defer part of the rate increase caused by placing a newly completed plant in service in order to avoid a "rate spike." A cost is capitalized only if it is probable that future revenue at least equal to the cost will result from including it in allowable costs and that revenue is intended to recover the previously incurred cost rather than fund similar future costs (980-340-25-1). Amounts deferred under a phase-in plan may be capitalized only for plants completed or substantially constructed before January 1, 1988, and only if the plan meets four strict criteria (980-340-25-3).
Key points (7)
- An incurred cost that would otherwise be expensed is capitalized as a regulatory asset only if (a) it is probable (Topic 450) that future revenue at least equal to the cost will result from its inclusion in allowable costs and (b) the revenue is provided to recover the previously incurred cost rather than to fund expected similar future costs (980-340-25-1); a cost failing these criteria is recognized later when they are met, and is charged to earnings if it ceases to meet them (980-340-40-1).
- For a phase-in plan on a plant with no substantial physical construction before January 1, 1988, none of the allowable costs deferred by the regulator may be capitalized for financial reporting (980-340-25-2).
- For plants completed or substantially constructed before January 1, 1988, all deferred allowable costs are capitalized as a separate deferred charge only if all four criteria are met: a formal plan agreed to by the regulator, specified timing of recovery, recovery of all deferrals within 10 years of when deferrals begin, and scheduled percentage rate increases that do not grow year over year (980-340-25-3); failing any one criterion, none may be capitalized.
- An allowance for earnings on shareholders' investment is not an incurred cost that would otherwise be charged to expense and cannot be capitalized under 980-340-25-1; it may be capitalized only during construction or as part of a qualifying phase-in plan (980-340-25-5 through 25-6).
- A regulator's exclusion of a cost from allowable costs reduces the carrying amount of the related regulatory asset by the excluded amount, other assets being tested under the Impairment or Disposal of Long-Lived Assets Subsections of Subtopic 360-10 (980-340-35-1); later allowance of previously excluded costs creates a new asset (980-340-35-2), and an indirect disallowance embedded in a phase-in plan is accounted for under Section 980-360-35 (980-340-35-4).
- Cumulative amounts capitalized under phase-in plans are reported as a separate balance sheet asset, and the net amount capitalized or recovered each period is reported as a separate item of other income or expense, not as a reduction of other expenses (980-340-45-1).
- Disclosure is required of the terms of all phase-in plans (including net amounts deferred for rate-making purposes under nonqualifying plans), of major costs recovered without a return on investment during the recovery period, and of any allowance for earnings on shareholders' investment capitalized for rate-making but not for financial reporting (980-340-50-1 through 50-3).
For students. Regulated utilities are the classic exception to the rule that costs are expensed when incurred — a regulator's rate action can itself create an asset. The most common misunderstanding is assuming any regulator-ordered deferral can be capitalized: deferrals under phase-in plans for post-1988 plants are never capitalized for GAAP (only disclosed), and an allowance for earnings on shareholders' investment is never capitalized outside construction or a qualifying phase-in plan.
Machine-generated study aid for ASC 340-980. Check the source paragraphs below.
340-980-00Status
Source downloaded: .Record version 207bbb854147. Effective date must be checked in the source.
| Paragraph | Action | Accounting Standards Update | Date |
| 980-340-25-4 | Amended | Accounting Standards Update No. 2016-02 | 02/25/2016 |
| Amended | Accounting Standards Update No. 2016-02 | 02/25/2016 | |
| Amended | Accounting Standards Update No. 2016-02 | 02/25/2016 |
340-980-05Overview and Background
Source downloaded: .Record version 6501674c8ff8. Effective date must be checked in the source.
Phase-In Plans
340-980-15Scope and Scope Exceptions
Source downloaded: .Record version af231b867dee. Effective date must be checked in the source.
Overall Guidance
340-980-25Recognition
Source downloaded: .Record version 177f82a3f184. Effective date must be checked in the source.
Effects of Regulation
- a It is probable (as defined in Topic 450) that future revenue in an amount at least equal to the capitalized cost will result from inclusion of that cost in allowable costs for rate-making purposes.
- b Based on available evidence, the future revenue will be provided to permit recovery of the previously incurred cost rather than to provide for expected levels of similar future costs. If the revenue will be provided through an automatic rate-adjustment clause, this criterion requires that the regulator's intent clearly be to permit recovery of the previously incurred cost.
- a The allowable costs in question are deferred pursuant to a formal plan that has been agreed to by the regulator.
- b The plan specifies the timing of recovery of all allowable costs that will be deferred under the plan.
- c All allowable costs deferred under the plan are scheduled for recovery within 10 years of the date when deferrals begin.
- d The percentage increase in rates scheduled under the plan for each future year is no greater than the percentage increase in rates scheduled under the plan for each immediately preceding year. That is, the scheduled percentage increase in Year 2 is no greater than the percentage increase granted in Year 1, the scheduled percentage increase in Year 3 is no greater than the scheduled percentage increase in Year 2, and so forth.
- aExample 1 (see paragraph 980-340-55-9) illustrates a sale with leaseback as a finance lease.
- bExample 2 (see paragraph 980-340-55-12) illustrates a sale with leaseback as an operating lease.
- cExample 3 (see paragraph 980-340-55-15) illustrates a sale with leaseback with profit recognition accelerated.
- dExample 4 (see paragraph 980-340-55-18) illustrates the modified depreciation method.
- eExample 5 (see paragraph 980-340-55-21) illustrates deferred costs before a rate order is issued.
- fExample 7 (see paragraph 980-340-55-39) illustrates a phase-in plan for two plants completed at different times that share common facilities.
340-980-35Subsequent Measurement
Source downloaded: .Record version 6aa0a8af4401. Effective date must be checked in the source.
Effect of Rate Action on Asset Value
Phase-In Plans
340-980-40Derecognition
Source downloaded: .Record version 8899c196b6a6. Effective date must be checked in the source.
340-980-45Other Presentation Matters
Source downloaded: .Record version 4df2656036b0. Effective date must be checked in the source.
Phase-In Plans
340-980-50Disclosure
Source downloaded: .Record version dcf07da05fc4. Effective date must be checked in the source.
Recovery of Cost Without Return on Investment
Phase-In Plans
Allowance for Earnings on Shareholders' Investment Capitalized for Rate-Making Purposes
340-980-55Implementation Guidance and Illustrations
Source downloaded: .Record version 5f21fee432f3. Effective date must be checked in the source.
Implementation Guidance
Illustrations
- a It defers depreciation expense compared with the depreciation methods that are acceptable under GAAP applicable to entities in general (as indicated in paragraph 360-10-35-10, annuity methods of depreciation are not acceptable under GAAP applicable to entities in general).
- b It defers depreciation expense compared with the method of depreciation used by Utility E's regulator for Utility E's electric generating plants prior to 1982.
- aUtility F has deferred costs before a rate order is issued (Case A).
- bUtility F has deferred costs before a rate order is issued and has subsequent interaction with a disallowance (Case B).
- cUtility G has deferred costs before a rate order is issued and has interaction with a subsequent phase-in plan (Case C).
-
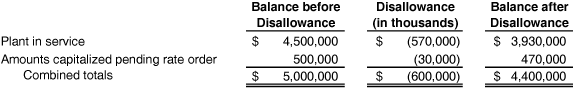 Balance before Disallowance Disallowance (in thousands) Balance after Disallowance Plant in service " $4,500,000 " " $(570,000)" " $3,930,000 " Amounts capitalized pending rate order " 500,000 " " (30,000)" " 470,000 " Combined totals " $5,000,000 " " $(600,000)" " $4,400,000 "
- a Assuming that $300,000,000 of the $500,000,000 capitalized for rate-making purposes during the 6-month period was also capitalized for financial reporting (the $200,000,000 allowance for earnings on shareholders' investment would not be capitalized), the total loss recognized by Utility F for financial reporting should be the amount that reduces the combined total of plant in service and amounts capitalized pending rate order ($4,800,000,000) to the combined total that will be honored for rate-making purposes ($4,400,000,000). The recognizable loss is $400,000,000.
- b Utility F should allocate to plant in service the lesser of the amount of the disallowance that was allocated to plant in service by the regulator ($570,000,000) or the total disallowance recognized for financial reporting ($400,000,000), or $400,000,000.
- c Utility F should allocate the rest of the disallowance recognized for financial reporting, if any, to amounts capitalized pending rate order. In this case, no amount is allocated to that asset.
-
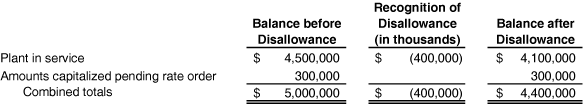 Balance before Disallowance Recognition of Disallowance (in thousands) Balance after Disallowance Plant in service " $4,500,000 " " $(400,000)" " $4,100,000 " Amounts capitalized pending rate order " 300,000 " " 300,000 " Combined totals " $5,000,000 " " $(400,000)" " $4,400,000 "
- a 19X1—A portion of the return (interest and an allowance for earnings on shareholders' investment) on unrecovered investment is deferred by excluding 25 percent of the cost of the plant from the rate base.
- b 19X2—All of the remaining cost of the plant is to be included in the rate base with no recovery of previously deferred amounts.
- c 19X3—All of the remaining cost of the plant is to be included in the rate base. Also, additional revenue is to be provided equal to the return on unrecovered investment excluded from rates in Year 1.
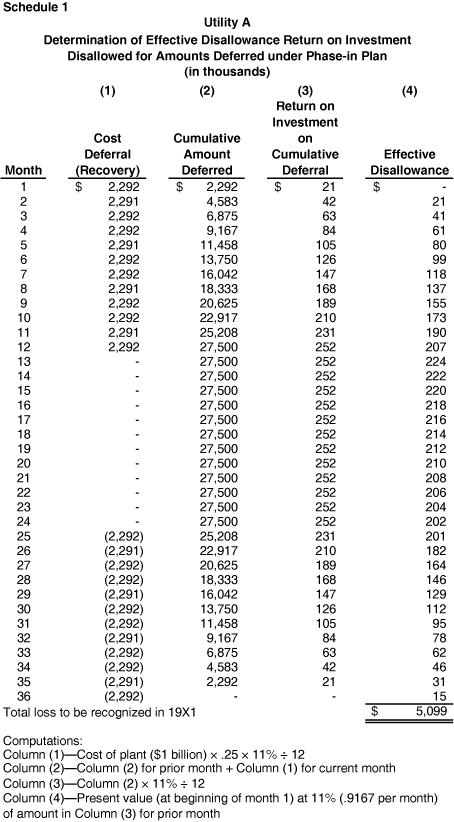 Schedule 1 Utility A Determination of Effective Disallowance Return on Investment Disallowed for Amounts Deferred under Phase-in Plan (in thousands) (1) (2) (3) (4) Month Cost Deferral (Recovery) Cumulative Amount Deferred Return on Investment on Cumulative Deferral Effective Disallowance 1 " $2,292 " " $2,292 " $21 $- 2 " 2,291 " " 4,583 " 42 21 3 " 2,292 " " 6,875 " 63 41 4 " 2,292 " " 9,167 " 84 61 5 " 2,291 " " 11,458 " 105 80 6 " 2,292 " " 13,750 " 126 99 7 " 2,292 " " 16,042 " 147 118 8 " 2,291 " " 18,333 " 168 137 9 " 2,292 " " 20,625 " 189 155 10 " 2,292 " " 22,917 " 210 173 11 " 2,291 " " 25,208 " 231 190 12 " 2,292 " " 27,500 " 252 207 13 - " 27,500 " 252 224 14 - " 27,500 " 252 222 15 - " 27,500 " 252 220 16 - " 27,500 " 252 218 17 - " 27,500 " 252 216 18 - " 27,500 " 252 214 19 - " 27,500 " 252 212 20 - " 27,500 " 252 210 21 - " 27,500 " 252 208 22 - " 27,500 " 252 206 23 - " 27,500 " 252 204 24 - " 27,500 " 252 202 25 " (2,292)" " 25,208 " 231 201 26 " (2,291)" " 22,917 " 210 182 27 " (2,292)" " 20,625 " 189 164 28 " (2,292)" " 18,333 " 168 146 29 " (2,291)" " 16,042 " 147 129 30 " (2,292)" " 13,750 " 126 112 31 " (2,292)" " 11,458 " 105 95 32 " (2,291)" " 9,167 " 84 78 33 " (2,292)" " 6,875 " 63 62 34 " (2,292)" " 4,583 " 42 46 35 " (2,291)" " 2,292 " 21 31 36 " (2,292)" - - 15 Total loss to be recognized in 19X1 " $5,099 " Computations: Column (1)—Cost of plant ($1 billion) × .25 × 11% ÷ 12 Column (2)—Column (2) for prior month + Column (1) for current month Column (3)—Column (2) × 11% ÷ 12 Column (4)—Present value (at beginning of month 1) at 11% (.9167 per month) of amount in Column (3) for prior month
- a Is effective after the in-service date of that plant
- b Addresses the costs of that plant.
Related subtopics
- 980-20 Discontinuation of Rate-Regulated AccountingRegulated Operations
- 980-10 OverallRegulated Operations
- 360-980 Regulated OperationsProperty, Plant, and Equipment
- 715-980 Regulated OperationsCompensation—Retirement Benefits
- 740-980 Regulated OperationsIncome Taxes
- 835-20 Capitalization of InterestInterest