ASC 715-958
Not-for-Profit Entities
715 Compensation—Retirement Benefits
Source downloaded: .Record version a8cd844beb77. Effective date must be checked in the source.
This Subtopic adapts Topic 715 (pension and other postretirement benefits) for not-for-profit entities, which do not report other comprehensive income. Everywhere Topic 715 would require net gains or losses, prior service costs or credits, and transition assets or obligations to run through OCI/AOCI, an NFP instead recognizes those amounts as changes in net assets without donor restrictions that have not yet been reclassified into net periodic benefit cost. Those amounts, and the non-service components of net periodic benefit cost, are presented in separate line items outside any intermediate measure of operations (or performance indicator for business-oriented health care NFPs).
Key points (7)
- An NFP applying the recognition provisions of paragraph 715-30-25-4 substitutes 'changes in net assets without donor restrictions arising from a defined benefit plan (or postretirement benefit plan) not yet reclassified as components of net periodic benefit cost' for AOCI references (715-958-25-1).
- The same substitution applies to gains and losses, prior service costs or credits, and transition assets or obligations under Sections 715-30-35 and 715-60-35, and to paragraphs 715-30-35-65, 715-60-35-127, and 715-30-35-25(a) (715-958-35-1 through 35-5).
- Gains and losses not immediately recognized in net periodic pension cost under 715-30-35-21 are recognized in accordance with 958-715-45-1 (715-958-35-6); NFPs not reporting OCI apply 715-30-35-79 through 35-96 in an analogous manner (715-958-35-7).
- The net gain or loss, prior service costs or credits, and transition asset or obligation that would go to OCI are reported as a separate line item or items, apart from expenses, outside an intermediate measure of operations or performance indicator (954-220-45-5), within changes in net assets without donor restrictions (715-958-45-1).
- Amounts previously so recognized are reclassified to net periodic pension cost under 715-30-35-3 through 35-28 or to net periodic postretirement benefit cost under 715-60-35-7 through 35-40, with the contra adjustment reported in the same line item (715-958-45-2).
- Service cost is reported in the same line item(s) as other employee compensation costs (unless capitalized), while the other components defined in 715-30-35-4 and 715-60-35-9 are reported separately and outside any intermediate measure of operations; both are reported by functional expense classification per 958-720-45-2 and 958-720-45-15 (715-958-45-3).
- Disclosures under Section 715-20-50 are made with substitutions: 'changes in net assets without donor restrictions' for OCI/AOCI and results of operations, and 'statement of activities' for 'statement of income' (715-958-50-1).
For students. The whole point of this Subtopic is translation: NFPs have no OCI, so every Topic 715 reference to OCI/AOCI becomes a change in (and cumulative amount within) net assets without donor restrictions. Students commonly confuse the two required separate line items — one for the non-service components of net periodic benefit cost, and a different one for gains/losses, prior service cost, and transition amounts not yet reclassified into that cost.
Machine-generated study aid for ASC 715-958. Check the source paragraphs below.
715-958-00Status
Source downloaded: .Record version aff7a60a0008. Effective date must be checked in the source.
715-958-05Overview and Background
Source downloaded: .Record version 157331563ea9. Effective date must be checked in the source.
715-958-15Scope and Scope Exceptions
Source downloaded: .Record version 16306cdff951. Effective date must be checked in the source.
Overall Guidance
Transactions
715-958-25Recognition
Source downloaded: .Record version 1f0acd99f2c4. Effective date must be checked in the source.
- aParagraph 715-30-25-4.
715-958-35Subsequent Measurement
Source downloaded: .Record version 19eaf5eb9e5d. Effective date must be checked in the source.
- aParagraph 715-30-35-65
- bParagraph 715-60-35-127.
715-958-45Other Presentation Matters
Source downloaded: .Record version 4fbe160c2eaa. Effective date must be checked in the source.
- a To net periodic pension cost, pursuant to the recognition and amortization provisions of paragraphs
- b To net periodic postretirement benefit cost, pursuant to the recognition and amortization provisions of paragraphs .
- a The service cost component of net periodic pension cost and net periodic postretirement benefit cost in the same line item(s) as other compensation costs arising from services rendered by the pertinent employees during the period (except for the amount being capitalized, if appropriate, in connection with production or construction of an asset)
- b The other components as defined in paragraphs 715-30-35-4 and 715-60-35-9 separately from the service cost component and outside an intermediate measure of operations, if one is presented, within changes in net assets without donor restrictions. If a separate line item or items are used to present the other components, that line item or items shall be appropriately described and different from the separate line item or items used to present the net gain or loss, the prior service costs or credits, and the transition asset or obligation that would be recognized in other comprehensive income in accordance with Sections 715-30-35 and 715-60-35.
715-958-50Disclosure
Source downloaded: .Record version 5f5cbce102e6. Effective date must be checked in the source.
- a The references to the net gain or loss, net prior service cost or credit, and net transition asset or obligation recognized in other comprehensive income in paragraphs 715-20-50-1(i) and 715-20-50-5(h) shall instead be to such amounts recognized as changes in net assets without donor restrictions arising from a defined benefit plan but not yet included in net periodic benefit cost.
- b The references to reclassification adjustments of other comprehensive income in paragraphs 715-20-50-1(i) and 715-20-50-5(h) shall instead be to reclassifications to net periodic benefit cost of amounts previously recognized as changes in net assets without donor restrictions arising from a defined benefit plan but not included in net periodic benefit cost when they arose.
- c The references to the net gain or loss, net prior service cost or credit, and net transition asset or obligation recognized in accumulated other comprehensive income in the following paragraphs shall instead be to such amounts that have been recognized as changes in net assets without donor restrictions arising from a defined benefit plan but not yet reclassified as components of net periodic benefit cost:
- 1 Paragraph 715-20-50-5(i)
- 2 Paragraph 715-20-50-1(j)
- 3
- 4
- 1
- d The references to results of operations (including items of other comprehensive income) in paragraphs 715-20-50-1 and 715-20-50-5 shall instead be to changes in net assets without donor restrictions and the references to a statement of income in those paragraphs shall instead be to a statement of activities.
715-958-55Implementation Guidance and Illustrations
Source downloaded: .Record version 51b921576256. Effective date must be checked in the source.
Implementation Guidance
Illustrations
- aRecognizes the additional net loss as a change in net assets without donor restrictions and a change in the liability that reflects the underfunded status of the plan
- bRecognizes the amortization of the transition obligation as a component of net periodic pension cost
- cRecognizes the amortization of prior service cost as a component of net periodic pension cost
- dRecognizes net periodic pension cost within the appropriate functional expense categories for 20X8, with the service cost component reported as part of the intermediate measure of operations (for example, increase in net assets from operating activities) and the other components reported in a separate line item, outside the intermediate measure of operations presented by NFP A, within changes in net assets without donor restrictions.
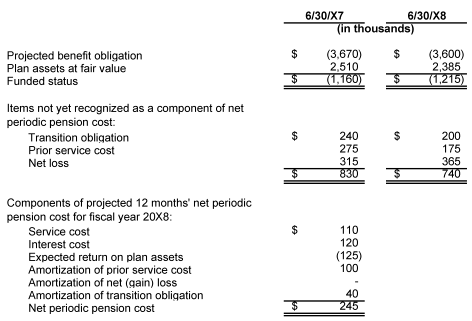 6/30/X7 6/30/X8 (in thousands) Projected benefit obligation " $(3,670)" " $(3,600)" Plan assets at fair value " 2,510 " " 2,385 " Funded status " $(1,160)" " $(1,215)" Items not yet recognized as a component of net periodic pension cost: Transition obligation $240 $200 Prior service cost 275 175 Net loss 315 365 $830 $740 Components of projected 12 months' net periodic pension cost for fiscal year 20X8: Service cost $110 Interest cost 120 Expected return on plan assets (125) Amortization of prior service cost 100 Amortization of net (gain) loss - Amortization of transition obligation 40 Net periodic pension cost $245
- aRecognize the additional loss in net assets without donor restrictions.
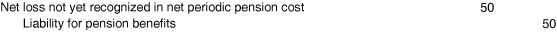 Net loss not yet recognized in net periodic pension cost 50 Liability for pension benefits 50
- bRecognize the amortization of the transition obligation in net periodic pension cost.
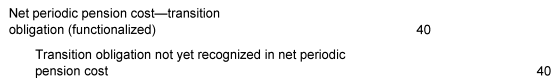 "Net periodic pension cost—transition obligation (functionalized)" 40 Transition obligation not yet recognized in net periodic pension cost 40
- cRecognize the amortization of prior service cost in net periodic pension cost.
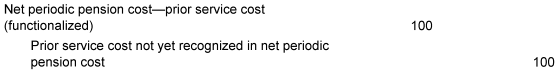 "Net periodic pension cost—prior service cost (functionalized)" 100 "Prior service cost not yet recognized in net periodic pension cost" 100
- dRecognize service cost separately and recognize the interest cost and the expected return on plan assets together in net periodic pension cost.
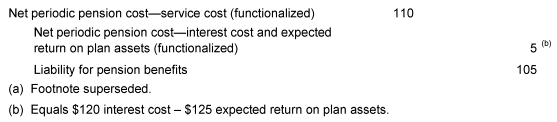 Net periodic pension cost—service cost (functionalized) 110 Net periodic pension cost—interest cost and expected return on plan assets (functionalized) 5 (b) Liability for pension benefits 105 "(a) Footnote superseded. " (b) Equals $120 interest cost - $125 expected return on plan assets.
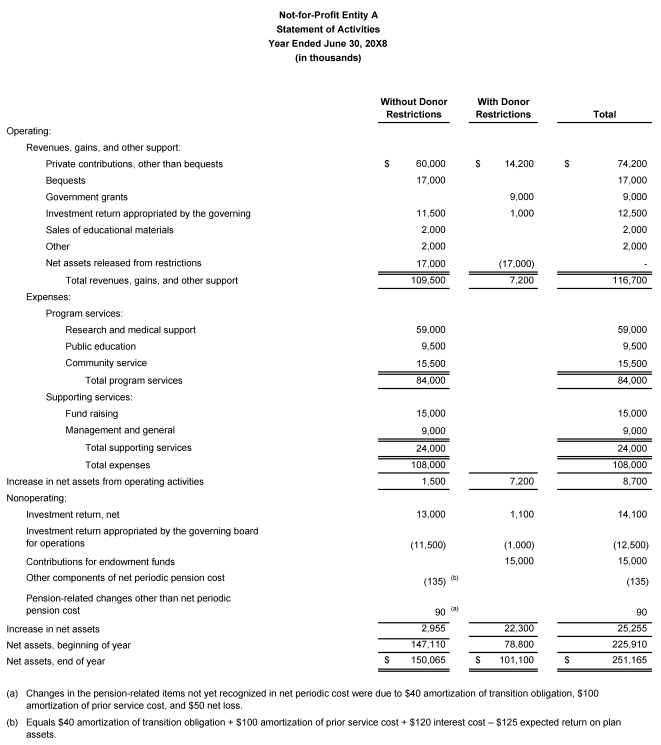 Not-for-Profit Entity A Statement of Activities "Year Ended June 30, 20X8" (in thousands) Without Donor Restrictions With Donor Restrictions Total Operating: "Revenues, gains, and other support:" "Private contributions, other than bequests" " $60,000 " " $14,200 " " $74,200 " Bequests " 17,000 " " 17,000 " Government grants " 9,000 " " 9,000 " "Investment return appropriated by the governing board for operations" " 11,500 " " 1,000 " " 12,500 " Sales of educational materials " 2,000 " " 2,000 " Other " 2,000 " " 2,000 " Net assets released from restrictions " 17,000 " " (17,000)" - "Total revenues, gains, and other support" " 109,500 " " 7,200 " " 116,700 " Expenses: Program services: Research and medical support " 59,000 " " 59,000 " Public education " 9,500 " " 9,500 " Community service " 15,500 " " 15,500 " Total program services " 84,000 " " 84,000 " Supporting services: Fund raising " 15,000 " " 15,000 " Management and general " 9,000 " " 9,000 " Total supporting services " 24,000 " " 24,000 " Total expenses " 108,000 " " 108,000 " Increase in net assets from operating activities " 1,500 " " 7,200 " " 8,700 " Nonoperating: "Investment return, net" " 13,000 " " 1,100 " " 14,100 " "Investment return appropriated by the governing board for operations" " (11,500)" " (1,000)" " (12,500)" Contributions for endowment funds " 15,000 " " 15,000 " Other components of net periodic pension cost (135) (b) (135) "Pension-related changes other than net periodic pension cost" 90 (a) 90 Increase in net assets " 2,955 " " 22,300 " " 25,255 " "Net assets, beginning of year" " 147,110 " " 78,800 " " 225,910 " "Net assets, end of year" " $150,065 " " $101,100 " " $251,165 " "(a) Changes in the pension-related items not yet recognized in net periodic cost were due to $40 amortization of transition obligation, $100 amortization of prior service cost, and $50 net loss." "(b) Equals $40 amortization of transition obligation + $100 amortization of prior service cost + $120 interest cost - $125 expected return on plan assets."
715-958-65Transition and Open Effective Date Information
Source downloaded: .Record version cb28a9a29d23. Effective date must be checked in the source.
Related subtopics
- 220-958 Not-for-Profit EntitiesIncome Statement—Reporting Comprehensive Income
- 715-980 Regulated OperationsCompensation—Retirement Benefits
- 205-958 Not-for-Profit EntitiesPresentation of Financial Statements
- 715-30 Defined Benefit Plans—PensionCompensation—Retirement Benefits
- 715-60 Defined Benefit Plans—Other PostretirementCompensation—Retirement Benefits
- 325-958 Not-for-Profit EntitiesInvestments—Other