ASC 205-958
Not-for-Profit Entities
205 Presentation of Financial Statements
Source downloaded: .Record version 46bae6ca391a. Effective date must be checked in the source.
ASC 958-205 governs the presentation of a not-for-profit entity's general-purpose financial statements. A complete set consists of a statement of financial position, a statement of activities, a statement of cash flows, and notes (958-205-45-4), with net assets classified in two minimum classes—net assets with donor restrictions and net assets without donor restrictions (958-205-45-2(b)). It also prescribes when donor restrictions expire, how endowment funds (including those under UPMIFA) are classified, and the required endowment and underwater endowment disclosures.
Key points (7)
- A complete set of NFP financial statements includes a statement of financial position at period end, a statement of activities and statement of cash flows for the period, plus accompanying notes (958-205-45-4).
- NFPs must classify and report net assets in two groups—with donor restrictions and without donor restrictions—based on the existence or absence of donor-imposed restrictions; the two classes are a minimum scheme that may be further disaggregated (958-205-45-2(b); 958-205-05-6B).
- All NFPs must report information about all expenses in one location (face of the statement of activities, a note schedule, or a separate statement) in an analysis showing the relationship of functional to natural classifications (958-205-45-6; 958-720-45-15).
- Expiration of a donor-imposed restriction is recognized in the period the restriction expires—when the stipulated time elapses or the stipulated purpose is fulfilled—and where multiple temporary restrictions exist, when the last one expires (958-205-45-9); restrictions on long-lived assets expire when the assets are placed in service (958-205-45-12).
- Under an enacted version of UPMIFA, the original gift, subsequent gifts, and investment returns of a donor-restricted endowment fund are net assets with donor restrictions until appropriated for expenditure by the governing board, at which point the appropriated amount is reclassified if time and purpose restrictions are met (958-205-45-13D through 45-13F).
- Accumulated losses of an underwater endowment fund stay with that fund in net assets with donor restrictions, and the NFP must disclose in the aggregate the fair value, the original gift/required level, and the deficiency (958-205-45-13H; 958-205-50-2).
- Required endowment disclosures include the board's interpretation of relevant law, spending and investment policies, endowment composition by net asset class and fund type, and a beginning-to-ending reconciliation of endowment balances (958-205-50-1A through 50-1B); reporting by fund groups is not required but is not precluded (958-205-45-3).
For students. This is the backbone of NFP reporting and a heavy CPA exam topic: know the three required statements, the two net asset classes, and the functional/natural expense analysis. The classic misunderstanding is endowment classification—under UPMIFA the entire donor-restricted endowment (including accumulated investment return and underwater deficits) stays in net assets with donor restrictions until the board appropriates it, while a board-designated (quasi-) endowment sits in net assets without donor restrictions.
Machine-generated study aid for ASC 205-958. Check the source paragraphs below.
205-958-00Status
Source downloaded: .Record version d1630ea27cb4. Effective date must be checked in the source.
205-958-05Overview and Background
Source downloaded: .Record version 590318c65eb4. Effective date must be checked in the source.
- aThe objectives of financial reporting by NFPs
- bA complete set of financial statements
- cStatement of functional expenses
- dComparative financial statements
- eExpiration of restrictions
- fReporting endowment funds
- gDisclosures of a general nature that do not belong with other Subtopics.
Purpose of Financial Statements
- aThe services an NFP provides and its ability to continue to provide those services
- bHow managers discharge their stewardship responsibilities and other aspects of their performance.
- aThe amount and nature of an NFP's assets, liabilities, and net assets
- bThe effects of transactions and other events and circumstances that change the amount and nature of net assets
- cThe amount and kinds of inflows and outflows of economic resources during a period and the relation between the inflows and outflows
- dHow an NFP obtains and spends cash, its borrowing and repayment of borrowing, and other factors that may affect its liquidity
- eThe service efforts of an NFP.
A Complete Set of Financial Statements
Reporting Endowment Funds
205-958-10Objectives
Source downloaded: .Record version 03d9322acc9f. Effective date must be checked in the source.
- aRequire information that meets the objectives of financial reporting for NFPs
- bDefine what constitutes a complete set of general-purpose financial statements for those entities
- cRequire methods of reporting that information that are all of the following:
- 1Comprehensive
- 2Understandable
- 3Useful for decisions by present and potential resource providers
- 4Consistent with the conceptual framework.
- 1
205-958-15Scope and Scope Exceptions
Source downloaded: .Record version 1456a8ea5f66. Effective date must be checked in the source.
Overall Guidance
205-958-45Other Presentation Matters
Source downloaded: .Record version e301c9eb338a. Effective date must be checked in the source.
- aReport assets and liabilities in reasonably homogeneous groups and sequence or classify them in ways that provide relevant information about their interrelationships, liquidity, and financial flexibility.
- bClassify and report net assets in two groups—net assets with donor restrictions and net assets without donor restrictions—based on the existence or absence of donor-imposed restrictions. Information about restrictions imposed by donors on the use of contributed assets, including their potential effects on specific assets and on liabilities or classes of net assets, shall be disclosed in accordance with paragraph 958-210-50-3, because it is helpful in assessing the financial flexibility of an NFP.
- cAggregate items of revenues, expenses, gains, and losses into reasonably homogeneous groups and classify and report them as increases or decreases in net assets with donor restrictions or net assets without donor restrictions.
- dClassify and report cash receipts and cash payments as resulting from investing, financing, or operating activities.
Complete Set of Financial Statements
Reporting of Expenses by Nature and Function
Comparative Financial Statements
Expirations of Donor-Imposed Restrictions
Reporting Endowment Funds
- aNet assets with donor restrictions. For example, a donor-restricted endowment would be classified as net assets with donor restrictions.
- bNet assets without donor restrictions. For example, a board-designated endowment fund, which generally results from an internal designation of net assets without donor restrictions, would thus generally be classified as net assets without donor restrictions.
Contributed Nonfinancial Assets
205-958-50Disclosure
Source downloaded: .Record version d36e2cd3ca5c. Effective date must be checked in the source.
Nature of the Not-for-Profit Entity's Activities
Reporting Endowment Funds
- a Net asset classification (for example, net assets with donor restrictions or net assets without donor restrictions)
- b Net asset composition (for example, board-designated endowment funds or donor-restricted endowment funds)
- c Changes in net asset composition
- d Spending policies
- e Related investment policies.
- a A description of the governing board's interpretation of the law or laws that underlie the NFP's net asset classification of donor-restricted endowment funds, including its interpretation of the ability to spend from underwater endowment funds.
- b A description of the NFP's policy or policies for the appropriation of endowment assets for expenditure (its endowment spending policy or policies), including its policy, and any actions taken during the period, concerning appropriation from underwater endowment funds.
- c A description of the NFP's endowment investment policies, including all of the following:
- 1 Return objectives and risk parameters
- 2 How return objectives relate to the NFP's endowment spending policy or policies
- 3 The strategies employed for achieving return objectives.
- 1
- d The composition of the NFP's endowment by net asset class at the end of the period, in total and by type of endowment fund, showing donor-restricted endowment funds separately from board-designated endowment funds.
- e A reconciliation of the beginning and ending balance of the NFP's endowment, in total and by net asset class, including, at a minimum, all of the following line items that apply:
- 1 Investment return, net
- 2
- 3 Amounts appropriated for expenditure
- 4
- 5 Other changes.
- 1
- a The fair value of the underwater endowment funds
- b The original endowment gift amount or level required to be maintained by donor stipulations or by law that extends donor restrictions
- c The amount of the deficiencies of the underwater endowment funds ((a) less (b)).
Ratio of Fundraising Expenses to Amounts Raised
Comparative Financial Statements
205-958-55Implementation Guidance and Illustrations
Source downloaded: .Record version 5b6eccd7805a. Effective date must be checked in the source.
Implementation Guidance
Illustrations
- aNot-for-Profit Entity A invested cash in excess of daily requirements in short-term investment instruments. Interest earned on these investments totaled $850, which is included in the net investment return on the statement of activities. The governing board previously designated a portion of net assets without donor restrictions for long-term investment (quasi-endowment). Those assets earned $5,800, comprising $2,000 of dividends, interest, and rents and $3,800 of realized and unrealized net gains.
- bNot-for-Profit Entity A received contributions without donor restrictions of the following: cash, $5,120; recognizable contributed services, $300; other consumable assets, $1,410; equipment, $140; and unconditional promises to give to support activities of 20X1, $1,020.
- cEquipment with an original cost of $660 and accumulated depreciation of $330 was destroyed in a fire. Insurance proceeds of $250 were received. The equipment was originally purchased with assets without associated donor restrictions.
- dAll conditions of a prior year's grant of $650 were substantially met. The grant proceeds were originally recorded as a refundable advance.
- eNot-for-Profit Entity A made a payment of $425 on its prior year unconditional grant to an unrelated agency.
- fNot-for-Profit Entity A repaid $1,140 of its notes payable. Interest of $32 was incurred and paid on these notes.
- gNot-for-Profit Entity A repaid $1,000 of its long-term debt. Interest of $350 was incurred and paid on the debt.
- hDepreciation amounted to $3,200.
- hhNot-for-Profit Entity A sold equipment that was fully depreciated for $200.
- hhhNot-for-Profit Entity A's financial assets consisted of cash and cash equivalents, short-term investments, accounts and interest receivable, contributions receivable, assets restricted to investment in land, buildings, and equipment, and long-term investments. The $193,490 of donor-restricted net assets included the net assets resulting from contributions receivable of $1,000, which were without purpose restrictions and were due within one year. The remaining amounts of contributions receivable were either purpose-restricted or due in greater than one year. In addition, amounts made unavailable by the governing board included $36,600 of board-designated long-term investments. The $1,300 liquidity reserve, created in a prior year when the governing board designated net assets without donor restrictions, was included as a reconciling item in Not-for-Profit Entity A's note on liquidity risk and the availability of resources because the intention of the designation was to support unanticipated liquidity needs and not general expenditures.
- iNot-for-Profit Entity A received contributions with donor restrictions as follows.
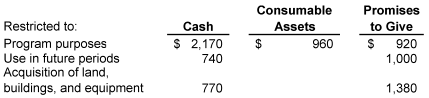 Restricted to: Cash Consumable Assets Promises to Give Program purposes " $2,170 " $960 $920 Use in future periods 740 1000 "Acquisition of land, buildings, and equipment" 770 " 1,380 "
- iiThe composition of assets restricted to investment in land, buildings, and equipment as of June 30, 20X1, and 20X0, is shown below. The change in restricted cash below represents a purchase of investments restricted to investment in land, buildings, and equipment.
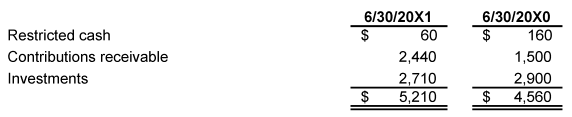 6/30/20X1 6/30/20X0 Restricted cash $60 $160 Contributions receivable " 2,440 " " 1,500 " Investments " 2,710 " " 2,900 " " $5,210 " " $4,560 "
- jIn addition, a donor transferred cash of $200 to set up an annuity trust having a related annuity obligation with a present value of $100. Upon the death of the beneficiary, the remaining interest will be used for a donor-restricted purpose.
- kIn addition, a donor contributed cash of $70 to create a term endowment. At the end of 15 years the endowment assets can be used to support Not-for-Profit Entity A's operations.
- lNot-for-Profit Entity A made payments of $145 to beneficiaries of annuity trust agreements.
- mA donor contributed a paid-up life insurance policy with a cash surrender value of $80. Upon the death of the insured, the death benefit must be used to create a donor-restricted endowment fund. There was no change in the cash surrender value between the date of the gift and the end of the fiscal year.
- nA donor contributed cash of $200 to create a donor-restricted endowment fund. The income is restricted to use for Program A activities.
- oNot-for-Profit Entity A collected promises to give of $3,055: $980 of amounts for general purposes, $610 of amounts restricted to future periods, $1,025 of amounts restricted to program purposes, and $440 of amounts for acquisition of land, buildings, and equipment.
- pNot-for-Profit Entity A utilized all of the $1,410 consumable assets contributed for general purposes, and $350 of the $960 consumable assets contributed for program purposes.
- qA trust annuitant died and the $400 remainder interest became available for the general use of Not-for-Profit Entity A. Management decided to invest the remainder interest in short-term investments. The actuarial gain on death of the annuitant is included in the actuarial loss on annuity obligations.
- rNot-for-Profit Entity A acquired and placed in service $1,500 of equipment for Program A; net assets with donor restrictions were available at the time the equipment was purchased.
- sNet investment return of $18,000 was earned from the pooled donor-restricted endowment. This comprised $12,000 of realized and unrealized net gains and $6,000 of interest and dividends. Additionally, $300 of interest and dividends was earned from separately invested donor-restricted endowment funds and annuity trust assets, which are required to be reinvested. The original endowment gift amount as adjusted to the level required by donor stipulations or by law that extends donor restrictions was $122,337.
- tNot-for-Profit Entity A reinvested the yield of $120 on a donor-restricted endowment fund that requires income to be added to the original gift until the fund's value is $2,500.
- uNot-for-Profit Entity A's governing board appropriated for current operations $7,500 of net assets with donor restrictions from the donor-restricted endowment fund. The full amount appropriated was reclassified to net assets without donor restrictions in the current year because the purpose restrictions on $3,000 of the appropriated amount were met in the current year and there were no purpose restrictions on the remaining $4,500.
- vNot-for-Profit Entity A follows an enacted version of UPMIFA.
- wNone of Not-for-Profit Entity A's endowment funds were underwater as of the date of the financial statements.
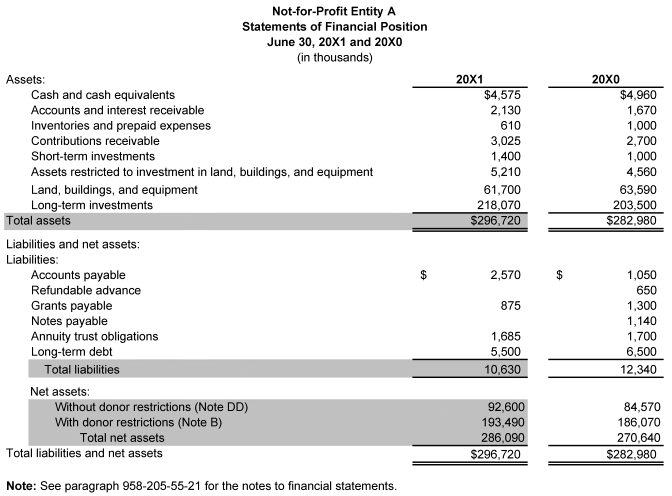 Not-for-Profit Entity A Statements of Financial Position " June 30, 20X1 and 20X0" (in thousands) Assets: 20X1 20X0 Cash and cash equivalents "$4,575 " "$4,960 " Accounts and interest receivable " 2,130 " " 1,670 " Inventories and prepaid expenses 610 " 1,000 " Contributions receivable " 3,025 " " 2,700 " Short-term investments " 1,400 " " 1,000 " "Assets restricted to investment in land, buildings, and equipment" " 5,210 " " 4,560 " "Land, buildings, and equipment" " 61,700 " " 63,590 " Long-term investments " 218,070 " " 203,500 " Total assets "$296,720 " "$282,980 " Liabilities and net assets: Liabilities: Accounts payable " $2,570 " " $1,050 " Refundable advance 650 Grants payable 875 " 1,300 " Notes payable " 1,140 " Annuity trust obligations " 1,685 " " 1,700 " Long-term debt " 5,500 " " 6,500 " Total liabilities " 10,630 " " 12,340 " Net assets: Without donor restrictions (Note DD) "92,600" "84,570" With donor restrictions (Note B) "193,490" "186,070" Total net assets "286,090" "270,640" Total liabilities and net assets "$296,720 " "$282,980 " Note: See paragraph 958-205-55-21 for the notes to financial statements.
- aFormat A reports information in a single column. That format most easily accommodates presentation of multiyear comparative information.
- bFormat B reports the same information in columnar (or multicolumn) format with a column for each class of net assets. Use of a total column is optional as long as the change in total net assets is presented in accordance with paragraph 958-210-45-1. That format makes evident that the effects of expirations on donor restrictions result in reclassification of net assets. It also accommodates presentation of aggregated information about contributions and investment return for the entity as a whole. However, care is needed for labels and headings to ensure that they clearly communicate all columns and subtotals.
- cFormat C reports information in two statements with summary amounts from a statement of revenues, expenses, and other changes in net assets without donor restrictions (Part 1 of 2) and a statement of changes in net assets (Part 2 of 2). Alternative formats for the statement of changes in net assets—a single-column and a multicolumn or columnar—are illustrated. The two-statement format focuses attention first on changes in net assets without donor restrictions. That format may be preferred by membership organizations and other NFPs that view certain transactions and events, including the receipts of donor-restricted revenues and gains from contributions and investment return, as incidental or insignificant to their daily operations.
- aRevenues, expenses, gains and losses, and reclassification of net assets shown last
- bCertain revenues, less directly related expenses, followed by a subtotal, then other revenues, other expenses, gains and losses, and reclassification of net assets
- cExpenses followed by revenues, gains and losses, and the reclassification of net assets.
- aExample 1 in Subtopic 958-220 (see paragraph 958-220-55-5) provides an illustration that shows how items may be sequenced to distinguish between operating and nonoperating activities or to make other distinctions, if desired.
- bExample 2 in Subtopic 958-220 (see paragraph 958-220-55-7) illustrates the display of an appropriately labeled subtotal for change in a class of net assets before the effects of a discontinued operation.
- cExample 3 in Subtopic 958-220 (see paragraph 958-220-55-8) provides three possible methods of displaying fundraising efforts in the revenue section of the statement of activities if an NFP acts as an agent, trustee, or intermediary in raising resources for another.
- dExample 1 in Subtopic 958-320 (see paragraph 958-320-55-4) provides an illustration of an NFP that presents:
- 1Net investment return
- 2Appropriation of funds from the quasi-endowment
- 3Appropriation of funds from a donor-restricted endowment fund in which the purpose restrictions on the appropriated amount have been met during the period.
- 1
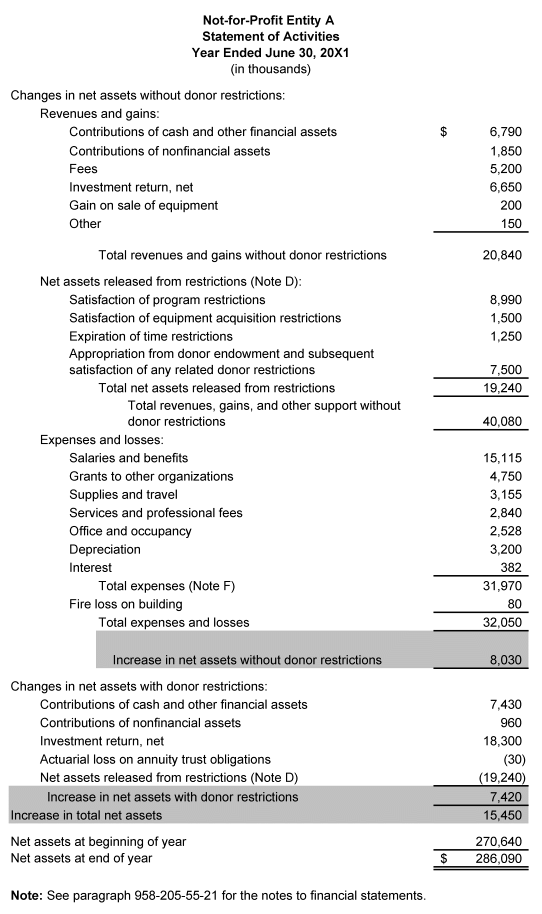 Not-for-Profit Entity A Statement of Activities " Year Ended June 30, 20X1" (in thousands) Changes in net assets without donor restrictions: Revenues and gains: Contributions of cash and other financial assets " $6,790 " Contributions of nonfinancial assets " 1,850 " Fees " 5,200 " "Investment return, net" " 6,650 " Gain on sale of equipment 200 Other 150 Total revenues and gains without donor restrictions " 20,840 " Net assets released from restrictions (Note D): Satisfaction of program restrictions " 8,990 " Satisfaction of equipment acquisition restrictions " 1,500 " Expiration of time restrictions " 1,250 " Appropriation from donor endowment and subsequent satisfaction of any related donor restrictions " 7,500 " Total net assets released from restrictions " 19,240 " "Total revenues, gains, and other support without donor restrictions" " 40,080 " Expenses and losses: Salaries and benefits " 15,115 " Grants to other organizations " 4,750 " Supplies and travel " 3,155 " Services and professional fees " 2,840 " Office and occupancy " 2,528 " Depreciation " 3,200 " Interest 382 Total expenses (Note F) " 31,970 " Fire loss on building 80 Total expenses and losses " 32,050 " Increase in net assets without donor restrictions " 8,030 " Changes in net assets with donor restrictions: Contributions of cash and other financial assets " 7,430 " Contributions of nonfinancial assets 960 "Investment return, net" " 18,300 " Actuarial loss on annuity trust obligations (30) Net assets released from restrictions (Note D) " (19,240)" Increase in net assets with donor restrictions " 7,420 " Increase in total net assets " 15,450 " Net assets at beginning of year " 270,640 " Net assets at end of year " $286,090 " Note: See paragraph 958-205-55-21 for the notes to financial statements.
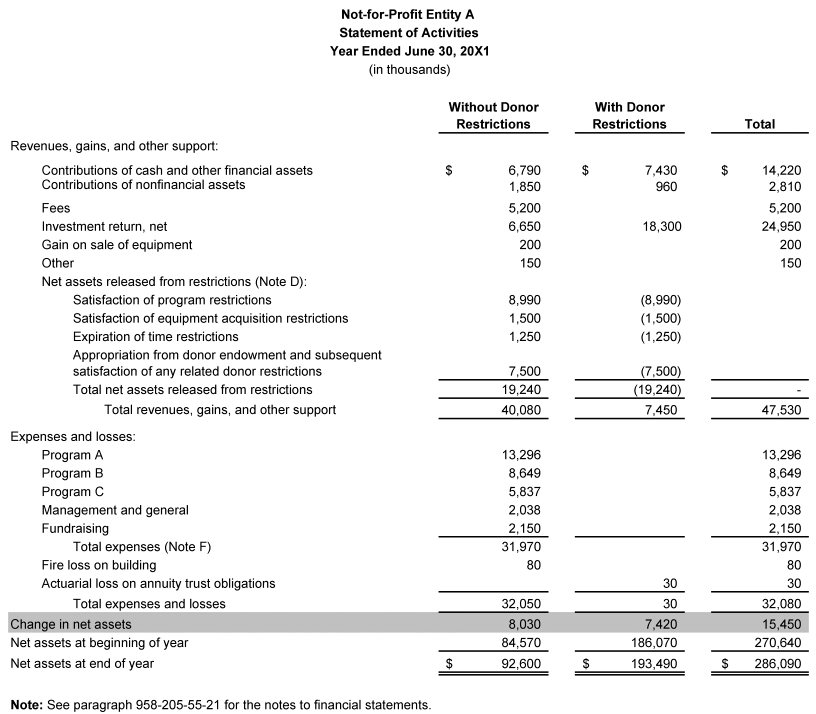 Not-for-Profit Entity A Statement of Activities " Year Ended June 30, 20X1" (in thousands) Without Donor Restrictions With Donor Restrictions Total "Revenues, gains, and other support:" Contributions of cash and other financial assets " $6,790 " " $7,430 " " $14,220 " Contributions of nonfinancial assets " 1,850 " 960 " 2,810 " Fees " 5,200 " " 5,200 " "Investment return, net" " 6,650 " "18,300" " 24,950 " Gain on sale of equipment 200 200 Other 150 150 Net assets released from restrictions (Note D): Satisfaction of program restrictions " 8,990 " " (8,990)" Satisfaction of equipment acquisition restrictions " 1,500 " " (1,500)" Expiration of time restrictions " 1,250 " " (1,250)" Appropriation from donor endowment and subsequent satisfaction of any related donor restrictions " 7,500 " " (7,500)" Total net assets released from restrictions " 19,240 " " (19,240)" - "Total revenues, gains, and other support" " 40,080 " " 7,450 " " 47,530 " Expenses and losses: Program A " 13,296 " " 13,296 " Program B " 8,649 " " 8,649 " Program C " 5,837 " " 5,837 " Management and general " 2,038 " " 2,038 " Fundraising " 2,150 " " 2,150 " Total expenses (Note F) " 31,970 " " 31,970 " Fire loss on building 80 80 Actuarial loss on annuity trust obligations 30 30 Total expenses and losses " 32,050 " 30 " 32,080 " Change in net assets " 8,030 " " 7,420 " " 15,450 " Net assets at beginning of year " 84,570 " " 186,070 " " 270,640 " Net assets at end of year " $92,600 " " $193,490 " " $286,090 " Note: See paragraph 958-205-55-21 for the notes to financial statements.
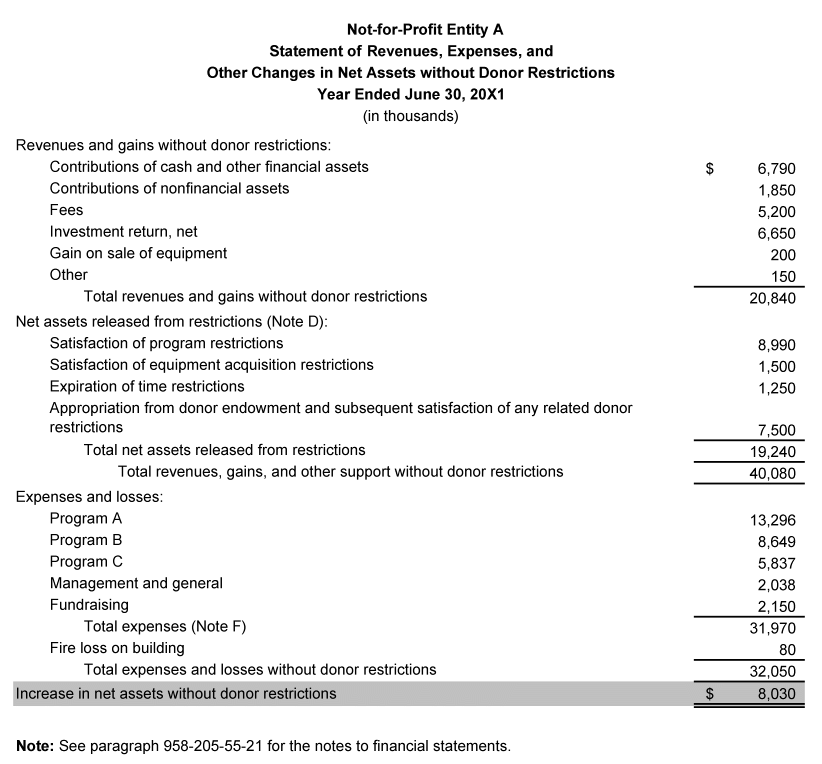 Not-for-Profit Entity A " Statement of Revenues, Expenses, and" Other Changes in Net Assets without Donor Restrictions " Year Ended June 30, 20X1" (in thousands) Revenues and gains without donor restrictions: Contributions of cash and other financial assets " $6,790 " Contributions of nonfinancial assets " 1,850 " Fees " 5,200 " "Investment return, net" " 6,650 " Gain on sale of equipment 200 Other 150 Total revenues and gains without donor restrictions " 20,840 " Net assets released from restrictions (Note D): Satisfaction of program restrictions " 8,990 " Satisfaction of equipment acquisition restrictions " 1,500 " Expiration of time restrictions " 1,250 " Appropriation from donor endowment and subsequent satisfaction of any related donor restrictions " 7,500 " Total net assets released from restrictions " 19,240 " "Total revenues, gains, and other support without donor restrictions" " 40,080 " Expenses and losses: Program A " 13,296 " Program B " 8,649 " Program C " 5,837 " Management and general " 2,038 " Fundraising " 2,150 " Total expenses (Note F) " 31,970 " Fire loss on building 80 Total expenses and losses without donor restrictions " 32,050 " Increase in net assets without donor restrictions " $8,030 " Note: See paragraph 958-205-55-21 for the notes to financial statements.
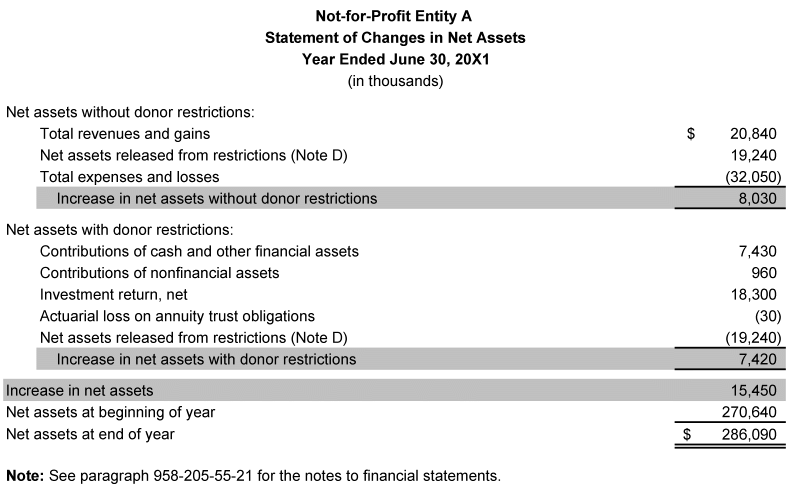 Not-for-Profit Entity A Statement of Changes in Net Assets " Year Ended June 30, 20X1" (in thousands) Net assets without donor restrictions: Total revenues and gains " $20,840 " Net assets released from restrictions (Note D) " 19,240 " Total expenses and losses " (32,050)" Increase in net assets without donor restrictions " 8,030 " Net assets with donor restrictions: Contributions of cash and other financial assets " 7,430 " Contributions of nonfinancial assets 960 "Investment return, net" " 18,300 " Actuarial loss on annuity trust obligations (30) Net assets released from restrictions (Note D) " (19,240)" Increase in net assets with donor restrictions " 7,420 " Increase in net assets " 15,450 " Net assets at beginning of year " 270,640 " Net assets at end of year " $286,090 " Note: See paragraph 958-205-55-21 for the notes to financial statements.
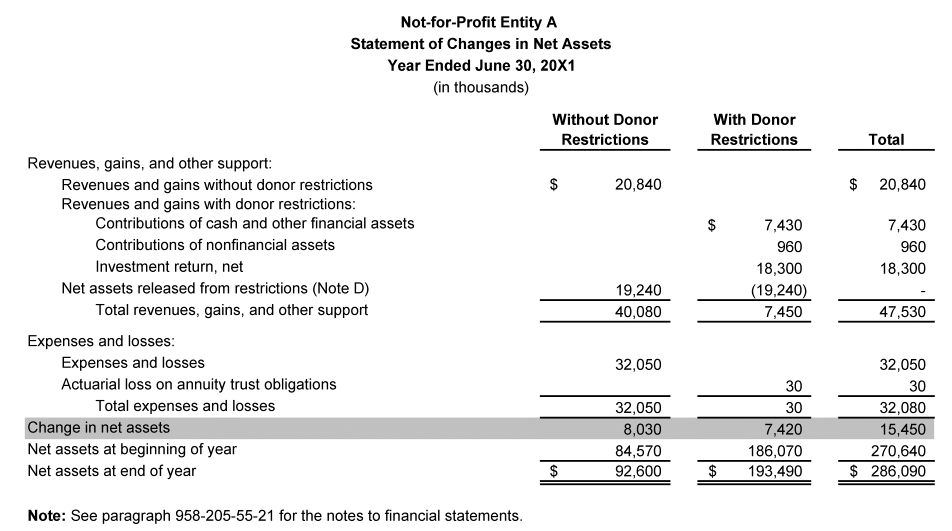 Not-for-Profit Entity A Statement of Changes in Net Assets " Year Ended June 30, 20X1" (in thousands) Without Donor Restrictions With Donor Restrictions Total "Revenues, gains, and other support:" Revenues and gains without donor restrictions " $20,840 " " $20,840 " Revenues and gains with donor restrictions: Contributions of cash and other financial assets " $7,430 " " 7,430 " Contributions of nonfinancial assets 960 960 "Investment return, net" " 18,300 " " 18,300 " Net assets released from restrictions (Note D) " 19,240 " " (19,240)" - "Total revenues, gains, and other support" " 40,080 " " 7,450 " " 47,530 " Expenses and losses: Expenses and losses " 32,050 " " 32,050 " Actuarial loss on annuity trust obligations 30 30 Total expenses and losses " 32,050 " 30 " 32,080 " Change in net assets " 8,030 " " 7,420 " " 15,450 " Net assets at beginning of year " 84,570 " " 186,070 " " 270,640 " Net assets at end of year " $92,600 " " $193,490 " " $286,090 " Note: See paragraph 958-205-55-21 for the notes to financial statements.
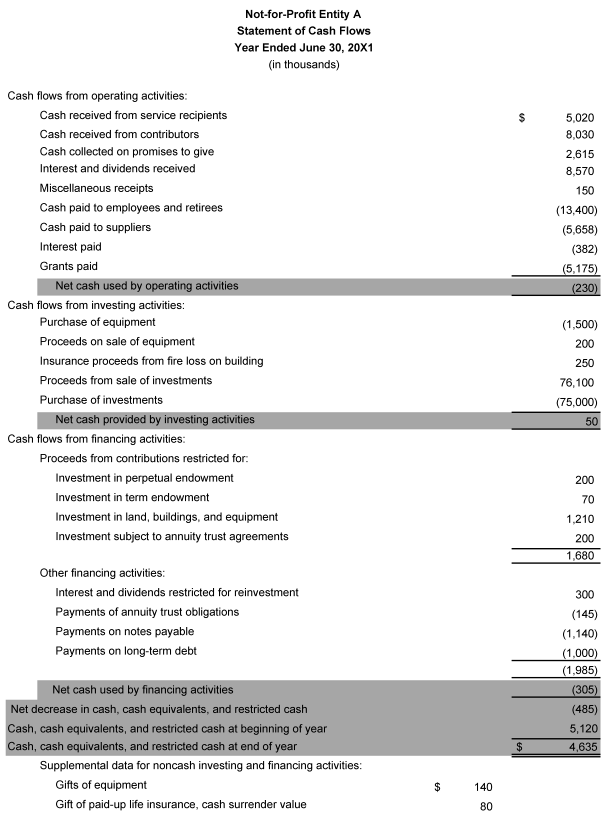 Not-for-Profit Entity A Statement of Cash Flows " Year Ended June 30, 20X1" (in thousands) Cash flows from operating activities: Change in net assets " $15,450 " Adjustments to reconcile change in net assets to net cash used by operating activities: Depreciation " 3,200 " Fire loss 80 Actuarial loss on annuity trust obligations 30 Gain on sale of equipment (200) Increase in accounts and interest receivable (460) Decrease in inventories and prepaid expenses 390 Increase in contributions receivable (325) Increase in accounts payable " 1,520 " Decrease in refundable advance (650) Decrease in grants payable (425) Contributions restricted for long-term investment " (2,740)" Realized and unrealized gains on investments " (15,800)" Interest and dividends restricted for reinvestment (300) Net cash used by operating activities (230) Cash flows from investing activities: Purchase of equipment " (1,500)" Proceeds on sale of equipment 200 Insurance proceeds from fire loss on building 250 Proceeds from sale of investments " 76,100 " Purchase of investments "(75,000)" Net cash provided by investing activities 50 Cash flows from financing activities: Proceeds from contributions restricted for: Investment in perpetual endowment 200 Investment in term endowment 70 "Investment in land, buildings, and equipment" " 1,210 " Investment subject to annuity trust agreements 200 " 1,680 " Other financing activities: Interest and dividends restricted for reinvestment 300 Payments of annuity trust obligations (145) Payments on notes payable " (1,140)" Payments on long-term debt " (1,000)" " (1,985)" Net cash used by financing activities (305) "Net decrease in cash, cash equivalents, and restricted cash" (485) "Cash, cash equivalents, and restricted cash at beginning of year" "5,120" "Cash, cash equivalents, and restricted cash at end of year" "$ 4,635" Supplemental data: Noncash investing and financing activities: Gifts of equipment $140 "Gift of paid-up life insurance, cash surrender value" 80 Interest paid 382
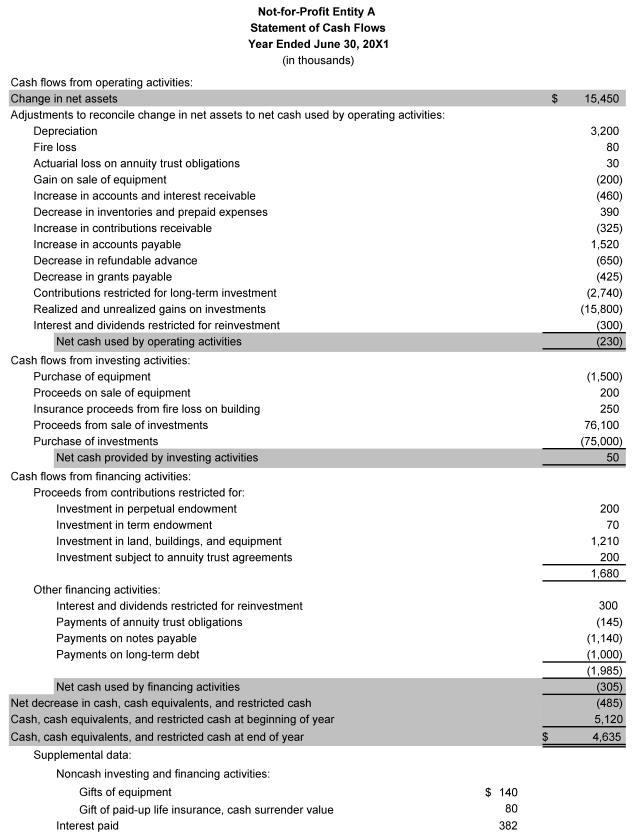 Not-for-Profit Entity A Statement of Cash Flows " Year Ended June 30, 20X1" (in thousands) Cash flows from operating activities: Change in net assets " $15,450 " Adjustments to reconcile change in net assets to net cash used by operating activities: Depreciation " 3,200 " Fire loss 80 Actuarial loss on annuity trust obligations 30 Gain on sale of equipment (200) Increase in accounts and interest receivable (460) Decrease in inventories and prepaid expenses 390 Increase in contributions receivable (325) Increase in accounts payable " 1,520 " Decrease in refundable advance (650) Decrease in grants payable (425) Contributions restricted for long-term investment " (2,740)" Realized and unrealized gains on investments " (15,800)" Interest and dividends restricted for reinvestment (300) Net cash used by operating activities (230) Cash flows from investing activities: Purchase of equipment " (1,500)" Proceeds on sale of equipment 200 Insurance proceeds from fire loss on building 250 Proceeds from sale of investments " 76,100 " Purchase of investments "(75,000)" Net cash provided by investing activities 50 Cash flows from financing activities: Proceeds from contributions restricted for: Investment in perpetual endowment 200 Investment in term endowment 70 "Investment in land, buildings, and equipment" " 1,210 " Investment subject to annuity trust agreements 200 " 1,680 " Other financing activities: Interest and dividends restricted for reinvestment 300 Payments of annuity trust obligations (145) Payments on notes payable " (1,140)" Payments on long-term debt " (1,000)" " (1,985)" Net cash used by financing activities (305) "Net decrease in cash, cash equivalents, and restricted cash" (485) "Cash, cash equivalents, and restricted cash at beginning of year" "5,120" "Cash, cash equivalents, and restricted cash at end of year" "$ 4,635" Supplemental data: Noncash investing and financing activities: Gifts of equipment $140 "Gift of paid-up life insurance, cash surrender value" 80 Interest paid 382
- Note B
- Net assets with donor restrictions are restricted for the following purposes or periods.
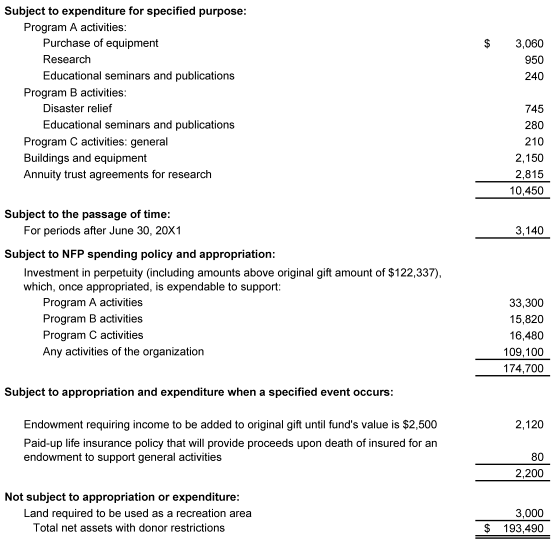 Subject to expenditure for specified purpose: Program A activities: Purchase of equipment " $3,060 " Research 950 Educational seminars and publications 240 Program B activities: Disaster relief 745 Educational seminars and publications 280 Program C activities: general 210 Buildings and equipment " 2,150 " Annuity trust agreements for research " 2,815 " " 10,450 " Subject to the passage of time: "For periods after June 30, 20X1" " 3,140 " Subject to NFP spending policy and appropriation: "Investment in perpetuity (including amounts above original gift amount of $122,337), which, once appropriated, is expendable to support:" Program A activities " 33,300 " Program B activities " 15,820 " Program C activities " 16,480 " Any activities of the organization " 109,100 " " 174,700 " Subject to appropriation and expenditure when a specified event occurs: "Endowment requiring income to be added to original gift until fund's value is $2,500" " 2,120 " Paid-up life insurance policy that will provide proceeds upon death of insured for an endowment to support general activities 80 " 2,200 " Not subject to appropriation or expenditure: Land required to be used as a recreation area " 3,000 " Total net assets with donor restrictions " $193,490 "
- Note D
- Net assets were released from donor restrictions by incurring expenses satisfying the restricted purposes or by occurrence of the passage of time or other events specified by donors.
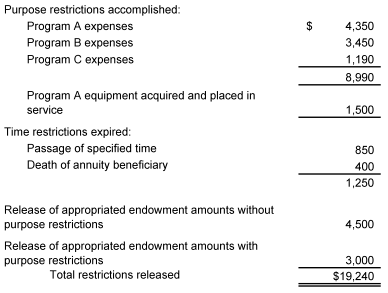 Purpose restrictions accomplished: Program A expenses "$4,350 " Program B expenses "3,450" Program C expenses "1,190" "8,990" Program A equipment acquired and placed in service " 1,500 " Time restrictions expired: Passage of specified time 850 Death of annuity beneficiary 400 " 1,250 " Release of appropriated endowment amounts without purpose restrictions "4,500" Release of appropriated endowment amounts with purpose restrictions "3,000" Total restrictions released "$19,240 "
- Note DD
- Not-for-Profit Entity A's governing board has designated, from net assets without donor restrictions of $92,600, net assets for the following purposes as of June 30, 20X1.
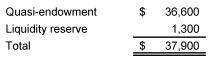 Quasi-endowment " $36,600 " Liquidity reserve "1,300 " Total " $37,900 "
- Note E
- Investments are carried at fair value, and realized and unrealized gains and losses are reflected within investment return, net, in the statement of activities. Not-for-Profit Entity A invests cash in excess of daily requirements in short-term investments. At June 30, 20X1, $1,400 was invested short term, and during the year short-term investments earned $850. Most long-term investments are held in two investment pools. Pool A is for donor-restricted endowments and the unappropriated net appreciation of those endowments. Pool B is for amounts designated by the board of trustees for long-term investment. Annuity trusts of $4,500, term endowments of $70, and certain donor-restricted endowments of $2,200 are separately invested. Long-term investment activity is reflected in the following table.
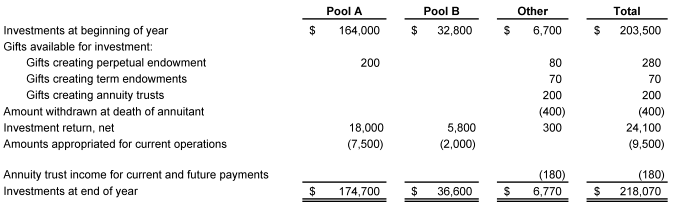 Pool A Pool B Other Total Investments at beginning of year " $164,000 " " $32,800 " " $6,700 " " $203,500 " Gifts available for investment: Gifts creating perpetual endowment 200 80 280 Gifts creating term endowments 70 70 Gifts creating annuity trusts 200 200 Amount withdrawn at death of annuitant (400) (400) "Investment return, net" "18,000" "5,800" 300 " 24,100 " Amounts appropriated for current operations " (7,500)" " (2,000)" " (9,500)" Annuity trust income for current and future payments (180) (180) Investments at end of year " $174,700 " " $36,600 " " $6,770 " " $218,070 " Pool A Pool B Other Total Permanently restricted net assets " $136,820 " " $2,200 " " $139,020 " Temporarily restricted net assets " 10,752 " " 4,570 " " 15,322 " Unrestricted net assets " 27,128 " " $36,600 " " 63,728 " " $174,700 " " $36,600 " " $6,770 " " $218,070 "
- Laws and regulations allow the governing board to appropriate so much of an endowment fund as is prudent considering the following relevant factors: the duration and preservation of the endowment fund, the purposes of Not-for-Profit Entity A and the endowment fund, general economic conditions, the possible effect of inflation or deflation, the expected total return from income and the appreciation of investments, Not-for-Profit Entity A's other resources, and Not-for-Profit Entity A's investment policy. Under Not-for-Profit Entity A's endowment spending policy, 5 percent of the average of the fair value at the end of the previous 3 years is appropriated, which was $7,500 for the year ended June 30, 20X1.
- Note F
- The table below presents expenses by both their nature and their function for fiscal year 20X1.
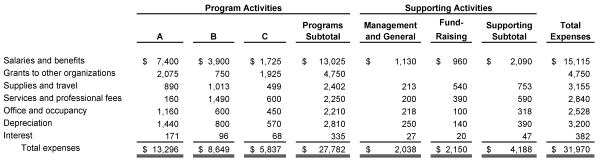 Program Activities Supporting Activities Total Expenses A B C Programs Subtotal Management and General Fund- Supporting Subtotal Raising Salaries and benefits " $7,400 " " $3,900 " " $1,725 " " $13,025 " " $1,130 " $960 " $2,090 " " $15,115 " Grants to other organizations " 2,075 " 750 " 1,925 " " 4,750 " " 4,750 " Supplies and travel 890 " 1,013 " 499 " 2,402 " 213 540 753 " 3,155 " Services and professional fees 160 " 1,490 " 600 " 2,250 " 200 390 590 " 2,840 " Office and occupancy " 1,160 " 600 450 " 2,210 " 218 100 318 " 2,528 " Depreciation " 1,440 " 800 570 " 2,810 " 250 140 390 " 3,200 " Interest 171 96 68 335 27 20 47 382 Total expenses " $13,296 " " $8,649 " " $5,837 " " $27,782 " " $2,038 " " $2,150 " " $4,188 " " $31,970 "
- The financial statements report certain categories of expenses that are attributable to more than one program or supporting function. Therefore, these expenses require allocation on a reasonable basis that is consistently applied. The expenses that are allocated include depreciation, interest, and office and occupancy, which are allocated on a square-footage basis, as well as salaries and benefits, which are allocated on the basis of estimates of time and effort.
- Note G
- The following reflects Not-for-Profit Entity A's financial assets as of the balance sheet date, reduced by amounts not available for general use because of contractual or donor-imposed restrictions within one year of the balance sheet date. Amounts not available include amounts set aside for long-term investing in the quasi-endowment that could be drawn upon if the governing board approves that action. However, amounts already appropriated from either the donor-restricted endowment or quasi-endowment for general expenditure within one year of the balance sheet date have not been subtracted as unavailable.
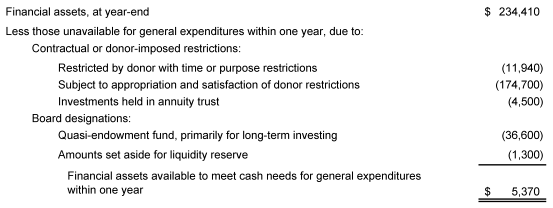 "Financial assets, at year-end" " $234,410 " "Less those unavailable for general expenditures within one year, due to: " Contractual or donor-imposed restrictions: Restricted by donor with time or purpose restrictions " (11,940)" Subject to appropriation and satisfaction of donor restrictions " (174,700)" Investments held in annuity trust " (4,500)" Board designations: "Quasi-endowment fund, primarily for long-term investing" " (36,600)" Amounts set aside for liquidity reserve " (1,300)" Financial assets available to meet cash needs for general expenditures within one year " $5,370 "
- Not-for-Profit Entity A is substantially supported by restricted contributions. Because a donor's restriction requires resources to be used in a particular manner or in a future period, Not-for-Profit Entity A must maintain sufficient resources to meet those responsibilities to its donors. Thus, financial assets may not be available for general expenditure within one year. As part of Not-for-Profit Entity A's liquidity management, it has a policy to structure its financial assets to be available as its general expenditures, liabilities, and other obligations come due. In addition, Not-for-Profit Entity A invests cash in excess of daily requirements in short-term investments. Occasionally, the board designates a portion of any operating surplus to its liquidity reserve, which was $1,300 as of June 30, 20X1. There is a fund established by the governing board that may be drawn upon in the event of financial distress or an immediate liquidity need resulting from events outside the typical life cycle of converting financial assets to cash or settling financial liabilities. In the event of an unanticipated liquidity need, Not-for-Profit Entity A also could draw upon $10,000 of available lines of credit (as further discussed in Note XX) or its quasi-endowment fund.
- Note H
- The following table provides a reconciliation of cash, cash equivalents, and restricted cash reported within the statement of financial position that sum to the total of the same such amounts shown in the statement of cash flows.
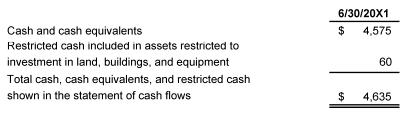 6/30/20X1 Cash and cash equivalents " $4,575 " "Restricted cash included in assets restricted to investment in land, buildings, and equipment" 60 "Total cash, cash equivalents, and restricted cash shown in the statement of cash flows" " $4,635 "
- Assets restricted to investment in land, buildings, and equipment on the statement of financial position include restricted cash received with a donor-imposed restriction that limits use of that cash to long-term purposes.
- aNFP B is issuing a full set of financial statements for both the current fiscal year, 200Y, and the previous fiscal year, 200X.NFP B is required to disclose the information in paragraph 958-205-50-1B for each period for which it presents financial statements; however, for simplicity, the disclosures provide information for a single period, 200Y.
- bNFP B has a sizable endowment.
- cBefore 200Y, an enacted version of the Uniform Prudent Management of Institutional Funds Act of 2006 became effective for the State to whose law NFP B is subject.
- d
- eNone of the funds have donor stipulations that override the restriction described in subsection 4(a) of the law, which the enacted version in the State included verbatim: "unless stated otherwise in the gift instrument, the assets in an endowment fund are donor-restricted assets until appropriated for expenditure by the institution."
- f
- g
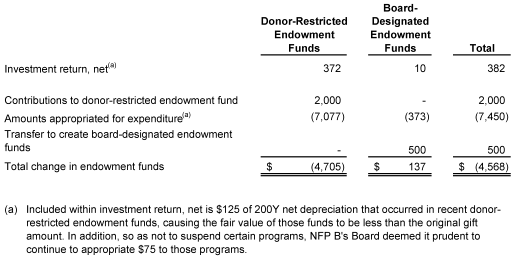 Board- Donor-Restricted Designated Endowment Endowment Funds Funds Total "Investment return, net(a)" 372 10 382 Contributions to donor-restricted endowment fund " 2,000 " - " 2,000 " Amounts appropriated for expenditure(a) " (7,077)" (373) " (7,450)" Transfer to create board-designated endowment funds - 500 500 Total change in endowment funds " $(4,705)" $137 " $(4,568)" (a) "Included within investment return, net is $125 of 200Y net depreciation that occurred in recent donor-restricted endowment funds, causing the fair value of those funds to be less than the original gift amount. In addition, so as not to suspend certain programs, NFP B's Board deemed it prudent to continue to appropriate $75 to those programs. "
- NOTE X: ENDOWMENT
- NFP B's endowment consists of approximately 100 individual funds established for a variety of purposes. Its endowment includes both donor-restricted endowment funds and funds designated by the Board of Trustees to function as endowments. As required by GAAP, net assets associated with endowment funds, including funds designated by the Board of Trustees to function as endowments, are classified and reported based on the existence or absence of donor-imposed restrictions.
- Interpretation of Relevant Law
- NFP B is subject to the State Prudent Management of Institutional Funds Act (SPMIFA) and, thus, classifies amounts in its donor-restricted endowment funds as net assets with donor restrictions because those net assets are time restricted until the Board of Trustees appropriates such amounts for expenditure. Most of those net assets also are subject to purpose restrictions that must be met before reclassifying those net assets to net assets without donor restrictions. The Board of Trustees of NFP B has interpreted SPMIFA as not requiring the maintenance of purchasing power of the original gift amount contributed to an endowment fund, unless a donor stipulates the contrary. As a result of this interpretation, when reviewing its donor-restricted endowment funds, NFP B considers a fund to be underwater if the fair value of the fund is less than the sum of (a) the original value of initial and subsequent gift amounts donated to the fund and (b) any accumulations to the fund that are required to be maintained in perpetuity in accordance with the direction of the applicable donor gift instrument. NFP B has interpreted SPMIFA to permit spending from underwater funds in accordance with the prudent measures required under the law.Additionally, in accordance with SPMIFA, NFP B considers the following factors in making a determination to appropriate or accumulate donor-restricted endowment funds:
- (1) The duration and preservation of the fund
- (2) The purposes of the organization and the donor-restricted endowment fund
- (3) General economic conditions
- (4) The possible effect of inflation and deflation
- (5) The expected total return from income and the appreciation of investments
- (6) Other resources of the organization
- (7) The investment policies of NFP B.
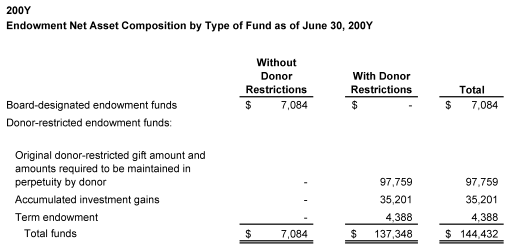 200Y "Endowment Net Asset Composition by Type of Fund as of June 30, 200Y" Without Donor Restrictions With Donor Restrictions Total Board-designated endowment funds " $7,084 " $- " $7,084 " Donor-restricted endowment funds: Original donor-restricted gift amount and amounts required to be maintained in perpetuity by donor - " 97,759 " " 97,759 " Accumulated investment gains Portion subject to appropriation under SPMIFA - " 35,201 " " 35,201 " Term endowment - " 4,388 " " 4,388 " Total funds " $7,084 " " $137,348 " " $144,432 "
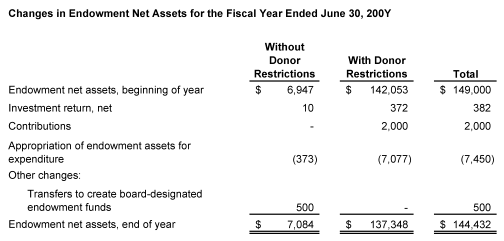 "Changes in Endowment Net Assets for the Fiscal Year Ended June 30, 200Y" Without Donor Restrictions With Donor Restrictions Total "Endowment net assets, beginning of year" " $6,947 " " $142,053 " " $149,000 " "Investment return, net" 10 372 382 Contributions - " 2,000 " " 2,000 " Appropriation of endowment assets for expenditure (373) " (7,077)" " (7,450)" Other changes: Transfers to create board-designated endowment funds 500 - 500 "Endowment net assets, end of year" " $7,084 " " $137,348 " " $144,432 "
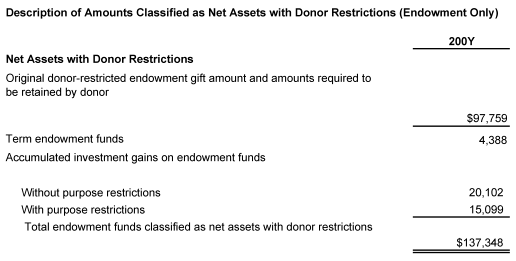 Description of Amounts Classified as Net Assets with Donor Restrictions (Endowment Only) 200Y Net Assets with Donor Restrictions Original donor-restricted endowment gift amount and amounts required to be retained by donor "$97,759 " Term endowment funds "4,388" Accumulated investment gains on endowment funds Without purpose restrictions " 20,102 " With purpose restrictions " 15,099 " Total endowment funds classified as net assets with donor restrictions "$137,348 "
- Underwater Endowment Funds
- From time to time, the fair value of assets associated with individual donor-restricted endowment funds may fall below the level that the donor or SPMIFA requires NFP B to retain as a fund of perpetual duration. Deficiencies of this nature exist in 3 donor-restricted endowment funds, which together have an original gift value of $3,500, a current fair value of $3,300, and a deficiency of $200 as of June 30, 200Y. These deficiencies resulted from unfavorable market fluctuations that occurred shortly after the investment of new contributions for donor-restricted endowment funds and continued appropriation for certain programs that was deemed prudent by the Board of Trustees.
- Return Objectives and Risk Parameters
- NFP B has adopted investment and spending policies for endowment assets that attempt to provide a predictable stream of funding to programs supported by its endowment while seeking to maintain the purchasing power of the endowment assets. Endowment assets include those assets of donor-restricted funds that the organization must hold in perpetuity or for a donor-specified period(s) as well as board-designated funds. Under this policy, as approved by the Board of Trustees, the endowment assets are invested in a manner that is intended to produce results that exceed the price and yield results of the S&P 500 index while assuming a moderate level of investment risk. NFP B expects its endowment funds, over time, to provide an average rate of return of approximately 8 percent annually. Actual returns in any given year may vary from this amount.
- Strategies Employed for Achieving Objectives
- To satisfy its long-term rate-of-return objectives, NFP B relies on a total return strategy in which investment returns are achieved through both capital appreciation (realized and unrealized) and current yield (interest and dividends). NFP B targets a diversified asset allocation that places a greater emphasis on equity-based investments to achieve its long-term return objectives within prudent risk constraints.
- Spending Policy and How the Investment Objectives Relate to Spending Policy
- NFP B has a policy of appropriating for distribution each year 5 percent of its endowment fund's average fair value over the prior 12 quarters through the calendar year-end preceding the fiscal year in which the distribution is planned. In establishing this policy, NFP B considered the long-term expected return on its endowment. Accordingly, over the long term, NFP B expects the current spending policy to allow its endowment to grow at an average of 3 percent annually. NFP B has a policy that permits spending from underwater endowment funds depending on the degree to which the fund is underwater, unless otherwise precluded by donor intent or relevant laws and regulations. The governing board appropriated for expenditure $75 from underwater endowment funds during the year, which represents 3 percent of the 12-quarter moving average, not the 5 percent it generally draws from its endowment.
205-958-60Relationships
Source downloaded: .Record version 4edf9dd43a8c. Effective date must be checked in the source.
Risks and Uncertainties
205-958-65Transition and Open Effective Date Information
Source downloaded: .Record version af38c3659561. Effective date must be checked in the source.
Related subtopics
- 210-958 Not-for-Profit EntitiesBalance Sheet
- 220-958 Not-for-Profit EntitiesIncome Statement—Reporting Comprehensive Income
- 320-958 Not-for-Profit EntitiesInvestments—Debt Securities
- 220-954 Health Care EntitiesIncome Statement—Reporting Comprehensive Income
- 360-958 Not-for-Profit EntitiesProperty, Plant, and Equipment
- 720-958 Not-for-Profit EntitiesOther Expenses