ASC 210-958
Not-for-Profit Entities
210 Balance Sheet
Source downloaded: .Record version fba8d495fcc0. Effective date must be checked in the source.
This subtopic governs the not-for-profit statement of financial position (the NFP equivalent of a balance sheet). At a minimum the statement must report totals for assets, liabilities, net assets, net assets with donor restrictions, and net assets without donor restrictions, focusing on the entity as a whole (958-210-45-1). It also requires liquidity-related presentation and disclosure, including qualitative information about how the NFP manages liquid resources and quantitative information about financial assets available for general expenditures within one year (958-210-50-1A).
Key points (7)
- A statement of financial position must focus on the NFP as a whole and report total assets, total liabilities, total net assets, total net assets with donor restrictions, and total net assets without donor restrictions (958-210-45-1).
- Interfund receivables and payables are not entity assets or liabilities; if displayed, they must be labeled and arranged so their amounts are eliminated from total assets and liabilities (958-210-45-2); no particular statement format is required or precluded (958-210-45-3).
- Assets and liabilities generally should be aggregated into reasonably homogeneous groups reflecting donor-imposed and other contractual restrictions to convey liquidity and financial flexibility (958-210-45-4 through 45-5).
- Restrictions generally apply to net assets rather than specific assets, so assets need not be disaggregated by restriction; however, cash or other assets received with donor restrictions limiting use to long-term purposes may not be classified with unrestricted assets available for current use (958-210-45-6).
- Limitations on cash and cash equivalents, contractual limitations on particular assets, and quantitative information on availability of financial assets for general expenditures within one year must appear on the face of the statement or in the notes (958-210-45-7).
- Additional liquidity information may be provided by sequencing assets/liabilities by nearness to cash or maturity, using a classified current/noncurrent format, or note disclosure (958-210-45-8); health care NFPs must use a classified format under 954-210-45-1.
- An NFP must disclose qualitative information on how it manages liquid resources for general expenditures within one year and quantitative information on availability of financial assets, considering nature, external donor/law/contract limits, and internal board limits (958-210-50-1A); board designations, including board-designated endowment funds, must be disclosed as to amounts and purposes (958-210-45-11).
For students. Exam questions turn on the two-class net asset model (with/without donor restrictions, after ASU 2016-14 eliminated the old three-class temporarily/permanently restricted split) and the required liquidity/availability disclosures. A common misunderstanding is thinking donor restrictions attach to specific assets — they attach to net assets, though long-term-purpose restricted cash still cannot be lumped with cash available for current use.
Machine-generated study aid for ASC 210-958. Check the source paragraphs below.
210-958-00Status
Source downloaded: .Record version 89fffd4e9ee2. Effective date must be checked in the source.
210-958-05Overview and Background
Source downloaded: .Record version b9b80c00110e. Effective date must be checked in the source.
- aThe NFP's ability to continue to provide services
- bThe NFP's liquidity, financial flexibility, ability to meet obligations, and needs for external financing.
210-958-15Scope and Scope Exceptions
Source downloaded: .Record version 0375f0c32025. Effective date must be checked in the source.
Overall Guidance
210-958-45Other Presentation Matters
Source downloaded: .Record version 30e36b51a2ff. Effective date must be checked in the source.
Totals and Format
- aTotal assets
- bTotal liabilities
- cTotal net assets
- d
- e
- f
Classification of Assets and Liabilities
- aRelevant information about the nature and amount of limitations on the use of cash and cash equivalents (such as cash held on deposit as a compensating balance) (see paragraph 958-210-50-3(b)).
- bContractual limitations on the use of particular assets. These include, for example, restricted cash or other assets set aside under debt agreements, assets set aside under self-insurance funding arrangements, assets set aside under collateral arrangements, or assets set aside to satisfy reserve requirements that states may impose under charitable gift annuity agreements (see paragraph 958-210-50-3(c)).
- cQuantitative information, and additional qualitative information in the notes as necessary, about the availability of an NFP's financial assets at the balance sheet date to meet cash needs for general expenditures within one year of the balance sheet date (see paragraph 958-210-50-1A(b)).
- aSequencing assets according to their nearness of conversion to cash and sequencing liabilities according to the nearness of their maturity and resulting use of cash
- bClassifying assets and liabilities as current and noncurrent, as defined by Subtopic 210-10 (required by paragraph 954-210-45-1 for statements of financial position prepared by not-for-profit, business-oriented health care entities)
- cDisclosing in notes to financial statements any additional relevant information about the liquidity or maturity of assets and liabilities, including restrictions on the use of particular assets (see paragraph 958-210-50-1).
Classification of Net Assets
- aAssets, such as land or works of art, donated with stipulations that they be used for a specified purpose, be preserved, and not be sold.
- bAssets donated with stipulations that they be invested to provide a permanent source of income. These result from gifts and bequests that create a donor-restricted endowment that is perpetual in nature.
- cSupport of particular operating activities.
- dInvestment for a specified term.
- eUse in a specified future period.
- fAcquisition of long-lived assets.
210-958-50Disclosure
Source downloaded: .Record version 2b06b7a937ad. Effective date must be checked in the source.
- a Qualitative information in the notes to financial statements that is useful in assessing an entity's liquidity and that communicates how an NFP manages its liquid resources available to meet cash needs for general expenditures within one year of the date of the statement of financial position
- b Quantitative information either on the face of the statement of financial position or in the notes, and additional qualitative information in the notes as necessary, that communicates the availability of an NFP's financial assets at the date of the statement of financial position to meet cash needs for general expenditures within one year of the date of the statement of financial position (see paragraph 958-210-45-7(c)). Availability of a financial asset may be affected by:
- 1 Its nature
- 2 External limits imposed by donors, laws, and contracts with others
- 3 Internal limits imposed by governing board decisions.
- 1
- a Unusual circumstances, such as special borrowing arrangements, requirements imposed by resource providers that cash be held in separate accounts, and known significant liquidity problems
- b The fact that the NFP has not maintained appropriate amounts of cash and cash equivalents to comply with donor-imposed restrictions (see paragraph 958-450-50-3)
- c Information about significant limits resulting from contractual agreements with suppliers, creditors, and others, including the existence of loan covenants.
- aA description of the kind of asset whose use is limited (see paragraph 958-210-45-6)
- bInformation about the nature and amount of limitations on the use of cash and cash equivalents (see paragraph 958-210-45-7(a))
- cContractual limitations on the use of particular assets (see paragraph 958-210-45-7(b))
- dInformation about the nature and amounts of different types of restrictions that affect how and when, if ever, the resources (net assets) can be used (see paragraph 958-210-45-9)
- e
- fInformation about additional limitations placed on net assets, such as information about the amounts and purposes of board designations of net assets without donor restrictions required in accordance with paragraph 958-210-45-11.
210-958-55Implementation Guidance and Illustrations
Source downloaded: .Record version b3c01ee5820d. Effective date must be checked in the source.
Illustrations
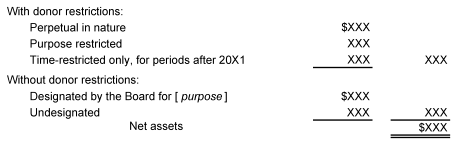 With donor restrictions: Perpetual in nature $XXX Purpose restricted XXX "Time-restricted only, for periods after 20X1" XXX XXX Without donor restrictions: Designated by the Board for [ purpose] $XXX Undesignated XXX XXX Net assets $XXX
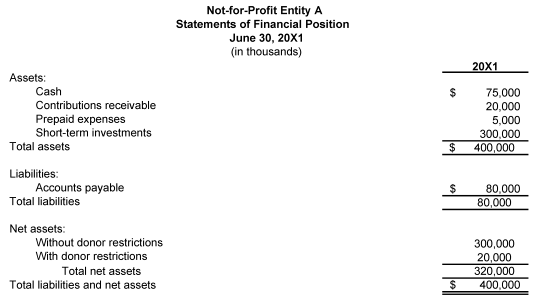 Not-for-Profit Entity A Statements of Financial Position " June 30, 20X1" (in thousands) 20X1 Assets: Cash " $75,000 " Contributions receivable " 20,000 " Prepaid expenses " 5,000 " Short-term investments " 300,000 " Total assets " $400,000 " Liabilities: Accounts payable " $80,000 " Total liabilities " 80,000 " Net assets: Without donor restrictions " 300,000 " With donor restrictions " 20,000 " Total net assets " 320,000 " Total liabilities and net assets " $400,000 "
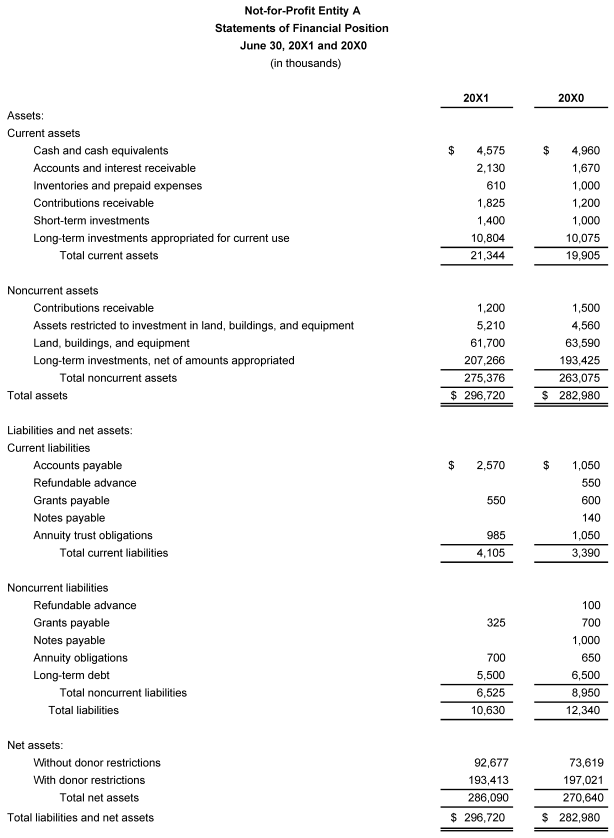 Not-for-Profit Entity A Statements of Financial Position " June 30, 20X1 and 20X0" (in thousands) 20X1 20X0 Assets: Current assets Cash and cash equivalents " $4,575 " " $4,960 " Accounts and interest receivable " 2,130 " " 1,670 " Inventories and prepaid expenses 610 " 1,000 " Contributions receivable " 1,825 " " 1,200 " Short-term investments " 1,400 " " 1,000 " Long-term investments appropriated for current use " 10,804 " " 10,075 " Total current assets " 21,344 " " 19,905 " Noncurrent assets Contributions receivable " 1,200 " " 1,500 " "Assets restricted to investment in land, buildings, and equipment" " 5,210 " " 4,560 " "Land, buildings, and equipment" " 61,700 " " 63,590 " "Long-term investments, net of amounts appropriated" " 207,266 " " 193,425 " Total noncurrent assets " 275,376 " " 263,075 " Total assets " $296,720 " " $282,980 " Liabilities and net assets: Current liabilities Accounts payable " $2,570 " " $1,050 " Refundable advance 550 Grants payable 550 600 Notes payable 140 Annuity trust obligations 985 " 1,050 " Total current liabilities " 4,105 " " 3,390 " Noncurrent liabilities Refundable advance 100 Grants payable 325 700 Notes payable " 1,000 " Annuity obligations 700 650 Long-term debt " 5,500 " " 6,500 " Total noncurrent liabilities " 6,525 " " 8,950 " Total liabilities " 10,630 " " 12,340 " Net assets: Without donor restrictions "92,677" "73,619" With donor restrictions "193,413" "197,021" Total net assets "286,090" "270,640" Total liabilities and net assets " $296,720 " " $282,980 "
- Note T
- NFP A's financial assets available within one year of the balance sheet date for general expenditure are as follows.
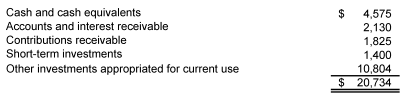 Cash and cash equivalents " $4,575 " Accounts and interest receivable " 2,130 " Contributions receivable " 1,825 " Short-term investments " 1,400 " Other investments appropriated for current use " 10,804 " " $20,734 "
- NFP A's endowment funds consist of donor-restricted endowments and a quasi-endowment. Income from donor-restricted endowments is restricted for specific purposes and, therefore, is not available for general expenditure. As described in Note Y, the quasi-endowment has a spending rate of 5 percent. $1.65 million of appropriations from the quasi-endowment will be available within the next 12 months.
- As part of NFP A's liquidity management, it has a policy to structure its financial assets to be available as its general expenditures, liabilities, and other obligations come due. In addition, NFP A invests cash in excess of daily requirements in short-term investments. To help manage unanticipated liquidity needs, NFP A has committed lines of credit in the amount of $20 million, which it could draw upon. Additionally, NFP A has a quasi-endowment of $33 million. Although NFP A does not intend to spend from its quasi-endowment other than amounts appropriated for general expenditure as part of its annual budget approval and appropriation process, amounts from its quasi-endowment could be made available if necessary. However, both the quasi-endowment and donor-restricted endowments contain investments with lock-up provisions that would reduce the total investments that could be made available (see Note X for disclosures about investments).
210-958-60Relationships
Source downloaded: .Record version 17f836fd5a7a. Effective date must be checked in the source.
Balance Sheet
Related subtopics
- 205-958 Not-for-Profit EntitiesPresentation of Financial Statements
- 220-958 Not-for-Profit EntitiesIncome Statement—Reporting Comprehensive Income
- 320-958 Not-for-Profit EntitiesInvestments—Debt Securities
- 210-954 Health Care EntitiesBalance Sheet
- 360-958 Not-for-Profit EntitiesProperty, Plant, and Equipment
- 230-958 Not-for-Profit EntitiesStatement of Cash Flows