ASC 210-946
Financial Services—Investment Companies
210 Balance Sheet
Source downloaded: .Record version 80d9ea1d849f. Effective date must be checked in the source.
This subtopic governs how an investment company presents its financial position — either a statement of assets and liabilities or a statement of net assets — and the schedule (or condensed schedule) of investments that accompanies it. It sets bright-line disclosure thresholds (1 percent of net assets for registered/other investment companies; 5 percent for nonregistered investment partnerships), special presentation rules for multiple-class, master-feeder, and fund-of-funds structures, and requires contract-value reporting for fully benefit-responsive investment contracts held by qualified defined contribution plan trusts.
Key points (7)
- An investment company presents financial position as either a statement of assets and liabilities or a statement of net assets, and a statement of net assets includes a schedule of investments (946-210-45-1 through 45-2).
- For multiple-class funds, composition of net assets is reported in total but net asset value per share and shares outstanding are reported for each class (946-210-45-4).
- In a master-feeder structure, the master fund generally does not report components of net assets, shares outstanding, or NAV per share and alone presents the portfolio of investments; each feeder reports its investment in the master (with NAV per share, shares outstanding, and components of net assets) and presents no schedule of portfolio investments (946-210-45-5 through 45-6).
- Investment companies other than nonregistered investment partnerships must name each investment exceeding 1 percent of net assets (and each issuer aggregating over 1 percent), disclose at a minimum the 50 largest investments, categorize investments by type and by industry/country/geographic region, and aggregate the remainder by category with percent of net assets (946-210-50-1).
- Nonregistered investment partnerships (hedge funds, LLCs, commodity pools, and similar) present a condensed schedule of investments using a 5 percent of net assets threshold, with long and short positions in any one issuer considered separately, special rules for derivatives by underlying, and investment objective and redemption restrictions for investments in other nonregistered partnerships exceeding 5 percent (946-210-50-4 through 50-6).
- If the reporting fund's proportional share of an investment held by an investee fund exceeds 5 percent of the reporting fund's net assets, that investment must be named and categorized in the condensed schedule or a note; if investee portfolio information is unavailable, that fact must be disclosed (946-210-50-9 through 50-10).
- For funds established under a trust adopted as part of qualified employer-sponsored defined contribution plans, contract value is the measurement attribute for net assets attributable to fully benefit-responsive investment contracts; the statement of assets and liabilities shows total assets, total liabilities, net assets reflecting all investments at fair value, and net assets, with the fair-value-to-contract-value adjustment shown as a single amount on the face (946-210-45-11, 45-16).
For students. Exam and practice traps here are the two different concentration thresholds — 1 percent for registered/other investment companies versus 5 percent for nonregistered investment partnerships — and the rule that long and short positions in the same issuer are tested separately. Students also frequently miss that in a master-feeder structure the schedule of investments appears only at the master level, while NAV per share and components of net assets appear only at the feeder level.
Machine-generated study aid for ASC 210-946. Check the source paragraphs below.
210-946-00Status
Source downloaded: .Record version dcd9d7054c9c. Effective date must be checked in the source.
| Paragraph | Action | Accounting Standards Update | Date |
| 946-210-45-18A | Added | Accounting Standards Update No. 2012-04 | 10/01/2012 |
| 946-210-45-20 | Added | Maintenance Update 2017-21 (PDF) | 12/22/2017 |
| 946-210-45-21 | Amended | Maintenance Update 2018-12 (PDF) | 09/10/2018 |
| 946-210-45-21 | Added | Maintenance Update 2017-21 (PDF) | 12/22/2017 |
| 946-210-50-7 | Superseded | Accounting Standards Update No. 2016-19 | 12/14/2016 |
| 946-210-50-9 | Amended | Accounting Standards Update No. 2016-19 | 12/14/2016 |
| 946-210-55-1 | Amended | Accounting Standards Update No. 2016-19 | 12/14/2016 |
| 946-210-55-2 | Amended | Maintenance Update 2016-11 (PDF) | 06/27/2016 |
210-946-05Overview and Background
Source downloaded: .Record version 34b5c0a81ba7. Effective date must be checked in the source.
210-946-15Scope and Scope Exceptions
Source downloaded: .Record version 4b89e4bcf581. Effective date must be checked in the source.
Overall Guidance
210-946-45Other Presentation Matters
Source downloaded: .Record version 81caa0cf4a0b. Effective date must be checked in the source.
Reporting Financial Position
Complex Capital Structures
Credit Enhancements
Fully Benefit-Responsive Investment Contracts
- a A traditional or separate account guaranteed investment contract
- b A bank investment contract
- c A synthetic guaranteed investment contract composed of a wrapper contract and the underlying wrapped portfolio of individual investments
- d A contract with similar characteristics.
- a Investments (including traditional guaranteed investment contracts)
- b Wrapper contracts.
- a Total assets
- b Total liabilities
- c Net assets reflecting all investments at fair value
- d Net assets.
- a The fair value of each investment contract, including separate disclosure of both of the following:
- 1 The fair value of the wrapper contract
- 2 The fair value of each of the corresponding underlying investments, if held by the fund, included in that investment contract.
- 1
- b Adjustment from fair value to contract value for each investment contract (if the investment contract is fully benefit-responsive)
- c Major credit ratings of the issuer or wrapper provider for each investment contract.
Cash and Cash Equivalents
210-946-50Disclosure
Source downloaded: .Record version 520a02beb55c. Effective date must be checked in the source.
Schedule of Investments
- aDisclose the name, number of shares, or principal amount of all of the following:
- 1Each investment (including short sales, written options, futures contracts, forward contracts, and other investment-related liabilities) whose fair value constitutes more than 1 percent of net assets. In applying the 1-percent test, total long and total short positions in any one issuer should be considered separately.
- 2All investments in any one issuer whose fair values aggregate more than 1 percent of net assets. In applying the 1-percent test, total long and total short positions in any one issuer should be considered separately.
- 3At a minimum, the 50 largest investments.
- 1
- bCategorize investments by both of the following characteristics:
- 1The type of investment (such as common stocks, preferred stocks, convertible securities, fixed income securities, government securities, options purchased, options written, warrants, futures contracts, loan participations and assignments, short-term securities, repurchase agreements, short sales, forward contracts, other investment companies, and so forth)
- 2The related industry, country, or geographic region of the investment.
- 1
- cDisclose the aggregate other investments (each of which is not required to be disclosed by (a)) without specifically identifying the issuers of such investments, and categorize as required by (b). The disclosure shall include both of the following:
- 1The percent of net assets that each such category represents
- 2The total value for category in (b)(1) and (b)(2).
- 1
- aHedge funds
- bLimited liability companies
- cLimited liability partnerships
- dLimited duration companies
- eOffshore investment companies with similar characteristics
- fCommodity pools subject to regulation under the Commodity Exchange Act of 1974.
- aCategorize investments by all of the following:
- 1Type (such as common stocks, preferred stocks, convertible securities, fixed-income securities, government securities, options purchased, options written, warrants, futures, loan participations, short sales, other investment companies, and so forth)
- 2Country or geographic region, except for derivative instruments for which the underlying is not a security (see (a)(4))
- 3Industry, except for derivative instruments for which the underlying is not a security (see (a)(4))
- 4For derivative instruments for which the underlying is not a security, by broad category of underlying (for example, grains and feeds, fibers and textiles, foreign currency, or equity indexes) in place of the categories in (a)(2) and (a)(3).
- 1
- bReport the percent of net assets that each such category represents and the total fair value and cost for each category in (a)(1) and (a)(2).
- cDisclose the name, number of shares or principal amount, fair value, and type of both of the following:
- 1Each investment (including short sales) constituting more than 5 percent of net assets, except for derivative instruments (see (e) and (f)). In applying the 5-percent test, total long and total short positions in any one issuer should be considered separately.
- 2All investments in any one issuer aggregating more than 5 percent of net assets, except for derivative instruments (see (e) and (f)). In applying the 5-percent test, total long and total short positions in any one issuer shall be considered separately.
- 1
- dAggregate other investments (each of which is 5 percent or less of net assets) without specifically identifying the issuers of such investments, and categorize them in accordance with the guidance in (a). In applying the 5-percent test, total long and total short positions in any one issuer shall be considered separately.
- eDisclose the number of contracts, range of expiration dates, and cumulative appreciation (depreciation) for open futures contracts of a particular underlying (such as wheat, cotton, specified equity index, or U.S. Treasury Bonds), regardless of exchange, delivery location, or delivery date, if cumulative appreciation (depreciation) on the open contracts exceeds 5 percent of net assets. In applying the 5-percent test, total long and total short positions in any one issuer shall be considered separately.
- fDisclose the range of expiration dates and fair value for all other derivative instruments of a particular underlying (such as foreign currency, wheat, specified equity index, or U.S. Treasury Bonds) regardless of counterparty, exchange, or delivery date, if fair value exceeds 5 percent of net assets. In applying the 5-percent test, total long and total short positions in any one issuer shall be considered separately.
- gProvide both of the following additional qualitative descriptions for each investment in another nonregistered investment partnership whose fair value constitutes more than 5 percent of net assets:
- 1The investment objective
- 2Restrictions on redemption (that is, liquidity provisions).
- 1
Fully Benefit-Responsive Investment Contracts
- aA description of the nature of those investment contracts.
- bA description of how those investment contracts operate.
- cA description of the methodology for calculating the interest crediting for those investment contracts, including all of the following:
- 1The key factors that could influence future average interest crediting rates
- 2The basis for and frequency of determining interest crediting rate resets
- 3Any minimum interest crediting rate under the terms of the contracts.
- 1
- dAn explanation of the relationship between future interest crediting rates and the amount reported on the statement of assets and liabilities representing the adjustment for the portion of net assets attributable to fully benefit-responsive investment contracts from fair value to contract value.
- eA reconciliation between the beginning and ending balance of the amount presented on the statement of assets and liabilities that represents the difference between net assets reflecting all investments at fair value and net assets for each period in which a statement of changes in net assets is presented. This reconciliation shall include both of the following:
- 1The change in the difference between the fair value and contract value of all fully benefit-responsive investment contracts
- 2The increase or decrease due to changes in the fully benefit-responsive status of the fund's investment contracts.
- 1
- fThe average yield earned by the entire fund (which may differ from the interest rate credited to participants in the fund) for each period for which a statement of assets and liabilities is presented. This average yield shall be calculated by dividing the annualized earnings of all investments in the fund (irrespective of the interest rate credited to participants in the fund) by the fair value of all investments in the fund.
- gThe average yield earned by the entire fund with an adjustment to reflect the actual interest rate credited to participants in the fund for each period for which a statement of assets and liabilities is presented. This average yield shall be calculated by dividing the annualized earnings credited to participants in the fund (irrespective of the actual earnings of the investments in the fund) by the fair value of all investments in the fund.
- hBoth of the following sensitivity analyses:
- 1The weighted average interest crediting rate (that is, the contract value yield) as of the date of the latest statement of assets and liabilities and the effect on this weighted average interest crediting rate, calculated as of the date of the latest statement of assets and liabilities and the end of the next four quarterly periods, under two or more scenarios where there is an immediate hypothetical increase or decrease in market yields, with no change to the duration of the underlying investment portfolio and no contributions or withdrawals. Those scenarios should include, at a minimum, immediate hypothetical increases and decreases in market yields equal to one-quarter and one-half of the current yield.
- 2The effect on the weighted average interest crediting rate calculated as of the date of the latest statement of assets and liabilities and the next four quarterly reset dates, under two or more scenarios where there are the same immediate hypothetical changes in market yields in the first analysis, combined with an immediate, one-time, hypothetical 10 percent decrease in the net assets of the fund due to participant transfers, with no change to the duration of the portfolio.
- 1
- iA description of the events that limit the ability of the fund to transact at contract value with the issuer (for example, premature termination of the contracts by the fund, plant closings, layoffs, plan termination, bankruptcy, mergers, and early retirement incentives), including a statement as to whether the occurrence of those events that would limit the fund's ability to transact at contract value with the participants in the fund is probable or not probable.
- jA description of the events and circumstances that would allow issuers to terminate fully benefit-responsive investment contracts with the fund and settle at an amount different from contract value.
210-946-55Implementation Guidance and Illustrations
Source downloaded: .Record version 4dd15eb9583a. Effective date must be checked in the source.
Illustrations
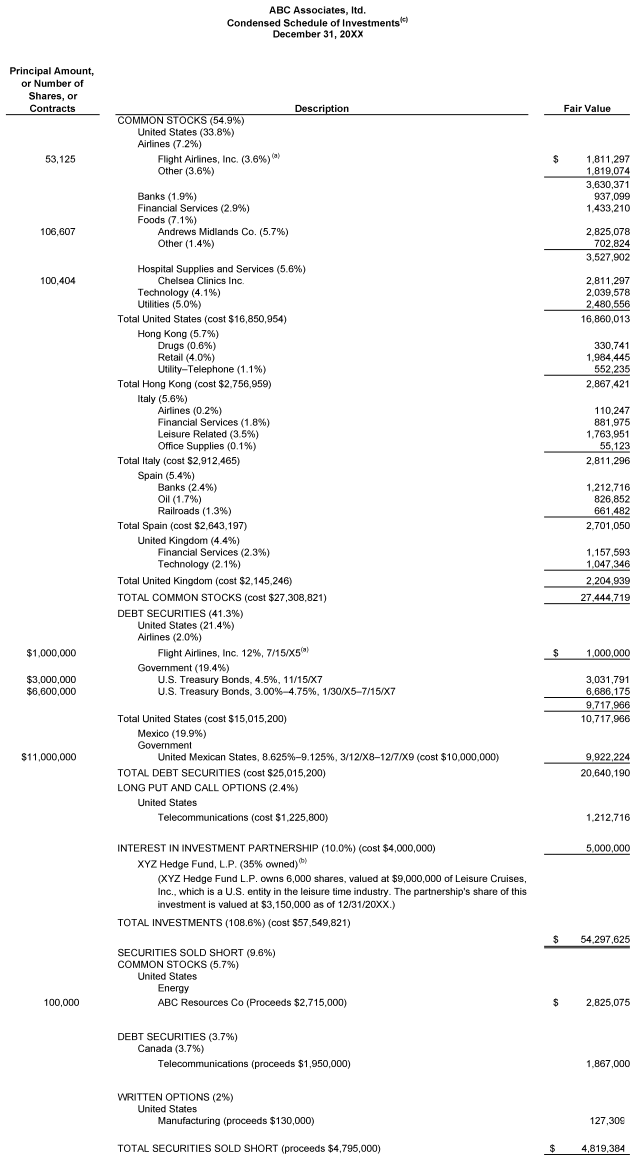 "ABC Associates, ltd." Condensed Schedule of Investments(c) "December 31, 20XX" "Principal Amount, or Number of Shares, or Contracts" Description Fair Value COMMON STOCKS (54.9%) United States (33.8%) Airlines (7.2%) "53,125 " "Flight Airlines, Inc. (3.6%) (a)" " $1,811,297 " Other (3.6%) " 1,819,074 " " 3,630,371 " Banks (1.9%) " 937,099 " Financial Services (2.9%) " 1,433,210 " Foods (7.1%) "106,607 " Andrews Midlands Co. (5.7%) " 2,825,078 " Other (1.4%) " 702,824 " " 3,527,902 " Hospital Supplies and Services (5.6%) "100,404 " Chelsea Clinics Inc. " 2,811,297 " Technology (4.1%) " 2,039,578 " Utilities (5.0%) " 2,480,556 " "Total United States (cost $16,850,954)" " 16,860,013 " Hong Kong (5.7%) Drugs (0.6%) " 330,741 " Retail (4.0%) " 1,984,445 " Utility-Telephone (1.1%) " 552,235 " "Total Hong Kong (cost $2,756,959) " " 2,867,421 " Italy (5.6%) Airlines (0.2%) " 110,247 " Financial Services (1.8%) " 881,975 " Leisure Related (3.5%) " 1,763,951 " Office Supplies (0.1%) " 55,123 " "Total Italy (cost $2,912,465) " " 2,811,296 " Spain (5.4%) Banks (2.4%) " 1,212,716 " Oil (1.7%) " 826,852 " Railroads (1.3%) " 661,482 " "Total Spain (cost $2,643,197) " " 2,701,050 " United Kingdom (4.4%) Financial Services (2.3%) " 1,157,593 " Technology (2.1%) " 1,047,346 " "Total United Kingdom (cost $2,145,246)" " 2,204,939 " "TOTAL COMMON STOCKS (cost $27,308,821)" " 27,444,719 " DEBT SECURITIES (41.3%) United States (21.4%) Airlines (2.0%) " $1,000,000 " "Flight Airlines, Inc. 12%, 7/15/X5 (a)" " $1,000,000 " Government (19.4%) " $3,000,000 " "U.S. Treasury Bonds, 4.5%, 11/15/X7 " " 3,031,791 " " $6,600,000 " "U.S. Treasury Bonds, 3.00%-4.75%, 1/30/X5-7/15/X7 " " 6,686,175 " " 9,717,966 " "Total United States (cost $15,015,200)" " 10,717,966 " Mexico (19.9%) Government " $11,000,000 " "United Mexican States, 8.625%-9.125%, 3/12/X8-12/7/X9 (cost $10,000,000) " " 9,922,224 " "TOTAL DEBT SECURITIES (cost $25,015,200)" " 20,640,190 " LONG PUT AND CALL OPTIONS (2.4%) United States "Telecommunications (cost $1,225,800) " " 1,212,716 " "INTEREST IN INVESTMENT PARTNERSHIP (10.0%) (cost $4,000,000) " " 5,000,000 " "XYZ Hedge Fund, L.P. (35% owned) (b)" "(XYZ Hedge Fund L.P. owns 6,000 shares, valued at $9,000,000 of Leisure Cruises, Inc., which is a U.S. entity in the leisure time industry. The partnership's share of this investment is valued at $3,150,000 as of 12/31/20XX.) " "TOTAL INVESTMENTS (108.6%) (cost $57,549,821) " " $54,297,625 " SECURITIES SOLD SHORT (9.6%) COMMON STOCKS (5.7%) United States Energy " 100,000 " "ABC Resources Co (Proceeds $2,715,000)" " $2,825,075 " DEBT SECURITIES (3.7%) Canada (3.7%) "Telecommunications (proceeds $1,950,000)" " 1,867,000 " WRITTEN OPTIONS (2%) United States "Manufacturing (proceeds $130,000) " " 127,309 " "TOTAL SECURITIES SOLD SHORT (proceeds $4,795,000) " " $4,819,384 "
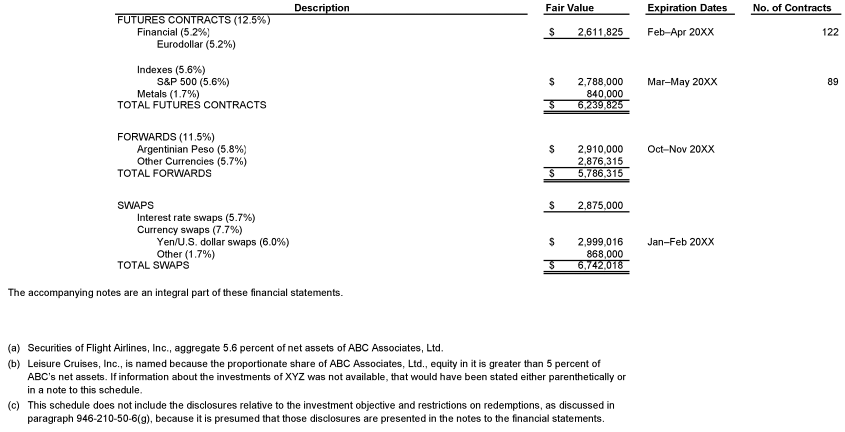 Description Fair Value Expiration Dates No. of Contracts FUTURES CONTRACTS (12.5%) Financial (5.2%) " $2,611,825 " Feb-Apr 20XX 122 Eurodollar (5.2%) Indexes (5.6%) S 500 (5.6%) " 2,788,000 " Mar-May 20XX 89 Metals (1.7%) " 840,000 " TOTAL FUTURES CONTRACTS " $6,239,825 " FORWARDS (11.5%) Argentinian Peso (5.8%) " $2,910,000 " Oct-Nov 20XX Other Currencies (5.7%) " 2,876,315 " TOTAL FORWARDS " $5,786,315 " SWAPS " $2,875,000 " Interest rate swaps (5.7%) Currency swaps (7.7%) Yen/U.S. dollar swaps (6.0%) " 2,999,016 " Jan-Feb 20XX Other (1.7%) " 868,000 " TOTAL SWAPS " $6,742,018 " The accompanying notes are an integral part of these financial statements. (a) "Securities of Flight Airlines, Inc., aggregate 5.6 percent of net assets of ABC Associates, Ltd." (b) "Leisure Cruises, Inc., is named because the proportionate share of ABC Associates, Ltd., equity in it is greater than 5 percent of ABC's net assets. If information about the investments of XYZ was not available, that would have been stated either parenthetically or in a note to this schedule." (c) "This schedule does not include the disclosures relative to the investment objective and restrictions on redemptions, as discussed in paragraph 946-210-50-6(g), because it is presumed that those disclosures are presented in the notes to the financial statements."
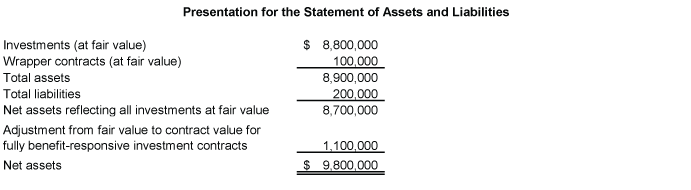 Presentation for the Statement of Assets and Liabilities Investments (at fair value) " $8,800,000 " Wrapper contracts (at fair value) " 100,000 " Total assets " 8,900,000 " Total liabilities " 200,000 " Net assets reflecting all investments at fair value " 8,700,000 " Adjustment from fair value to contract value for fully benefit-responsive investment contracts " 1,100,000 " Net assets " $9,800,000 "
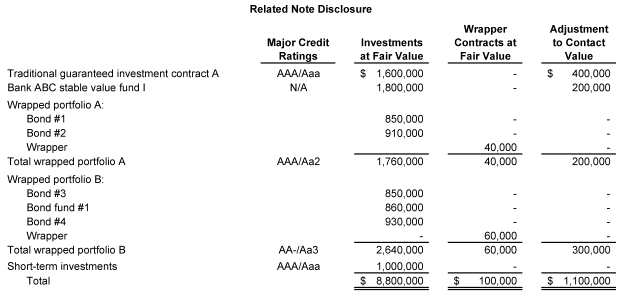 Related Footnote Disclosure Major Credit Ratings Investments at Fair Value Wrapper Contracts at Fair Value Adjustment to Contact Value Traditional guaranteed investment contract A AAA/Aaa " $1,600,000 " - " $400,000 " Bank ABC stable value fund I N/A " 1,800,000 " - " 200,000 " Wrapped portfolio A: Bond #1 " 850,000 " - - Bond #2 " 910,000 " - - Wrapper " 40,000 " - Total wrapped portfolio A AAA/Aa2 " 1,760,000 " " 40,000 " " 200,000 " Wrapped portfolio B: Bond #3 " 850,000 " - - Bond fund #1 " 860,000 " - - Bond #4 " 930,000 " - - Wrapper - " 60,000 " - Total wrapped portfolio B AA-/Aa3 " 2,640,000 " " 60,000 " " 300,000 " Short-term investments AAA/Aaa " 1,000,000 " - - Total " $8,800,000 " " $100,000 " " $1,100,000 "
210-946-S00StatusSEC
Source downloaded: .Record version 0e28393952b2. Effective date must be checked in the source.
| Paragraph | Action | Accounting Standards Update | Date |
| Amended | Accounting Standards Update No. 2019-07 | 07/26/2019 |
210-946-S45Other Presentation MattersSEC
Source downloaded: .Record version 9f4424eb8919. Effective date must be checked in the source.
Certificate Reserves
Balance Sheet Format
Statements of Net Assets Format
Format for Balance Sheets Filed by Issuers of Face-Amount Certificates
210-946-S50DisclosureSEC
Source downloaded: .Record version 294b62771052. Effective date must be checked in the source.
Cash
Notes Payable, Bonds, and Similar Debt
Units of Capital
Statement of Net Assets
Balance Sheets Filed by Issuers of Face-Amount Certificates
210-946-S99SEC MaterialsSEC
Source downloaded: .Record version f290d6acbcd8. Effective date must be checked in the source.
SEC Rules, Regulations, and Interpretations
- This section is applicable to balance sheets filed by registered investment companies and business development companies except for persons who substitute a statement of net assets in accordance with the requirements specified in § 210.6-05, and issuers of face-amount certificates which are subject to the special provisions of § 210.6-06. Balance sheets filed under this rule shall comply with the following provisions:
- ASSETS
- 1. Investments in securities of unaffiliated issuers.
- 2. Investments in and advances to affiliates. State separately investments in and advances to: (a) Controlled companies and (b) other affiliates.
- 3. Other investments. State separately amounts of assets related to
- (a) variation margin receivable on futures contracts,
- (b) forward foreign currency contracts;
- (c) swap contracts; and
- (d) investments—other than those presented in §§210.12-12, 12-12A, 12-12B, 12-13, 12-13A, 12-13B, and 12-13C
- 4. Cash. Include under this caption cash on hand and demand deposits.
- Provide in a note to the financial statements the information required under § 210.5-02.1 regarding restrictions and compensating balances.
- 5. Receivables.
- (a) State separately amounts receivable from
- (1) sales of investments;
- (2) subscriptions to capital shares;
- (3) dividends and interest;
- (4) directors and officers; and
- (5) others.
- (b) If the aggregate amount of notes receivable exceeds 10 percent of the aggregate amount of receivables, the above information shall be set forth separately, in the balance sheet or in a note thereto, for accounts receivable and notes receivable.
- 6. Deposits for securities sold short and other investments. State separately amounts held by others in connection with:
- (a) Short sales;
- (b) open option contracts;
- (c) futures contracts;
- (d) forward foreign currency contracts;
- (e) swap contracts; and
- (f) investments—other than those presented in §§210.12-12, 12-12A, 12-12B, 12-13, 12-13A, 12-13B, and 12-13C.
- 7. Other assets. State separately
- (a) prepaid and deferred expenses;
- (b) pension and other special funds;
- (c) organization expenses; and
- (d) any other significant item not properly classified in another asset caption.
- 8. Total assets.
- LIABILITIES
- 9. Other investments. State separately amounts of liabilities related to:
- (a) Securities sold short;
- (b) open option contracts written;
- (c) variation margin payable on futures contracts;
- (d) forward foreign currency contracts;
- (e) swap contracts; and
- (f) investments—other than those presented in §§210.12-12, 12-12A, 12-12B, 12-13, 12-13A, 12-13B, and 12-13C.
- 10. Accounts payable and accrued liabilities. State separately amounts payable for:
- (a) Other purchases of securities;
- (b) capital shares redeemed;
- (c) dividends or other distributions on capital shares; and
- (d) others.
- State separately the amount of any other liabilities which are material.
- 11. Deposits for securities loaned. State the value of securities loaned and indicate the nature of the collateral received as security for the loan, including the amount of any cash received.
- 12. Other liabilities. State separately
- (a) amounts payable for investment advisory, management and service fees; and
- (b) the total amount payable to:
- (1) Officers and directors;
- (2) controlled companies; and
- (3) other affiliates, excluding any amounts owing to noncontrolled affiliates which arose in the ordinary course of business and which are subject to usual trade terms.
- 13. Notes payable, bonds and similar debt.
- (a) State separately amounts payable to:
- (1) Banks or other financial institutions for borrowings;
- (2) controlled companies;
- (3) other affiliates; and
- (4) others, showing for each category amounts payable within one year and amounts payable after one year.
- (b) Provide in a note the information required under § 210.5-02.19(b) regarding unused lines of credit for short-term financing and § 210.5-02.22(b) regarding unused commitments for long-term financing arrangements.
- 14. Total liabilities.
- 15. Commitments and contingent liabilities.
- NET ASSETS
- 16. Units of capital.
- (a) Disclose the title of each class of capital shares or other capital units, the number authorized, the number outstanding, and the dollar amount thereof.
- (b) Unit investment trusts, including those which are issuers of periodic payment plan certificates, also shall state in a note to the financial statements:
- (1) The total cost to the investors of each class of units or shares;
- (2) the adjustment for market depreciation or appreciation;
- (3) other deductions from the total cost to the investors for fees, loads and other charges, including an explanation of such deductions; and
- (4) the net amount applicable to the investors.
- 17. Total distributable earnings (loss). Disclose total distributable earnings (loss), which generally comprise:
- (a) Accumulated undistributed investment income-net,
- (b) accumulated undistributed net realized gains (losses) on investment transactions, and
- (c) net unrealized appreciation (depreciation) in value of investments at the balance sheet date.
- 18. Other elements of capital. Disclose any other elements of capital or residual interests appropriate to the capital structure of the reporting entity.
- 19. Net assets applicable to outstanding units of capital. State the net asset value per share.
- In lieu of the balance sheet otherwise required by § 210.6-04, persons may substitute a statement of net assets if at least 95 percent of the amount of the person's total assets are represented by investments in securities of unaffiliated issuers. If presented in such instances, a statement of net assets shall consist of the following:
- STATEMENTS OF NET ASSETS
- 1. A schedule of investments in securities of unaffiliated issuers as prescribed in § 210.12-12.
- 2. The excess (or deficiency) of other assets over (under) total liabilities stated in one amount, except that any amounts due from or to officers, directors, controlled persons, or other affiliates, excluding any amounts owing to noncontrolled affiliates which arose in the ordinary course of business and which are subject to usual trade terms, shall be stated separately.
- 3. Disclosure shall be provided in the notes to the financial statements for any item required under §210.6-04.3 and §§210.6-04.9 to 210.6-04.13.
- 4. The balance of the amounts captioned as net assets. The number of outstanding shares and net asset value per share shall be shown parenthetically.
- 5. The information required by (i) § 210.6-04.16, (ii) § 210.6-04.17 and (iii) § 210.6-04.18 shall be furnished in a note to the financial statements.
- Balance sheets filed by issuers of face-amount certificates shall comply with the following provisions:
- ASSETS
- 1. Investments. State separately each major category: such as, real estate owned, first mortgage loans on real estate, other mortgage loans on real estate, investments in securities of unaffiliated issuers, and investments in and advances to affiliates.
- 2. Cash. Include under this caption cash on hand and demand deposits. Provide in a note to the financial statements the information required under § 210.5-02.1 regarding restrictions and compensating balances.
- 3. Receivables.
- (a) State separately amounts receivable from
- (1) sales of investments;
- (2) dividends and interest;
- (3) directors and officers; and
- (4) others.
- (b) If the aggregate amount of notes receivable exceeds 10 percent of the aggregate amount of receivables, the above information shall be set forth separately, in the balance sheet or in a note thereto, for accounts receivable and notes receivable.
- 4. Total qualified assets. State in a note to the financial statements the amount of qualified assets on deposit classified as to general categories of assets and as to general types of depositories, such as banks and states, together with a statement as to the purpose of the deposits.
- 5. Other assets. State separately:
- (a) Investments in securities of unaffiliated issuers not included in qualifying assets in item 1 above;
- (b) investments in and advances to affiliates not included in qualifying assets in item 1 above; and
- (c) any other significant item not properly classified in another asset caption.
- 6. Total assets.
- LIABILITIES
- 7. Certificate reserves. Issuers of face-amount certificates shall state separately reserves for:
- (a) Certificates of the installment type;
- (b) certificates of the fully-paid type;
- (c) advance payments;
- (d) additional amounts accrued for or credited to the account of certificate holders in the form of any credit, dividend, or interest in addition to the minimum amount specified in the certificate; and
- (e) other certificate reserves.
- State in an appropriate manner the basis used in determining the reserves, including the rates of interest of accumulation.
- 8. Notes payable, bonds and similar debt.
- (a) State separately amounts payable to:
- (1) Banks or other financial institutions for borrowings;
- (2) controlled companies;
- (3) other affiliates; and
- (4) others, showing for each category amounts payable within one year and amounts payable after one year.
- (b) Provide in a note the information required under § 210.5-02.19(b) regarding unused lines of credit for short-term financing and § 210.5-02.22(b) regarding unused commitments for long-term financing arrangements.
- 9. Accounts payable and accrued liabilities. State separately
- (a) amounts payable for investment advisory, management and service fees; and
- (b) the total amount payable to:
- (1) Officers and directors;
- (2) controlled companies; and
- (3) other affiliates, excluding any amounts owing to noncontrolled affiliates which arose in the ordinary course of business and which are subject to usual trade terms.
- State separately the amount of any other liabilities which are material.
- 10. Total liabilities.
- 11. Commitments and contingent liabilities.
- STOCKHOLDERS' EQUITY
- 12. Capital shares. Disclose the title of each class of capital shares or other capital units, the number authorized, the number outstanding and the dollar amount thereof. Show also the dollar amount of any capital shares subscribed but unissued, and show the deduction for subscriptions receivable therefrom.
- 13. Other elements of capital.
- (a) Disclose any other elements of capital or residual interests appropriate to the capital structure of the reporting entity.
- (b) A summary of each account under this caption setting forth the information prescribed in § 210.3-04 shall be given in a note or separate statement for each period in which a statement of operations is presented.
- 14. Total liabilities and stockholders' equity.
Related subtopics
- 220-946 Financial Services—Investment CompaniesIncome Statement—Reporting Comprehensive Income
- 210-942 Financial Services—Depository and LendingBalance Sheet
- 205-946 Financial Services—Investment CompaniesPresentation of Financial Statements
- 946-10 OverallFinancial Services—Investment Companies
- 210-944 Financial Services—InsuranceBalance Sheet
- 205-962 Plan Accounting—Defined Contribution Pension PlansPresentation of Financial Statements