ASC 220-954
Health Care Entities
220 Income Statement—Reporting Comprehensive Income
Source downloaded: .Record version 5317171da8cc. Effective date must be checked in the source.
This Subtopic governs how not-for-profit, business-oriented health care entities present their statement of operations and statement of changes in net assets. Its central requirement is a clearly labeled "performance indicator" (e.g., revenues over expenses) reported in a statement that also shows total changes in net assets without donor restrictions, with a specified list of items — such as equity transfers, donor-restricted contributions, other comprehensive income items, and unrealized gains/losses on non-trading debt securities — required to be reported outside that indicator.
Key points (7)
- The guidance applies only to not-for-profit, business-oriented health care entities (220-954-15-2), and the statement of operations may be combined with the statement of changes in equity (net assets) (220-954-45-1).
- The statement of operations must include a performance indicator that is clearly labeled with a descriptive term such as revenues over expenses or performance earnings, presented in a statement that also shows total changes in net assets without donor restrictions (220-954-45-5).
- Paragraph 220-954-45-8 lists items reported separately from (outside) the performance indicator, including owner transactions, equity transfers with controlled/controlling/common-control entities, receipt of donor-restricted contributions, contributions of and assets released for long-lived assets, other comprehensive income items under 220-10-45-10A, donor- or law-restricted investment returns, inherent contributions increasing net assets with donor restrictions, and instrument-specific credit risk changes under 825-10-45-5.
- Unrestricted investment return inside the performance indicator includes dividend and interest income, realized gains and losses, unrealized gains/losses on trading debt securities, credit loss expense, and unrealized gains/losses and impairments on Topic 321 equity investments; unrealized gains and losses on non-trading debt securities are excluded (220-954-45-9).
- Increases in net assets from services received from personnel of an affiliate that are not charged to the recipient are reported as equity transfers regardless of the affiliate's status, while the related expense or asset is reported like other such expenses or assets (220-954-45-3); equity transfers are excluded from the performance indicator and create no step-up in basis (220-954-45-2).
- Functional expense classification groups costs by purpose into program services and supporting activities, with the extent of subclassification depending on the entity's nature and complexity, and allocations based on full cost allocations (220-954-45-4).
- The notes must describe the nature and composition of the performance indicator (220-954-50-1), and if an intermediate measure of operations is reported and its use is not apparent, the notes must describe the measure or the items excluded from operations (220-954-50-2).
For students. The performance indicator is the NFP health care analogue of "net income," and exam questions almost always test which items fall outside it; the most common error is treating all unrealized gains as excluded — unrealized gains on trading debt securities and on Topic 321 equity investments are inside the indicator, only non-trading debt security unrealized gains are outside.
Machine-generated study aid for ASC 220-954. Check the source paragraphs below.
220-954-00Status
Source downloaded: .Record version 7bcf5bf523df. Effective date must be checked in the source.
220-954-05Overview and Background
Source downloaded: .Record version 7012b417e47b. Effective date must be checked in the source.
220-954-15Scope and Scope Exceptions
Source downloaded: .Record version b61861f8e5e2. Effective date must be checked in the source.
Overall Guidance
Entities
220-954-45Other Presentation Matters
Source downloaded: .Record version 6ce29bf76252. Effective date must be checked in the source.
Statement of Activities
Equity Transfers
Functional Allocations
Performance Indicator and Intermediate Operating Measures
- aTransactions with owners acting in that capacity.
- bEquity transfers involving other entities that control the reporting entity, are controlled by the reporting entity, or are under common control with the reporting entity.
- cReceipt of donor-restricted contributions.
- dContributions of, and assets released from donor restrictions related to, long-lived assets.
- eItems that are required to be reported in or reclassified from other comprehensive income in accordance with paragraph 220-10-45-10A, which includes, but is not limited to, gains or losses, prior service costs or credits, and transition assets or obligations recognized in accordance with Topic 715; foreign currency translation adjustments; the portion of the gain or loss on derivative instruments designated and qualifying as cash flow hedging instruments included in the assessment of effectiveness, and for all qualifying hedging relationships amounts excluded from the assessment of effectiveness and recognized in earnings through an amortization approach in accordance with paragraph 815-20-25-83A.
- fItems that are required to be reported separately under specialized not-for-profit standards.
- gUnrealized gains and losses on investments on other than trading debt securities, in accordance with paragraph 954-220-45-9.
- hInvestment returns restricted by donors or by law.
- i
- j
- kAn inherent contribution (see paragraph 958-805-25-31) that increases net assets with donor restrictions, as described in paragraph 954-805-45-2.
- lThe portion of the total change in the fair value of the liability resulting from a change in the instrument-specific credit risk, in accordance with paragraph 825-10-45-5.
- aIncluded in the performance indicator are:
- 1Dividend, interest, and other similar investment income
- 2Realized gains and losses
- 3Unrealized gains and losses on trading debt securities (trading securities are defined in Topic 320)
- 4Credit loss expense (see Topic 326)
- 5Unrealized gains and losses and impairments on equity investments accounted for under Topic 321.
- 1
- bExcluded from the performance indicator are unrealized gains and losses on debt securities, unless the debt security is a trading debt security.
220-954-50Disclosure
Source downloaded: .Record version d63980305f35. Effective date must be checked in the source.
Performance Indicator and Intermediate Operating Measures
220-954-55Implementation Guidance and Illustrations
Source downloaded: .Record version b8bfe576bbcc. Effective date must be checked in the source.
Illustrations
- Entry at the end of Year 1 to adjust the recorded value of the securities to fair value.
-
 Investments $200 Change in net unrealized gains and losses on investments $200
-
- Entry at the end of Year 2 to record the sale of the securities.
-
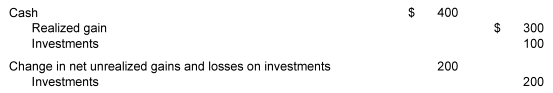 Cash $400 Realized gain $300 Investments 100 Change in net unrealized gains and losses on investments 200 Investments 200
-
-
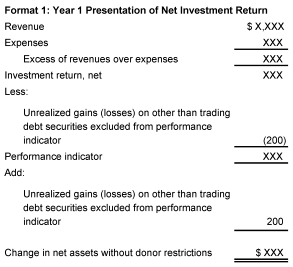 Format 1: Year 1 Presentation of Net Investment Return Revenue " $ X,XXX " Expenses XXX Excess of revenues over expenses XXX "Investment return, net" XXX Less: Unrealized gains (losses) on other than trading debt securities excluded from performance indicator (200) Performance indicator XXX Add: Unrealized gains (losses) on other than trading debt securities excluded from performance indicator 200 Change in net assets without donor restrictions $ XXX
-
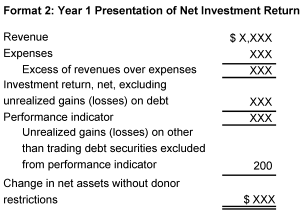 Format 2: Year 1 Presentation of Net Investment Return Revenue " $ X,XXX " Expenses XXX Excess of revenues over expenses XXX "Investment return, net, excluding unrealized gains (losses) on debt securities (other than trading)" XXX Performance indicator XXX Unrealized gains (losses) on other than trading debt securities excluded from performance indicator 200 Change in net assets without donor restrictions $ XXX
Related subtopics
- 220-958 Not-for-Profit EntitiesIncome Statement—Reporting Comprehensive Income
- 325-958 Not-for-Profit EntitiesInvestments—Other
- 320-958 Not-for-Profit EntitiesInvestments—Debt Securities
- 205-958 Not-for-Profit EntitiesPresentation of Financial Statements
- 815-954 Health Care EntitiesDerivatives and Hedging
- 810-954 Health Care EntitiesConsolidation