ASC

ASC 605-958

Not-for-Profit Entities

605 Revenue Recognition

Source downloaded: .Record version 2766135dbcf4. Effective date must be checked in the source.

ASC 958-605 governs revenue recognition by not-for-profit entities, principally contributions received. Its core rules are (1) distinguishing contributions (no commensurate value to the resource provider) from exchange transactions accounted for under Topic 606, (2) recognizing unconditional contributions as revenue or gains at fair value when received while conditional contributions (a barrier plus a right of return/release) are deferred as refundable advances until the barrier is substantially met, and (3) classifying contributions as with or without donor restrictions. It also covers agency-type transfers where an NFP recipient acts as intermediary, agent, or trustee for a donor and a specified third-party beneficiary.

Key points (7)
  • Contributions received are recognized as revenues or gains in the period received (revenues if part of ongoing major or central activities, gains if peripheral) and measured at fair value (958-605-25-2; 958-605-30-2).
  • Whether a transfer is a contribution or an exchange turns on whether the resource provider receives commensurate value; indirect or public benefit, mission execution, and donor sentiment are not commensurate value, and the type of resource provider (including government) is irrelevant (958-605-15-5A).
  • A donor-imposed condition requires both (a) one or more barriers to be overcome and (b) a right of return of assets or right of release from obligation; barrier indicators include measurable performance-related barriers, limited discretion over the conduct of an activity, and stipulations related to the purpose of the agreement (958-605-25-5A through 25-5D).
  • Ambiguous stipulations that are not clearly unconditional are presumed conditional, and a conditional transfer is accounted for as a refundable advance until the conditions are substantially met or explicitly waived (958-605-25-5E; 25-5F; 35-2).
  • Contributed services are recognized only if they create or enhance nonfinancial assets or require specialized skills provided by persons possessing those skills that would otherwise be purchased (958-605-25-16); contributed collection items need not be recognized if collections are not capitalized (958-605-25-19).
  • Contributions with donor-imposed restrictions increase net assets with donor restrictions, while exchange revenues and gifts of long-lived assets without use-period stipulations go to net assets without donor restrictions, and promises due in future periods are presumed donor-restricted (958-605-45-1, 45-3, 45-5, 45-6).
  • A recipient entity acting as agent, trustee, or intermediary recognizes a liability to the specified beneficiary rather than contribution revenue unless granted explicit variance power or financially interrelated with the beneficiary (958-605-25-24 through 25-27; 45-9), and contributed nonfinancial assets must be presented separately with the disclosures in 958-605-50-1A.

For students. The most tested distinction is condition versus restriction: a condition (barrier + right of return/release) delays revenue recognition, while a restriction only affects net asset classification. Students commonly err by assuming government grants are always exchange transactions—under 958-605-15-5A the resource provider's identity is irrelevant, and a grant is a contribution unless the grantor itself receives commensurate value.

Machine-generated study aid for ASC 605-958. Check the source paragraphs below.

605-958-00Status

Source downloaded: .Record version 346077d24426. Effective date must be checked in the source.

605-958-00-1
The following table identifies the changes made to this Subtopic.
ParagraphActionAccounting Standards UpdateDate
AffiliateAmendedMaintenance Update 2018-12 (PDF)09/10/2018
Agency TransactionAddedAccounting Standards Update No. 2015-1006/12/2015
Agency Transactions (Not for Profits)SupersededAccounting Standards Update No. 2015-1006/12/2015
Board-Designated Endowment FundAmendedAccounting Standards Update No. 2016-1408/18/2016
CollectionsAmendedAccounting Standards Update No. 2019-0303/21/2019
Conditional ContributionAddedAccounting Standards Update No. 2018-0806/21/2018
Conditional Promise to GiveAmendedAccounting Standards Update No. 2018-0806/21/2018
ContractAddedAccounting Standards Update No. 2014-0905/28/2014
ContributionAmendedAccounting Standards Update No. 2018-0806/21/2018
ContributionAmendedAccounting Standards Update No. 2010-0701/28/2010
Contributions ReceivableAddedAccounting Standards Update No. 2016-1408/18/2016
Control (1st def.)SupersededAccounting Standards Update No. 2015-1006/12/2015
CustomerAddedAccounting Standards Update No. 2014-0905/28/2014
Donor-Imposed ConditionAmendedAccounting Standards Update No. 2018-0806/21/2018
Donor-Imposed RestrictionAmendedAccounting Standards Update No. 2016-1408/18/2016
Donor-Restricted Endowment FundAddedAccounting Standards Update No. 2016-1408/18/2016
Donor-Restricted SupportAddedAccounting Standards Update No. 2016-1408/18/2016
Endowment FundAmendedAccounting Standards Update No. 2016-1408/18/2016
Environmental CreditAddedAccounting Standards Update No. 2026-0205/19/2026
Environmental Credit ObligationAddedAccounting Standards Update No. 2026-0205/19/2026
Equity Security (1st def.)AmendedAccounting Standards Update No. 2016-0101/05/2016
ExchangeAddedAccounting Standards Update No. 2025-1012/04/2025
Financial Asset (2nd def.)AmendedAccounting Standards Update No. 2016-1912/14/2016
Funds Functioning as EndowmentAddedAccounting Standards Update No. 2016-1408/18/2016
Government GrantAddedAccounting Standards Update No. 2025-1012/04/2025
Income TaxesAddedAccounting Standards Update No. 2026-0205/19/2026
Monetary AssetsAddedAccounting Standards Update No. 2025-1012/04/2025
Most Advantageous MarketAddedAccounting Standards Update No. 2020-0709/17/2020
Net AssetsAddedAccounting Standards Update No. 2016-1408/18/2016
Net Assets with Donor RestrictionsAddedAccounting Standards Update No. 2016-1408/18/2016
Net Assets without Donor RestrictionsAddedAccounting Standards Update No. 2016-1408/18/2016
Nonreciprocal Transfer (1st def.)AddedAccounting Standards Update No. 2026-0205/19/2026
Permanent EndowmentSupersededAccounting Standards Update No. 2016-1408/18/2016
Permanent RestrictionSupersededAccounting Standards Update No. 2016-1408/18/2016
Permanently Restricted Net AssetsSupersededAccounting Standards Update No. 2016-1408/18/2016
Principal MarketAddedAccounting Standards Update No. 2020-0709/17/2020
ReclassificationSupersededAccounting Standards Update No. 2016-1408/18/2016
Reclassification of Net AssetsAddedAccounting Standards Update No. 2016-1408/18/2016
Restricted SupportSupersededAccounting Standards Update No. 2016-1408/18/2016
RevenueAddedAccounting Standards Update No. 2014-0905/28/2014
Temporarily Restricted Net AssetsSupersededAccounting Standards Update No. 2016-1408/18/2016
Unrestricted Net AssetsSupersededAccounting Standards Update No. 2016-1408/18/2016
Unrestricted SupportSupersededAccounting Standards Update No. 2016-1408/18/2016
958-605-05-1AmendedAccounting Standards Update No. 2014-0905/28/2014
958-605-05-2AmendedAccounting Standards Update No. 2014-0905/28/2014
958-605-15-2AAddedAccounting Standards Update No. 2018-0806/21/2018
AmendedAccounting Standards Update No. 2018-0806/21/2018
958-605-15-5AAddedAccounting Standards Update No. 2018-0806/21/2018
958-605-15-6AmendedAccounting Standards Update No. 2026-0205/19/2026
958-605-15-6AmendedAccounting Standards Update No. 2025-1012/04/2025
958-605-15-7AAddedAccounting Standards Update No. 2018-0806/21/2018
958-605-15-13AddedAccounting Standards Update No. 2016-1912/14/2016
958-605-25-1AmendedAccounting Standards Update No. 2018-0806/21/2018
958-605-25-1AmendedAccounting Standards Update No. 2014-0905/28/2014
958-605-25-2AmendedAccounting Standards Update No. 2018-0806/21/2018
958-605-25-2AAddedAccounting Standards Update No. 2018-0806/21/2018
AddedAccounting Standards Update No. 2018-0806/21/2018
958-605-25-11AmendedAccounting Standards Update No. 2018-0806/21/2018
958-605-25-12SupersededAccounting Standards Update No. 2018-0806/21/2018
958-605-25-13AmendedAccounting Standards Update No. 2018-0806/21/2018
958-605-25-14SupersededAccounting Standards Update No. 2018-0806/21/2018
958-605-25-17AmendedAccounting Standards Update No. 2013-0604/19/2013
958-605-25-23AmendedAccounting Standards Update No. 2016-1408/18/2016
958-605-25-24AmendedAccounting Standards Update No. 2016-1408/18/2016
958-605-25-33AmendedAccounting Standards Update No. 2015-1006/12/2015
958-605-30-3AmendedAccounting Standards Update No. 2011-0405/12/2011
958-605-35-3AmendedAccounting Standards Update No. 2012-0410/01/2012
958-605-45-1AmendedAccounting Standards Update No. 2016-1408/18/2016
958-605-45-2SupersededAccounting Standards Update No. 2014-0905/28/2014
AmendedAccounting Standards Update No. 2016-1408/18/2016
958-605-45-4AmendedAccounting Standards Update No. 2018-0806/21/2018
958-605-45-4AmendedAccounting Standards Update No. 2016-0101/05/2016
958-605-45-4AAddedAccounting Standards Update No. 2018-0806/21/2018
958-605-45-4BAddedAccounting Standards Update No. 2018-0806/21/2018
958-605-45-7AAddedAccounting Standards Update No. 2020-0709/17/2020
958-605-50-1SupersededAccounting Standards Update No. 2020-0709/17/2020
958-605-50-1AAddedAccounting Standards Update No. 2020-0709/17/2020
958-605-50-1BAddedAccounting Standards Update No. 2020-0709/17/2020
958-605-50-2AmendedAccounting Standards Update No. 2016-1408/18/2016
958-605-50-3SupersededAccounting Standards Update No. 2016-1408/18/2016
958-605-55-1AmendedAccounting Standards Update No. 2015-1006/12/2015
958-605-55-1AAddedAccounting Standards Update No. 2018-0806/21/2018
958-605-55-2AAmendedAccounting Standards Update No. 2018-0806/21/2018
958-605-55-3SupersededAccounting Standards Update No. 2018-0806/21/2018
958-605-55-3AAddedAccounting Standards Update No. 2018-0806/21/2018
958-605-55-4AmendedAccounting Standards Update No. 2018-0806/21/2018
958-605-55-6AmendedAccounting Standards Update No. 2012-0410/01/2012
958-605-55-7AmendedAccounting Standards Update No. 2018-0806/21/2018
958-605-55-8SupersededAccounting Standards Update No. 2018-0806/21/2018
958-605-55-8AmendedAccounting Standards Update No. 2016-1912/14/2016
958-605-55-13AAddedAccounting Standards Update No. 2018-0806/21/2018
958-605-55-14AmendedAccounting Standards Update No. 2018-0806/21/2018
AddedAccounting Standards Update No. 2018-0806/21/2018
AmendedAccounting Standards Update No. 2018-0806/21/2018
AddedAccounting Standards Update No. 2018-0806/21/2018
958-605-55-21AmendedAccounting Standards Update No. 2018-0806/21/2018
AmendedAccounting Standards Update No. 2016-1408/18/2016
958-605-55-25SupersededAccounting Standards Update No. 2025-1212/17/2025
958-605-55-34AmendedAccounting Standards Update No. 2016-1408/18/2016
958-605-55-37AmendedAccounting Standards Update No. 2016-1408/18/2016
958-605-55-38AmendedAccounting Standards Update No. 2016-1408/18/2016
958-605-55-48AmendedAccounting Standards Update No. 2016-1408/18/2016
958-605-55-51AmendedAccounting Standards Update No. 2018-0806/21/2018
AddedAccounting Standards Update No. 2018-0806/21/2018
AddedAccounting Standards Update No. 2020-0709/17/2020
958-605-55-82SupersededAccounting Standards Update No. 2018-0806/21/2018
AmendedAccounting Standards Update No. 2016-1408/18/2016
958-605-55-98AmendedAccounting Standards Update No. 2016-1408/18/2016
958-605-55-100AmendedAccounting Standards Update No. 2016-1408/18/2016
958-605-55-105AmendedAccounting Standards Update No. 2016-1408/18/2016
958-605-55-107AmendedAccounting Standards Update No. 2016-1408/18/2016
958-605-55-110AmendedAccounting Standards Update No. 2016-1408/18/2016
958-605-55-110AmendedAccounting Standards Update No. 2012-0410/01/2012

605-958-05Overview and Background

Source downloaded: .Record version dc8ed38c8e7d. Effective date must be checked in the source.

605-958-05-1
This Subtopic provides guidance on revenue recognition by not-for-profit entities (NFPs). NFPs also shall comply with the applicable standards in Topic 606. The guidance is presented in the following three Subsections:
  1. a
    General
  2. b
    Contributions Received
  3. c
    Transfers of Assets to a Not-for-Profit Entity or Charitable Trust that Raises or Holds Contributions for Others.
605-958-05-2
The General Subsections provide guidance on the presentation of exchange transactions in a statement of activities. They also provide implementation guidance for distinguishing contribution transactions from exchange transactions.

Contributions Received

605-958-05-3
The Contributions Received Subsections establish standards of financial accounting and reporting for contributions received. They also establish standards for collections of works of art, historical treasures, and similar assets acquired by contribution.

Transfers of Assets to a Not-for-Profit Entity or Charitable Trust That Raises or Holds Contributions for Others

605-958-05-4
The Transfers of Assets to a Not-for-Profit Entity or Charitable Trust that Raises or Holds Contributions for Others Subsections provide guidance for transfers of assets for which it may be unclear as to who should report a contribution because a donor uses a recipient entity as its intermediary, agent, or trustee to transfer assets to a third-party donee. Although the transaction between the donor and the donee may be a contribution, in many instances, the transfer of assets from the donor is not a contribution received by the recipient entity, and the transfer of assets to the donee is not a contribution made by the recipient entity.

605-958-15Scope and Scope Exceptions

Source downloaded: .Record version 14d8256a7c74. Effective date must be checked in the source.

Overall Guidance

605-958-15-1
This Subtopic follows the same Scope and Scope Exceptions as outlined in the Overall Subtopic, see Section 958-10-15.
605-958-15-2
The General Subsection of this Section establishes the pervasive scope for this Subtopic, with specific exceptions noted in the other Subsections of this Section.
605-958-15-2A
A business entity shall consider the guidance in this Subtopic when determining whether a transaction is a contribution within the scope of this Subtopic. Additionally, paragraphs and 958-605-55-13A through 55-14I apply to all resource providers, including business entities that act as resource providers.

Contributions Received

605-958-15-3
The Contributions Received Subsections follow the same Scope and Scope Exceptions as outlined in the General Subsection of this Subtopic, see paragraph 958-605-15-1, with specific exceptions noted below.

Entities

605-958-15-4
Accounting for contributions is an issue primarily for not-for-profit entities (NFPs) because contributions received are a significant source of revenues for many of those entities. However, except for Section 958-605-45, the guidance in the Contributions Received Subsections applies to all entities (NFPs and business entities) that receive contributions unless otherwise indicated.

Transactions

605-958-15-5
The guidance in the Contributions Received Subsections applies to the following transactions and activities:
  1. a
    Contributions of cash and other assets, including promises to give, or a reduction, settlement, or cancellation of liabilities.
605-958-15-5A
In determining whether a transfer of assets is an exchange transaction in which a resource provider (for example, a government agency, a foundation, a corporation, or other entity) receives commensurate value in return for the resources transferred or a contribution, the type of resource provider shall not factor into the determination and an entity shall evaluate the terms of an agreement and consider the following (additional clarification is provided in paragraphs and 958-605-55-13A through 55-14I):
  1. a
    The resource provider (including a foundation, a government agency, a corporation, or other entity) is not synonymous with the general public. A benefit received by the public as a result of the assets transferred is not equivalent to commensurate value received by the resource provider. Therefore, if the resource provider receives indirect value in exchange for the assets transferred or if the value received by the resource provider is incidental to the potential public benefit from using the assets transferred, the transaction shall not be considered commensurate value received in return.
  2. b
    Execution of the resource provider's mission or the positive sentiment from acting as a donor shall not constitute commensurate value received by the resource provider for purposes of determining whether the transfer of assets is a contribution or an exchange.
  3. c
    If the expressed intent asserted by both the recipient and the resource provider is to exchange resources for goods or services that are of commensurate value, the transaction shall be indicative of an exchange transaction. The transaction shall be indicative of a contribution if the recipient solicits assets from the resource provider without the intent of exchanging goods or services of commensurate value.
  4. d
    If the resource provider has full discretion in determining the amount of the transferred assets, the transaction shall be indicative of a contribution. If both the recipient and the resource provider agree on the amount of assets transferred in exchange for goods and services that are of commensurate value, the transaction shall be indicative of an exchange transaction.
  5. e
    If the penalties assessed on the recipient for failure to comply with the terms of the agreement are limited to the delivery of assets or services already provided and the return of the unspent amount, the transaction is generally indicative of a contribution. The existence of contractual provisions for economic forfeiture beyond the amount of assets transferred by the resource provider to penalize the recipient for nonperformance generally indicates that the transaction is an exchange of commensurate value.
605-958-15-6
The guidance in the Contributions Received Subsections does not apply to the following transactions and activities:
  1. a
    Transfers of assets that are in substance purchases of goods or services—exchange transactions in which each party receives and sacrifices commensurate value (in accordance with the guidance in paragraph 958-605-15-5A). However, if an entity voluntarily transfers assets to another or performs services for another in exchange for assets of substantially lower value and no unstated rights or privileges are involved, the contribution received that is inherent in that transaction is within the scope of the Contributions Received Subsections.
  2. b
    Transfers of assets in which the reporting entity acts as an agent, trustee, or intermediary, rather than as a donor or donee (see the Transfers of Assets to a Not-for-Profit Entity or Charitable Trust That Raises or Holds Contributions for Others Subsections of this Subtopic).
  3. c
    Tax exemptions, tax incentives, or tax abatements.
  4. d
    Transfers of assets from government entities to business entities.
  5. e
    Transfers of assets (typically from a government entity) that are part of an existing exchange transaction between a recipient and an identified customer. Some examples include payments under Medicare and Medicaid programs, provisions of health care or education services by a government for its employees, and Pell Grants or similar state or local government tuition assistance programs. In those instances, an entity shall apply the applicable guidance (for example, Topic 606 on revenue from contracts with customers) to the underlying transaction with the customer, and the payments from the third parties would be payments on behalf of those customers.
Transition date:(P) December 16, 2027; (N) December 16, 2028Transition guidance:
818-10-65-1The guidance in the Contributions Received Subsections does not apply to the following transactions and activities:
  1. a
    Transfers of assets that are in substance purchases of goods or services—exchange transactions in which each party receives and sacrifices commensurate value (in accordance with the guidance in paragraph 958-605-15-5A). However, if an entity voluntarily transfers assets to another or performs services for another in exchange for assets of substantially lower value and no unstated rights or privileges are involved, the contribution received that is inherent in that transaction is within the scope of the Contributions Received Subsections.
  2. b
    Transfers of assets in which the reporting entity acts as an agent, trustee, or intermediary, rather than as a donor or donee (see the Transfers of Assets to a Not-for-Profit Entity or Charitable Trust That Raises or Holds Contributions for Others Subsections of this Subtopic).
  3. c
    Tax exemptions, tax incentives, or tax abatements.
  4. d
    Transfers of assets from government entities to business entities.
  5. e
    Transfers of assets (typically from a government entity) that are part of an existing exchange transaction between a recipient and an identified customer. Some examples include payments under Medicare and Medicaid programs, provisions of health care or education services by a government for its employees, and Pell Grants or similar state or local government tuition assistance programs. In those instances, an entity shall apply the applicable guidance (for example, Topic 606 on revenue from contracts with customers) to the underlying transaction with the customer, and the payments from the third parties would be payments on behalf of those customers.
  6. f
    Transfers of environmental credits received from a regulator or its designee(s). Subtopic 818-20 provides accounting guidance for environmental credits.
Transition date:(P) December 16, 2028; (N) December 16, 2029Transition guidance:
832-10-65-2The guidance in the Contributions Received Subsections does not apply to the following transactions and activities:
  1. a
    Transfers of assets that are in substance purchases of goods or services—exchange transactions in which each party receives and sacrifices commensurate value (in accordance with the guidance in paragraph 958-605-15-5A). However, if an entity voluntarily transfers assets to another or performs services for another in exchange for assets of substantially lower value and no unstated rights or privileges are involved, the contribution received that is inherent in that transaction is within the scope of the Contributions Received Subsections.
  2. b
    Transfers of assets in which the reporting entity acts as an agent, trustee, or intermediary, rather than as a donor or donee (see the Transfers of Assets to a Not-for-Profit Entity or Charitable Trust That Raises or Holds Contributions for Others Subsections of this Subtopic).
  3. c
    Tax exemptions, tax incentives, or tax abatements.
  4. d
    Transfers of assets from government entities to business entities. Topic 832 provides accounting guidance for government grants received by business entities.
  5. e
    Transfers of assets (typically from a government entity) that are part of an existing exchange transaction between a recipient and an identified customer. Some examples include payments under Medicare and Medicaid programs, provisions of health care or education services by a government for its employees, and Pell Grants or similar state or local government tuition assistance programs. In those instances, an entity shall apply the applicable guidance (for example, Topic 606 on revenue from contracts with customers) to the underlying transaction with the customer, and the payments from the third parties would be payments on behalf of those customers.
605-958-15-7
The Contributions Received Subsections also use terms such as gift and donation to refer to a contribution; however, they generally avoid terms such as awards, grants, sponsorships, and appropriations that often are more broadly used to refer not only to contributions but also to assets transferred in exchange transactions in which the grantor, sponsor, or appropriator expects to receive commensurate value.
605-958-15-7A
Contribution revenue within the scope of this Subtopic can be presented in the financial statements of an entity using different terms (for example, gift, grant, donation, or other terms). While some of those terms are generally not used in this guidance, the term used in the presentation of financial statements to label revenue that is accounted for within the scope of this Subtopic is not a factor in determining whether an agreement is within the scope of this Subtopic.

Transfers of Assets to a Not-for-Profit Entity or Charitable Trust That Raises or Holds Contributions for Others

Overall Guidance

605-958-15-8
The Transfers of Assets to a Not-for-Profit Entity or Charitable Trust that Raises or Holds Contributions for Others Subsections follow the same Scope and Scope Exceptions as outlined in the General Subsection of this Subtopic, see paragraph 958-605-15-1, with specific exceptions noted below.

Entities

605-958-15-9
The guidance in the Transfer of Assets to a Not-for-Profit Entity or Charitable Trust that Raises or Holds Contributions for Others Subsections does not apply to the following entities:
  1. a
    A trustee holding assets on behalf of a specified beneficiary (but paragraphs 958-605-25-29 and 958-605-25-31 establish standards for the beneficiary's reporting of its rights to trust assets—its beneficial interest in the charitable trust).

Transactions

605-958-15-10
The guidance in the Transfers of Assets to a Not-for-Profit Entity or Charitable Trust that Raises or Holds Contributions for Others Subsections applies to the following transactions and activities:
  1. a
    Transactions in which an entity—the donor—makes a contribution by transferring assets to an NFP or charitable trust—the recipient entity—that accepts the assets from the donor and agrees to use those assets on behalf of or transfer those assets, the return on investment of those assets, or both to an unaffiliated entity—the beneficiary—that is specified by the donor. (An unaffiliated beneficiary is a beneficiary other than the donor or its affiliate.)
  2. b
    Transactions that take place in a similar manner to (a) but are not contributions for either of the following reasons:
    1. 1
      The entity that transfers the assets to the recipient entity—the resource provider—is related to the beneficiary in a way that causes the transfer to be reciprocal.
    2. 2
      Conditions imposed by the resource provider or the relationships between the parties make the transfer of assets to the recipient entity revocable or repayable.
605-958-15-11
The types of transferred assets addressed by the preceding paragraph are cash and other assets, including securities, land, buildings, use of facilities or utilities, materials and supplies, intangible assets, services, and unconditional promises to give those items in the future.
605-958-15-12
If the transfer of assets is not a contribution or not yet a contribution, the Transfers of Assets to a Not-for-Profit Entity or Charitable Trust that Raises or Holds Contributions for Others Subsections use the term resource provider rather than the term donor to refer to the entity that transfers the assets to the recipient entity.
605-958-15-13
Paragraph 958-605-05-4 applies to transfers to affiliates only if the affiliate recipient entity is not the beneficiary of the transferred assets.

605-958-25Recognition

Source downloaded: .Record version fae030e46398. Effective date must be checked in the source.

605-958-25-1
Exchange transactions shall be accounted for in accordance with other applicable Topics, such as Topic 606 on revenue from contracts with customers.

Contributions Received

605-958-25-2
Except as provided in paragraphs (related to contributed services, works of art, historical treasures, and similar items), contributions received shall be recognized as revenues or gains in the period received and as assets, decreases of liabilities, or expenses depending on the form of the benefits received. The classification of contributions received as revenues or gains depends on whether the transactions are part of the NFP's ongoing major or central activities (revenues), or are peripheral or incidental to the NFP (gains). A contribution made and a corresponding contribution received generally are recognized by both the donor and the donee at the same time, that is, when made or received, respectively, or if conditional, when the barrier is overcome. The definition of a contribution encompasses both a transfer of cash or other assets to an entity and a reduction, settlement, or cancellation of its liabilities.
605-958-25-2A
After a contribution has been deemed not to contain a donor-imposed condition (see paragraphs ), an entity shall consider whether the contribution includes a donor-imposed restriction, which includes the consideration about how broad or narrow the purpose of the agreement is and whether the resources can be used only after a specified date.
605-958-25-3
Donor-imposed restrictions place limits on the use of contributed resources and may affect an entity's performance and its ability to provide services. However, limitations on the use of donated resources do not change the fundamental nature of the contribution transaction or conclusions about when to recognize the underlying event.
605-958-25-4
A major uncertainty about the existence of value may indicate that an item received or given should not be recognized. For example, a gift of clothing or furniture has no value unless it can be utilized in either of the following ways:
  1. a
    Used internally by the not-for-profit entity (NFP) or for program purposes
  2. b
    Sold by the NFP.
If an item is accepted solely to be saved for its potential future use in scientific or educational research and has no alternative use, it may have uncertain value, or perhaps no value, and shall not be recognized. For example, contributions of flora, fauna, photographs, and objects that are identified with historic persons, places, or events often have no value or have highly restricted alternative uses.
605-958-25-5
However, contributed tangible property worth accepting generally possesses the common characteristic of all assets—future economic benefit or service potential. The future economic benefit or service potential of a tangible item usually can be obtained by exchanging it for cash or by using it to produce goods or services. Certain forms of contributed resources may be more difficult to measure reliably than others, but the form of the contributed resources alone should not change conclusions about whether to recognize the underlying event.
605-958-25-5A
A donor-imposed condition must have both:
  1. a
    One or more barriers that must be overcome before a recipient is entitled to the assets transferred or promised
  2. b
    A right of return to the contributor for assets transferred (or for a reduction, settlement, or cancellation of liabilities) or a right of release of the promisor from its obligation to transfer assets (or reduce, settle, or cancel liabilities).
605-958-25-5B
For a donor-imposed condition to exist, it must be determinable from the agreement (or another document referenced in the agreement) that a recipient is only entitled to the transferred assets or a future transfer of assets if it has overcome the barrier. An agreement does not need to include the specific phrase right of return or release from obligation; however, an agreement should be sufficiently clear to be able to support a reasonable conclusion about when a recipient would be entitled to the transfer of assets. In the absence of any apparent indication that a recipient is only entitled to the transferred assets or a future transfer of assets if it has overcome a barrier, the agreement shall not be considered to contain a right of return of assets transferred or a right of release from obligation and shall be deemed a contribution without donor-imposed conditions.

Barrier

605-958-25-5C
An entity must evaluate the facts and circumstances of an agreement to determine whether a stipulation represents a barrier that must be overcome before the recipient is entitled to the assets transferred or promised. A barrier often places specific requirements on an organization about the use of the transferred assets to be entitled to those assets. A probability assessment about whether the recipient is likely to meet the stipulation is not a factor when determining whether an agreement contains a barrier. In cases of ambiguous donor stipulations, see paragraph 958-605-25-5E.
605-958-25-5D
The following table contains a list of indicators that may be helpful in determining whether an agreement contains a barrier. Depending on the facts and circumstances, some indicators may be more significant than others, and no single indicator shall be determinative. See paragraphs and for implementation guidance and illustrative examples on determining whether a contribution is conditional.
Indicates a Barrier
Measurable Performance-Related Barrier or Other Measurable Barrier
The agreement includes a measurable performance-related barrier or other measurable barrier.
Measurable performance-related barriers or other measurable barriers often are coupled with a time limitation (for example, indicating that the outcomes are to be achieved within a specified time frame).
Examples of measurable performance-related barriers include a requirement that indicates that a recipient's entitlement to transferred assets is contingent upon the achievement of any of the following:
  1. a
    A specified level of service
  2. b
    An identified number of units of output
  3. c
    A specific outcome.
Other measurable barriers stipulate that a recipient is entitled to the resources if an identified event occurs (for example, a matching requirement).
Limited Discretion by the Recipient on the Conduct of an Activity
The recipient has limited discretion over the manner in which an activity can be conducted. Limited discretion of the recipient is more specific than a donor-imposed restriction. Restrictions limit the use of a contribution to a specific activity or time but do not necessarily place limitations on how the activity is performed. Examples of limited discretion could include a requirement to follow specific guidelines about incurring qualifying expenses, a requirement to hire specific individuals as part of the workforce conducting the activity (such as the hiring of specified employees or an identified professor at a university), and a specific protocol that must be adhered to.
Stipulations That Are Related to the Purpose of the Agreement
The stipulations are related to the purpose of the agreement. Examples could include a requirement for (a) a homeless shelter to provide a specified number of meals to the homeless (also an example of a measurable performance-related barrier), (b) an animal shelter to expand its facility to accommodate a specified number of additional animals, and (c) a research report that summarizes the findings from a grant on gluten-related allergies.
A stipulation that is unrelated to the purpose of the agreement (for example, administrative and trivial stipulations) is not indicative of a barrier.
Administrative and trivial stipulations could include routine reporting such as a requirement to provide (a) an annual report or (b) a report that summarizes the recipient's performance to demonstrate the underlying actions that were taken to meet the barrier(s) specified in the agreement.
For example, a report that indicates the number of meals that a homeless shelter provided to the homeless is typically not a stipulation that would contribute to achieving the purpose of the agreement. Rather, the action of providing a specified number of meals to the homeless would meet the stipulation that is required by a recipient to achieve the purpose of the agreement.
605-958-25-5E
Determining whether a contribution is conditional can be difficult if it contains donor stipulations that do not clearly state whether both:
  1. a
    One or more barriers exist
  2. b
    The right to receive or retain payment or delivery of the promised assets depends on meeting those barriers.
In cases of ambiguous donor stipulations, a contribution containing stipulations that are not clearly unconditional shall be presumed to be a conditional contribution.
605-958-25-5F
A transfer of assets that is a conditional contribution shall be accounted for as a refundable advance until the conditions have been substantially met or explicitly waived by the donor.
605-958-25-6
This Subsection provides additional guidance for the following types of contributed assets:
  1. a
    Promises to give
  2. b
    Contributed services
  3. c
    Works of art, historical treasures, and similar items
  4. d
    Items given for use in fundraising.

Promises to Give

605-958-25-7
The recognition guidance in the Contributions Received Subsections depends on whether the promise to give is unconditional or conditional as follows.
605-958-25-8
Pursuant to paragraph 958-605-25-2, an unconditional promise to give shall be recognized when it is received. However, to be recognized there must be sufficient evidence in the form of verifiable documentation that a promise was made and received.
605-958-25-9
A communication that does not indicate clearly whether it is a promise is considered an unconditional promise to give if it indicates an unconditional intention to give that is legally enforceable. Legal enforceability refers to the availability of legal remedies, not the intent to use them.
605-958-25-10
Solicitations for donations that clearly include wording such as information to be used for budget purposes only or that clearly and explicitly allow resource providers to rescind their indications that they will give are intentions to give rather than promises to give and shall not be reported as contributions.
605-958-25-11
Conditional promises to give, which contain donor-imposed conditions that represent a barrier that must be overcome as well as a right of release from obligation, shall be recognized when the condition or conditions on which they depend are substantially met, that is, when a conditional promise becomes unconditional. Imposing a condition creates a barrier that must be overcome before the recipient is entitled to the assets promised. For example, a promise to contribute cash if a like amount of new gifts is raised from others within 30 days and a provision that the cash will not be transferred if the gifts are not raised impose a condition on which entitlement to a promised gift depends.
605-958-25-13
A transfer of assets after a conditional promise to give is made and before the conditions are met is the same as a transfer of assets that is a conditional contribution (see paragraph 958-605-25-5F). A change in the original conditions of the agreement between promisor and promisee shall not be implied without an explicit waiver (see paragraph 958-605-35-2).
605-958-25-15
Absence of a specified time for transfer of cash or other assets, by itself, does not necessarily lead to a determination that a promise to give is ambiguous. If the parties fail to express the time or place of performance and performance is unconditional, performance within a reasonable time after making a promise is an appropriate expectation; similarly, if a promise is conditional, performance within a reasonable time after fulfilling the condition is an appropriate expectation. Promises to give that are silent about payment terms but otherwise are clearly unconditional shall be accounted for as unconditional promises to give.

Contributed Services

605-958-25-16
Contributions of services shall be recognized if the services received meet any of the following criteria:
  1. a
    They create or enhance nonfinancial assets.
  2. b
    They require specialized skills, are provided by individuals possessing those skills, and would typically need to be purchased if not provided by donation. Services requiring specialized skills are provided by accountants, architects, carpenters, doctors, electricians, lawyers, nurses, plumbers, teachers, and other professionals and craftsmen.
Contributed services and promises to give services that do not meet these criteria shall not be recognized. See Examples 7 through 11 (paragraph ) for illustrations of this guidance.
605-958-25-17
For services received from personnel of an affiliate that directly benefit the recipient NFP and for which the affiliate does not charge the recipient NFP, the guidance in Subtopic 958-720 shall be followed. Charging the recipient NFP means requiring payment from the recipient NFP at least for the approximate amount of the direct personnel costs (for example, compensation and any payroll-related fringe benefits) incurred by the affiliate in providing a service to the recipient NFP or the approximate fair value of that service.

Works of Art, Historical Treasures, and Similar Items

605-958-25-18
Contributions of works of art, historical treasures, and similar items that are not part of a collection shall be recognized as assets and as revenue or gains in financial statements pursuant to paragraph 958-360-25-2.
605-958-25-19
An entity need not recognize contributions of works of art, historical treasures, and similar assets if the donated items are added to collections that meet all three of the criteria in the definition of a collection. Contributed collection items shall be recognized as revenues or gains if collections are capitalized and shall not be recognized as revenues or gains if collections are not capitalized. An entity that does not recognize and capitalize its collections or that capitalizes collections prospectively shall disclose the additional information required by paragraphs 958-360-45-3 and 958-360-45-5.

Items Given for Use in Fundraising

605-958-25-20
NFPs may also receive items, such as tickets, gift certificates, works of art, and merchandise, that are to be used for fundraising purposes by transferring them to other resource providers (the ultimate resource provider or recipient) during fundraising events. Those gifts in kind can be linked to asset transfers from the original resource providers to the ultimate resource providers (recipients) because they are, in substance, part of the same transaction; those gifts in kind shall be reported as contributions and measured at fair value when originally received by an NFP. The difference between the amount received for those items from the ultimate resource providers (recipients) and the fair value of the gifts in kind when originally contributed to the NFP shall be recognized as adjustments to the original contributions when the items are transferred to the ultimate resource providers (recipients).

Transfers of Assets to a Not-for-Profit Entity or Charitable Trust That Raises or Holds Contributions for Others

605-958-25-21
This Subsection provides recognition guidance for the following types of recipients of donated assets:
  1. a
    Intermediaries
  2. b
    Agents
  3. c
    Specified beneficiaries.
605-958-25-22
It also provides guidance for transfers to a recipient entity that are not recognized as contributions because of any of the following conditions:
  1. a
    The transfer is revocable.
  2. b
    The transfer is repayable.
  3. c
    The transfer is reciprocal.

Intermediary

605-958-25-23
If an intermediary receives cash or other financial assets, it shall recognize its liability to the specified beneficiary concurrent with its recognition of the assets received from the donor. If an intermediary receives nonfinancial assets, it is permitted, but not required, to recognize its liability and those assets provided that the intermediary reports consistently from period to period and discloses its accounting policy. While not required, a not-for-profit entity (NFP) may choose to present its individual assets and liabilities by net asset class, in which case those assets and liabilities attributable to the agency transaction would be reported in the net assets without donor restrictionsclass.

Agent

605-958-25-24
Except as described in paragraphs 958-605-25-25 and 958-605-25-27, a recipient entity that accepts assets from a donor and agrees to use those assets on behalf of or transfer those assets, the return on investment of those assets, or both to a specified beneficiary is not a donee. It shall recognize its liability to the specified beneficiary concurrent with its recognition of cash or other financial assets received from the donor. Except as described in those paragraphs, a recipient entity that receives nonfinancial assets is permitted, but not required, to recognize its liability and those assets provided that the recipient entity reports consistently from period to period and discloses its accounting policy. Similar to the guidance in paragraph 958-605-25-23, those assets and liabilities would be reported in the net assets without donor restrictions class.
605-958-25-25
A recipient entity that is directed by a donor to distribute the transferred assets, the return on investment of those assets, or both to a specified unaffiliated beneficiary acts as a donee, rather than an agent, trustee, or intermediary, if the donor explicitly grants the recipient entity variance power—that is, the unilateral power to redirect the use of the transferred assets to another beneficiary.
605-958-25-26
Although variance power has the appearance of being conditional, the asserted condition is not effective for the following reasons:
  1. a
    The condition can be substantially met solely by a declaration of the governing board of the recipient entity that states that a distribution to a specified beneficiary is unnecessary, incapable of fulfillment, or inconsistent with the charitable needs of the community or not-for-profit entities (NFPs) being served.
  2. b
    The variance power is unilateral—exercise of the power does not require approval from the donor, beneficiary, or any other interested party.
A recipient entity that is explicitly granted variance power has the ability to use assets it receives to further its own purpose from the date it accepts the assets. In that situation, the recipient entity shall account for receipt of funds by recognizing an asset and corresponding contribution revenue unless the transfer is revocable, repayable, or reciprocal as described in paragraph 958-605-25-33. Example 10 (see paragraphs ) illustrates a reciprocal transaction in which the NFP transfers assets to a recipient entity and names itself as the specified beneficiary.
605-958-25-27
If a recipient entity and a specified beneficiary are financially interrelated entities and the recipient entity is not a trustee, the recipient entity shall recognize a contribution received when it receives assets (financial or nonfinancial) from the donor that are specified for the beneficiary.

Specified Beneficiary

605-958-25-28
A specified beneficiary shall recognize its rights to the assets (financial or nonfinancial) held by a recipient entity as an asset unless the recipient entity is explicitly granted variance power (see paragraph 958-605-25-25). Those rights are any one of the following:
  1. a
    An interest in the net assets of the recipient entity (see paragraph 958-605-25-32)
  2. b
    A beneficial interest
  3. c
    A receivable.
605-958-25-29
If the beneficiary has an unconditional right to receive all or a portion of the specified cash flows from a charitable trust or other identifiable pool of assets, the beneficiary shall recognize that beneficial interest.
605-958-25-30
If the beneficiary's rights are neither an interest in the net assets of the recipient entity (see paragraph 958-605-25-32) nor a beneficial interest (see the preceding paragraph), a beneficiary shall recognize its rights to the assets held by a recipient entity as a receivable and contribution revenue in accordance with paragraphs and 958-605-45-5 for unconditional promises to give.
605-958-25-31
If the donor explicitly grants a recipient entity variance power, the specified unaffiliated beneficiary shall not recognize its potential for future distributions from the assets held by the recipient entity. Those future distributions, if they occur, shall be recognized as contributions by the specified beneficiary when received or unconditionally promised.
605-958-25-32
Pursuant to paragraph 958-20-25-2, if the beneficiary and the recipient entity are financially interrelated entities, the beneficiary shall recognize its interest in the net assets of the recipient entity. See Subtopic 958-20 for additional information about transactions involving financially interrelated entities.

Transfers That Are Not Contributions Because They Are Revocable, Repayable, or Reciprocal

605-958-25-33
A transfer of assets to a recipient entity is not a contribution and shall be accounted for as an asset by the resource provider and as a liability by the recipient entity if any of the following conditions are present:
  1. a
    The transfer is subject to the resource provider's unilateral right to redirect the use of the assets to another beneficiary.
  2. b
    The transfer is accompanied by the resource provider's conditional promise to give or is otherwise revocable or repayable.
  3. c
    The resource provider controls the recipient entity and specifies an unaffiliated beneficiary. See the definition of control in Subtopic 958-810.
  4. d
    The resource provider specifies itself or its affiliate as the beneficiary and the transfer is not an equity transaction (see paragraph 958-20-25-4).

605-958-30Initial Measurement

Source downloaded: .Record version 82fe80803b0f. Effective date must be checked in the source.

Contributions Received

605-958-30-1
This Subsection provides initial measurement guidance for contributions received, including the following types of contributions:
  1. a
    Unconditional promises to give
  2. b
    Inventory items
  3. c
    Contributed services
  4. d
    Gifts in kind.
605-958-30-2
Contributions received shall be measured at their fair values. Topic 820 establishes a framework for measuring fair value. See the Fair Value Option Subsections of Subtopic 825-10 for guidance about electing at initial recognition to subsequently measure financial instruments and certain other contracts at fair value.
605-958-30-3
Paragraph 820-10-35-2B states that a fair value measurement takes into account the effect of a restriction on the sale or use of an asset if market participants would take into account the effect of the restriction when pricing the asset. Example 6 (see paragraph 820-10-55-51) illustrates that restrictions that are a characteristic of an asset, and, therefore, would transfer to a market participant, are the only restrictions reflected in fair value. Donor restrictions that are specific to the donee are reflected in the classification of net assets, not in the measurement of fair value.

Unconditional Promises to Give

605-958-30-4
If present value techniques are used to measure the fair value of unconditional promises to give, the entity shall determine the amount and timing of the future cash flows of unconditional promises to give cash (or, for promises to give noncash assets, the quantity and nature of assets expected to be received). In making that determination, the entity shall consider all the elements in paragraph 820-10-55-5, including the following:
  1. a
    When the receivable is expected to be collected
  2. b
    The creditworthiness of the other parties
  3. c
    The entity's past collection experience
  4. d
    The entity's policies concerning the enforcement of promises to give
  5. e
    Expectations about possible variations in the amount or timing of the cash flows (that is, the uncertainty inherent in the cash flows)
  6. f
    Other factors concerning the receivable's collectibility.
605-958-30-5
If present value techniques are used to measure fair value, the present value of unconditional promises to give should be measured using a discount rate that is consistent with the general principles for present value measurement discussed in paragraphs . In conformity with paragraph 835-30-25-11, the discount rate shall be determined at the time the unconditional promise to give is initially recognized and shall not be revised subsequently unless the entity has elected to measure the promise to give at fair value in conformity with the Fair Value Option Subsections of Subtopic 825-10.
605-958-30-6
Unconditional promises to give that are expected to be collected in less than one year may be measured at net realizable value because that amount results in a reasonable estimate of fair value.
605-958-30-7
If a promise to give has not previously been recognized as contribution revenue because it was conditional, fair value shall be measured when the conditions are met.
605-958-30-8
A present value technique is one valuation technique for measuring the fair value of an unconditional promise to give noncash assets; other valuation techniques also are available, as described in Topic 820. If present value techniques are used, the fair value of contributions arising from unconditional promises to give noncash assets might be determined based on the present value of the projected fair value of the underlying noncash assets at the date that those assets are expected to be received (that projected fair value is referred to in this Section as the future fair value) and in the quantities that those assets are expected to be received, if the date is one year or more after the financial statement date. Both the likelihood of the promise being fulfilled and the future fair value of those underlying assets, such as the future fair value per share of a promised equity security, should be considered in determining the future amount to be discounted. The quantity, nature, and timing of assets expected to be received, such as the number of shares of a promised equity security, the entity in which those shares represent an equity interest, and when those shares will be received should be considered in determining the likelihood of the promise being fulfilled. In cases in which the future fair value of the underlying asset is difficult to determine, the fair value of an unconditional promise to give noncash assets may be based on the fair value of the underlying asset at the date of initial recognition. No discount for the time value of money shall be reported if an asset's fair value at the date of initial recognition is used to measure the fair value of the contribution.

Inventory Items

605-958-30-9
Inputs for measuring fair value of contributed inventory items may be obtained from published catalogs, vendors, independent appraisals, and other sources. If methods such as estimates, averages, or computational approximations, such as average value per pound or subsequent sales, can reduce the cost of measuring the fair value of inventory, use of those methods is appropriate, provided the methods are applied consistently, and the results of applying those methods are reasonably expected not to be materially different from the results of a detailed measurement of the fair value of contributed inventory.

Contributed Services

605-958-30-10
Contributions of services that create or enhance nonfinancial assets may be measured by referring to either the fair value of the services received or the fair value of the asset or of the asset enhancement resulting from the services. Fair value should be used for the measure regardless of whether the NFP could afford to purchase the services at their fair value.

Gifts in Kind

605-958-30-11
Gifts in kind that can be used or sold shall be measured at fair value. In determining fair value, entities should consider the quality and quantity of the gifts, as well as any applicable discounts that would have been received by the entity, including discounts based on that quantity if the assets had been acquired in exchange transactions. Fair value would generally not increase when a gift in kind is passed from one entity to another. However, fair value could increase if an entity adds value to the gift, such as by cleaning and packaging the gift. Any increases should be evaluated to determine whether the entity did, in fact, add to the fair value of the assets.

Transfers of Assets to a Not-for-Profit Entity or Charitable Trust That Raises or Holds Contributions for Others

Intermediary

605-958-30-12
Both the liability and the assets shall be measured at the fair value of the assets received from the donor.

Agent

605-958-30-13
Both the liability and the assets shall be measured at the fair value of the assets received from the donor.

Specified Beneficiary

605-958-30-14
If the beneficiary has an unconditional right to receive all or a portion of the specified cash flows from a charitable trust or other identifiable pool of assets, the beneficiary shall measure that beneficial interest at fair value. The fair value of a perpetual trust held by a third party generally can be measured using the fair value of the assets contributed to the trust, unless facts and circumstances indicate that the fair value of the beneficial interest differs from the fair value of the assets contributed to the trust. If the beneficiary recognizes a receivable pursuant to paragraph 958-605-25-30, the beneficiary shall measure its rights to the assets held by a recipient entity at fair value in accordance with paragraph 958-605-30-2 and paragraphs for unconditional promises to give.

605-958-35Subsequent Measurement

Source downloaded: .Record version 08b995cc2426. Effective date must be checked in the source.

Contributions Received

605-958-35-1
See Section 958-310-35-4 for subsequent measurement guidance for unconditional promises to give.
605-958-35-2
Pursuant to paragraph 958-605-25-13, if the maker of a conditional promise to give transfers assets before specified conditions are substantially met, the transfer shall be recognized by the recipient as a refundable advance, a liability. When the conditions are substantially met, the refundable advance shall be recognized as revenue or gain.

Transfers of Assets to a Not-for-Profit Entity or Charitable Trust That Raises or Holds Contributions for Others

Specified Beneficiary

605-958-35-3
If the beneficiary has an unconditional right to receive all or a portion of the specified cash flows from a charitable trust or other identifiable pool of assets, the beneficiary shall subsequently remeasure that beneficial interest at fair value (see paragraph 958-30-35-10). The fair value of a perpetual trust held by a third party generally can be measured using the fair value of the assets of the trust at the date of remeasurement, unless facts and circumstances indicate that the fair value of the beneficial interest differs from the fair value of the assets contributed to the trust. Annual distributions from a perpetual trust held by a third party are reported as investment income.

605-958-45Other Presentation Matters

Source downloaded: .Record version c22d4f2fd1a7. Effective date must be checked in the source.

605-958-45-1
Resources received in exchange transactions shall be classified as revenues in the net assets without donor restrictions class, even in circumstances in which resource providers place limitations on the use of the resources. For example, resources received from governments in exchange transactions in which those governments have placed limitations on the use of the resources shall be reported as revenues in the net assets without donor restrictions class, because those limitations are not donor-imposed restrictions on contributions. See paragraph 958-210-50-2 for additional information about significant contractual limitations.

Contributions Received

605-958-45-3
A not-for-profit entity (NFP) shall distinguish between contributions received with donor-imposed restrictions and those received without donor-imposed restrictions. The former shall be reported as donor-restricted support that increases net assets with donor restrictions. The latter shall be reported as support that increases net assets without donor restrictions.
605-958-45-4
A restriction on an NFP's use of the assets contributed results either from a donor's explicit stipulation or from circumstances surrounding the receipt of the contribution that make clear the donor's implicit restriction on use.

Simultaneous Release Option

605-958-45-4A
An NFP may elect a policy to report donor-restricted contributions whose restrictions are met in the same reporting period as the revenue is recognized as support within net assets without donor restrictions provided that the NFP has a similar policy for reporting investment gains and income (see paragraph 958-220-45-24), reports consistently from period to period, and discloses its accounting policy.
605-958-45-4B
An NFP may elect the policy described in paragraph 958-605-45-4A for donor-restricted contributions that were initially conditional contributions (the condition has been met) without also having to elect it for other donor-restricted contributions or investment gains and income provided that the NFP reports consistently from period to period and discloses its accounting policy.
605-958-45-5
Receipts of unconditional promises to give with payments due in future periods shall be reported as donor-restricted support unless explicit donor stipulations or circumstances surrounding the receipt of a promise make clear that the donor intended it to be used to support activities of the current period. It is reasonable to assume that by specifying future payment dates, donors indicate that their gifts are to support activities in each period in which a payment is scheduled. For example, receipts of unconditional promises to give cash in future years generally increase net assets with donor restrictions.
605-958-45-6
Gifts of long-lived assets received without stipulations about how long the donated asset must be used shall be reported as revenue without donor restrictions.Gifts of cash or other assets restricted to acquire long-lived assets shall initially be reported as donor-restricted support and shall be released from restrictions by reclassifying net assets with donor restrictions to net assets without donor restrictions when the asset is acquired and placed in service in accordance with paragraph 958-360-45-1A, unless the donor also has placed a time restriction on the use of the long-lived asset, in which case the release occurs over the life of the time restriction. (Pursuant to paragraph 958-205-45-12, all NFPs are not permitted to imply a time restriction that expires over the useful life of a long-lived asset.)
605-958-45-7
Pursuant to paragraph 958-220-45-3, reclassifications of net assets for expirations of donor-imposed restrictions are reported separately from other transactions.

Contributed Nonfinancial Assets

605-958-45-7A
An NFP shall present contributed nonfinancial assets as a separate line item in the statement of activities, apart from contributions of cash and other financial assets. See paragraph 958-605-50-1A for disclosure requirements for contributed nonfinancial assets.

Transfers of Assets to a Not-for-Profit Entity or Charitable Trust That Raises or Holds Contributions for Others

Interest in a Perpetual Trust

605-958-45-8
A specified beneficiary shall classify the contribution of a perpetual interest in a trust held by a third party as donor-restricted support that is perpetual in nature, because the trust is similar to a donor-restricted endowment that is perpetual in nature that the not-for-profit entity (NFP) does not control, rather than a multiyear promise to give. Any distributions from the trust that are free of purpose or time restrictions shall be reported as net assets without donor restrictions. Any distributions from the trust that are restricted for a particular time or purpose shall be reported as net assets with donor restrictions and released from restrictions when the time has elapsed or the purpose has been met by the NFP.

Reporting Results of Fundraising Efforts in the Financial Statements

605-958-45-9
Recipient entities that solicit and collect cash, products, or services and distribute those assets for charitable purposes to beneficiaries specified by the donor may desire to report the results of total campaign efforts to the users of financial statements. Although the receipt of the transferred assets is an inflow of assets from activities that constitute the entity's ongoing major or central operations, that inflow is accompanied by an offsetting liability to the specified beneficiary. Consequently, the receipt of the transferred assets is not revenue.
605-958-45-10
To the extent that an NFP's activities include raising and distributing cash, the total amounts raised and distributed may be evident from a statement of cash flows prepared using the direct method for reporting operating cash flows. In addition, generally accepted accounting principles (GAAP) do not preclude entities from providing supplementary information or additional disclosures. An NFP may provide a schedule reflecting fundraising efforts or campaign accomplishments or may disclose total amounts raised on the statement of activities, provided that amounts raised in an agent, trustee, or intermediary capacity are not shown as revenues. See Example 3 (paragraph 958-220-55-8) for an illustration of three possible methods of displaying fundraising efforts in the revenue section of a statement of activities.

605-958-50Disclosure

Source downloaded: .Record version ba7ebd9a8d9e. Effective date must be checked in the source.

Contributions Received

Contributed Nonfinancial Assets

605-958-50-1A
A not-for-profit entity (NFP) shall disclose in the notes to financial statements a disaggregation of the amount of contributed nonfinancial assets recognized within the statement of activities by category that depicts the type of contributed nonfinancial assets. For each category of contributed nonfinancial assets, an NFP also shall disclose the following:
  1. a
    Qualitative information about whether contributed nonfinancial assets were either monetized or utilized during the reporting period. If utilized, a description of the programs or other activities in which those assets were used shall be disclosed.
  2. b
    The NFP's policy (if any) about monetizing rather than utilizing contributed nonfinancial assets.
  3. c
    A description of any donor-imposed restrictions associated with the contributed nonfinancial assets.
  4. d
    A description of the valuation techniques and inputs used to arrive at a fair value measure in accordance with paragraph 820-10-50-2(bbb)(1), at initial recognition.
  5. e
    The principal market (or most advantageous market) used to arrive at a fair value measure if it is a market in which the recipient NFP is prohibited by a donor-imposed restriction from selling or using the contributed nonfinancial assets.
See paragraph 958-605-50-1B for additional disclosures for contributed services.

Contributed Services

605-958-50-1B
An entity (NFPs and business entities) that receives contributed services shall describe the programs or activities for which those services were used, including the nature and extent of contributed services received for the period and the amount recognized as revenues for the period. Entities are encouraged to disclose the fair value of contributed services received but not recognized as revenues if that is practicable. The nature and extent of contributed services received can be described by nonmonetary information, such as the number and trends of donated hours received or service outputs provided by volunteer efforts, or other monetary information, such as the dollar amount of contributions raised by volunteers. Disclosure of contributed services is required regardless of whether the services received are recognized as revenue in the financial statements.

Accounting Policies

605-958-50-2
When a not-for-profit entity (NFP) chooses to report donor-restricted contributionswhose restrictions are met in the same reporting period as support within net assets without donor restrictions in accordance with paragraph 958-605-45-4, it shall disclose its accounting policy.

Transfers of Assets to a Not-for-Profit Entity or Charitable Trust That Raises or Holds Contributions for Others

Intermediary or Agent

605-958-50-4
An intermediary or other recipient entity shall disclose its accounting policy for recognizing nonfinancial assets that it accepts from a donor on behalf of a specified beneficiary.
605-958-50-5
Additional information about transactions in which a not-for-profit entity (NFP) acts as an agent, trustee, or intermediary may be required to be disclosed under Topic 850.

Transfer Specifying Transferor or Its Affiliate as Beneficiary

605-958-50-6
If an NFP transfers assets to a recipient entity and specifies itself or its affiliate as the beneficiary, it shall disclose the following information for each period for which a statement of financial position is presented:
  1. a
    The identity of the recipient entity to which the transfer was made
  2. b
    Whether variance power was granted to the recipient entity and, if so, a description of the terms of the variance power
  3. c
    The terms under which amounts will be distributed to the resource provider or its affiliate
  4. d
    The aggregate amount recognized in the statement of financial position for those transfers and whether that amount is recorded as an interest in the net assets of the recipient entity or as another asset (for example, as a beneficial interest in assets held by others or a refundable advance).

605-958-55Implementation Guidance and Illustrations

Source downloaded: .Record version 3ea113f8b3b7. Effective date must be checked in the source.

605-958-55-1
This Section, which is an integral part of the requirements of this Subtopic, provides general guidance to be used in distinguishing contributions from exchange transactions, including membership dues and agency transactions.
605-958-55-1A
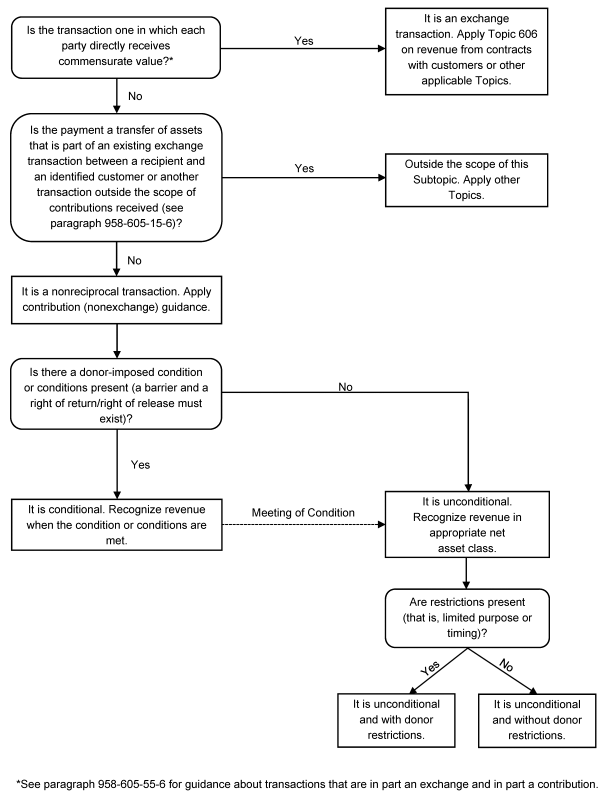
The following diagram illustrates the process for determining whether a transfer of assets to a recipient is a contribution, an exchange transaction, or another type of transaction and whether a contribution is conditional. The diagram also illustrates whether there is an associated donor restriction with a contribution.
  • Is the transaction one in which each party directly receives commensurate value? It is an exchange transaction. Apply Topic 606 on revenue from contracts with customers or other applicable Topics. Is the payment a transfer of assets that is part of an existing exchange transaction between a recipient and an identified customer or another transaction outside the scope of contributions received (see paragraph 958-605-15-6)? Outside the scope of this Subtopic. Apply other Topics. It is a nonreciprocal transaction. Apply contribution (nonexchange) guidance. Is there a donor-imposed condition or conditions present (a barrier and a right of return/right of release must exist)? It is conditional. Recognize revenue when the condition or conditions are met. It is unconditional. Recognize revenue in appropriate net asset class. Are restrictions present (that is, limited purpose or timing)? It is unconditional and with donor restrictions. It is unconditional and without donor restrictions.

Implementation Guidance

605-958-55-2
The accounting and reporting of grants, membership dues, and sponsorships is determined by the underlying substance of the transaction. Those terms are broadly used to refer not only to contributions but also to assets transferred in exchange transactions. A grant, sponsorship, or membership may be entirely a contribution, entirely an exchange, or a combination of the two; therefore, care must be taken in evaluating each grant, sponsorship, or membership agreement. In addition, those resource transfers may also have the characteristics of agency transactions.
605-958-55-2A
The implementation guidance is organized as follows:
  1. a
    Distinguishing contributions from exchange transactions (see paragraphs )
  2. b
    Distinguishing the contribution portion of membership dues (see paragraphs )
  3. c
    Distinguishing contributions from agency transactions (see paragraph 958-605-55-13).
605-958-55-3A
The guidance in this Subtopic about distinguishing between contributions and exchange transactions applies to both a resource provider (for example, a corporate foundation, a corporation, or a not-for-profit entity [NFP]) and a recipient.
605-958-55-4
Foundations, business entities, and other types of entities may provide resources to NFPs or business entities under programs referred to as grants, awards, or sponsorships. Those asset transfers are contributions if the resource providers do not receive commensurate value in exchange for the assets transferred or if the value received by the resource providers is incidental to the potential public benefit from using the assets transferred. A grant made by a resource provider to an NFP would likely be a contribution if the activity specified by the grant is to be planned and carried out by the NFP and the NFP has the right to the benefits of carrying out the activity. If, however, the grant is made by a resource provider that provides materials to be tested in the activity and that retains the right to any patents or other results of the activity, the grant would likely be an exchange transaction. A careful assessment of the characteristics of the transaction, from the perspectives of both the resource provider and the recipient, is necessary to determine whether a contribution has occurred.
605-958-55-5
For example, a resource provider may sponsor research and development activities at a research university and retain proprietary rights or other privileges, such as patents, copyrights, or advance and exclusive knowledge of the research outcomes. The research outcomes may be intangible, uncertain, or difficult to measure, and may be perceived by the university as a sacrifice of little or no value; however, their value often is commensurate with the value that a resource provider expects in exchange. Similarly, a resource provider may sponsor research and development activities and specify the protocol of the testing so the research outcomes are particularly valuable to the resource provider. Those transactions are not contributions if their potential public benefits are secondary to the potential proprietary benefits to the resource providers.
605-958-55-6
Moreover, a single transaction may be in part an exchange and in part a contribution. For example, if a donor transfers a building to an entity at a price significantly lower than its fair value and no unstated rights or privileges are involved, the transaction is in part an exchange of assets and in part a contribution to be accounted for as required by the Contributions Received Subsections of this Subtopic. See paragraphs for premiums provided to donors and Example 4 (paragraphs ) for direct benefits provided to donors at special events.
605-958-55-7
Example 1 (see paragraph 958-30-55-2) and paragraphs 958-605-55-13A through 55-14I illustrate the need to assess the relevant facts and circumstances to distinguish between the receipt of resources in an exchange and the receipt of resources in a contribution.
605-958-55-9
The term members is used broadly by some NFPs to refer to their donors and by other NFPs to refer to individuals or other entities that pay dues in exchange for a defined set of benefits. Some NFPs receive dues from their members. These transfers often have elements of both a contribution and an exchange transaction because members receive tangible or intangible benefits from their membership in the NFP. Usually, the determination of whether membership dues are contributions rests on whether the value received by the member is commensurate with the dues paid.
605-958-55-10
For example, if an NFP has annual dues of $100 and the only benefit members receive is a monthly newsletter with a fair value of $25, $25 of the dues are received in an exchange transaction and should be recognized as revenue as the earnings process is completed and $75 of the dues are a contribution. (See paragraph 958-605-25-1 for recognition of the exchange portion of membership dues. See the Contributions Received Subsections of this Subtopic for the reporting of the contribution portion.)
605-958-55-11
Member benefits generally have value regardless of how often (or whether) the benefits are used. For example, most would agree that a health club membership is an exchange transaction, even if the member stops using the facilities before the completion of the membership period. It may be difficult, however, to measure the benefits members receive and to determine whether the value of those benefits is approximately equal to the dues paid by the members.
605-958-55-12
The following table contains a list of indicators that may be helpful in determining whether membership dues are contributions, exchange transactions, or a combination of both. Depending on the facts and circumstances, some indicators may be more significant than others; however, no single indicator is determinative of the classification of a particular transaction.
  • Indicators Useful for Determining the Contribution and Exchange Portions of Membership Dues
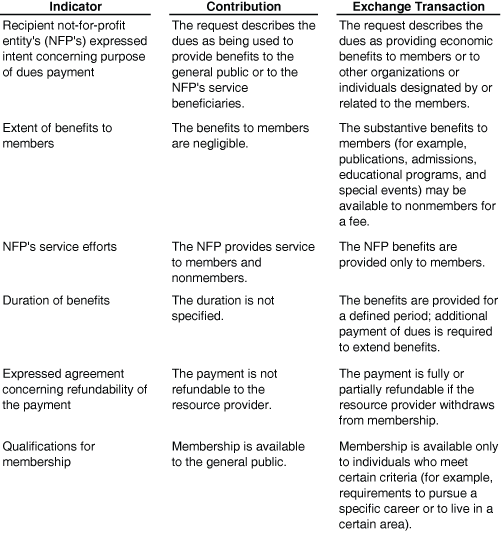
    Indicator Contribution Exchange Transaction Recipient not-for-profit entity's (NFP's) expressed intent concerning purpose of dues payment The request describes the dues as being used to provide benefits to the general public or to the NFP's service beneficiaries. The request describes the dues as providing economic benefits to members or to other organizations or individuals designated by or related to the members. Extent of benefits to members The benefits to members are negligible. "The substantive benefits to members (for example, publications, admissions, educational programs, and special events) may be available to nonmembers for a fee." NFP's service efforts The NFP provides service to members and nonmembers. The NFP benefits are provided only to members. Duration of benefits The duration is not specified. The benefits are provided for a defined period; additional payment of dues is required to extend benefits. Expressed agreement concerning refundability of the payment The payment is not refundable to the resource provider. The payment is fully or partially refundable if the resource provider withdraws from membership. Qualifications for membership Membership is available to the general public. "Membership is available only to individuals who meet certain criteria (for example, requirements to pursue a specific career or to live in a certain area)."
605-958-55-13
A transfer of assets may appear to be a contribution if a donor uses a recipient entity as its intermediary, agent, or trustee to transfer assets to a third-party donee, particularly if the recipient entity indirectly achieves its mission by disbursing the assets. Although the transaction between the donor and the donee may be a contribution, the transfer of assets from the donor is not a contribution received by the recipient entity, and the transfer of assets to the donee is not a contribution made by the recipient entity. (See the Transfers of Assets to a Not-for-Profit Entity or Charitable Trust that Raises or Holds Contributions for Others Subsection of this Section for implementation guidance on and illustrations of agency transactions.)

Illustrations

605-958-55-13A
Examples 1 through 5 illustrate the guidance in Section 958-605-15 for determining whether a transaction is an exchange or a contribution. The analysis in each Example is not intended to represent the only manner in which the guidance could be applied, and the Examples are not intended to apply to only a specific illustration. Although some aspects of the Examples may be present in actual fact patterns, all relevant facts and circumstances of a particular fact pattern should be evaluated when applying the guidance in this Subtopic. The guidance in these Examples about distinguishing between contributions and exchange transactions applies to both a resource provider (for example, a corporate foundation, a corporation, or an NFP) and a recipient.
605-958-55-14
Not-for-Profit Entity A (NFP A) is a large research university with a cancer research center. NFP A regularly conducts research to discover more effective methods of treating cancer and often receives contributions to support its efforts. NFP A receives resources from a pharmaceutical entity to finance the costs of a clinical trial of an experimental cancer drug the pharmaceutical entity developed. The pharmaceutical entity specifies the protocol of the testing, including the number of participants to be tested, the dosages to be administered, and the frequency and nature of follow-up examinations. The pharmaceutical entity requires a detailed report of the test outcome within two months of the test's conclusion. Additionally, the rights to the results of the study belong to the pharmaceutical entity.
605-958-55-14A
Because the results of the clinical trial have particular commercial value for the pharmaceutical entity, the pharmaceutical entity is receiving commensurate value as the resource provider. Therefore, the receipt of the resources is not a contribution received by NFP A, nor is the disbursement of the resources a contribution made by the pharmaceutical entity. See paragraph 958-605-15-5A.
605-958-55-14B
Student L is enrolled at University A. Student L's total tuition charged for the semester is $30,000. Student L received a grant in the amount of $2,000 to use toward the tuition fee, which is paid directly by the grantor to University A.
605-958-55-14C
The grant was awarded to Student L, not to University A. University A entered into an exchange transaction with Student L and accounts for the $30,000 of revenue in accordance with the guidance in the appropriate Subtopic. The $2,000 grant does not create additional revenue but, rather, serves as a partial payment against the $30,000 due to University A. Student L is an identified customer of University A who is receiving the benefit from the grant transaction. See paragraph 958-605-15-6(e).
605-958-55-14D
Patient R is a patient at Hospital B. The total amount due for services rendered is $10,000. Patient R has Medicare, and it covers $8,000 of the services, which is paid directly by the government to Hospital B. Hospital B bills Patient R for $2,000.
605-958-55-14E
Medicare is a form of insurance. Hospital B has a contract with a customer (Patient R) and determines that the $10,000 should be accounted for as an exchange transaction in accordance with the guidance in the appropriate Topic. The Medicare payment of $8,000 and Patient R's payment of $2,000 serve as a payment source for services rendered in the amount of $10,000 owed to Hospital B. The payment to Hospital B relates to an existing exchange transaction between Hospital B and an identified customer (Patient R). See paragraph 958-605-15-6(e).
605-958-55-14F
The local government provided funding to NFP C to perform a research study on the benefits of a longer school year. The agreement requires NFP C to plan the study, perform the research, and summarize and submit the research to the local government. The local government retains all rights to the study.
605-958-55-14G
NFP C concludes that this is a procurement arrangement in which commensurate value is being exchanged between two parties and that it should follow the relevant guidance for exchange transactions. NFP C is to perform a research study for the local government and turn over a summary of the study's findings to the local government. The local government retains the rights to the study. See paragraph 958-605-15-5A(c).
605-958-55-14H
University D applied for and was awarded a grant from the federal government. University D must follow the rules and regulations established by the Office of Management and Budget of the federal government and the federal awarding agency. University D is required to incur qualifying expenses to be entitled to the assets. Any unspent money during the grant period is forfeited, and University D is required to return any advanced funding that does not have related qualifying expenses. University D also is required to submit a summary of research findings to the federal government, but University D retains the rights to the findings and has permission to publish the findings if it desires.
605-958-55-14I
University D concludes that this grant is not a transaction in which there is commensurate value being exchanged. The federal government, as the resource provider, does not receive direct commensurate value in exchange for the assets provided to University D because University D retains all rights to the research and findings. University D and the public receive the primary benefit of any findings, and the federal government receives an indirect benefit because the research and findings serve the general public. Thus, University D determines that this grant should be accounted for under the contribution guidance in this Subtopic. See paragraph 958-605-15-5A(a).

Contributions Received

Implementation Guidance

605-958-55-15
Distinguishing between a condition stipulated by a donor and a restriction on the use of a contribution imposed by a donor may require the exercise of judgment. A donor-imposed condition depends on whether the agreement includes a barrier that must be overcome before a recipient is entitled to the assets transferred or promised. The agreement also must give either the contributor a right of return of the assets it has transferred or the promisor a right of release from its obligation to transfer assets. Donor-imposed conditions should be substantially met by the entity before the receipt of assets (including contributions receivable) is recognized as a contribution. In contrast to donor-imposed conditions, donor-imposed restrictions limit the use of the contribution, but they do not affect whether the recipient is entitled to the contribution.
605-958-55-16
If donor stipulations do not clearly state whether the right to receive or retain payment or take delivery depends on meeting those stipulations, or if those stipulations are ambiguous, distinguishing a conditional promise to give from an unconditional promise to give may be difficult. If the ambiguity cannot be resolved by reviewing the facts and circumstances surrounding the contribution and communicating with the donor, presume that a promise containing stipulations that are not clearly unconditional is a conditional promise to give. However, if the stipulation is not related to the purpose of the agreement (generally stipulations that are administrative or trivial), that stipulation is not indicative of a barrier (for example, a stipulation that an annual report must be provided by the donee to receive subsequent annual payments on a multiyear promise is not a barrier if the administrative requirement is not related to the purpose of the agreement.)
605-958-55-17
A challenge (matching) grant is a common form of a conditional promise to give. For example, a resource provider promises to contribute $1 for each $1 of contributions received by a not-for-profit entity (NFP), up to $100,000, over the next 6 months. As contributions are received from other resource providers, the conditions would be met and the promise would become unconditional. For example, if $10,000 is received in the first month from donors, $10,000 of the conditional promise would become unconditional and should be recognized as contribution revenue.
605-958-55-17A
A donor-imposed condition must have both:
  1. a
    One or more barriers that must be overcome before a recipient is entitled to the assets transferred or promised.
  2. b
    A right of return to the contributor for assets transferred (or for a reduction, settlement, or cancellation of liabilities) or a right of release of the promisor from its obligation to transfer assets (or to reduce, settle, or cancel liabilities).
See paragraphs for examples.
605-958-55-17B
It is possible that some agreements that do not contain any barriers could contain either a right of return of assets transferred or a right of release from obligation. For example, some foundations include a right-of-return or a right-of-release-from-obligation clause in their agreements as a matter of policy and standard wording but impose no barriers that must be achieved before a recipient is entitled to the resources. The resources would be considered unconditional, and revenue would be recognized immediately.
605-958-55-17C
Some agreements include multiple requirements that must be overcome before an entity is entitled to transferred assets or a future transfer of assets. An entity must consider facts and circumstances and use judgment to determine which stipulations, if any, of an agreement are deemed to be a barrier or barriers that must be achieved before an entity is entitled to assets.
605-958-55-17D
As described in paragraph 958-605-25-5D, a measurable performance-related barrier or other measurable barrier may be indicative of a donor-imposed condition. Examples of measurable performance-related barriers or other measurable barriers could include:
  1. a
    Specified level of service. An entity is given assets, and the resource provider stipulates that the assets must be used to provide a specific level of service (for example, 1,000 meals per week for a soup kitchen). The barrier that must be overcome before the recipient is entitled to the resources is the specified level of service that must be achieved.
  2. b
    Specific output or outcome. An entity is given assets, entitlement to which is contingent upon producing a specific output or achieving a measurable outcome stemming from the entity's activities (for example, students achieving a minimum standardized test score, a decline in drop-out rates following an entity's educational efforts, and community residents exhibiting a decline in symptoms of malnutrition following an entity's efforts in providing meals).
  3. c
    Matching. A resource provider specifies the ratio or amount of a matching contribution. The recipient is not entitled to receive the promised assets until it has met the required match (the barrier or hurdle that must be overcome).
  4. d
    Outside event. Agreements may include requirements that are imposed on, and would need to be overcome by, other parties, including the resource provider. A resource provider specifies that a certain outside event needs to occur for the recipient to be entitled to receive the assets (for example, a resource provider promises to contribute a certain amount of assets if the resource provider's net worth reaches a specified level).
605-958-55-17E
As described in paragraph 958-605-25-5D, limited discretion may be indicative of a donor-imposed condition. Limited discretion of the recipient on the conduct of an activity is more specific than a donor-imposed restriction. Restrictions limit the use of a contribution to a specific activity or time but do not necessarily place limitations on how the activity is performed. This indicator focuses on limitations concerning specific requirements about how an activity must be conducted for a recipient to be entitled to the resources. For example, an agreement might specify that the recipient should incur qualifying expenses in compliance with established rules and regulations. This is in contrast to a restriction, which typically places limits only on a specific activity that is being funded and does not affect the extent to which a recipient is entitled to the resources (for example, a requirement that a contribution be used to fund one of an organization's programs).
605-958-55-17F
An indicator noting that a stipulation is related to the purpose of the agreement could be helpful in the context of considering the agreement collectively with the other indicators. If a stipulation is unrelated to the purpose of the agreement (for example, trivial or administrative stipulations), the stipulation would not be indicative of a barrier. If administrative tasks are required that are unrelated to the purpose of the agreement, there most likely would be other requirements that would be more indicative of a barrier that must be overcome before the recipient is entitled to the resources (for example, a specific event or activity to occur). Producing an annual report is a common requirement in contribution agreements; however, the annual report typically is not related to the underlying purpose of the agreement. Generally, a report is administrative in nature and is intended to provide a resource provider with information to confirm that the transferred assets were used in accordance with the purpose of the agreement and is not intended to affect the extent to which the recipient is entitled to the contribution.
605-958-55-18
A promise to give is a written or oral agreement to contribute cash or other assets to another entity. The Contributions Received Subsections of this Subtopic avoid using the term pledge because that term is used to describe not only promises to give but also plans or intentions to give that are not promises. There are other terms used to describe promises to give such as subscriptions, awards, appropriations, or grants. A communication received from a potential donor must be carefully evaluated to determine if it is a promise to give, since a communication that clearly is not a promise is not recognized in the financial statements.
605-958-55-19
Pursuant to paragraph 958-605-25-8, to be recognized in financial statements there must be sufficient evidence in the form of verifiable documentation that a promise to give was made and received. That requirement does not preclude recognition of verifiable oral promises, such as those documented by tape recordings, written registers, or other means that permit subsequent verification.
605-958-55-20
Promises to give services generally involve personal services that, if not explicitly conditional, are often implicitly conditioned upon the future and uncertain availability of specific individuals whose services have been promised.
605-958-55-21
Certain promises become unconditional in stages because they are dependent on several or a series of conditions—milestones—rather than on a single condition and are recognized in increments as each of the conditions is met. Similarly, other promises are conditioned on promisees' incurring certain qualifying expenses (or costs). Those promises become unconditional and are recognized to the extent that the expenses are incurred. A portion of those contributions should be recognized as revenue as each of those stages is met.
605-958-55-22
The present value of the future cash flows is one valuation technique for measuring the fair value of contributions arising from unconditional promises to give cash; other valuation techniques also are available, as described in Topic 820. The following table illustrates the use of present value techniques for initial recognition and measurement of unconditional promises to give cash that are expected to be collected one year or more after the financial statement date.
  • Initial Recognition of Unconditional Promises to Give Cash
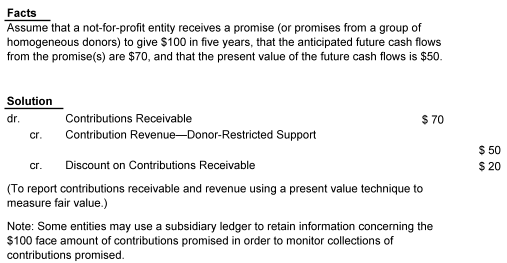
    Facts "Assume that a not-for-profit entity receives a promise (or promises from a group of homogeneous donors) to give $100 in five years, that the anticipated future cash flows from the promise(s) are $70, and that the present value of the future cash flows is $50." Solution dr. Contributions Receivable $70 cr. Contribution Revenue—Donor-Restricted Support $50 cr. Discount on Contributions Receivable $20 (To report contributions receivable and revenue using a present value technique to measure fair value.) Note: Some entities may use a subsidiary ledger to retain information concerning the $100 face amount of contributions promised in order to monitor collections of contributions promised.
605-958-55-23
The use of property, utilities, or advertising time is considered to be forms of contributed assets, rather than contributed services. Pursuant to paragraph 958-605-25-2, an NFP would recognize the fair value of the use of property, utilities, or advertising time as both revenue and expense in the period received and used. Fair value could be estimated by using billing rates normally charged to other customers under similar circumstances. Whether those contributions should be reported is unaffected by whether the NFP could afford to purchase the utilities or facilities at their fair value. If the transaction is an unconditional promise to give electric, telephone, or other utilities for a specified number of periods, the promise should be reported as a contribution receivable and as donor-restricted support that increases net assets with donor restrictions, pursuant to paragraph 958-605-25-8.
605-958-55-24
Unconditional promises to give the use of long-lived assets (such as a building or other facilities) for a specified number of periods in which the donor retains legal title to the long-lived asset may be received in connection with leases or may be similar to leases but have no lease payments. For example, an NFP may use facilities under a lease agreement that calls for lease payments at amounts below the fair rental value of the property. In circumstances in which an NFP receives an unconditional promise to give for a specified number of periods, the promise should be reported as revenue and as a contribution receivable for the difference between the fair rental value of the property and the stated amount of the lease payments. In other words, if a donor promises that the NFP can use a facility for 10 years, the NFP has received a multiyear promise to give and should report the fair value of that promise as a contribution with a donor-imposed restriction in Year 1. Amounts reported as contributions shall not exceed the fair value of the long-lived asset at the time the NFP receives the unconditional promise to give. The contribution receivable may be described in the financial statements based on the item whose use is being contributed, such as a building, rather than as contributions receivable.
605-958-55-25
Property and equipment used in exchange transactions (other than lease transactions), such as federal contracts, in which the resource provider retains legal title during the term of the arrangement should be reported as a contribution at fair value at the date received by the NFP only if it is probable that the NFP will be permitted to keep the assets when the arrangement terminates.
Transition date:(P) December 16, 2026; (N) December 16, 2026Transition guidance:
105-10-65-10Paragraph superseded by Accounting Standards Update No. 2025-12.
605-958-55-26
Contributions are received in several different forms. Most often the item contributed is an asset, but it also can be forgiveness of a liability. The types of assets commonly contributed include cash, marketable securities, land, buildings, use of facilities or utilities, materials and supplies, intangible assets, other goods or services, and unconditional promises to give those items in the future. The Contributions Received Subsection of Section 958-605-30 requires NFPs receiving contributions to recognize them at the fair values of the assets received. However, recognition of contributions of works of art, historical treasures, and similar assets is not required if the donated items are added to collections (see paragraph 958-360-25-1), and recognition of contributions of services is prohibited if the services do meet any of the criteria in paragraph 958-605-25-16.
605-958-55-27
Examples 1 through 6 (see paragraphs ) provide illustrations on different types of contributed assets, including the following:
  1. a
    Real property
  2. b
    Works of art
  3. c
    Historical objects
  4. d
    Utilities
  5. e
    Use of property
  6. f
    Interest in an estate.
605-958-55-28
Recognition of contributions of services is required for those contributed services received that meet any of the specified conditions of paragraph 958-605-25-16 and is precluded for contributed services that do not. The criterion in paragraph 958-605-25-16(b)requires that recognized services be specialized skills provided by individuals possessing those skills. An individual who receives some training does not necessarily possess a specialized skill. For example, if a volunteer receives some training from an NFP to learn how to help other people learn to read, that volunteer does not possess the specialized skills that a reading teacher possesses.
605-958-55-29
Examples 7 through 11 (see paragraphs ) provide illustrations on different types of contributed services, including the following:
  1. a
    Construction services
  2. b
    Teaching services
  3. c
    Board of trustee services
  4. d
    Companion services
  5. e
    Fundraising services.
605-958-55-30
See paragraph 275-10-50-18 for guidance on disclosures about risk concentrations.
605-958-55-31
Example 12 (see paragraph 958-605-55-69) illustrates the situation in which an NFP relies on specific donors for contributions.

Illustrations

605-958-55-32
This Example illustrates the application of the recognition and measurement principles of paragraphs 958-605-25-2 and 958-605-30-2.
605-958-55-33
Mission A, a religious NFP, receives a building (including the land on which it was constructed) as a gift from a local corporation with the understanding that the building will be used principally as an education and training center for Mission A's members or for any other purpose consistent with Mission A's plans.
605-958-55-34
Mission A would recognize the contributed property as an asset and as support and measure that property at its fair value (see paragraph 958-605-30-2). Information necessary to estimate the fair value of that property could be obtained from various sources, including amounts recently paid for similar properties in the locality, and estimates of its replacement cost adjusted to reflect the price that would be received for the contributed property. This contribution is revenue without donor restrictions because the donated assets may be used for any purpose and the donor did not impose a time restriction.
605-958-55-35
This Example illustrates the application of the recognition and measurement principles of paragraph 958-605-25-19.
605-958-55-36
Museum B, which preserves its collections as described in paragraph 958-605-25-19, receives a gift of a valuable painting from a donor. The donor obtained an independent appraisal of the fair value of the painting for tax purposes and furnished a copy to the museum. The museum staff evaluated the painting to determine its authenticity and worthiness for addition to the museum's collection. The staff recommended that the gift be accepted, adding that it was not aware of any evidence contradicting the fair value provided by the donor and the donor's appraiser.
605-958-55-37
If Museum B capitalizes its collections, Museum B would recognize the fair value of the contributed work of art received as revenue and capitalize it as an asset at its fair value (see paragraph 958-605-25-19). If Museum B does not capitalize its collections, Museum B is precluded from recognizing the contribution (see that paragraph) and would provide the information required by paragraphs 958-360-45-3 and 958-360-45-5.
605-958-55-38
If Museum B accepted the painting with the donor's understanding that it would be sold rather than added to its collection, Museum B would recognize the contribution of the painting received as revenue without donor restrictions and as an asset at its fair value (see paragraphs 958-605-30-2 and 958-605-45-6).
605-958-55-39
This Example illustrates the application of the recognition and measurement principles of paragraph 958-605-25-19.
605-958-55-40
Historical Society C receives several old photographs as a gift from a long-time local resident. The photographs depict a particular area as it was 75 years ago. After evaluating whether the photographs were worthy of addition to the historical society's collection, the staff concluded the photographs should be accepted solely because of their potential historical and educational use; that is, the photographs may be of interest to future researchers, historians, or others interested in studying the area. The photographs are not suitable for display and no alternative use exists.
605-958-55-41
Regardless of whether Historical Society C capitalizes its collections, Historical Society C would not recognize the contributed photographs as assets because there is major uncertainty about the existence of value and no alternative use exists (see paragraph 958-605-25-4).
605-958-55-42
This Example illustrates the application of the recognition and measurement principles of paragraphs 958-605-25-2 and 958-605-30-2.
605-958-55-43
Foundation D operates from a building it owns. The holding company of a local utility has been contributing electricity on a continuous basis subject to the donor's cancellation.
605-958-55-44
The simultaneous receipt and use of electricity or other utilities is a form of contributed assets and not services. Foundation D would recognize the fair value of the contributed electricity as both revenue and expense in the period it is received and used (see paragraph 958-605-30-2). Foundation D could estimate the fair value of the electricity received by using rates normally charged to a consumer of similar usage requirements.
605-958-55-45
This Example illustrates the application of the recognition and measurement principles of paragraphs 958-605-25-2 and 958-605-30-2.
605-958-55-46
Charity E receives the free use of 10,000 square feet of prime office space provided by a local entity. The local entity has informed Charity E that it intends to continue providing the space as long as it is available, and although it expects it would be able to give the charity 30 days advance notice, it may discontinue providing the space at any time. The local entity normally rents similar space for $14 to $16 annually per square foot, the going market rate for office space in the area. Charity E decides to accept this gift—the free use of office space—to conduct its daily central administrative activities.
605-958-55-47
The simultaneous receipt and use of facilities is a form of contributed assets and not services. Charity E would recognize the fair value of the contributed use of facilities as both revenue and expense in the period it is received and used (see paragraph 958-605-30-2).
605-958-55-48
If the local entity explicitly and unconditionally promises the use of the facility for a specified period of time (for example, five years), the promise would be an unconditional promise to give. In that case, Charity E would recognize the receipt of the unconditional promise as a receivable and as donor-restricted support at its fair value. The donor would recognize the unconditional promise when made as a payable and an expense at its fair value (see paragraph 720-25-25-1).
605-958-55-49
This Example illustrates the application of the recognition and measurement principles of paragraphs 958-605-25-2 and 958-605-30-2.
605-958-55-50
In 19X0, Individual notifies Church F that she has remembered the church in her will and provides a written copy of the will. In 19X5, Individual dies. In 19X6, Individual's last will and testament enters probate and the probate court declares the will valid. The executor informs Church F that the will has been declared valid and that it will receive 10 percent of Individual's estate, after satisfying the estate's liabilities and certain specific bequests. The executor provides an estimate of the estate's assets and liabilities and the expected amount and time for payment of Church F's interest in the estate.
605-958-55-51
The 19X0 communication between Individual and Church F specified an intention to give. The ability to modify a will at any time prior to death is well established; thus in 19X0 Church F did not receive a promise to give and did not recognize a contribution received. When the probate court declares the will valid, Church F would recognize a receivable and revenue for an unconditional promise to give at the fair value of its interest in the estate (see paragraphs 958-310-35-6, 958-605-30-5, and 958-605-30-6). If the promise to give contained in the valid will was instead conditional based on a barrier that must be overcome for Church F to be entitled to the assets, Church F would recognize the contribution when the condition was substantially met. A conditional promise in a valid will would be disclosed in notes to financial statements (see paragraph 958-310-50-4).
605-958-55-52
This Example illustrates the application of the recognition and measurement principles of paragraphs 958-605-25-16 and 958-605-30-10.
605-958-55-53
Institute G decides to construct a building on its property. It obtains the necessary architectural plans and specifications and purchases the necessary continuing architectural services, materials, permits, and so forth at a total cost of $400,000. A local construction entity contributes the necessary labor and equipment. An independent appraisal of the building (exclusive of land), obtained for insurance purposes, estimates its fair value at $725,000.
605-958-55-54
Institute G would recognize the services contributed by the construction entity because the contributed services received meet the condition in paragraph 958-605-25-16(a) (the services received create or enhance nonfinancial assets) or because the services meet the condition in paragraph 958-605-25-16(b) (the services require specialized skills, are provided by individuals possessing those skills, and would typically need to be purchased if not provided by donation). Contributions of services that create or enhance nonfinancial assets may be measured by referring to either the fair value of the services received or the fair value of the asset or of the asset enhancement resulting from the services (see paragraph 958-605-30-10). In this Example, the fair value of the contributed services received could be determined by subtracting the cost of the purchased services, materials, and permits ($400,000) from the fair value of the asset created ($725,000), which results in contributed services received of $325,000. Alternatively, the amount the construction entity would have charged could be used if more readily available.
605-958-55-55
If some of the labor did not require specialized skills and was provided by volunteers, those services still would be recognized because they meet the condition in paragraph 958-605-25-16(a).
605-958-55-56
This Example illustrates the application of the recognition and measurement principles of paragraphs 958-605-25-16 and 958-605-30-10.
605-958-55-57
Faculty salaries are a major expense of University H. The faculty includes both compensated faculty members (approximately 80 percent) and uncompensated faculty members (approximately 20 percent) who are associated with religious orders and contribute their services to the university. The performance of both compensated and uncompensated faculty members is regularly and similarly evaluated; both must meet the university's standards and both provide services in the same way.
605-958-55-58
University H would recognize both revenue and expense for the services contributed by the uncompensated faculty members because the contribution meets the condition in paragraph 958-605-25-16(b). Teaching requires specialized skills; the religious personnel are qualified and trained to provide those skills; and University H typically would hire paid instructors if the religious personnel did not donate their services. University H could refer to the salaries it pays similarly qualified compensated faculty members to determine fair value of the services received.
605-958-55-59
Similarly, if the uncompensated faculty members were given a nominal stipend to help defray certain of their out-of-pocket expenses, University H still would recognize both revenue and expense for the services contributed. The contribution received would be measured at the fair value of the services received less the amount of the nominal stipend paid.
605-958-55-60
This Example illustrates the application of the recognition and measurement principles of paragraphs 958-605-25-16 and 958-605-30-10.
605-958-55-61
A member of the board of trustees of Civic Organization I is a lawyer and from time to time in the capacity of a trustee provides advice on general business matters, including questions about business opportunities and risks and ethical, moral, and legal matters. The advice provided on legal matters is provided as a trustee in the role of a trustee, not as a lawyer, and the opinions generally are limited to routine matters. Generally, the lawyer suggests that Civic Organization I seek the opinion of its attorneys on substantive or complex legal questions. All of Civic Organization I's trustees serve without compensation, and most trustees have specialized expertise (for example, a chief executive officer, a minister, a physician, a professor, and a public accountant) that makes their advice valuable to Civic Organization I. The trustee-lawyer also serves without compensation as a trustee for two other charitable organizations.
605-958-55-62
Civic Organization I would be precluded from recognizing the contributed services it receives from its trustee-lawyer or its other trustees because the services contributed do not meet either of the conditions in paragraph 958-605-25-16. The condition in (a) in that paragraph is not relevant. The trustee-lawyer's services do not meet the condition in (b) in that paragraph because the substantive or complex legal questions that require the specialized skills of a lawyer are referred to Civic Organization I's attorneys or because the advice provided by trustees typically would not be purchased if not provided by donation.
605-958-55-63
This Example illustrates the application of the recognition and measurement principles of paragraphs 958-605-25-16 and 958-605-30-10.
605-958-55-64
Hospital J provides short-term inpatient and outpatient care and also provides long-term care for the elderly. As part of the long-term care program, the hospital has organized a program whereby local high school students may contribute a minimum of 10 hours a week, from 3:00 p.m. to 6:00 p.m., to the hospital. These students are assigned various duties, such as visiting and talking with the patients, distributing books and magazines, reading, playing chess, and similar activities. Hospital J does not pay for these services or similar services. The services are accepted as a way of enhancing or supplementing the quality of care and comfort provided to the elderly long-term care patients.
605-958-55-65
Hospital J would be precluded from recognizing the contributed services because the services contributed do not meet either of the conditions in paragraph 958-605-25-16. The condition in (a) in that paragraph is not relevant. The condition in (b) in that paragraph has not been met because the services the students provide do not require specialized skills nor would they typically need to be purchased if not provided by donation.
605-958-55-66
This Example illustrates the application of the recognition and measurement principles of paragraphs 958-605-25-16 and 958-605-30-10.
605-958-55-67
College K conducts an annual fund-raising campaign to solicit contributions from its alumni. In prior years, College K recruited unpaid student volunteers to make phone calls to its alumni. This year, a telemarketing entity, whose president is an alumnus of College K, contributed its services to College K for the annual alumni fundraising campaign. The entity normally provides telemarketing services to a variety of clients on a fee basis. College K provided the entity with a list of 10,000 alumni, several copies of a typed appeal to be read over the phone, and blank contribution forms to record pledges received. The entity contacted most of the 10,000 alumni.
605-958-55-68
College K would be precluded from recognizing the contributed services of the telemarketing entity. The condition in paragraph 958-605-25-16(a) is not relevant. The condition in paragraph 958-605-25-16(b) has not been met because the services do not require specialized skills or because College K typically would not need to purchase the services if they were not provided by donation. College K normally conducts its campaign with untrained students in a manner similar to the manner used by the telemarketing firm.
605-958-55-69
This Example illustrates the disclosure requirements of paragraphs 275-10-50-16.
605-958-55-70
Zebra Zoo is supported by contributions from the public. In the current year, 2 contributors provided 35 percent of Zebra Zoo's combined revenues. The following disclosure is required (see paragraph 275-10-50-16) because the two contributors provided a significant portion of Zebra Zoo's revenues. It is always considered reasonably possible that a customer, grantor, or contributor will be lost in the near term.
  • Approximately 35 percent of Zebra Zoo's combined revenues were provided by 2 contributors.
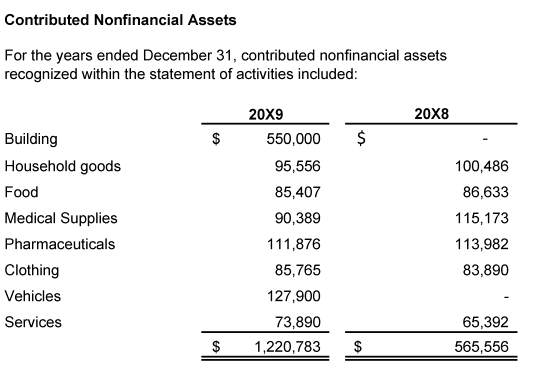
605-958-55-70A
Examples 13 through 21 (paragraphs ) illustrate how an entity might apply certain aspects of the guidance in this Subtopic in determining whether a contribution is conditional (all fact patterns are considered to be contributions or conditional contributions within the scope of this Subtopic). The analysis in each Example is not intended to represent the only manner in which the guidance could be applied, and the Examples are not intended to apply to only a specific illustration. Although some aspects of the Examples may be present in actual fact patterns, all relevant facts and circumstances of a particular fact pattern would need to be evaluated when applying the guidance in this Subtopic (for guidance on release from restrictions, see Section 958-605-45). Some examples are presented from the perspective of a resource provider (for example, an individual, a business corporation, a foundation, or an other NFP), and other examples are presented from the perspective of a resource recipient. The guidance in this Subtopic on determining whether a contribution is conditional applies to both contributions made by a resource provider and contributions received by a recipient.
605-958-55-70B
Many agreements include a requirement that assets must be used for allowable and reasonable qualifying expenses (or costs) that are based on specific requirements of an agreement about the conduct of an activity (for example, in compliance with principles issued by the Office of Management and Budget or other similarly restrictive grant documents) that results in limited discretion by a recipient on the conduct of an activity and, thus, is indicative of a donor-imposed condition. These agreements often are paid on a cost-reimbursement basis that requires a recipient to incur specific qualifying expenses to be entitled to the promised resources. The specific requirements about allowable qualifying expenses are often accompanied by very close cost reporting and monitoring by the resource provider.
605-958-55-70C
Foundation A gives NFP D a grant in the amount of $400,000 to provide specific career training to disabled veterans. The grant requires NFP D to provide training to at least 8,000 disabled veterans during the next fiscal year (2,000 during each quarter), with specific minimum targets that must be met each quarter. Foundation A specifies a right of release from the obligation in the agreement that it will only give NFP D $100,000 each quarter if NFP D demonstrates that those services have been provided to at least 2,000 disabled veterans during the quarter.
605-958-55-70D
Foundation A determines that it should account for this grant as conditional. The agreement contains a right of release from obligation because the resource provider will only transfer assets if NFP D provides training to at least 8,000 disabled veterans during the year (with a minimum requirement of 2,000 disabled veterans per quarter) as specified in the agreement. Foundation A requires NFP D to achieve a specific level of service that would be considered a measurable performance-related barrier (in the form of milestones by specifying 2,000 disabled veterans per quarter). In this Example, NFP D's entitlement to the transferred assets is contingent upon serving at least 2,000 disabled veterans. The likelihood of serving at least 2,000 disabled veterans for the quarter is not a consideration from the perspective of either Foundation A or NFP D when assessing whether the contribution contains a barrier and is deemed conditional.
605-958-55-70E
NFP B is a hospital that has a research program. NFP B receives a $300,000 grant from the federal awarding agency to fund thyroid cancer research. The terms of the grant specify that NFP B must incur certain qualifying expenses (or costs) in compliance with rules and regulations established by the Office of Management and Budget and the federal awarding agency. The grant is paid on a cost-reimbursement basis by NFP B initiating drawdowns of the grant assets. Any unused assets are forfeited, and any unallowed costs that have been drawn down by NFP B are required to be refunded.
605-958-55-70F
NFP B determines that this grant is conditional. The grant agreement limits NFP's discretion as a result of the specific requirements on how NFP B may spend the assets (incurring certain qualifying expenses in accordance with the Office of Management and Budget rules and regulations). The grant also includes a release from the promisor's obligation for unused assets. The requirement to spend the assets on qualifying expenses is a barrier to entitlement because the requirement limits NFP B's discretion about how to use the assets, and the assets would need to be spent on specific items on the basis of the requirements of the agreement (for example, adherence to cost principles) before NFP B is entitled to the assets. This is in contrast to a restriction that typically places limits only on a specific activity that is being funded. NFP B records revenue during the grant period when the barriers have been overcome as it incurs qualifying expenses. The likelihood of incurring qualifying expenses is not a consideration when assessing whether the contribution is deemed conditional.
605-958-55-70G
NFP E is a public charity that performs research on various diseases and allergies, including gluten-related allergies, as part of its overall mission. It receives a $100,000 grant from a foundation to perform research on gluten-related allergies over the next year. The grant agreement includes a right of return as part of the foundation's standard wording and a requirement that at the end of the grant period a report must be filed with the foundation that explains how the assets were spent.
605-958-55-70H
NFP E determines that the grant is not a conditional contribution. The purpose of research on gluten-related allergies results in donor-restricted revenue because the purpose of the grant (working on gluten-free allergies) is narrower than the overall mission of the entity. There are no requirements in the agreement that would indicate that a barrier exists, which must be overcome before the recipient is entitled to the resources. NFP E also determines that the reporting requirement alone is not a barrier because it is an administrative requirement and not related to the purpose of the agreement, which is the actual research. This is an example in which a grant including a right of return could not be considered conditional because the return clause is not coupled with a barrier to be overcome, as determined by NFP E using judgment to assess the indicators of a barrier.
605-958-55-70I
NFP DD is a hospital that received an upfront cash contribution from an individual to perform research on Alzheimer's disease during NFP DD's next fiscal year. The agreement does not include a right of return or a barrier that must be overcome to be entitled to the funds.
605-958-55-70J
NFP DD determines that this contribution is not conditional because it does not include a right of return (or similar language) of the assets that have been transferred upfront. NFP DD concludes that it should recognize the revenue upon receipt of the assets from the individual as donor-restricted because it is required to use the assets for Alzheimer's research, which is narrower than NFP DD's overall mission, during the next fiscal year.
605-958-55-70K
Foundation B receives a grant proposal from an animal rescue facility, NFP F, which requests a 2-year grant in the amount of $500,000 upfront to be used to expand its operations. The agreement indicates that NFP F must expand its facility by at least 5,000 square feet to accommodate additional animals by the end of the 2 years. The grant contains a right of return if the minimum expansion target is not achieved.
605-958-55-70L
Foundation B determines that this grant is conditional. The grant includes a measurable barrier (5,000 additional square feet) that must be achieved by NFP F to be entitled to the assets and a right of return for unused assets or unmet requirements.
605-958-55-70M
NFP G is a university that is conducting a capital campaign to build a new building to house its school of mathematics and to make capital improvements to existing buildings on campus, including a new heating system and an upgraded telephone and computer network. NFP G receives an upfront grant in the amount of $10,000 from a foundation as part of its capital campaign. The agreement contains a right of return requiring that the assets be reimbursed to the resource provider if the assets are not used for the purposes outlined in the capital campaign solicitation materials. The resource provider does not include any specifications in the agreement about how the building should be constructed or on how other improvements should be made.
605-958-55-70N
NFP G determines that this grant is not conditional because the agreement places limits only on the specific activity that is being funded (for example, the assets can be used toward the new building or toward other capital improvements such as the heating system and an upgraded telephone and computer network within existing buildings on campus). The resource provider does not include any specifications about how the building should be constructed, and the agreement only indicates that NFP G must use the grant for the purpose outlined in the capital campaign materials. NFP G recognizes this grant as donor-restricted revenue because it must be used for capital purposes, which is narrower than NFP G's overall mission. This Example illustrates a fact pattern in which a grant can include a right of return and would be deemed a contribution that does not contain a donor-imposed condition because the return clause is not coupled with a barrier to be overcome, as determined by NFP G using judgment to assess the indicators of a barrier.
605-958-55-70O
NFP I is a museum that receives a grant from an individual donor to build a new wing on the existing museum building. The agreement contains a $1 million multiyear promise to give the money to be used for the new wing on the building. The agreement also includes specific building requirements, including square footage and that the new wing must be environmentally friendly with Leadership in Energy and Environmental Design certification. The first installment of the gift will not be paid until NFP I submits architectural designs that meet the building requirements. Additional installments of the grant will be paid in specified increments upon achieving other milestones identified in the grant agreement. If a particular milestone is not achieved, the donor is released from its obligation to make installment payments.
605-958-55-70P
NFP I determines that this agreement is conditional because NFP I is not entitled to the assets until a milestone is met (for example, an architectural plan including square footage and Leadership in Energy and Environmental Design certification). In this example, a milestone is deemed a measurable performance barrier because NFP I's entitlement to the transferred assets is contingent upon the completion of a milestone. In addition, the agreement includes a release of the resource provider's obligation to transfer assets if the stipulations are not met. NFP I recognizes the revenue as the barriers are overcome, which is upon meeting the specific requirements as NFP I builds the new wing. The likelihood of meeting a milestone is not a consideration when assessing whether the contribution is deemed conditional.
605-958-55-70Q
NFP J operates as a homeless shelter that provides individuals with temporary accommodations, meals, and counseling. NFP J receives an upfront grant of $75,000 from the city for its meals program. The grant requires NFP J to use the assets to provide at least 5,000 meals to the homeless. The grant contains a right of return for meals not served.
605-958-55-70R
NFP J determines that this grant is conditional because it contains a measurable performance-related barrier (to provide 5,000 meals) and a right of return. NFP J recognizes assets received in advance of satisfying the conditions as a refundable advance liability and will then recognize $75,000 as donor-restricted revenue when at least 5,000 meals are served because the purpose of the grant is narrower than the overall purpose of NFP J. The likelihood of providing the meals is not a consideration when assessing whether the contribution is deemed conditional.
605-958-55-70S
NFP H is a recreational organization that provides various sports programs to children that live in the community. NFP H receives an upfront grant in the amount of $40,000 from a foundation to be used toward its tennis program. Consistent with NFP H's grant proposal, the agreement includes specific guidelines for which NFP H could use the assets (for example, to hire 10 tennis instructors or to provide a summer camp for 9 weeks) but does not specify that NFP H's entitlement to the $40,000 is dependent upon NFP H meeting any of the specific indicated guidelines in the agreement. The grant contains a right of return for funds not spent on the tennis program.
605-958-55-70T
NFP H determines that this grant is not conditional because it does not contain a barrier to overcome to be entitled to the transferred assets. Although the grant agreement contains guidelines for how NFP H could spend the $40,000, the agreement does not specify that entitlement to the transferred assets are dependent upon meeting any of the guidelines. Because the guidelines in the grant agreement were not required to be met to be entitled to the funding, the agreement does not contain a barrier to overcome. NFP H should recognize the revenue upon receipt of the assets as donor restricted because it is required to use the assets for the tennis program, which is narrower than NFP H's overall mission.
605-958-55-70U
This Example illustrates the requirements described in paragraph 958-605-50-1A. Those disclosure requirements are not prescriptive on how the information should be disclosed; therefore, this Example demonstrates two alternative formats. This Example does not illustrate all categories of contributed nonfinancial assets, such as intangible assets. An NFP may be required to include disclosure information about valuation techniques and inputs, including assumptions and judgments that an NFP makes, in addition to those included in this Example, which is consistent with the fair value disclosures required by Topic 820. The valuation language used in this Example is not intended to provide guidance on how contributions of nonfinancial assets should be valued, including whether the principal market (or most advantageous market) disclosed is appropriate in the circumstances. While not illustrated in this Example, there may be additional information about the nature and extent of contributed services, including nonrecognized contributed services, that an entity may disclose in accordance with paragraph 958-605-50-1B.
605-958-55-70V
The following illustration includes a table disclosing the amounts recognized within the statement of activities by category as well as a narrative disclosure about donor-imposed restrictions and valuation techniques and inputs for each category of contributed nonfinancial asset.
  • Contributed Nonfinancial Assets "For the years ended December 31, contributed nonfinancial assets recognized within the statement of activities included:" 20X9 20X8 Building Building " $550,000 " $ - Household goods Household goods " 95,556 " " 100,486 " Food Food " 85,407 " " 86,633 " Medical supplies Medical Supplies " 90,389 " " 115,173 " Pharmaceuticals Pharmaceuticals " 111,876 " " 113,982 " Clothing Clothing " 85,765 " " 83,890 " Vehicles Vehicles " 127,900 " - Services Services " 73,890 " " 65,392 " " $1,220,783 " " $565,556 "
  • NFP K recognized contributed nonfinancial assets within revenue, including a contributed building, vehicles, household goods, food, medical supplies, pharmaceuticals, clothing, and services. Unless otherwise noted, contributed nonfinancial assets did not have donor-imposed restrictions.
  • It is NFP K's policy to sell all contributed vehicles immediately upon receipt at auction or for salvage unless the vehicle is restricted for use in a specific program by the donor. No vehicles received during the period were restricted for use. All vehicles were sold and valued according to the actual cash proceeds on their disposition.
  • The contributed building will be used for general and administrative activities. In valuing the contributed building, which is located in Metropolitan Area B, NFP K estimated the fair value on the basis of recent comparable sales prices in Metropolitan Area B's real estate market.
  • Contributed food was utilized in the following programs: natural disaster services, domestic community development, and services to community shelters. Contributed household goods were used in domestic community development and services to community shelters. Contributed clothing was used in specific community shelters. Contributed medical supplies were utilized in natural disaster services. In valuing household goods, food, clothing, and medical supplies, NFP K estimated the fair value on the basis of estimates of wholesale values that would be received for selling similar products in the United States.
  • Contributed pharmaceuticals were restricted by donors to use outside the United States and were utilized in international health services and natural disaster services. In valuing contributed pharmaceuticals otherwise legally permissible for sale in the United States, NFP K used the Federal Upper Limit based on the weighted average of the most recently reported monthly Average Manufacturer Prices (AMP) that approximate wholesale prices in the United States (that is, the principal market). In valuing pharmaceuticals not legally permissible for sale in the United States (and primarily consumed in developing markets), NFP K used third-party sources representing wholesale exit prices in the developing markets in which the products are approved for sale (that is, the principal markets).
  • Contributed services recognized comprise professional services from attorneys advising NFP K on various administrative legal matters. Contributed services are valued and are reported at the estimated fair value in the financial statements based on current rates for similar legal services.
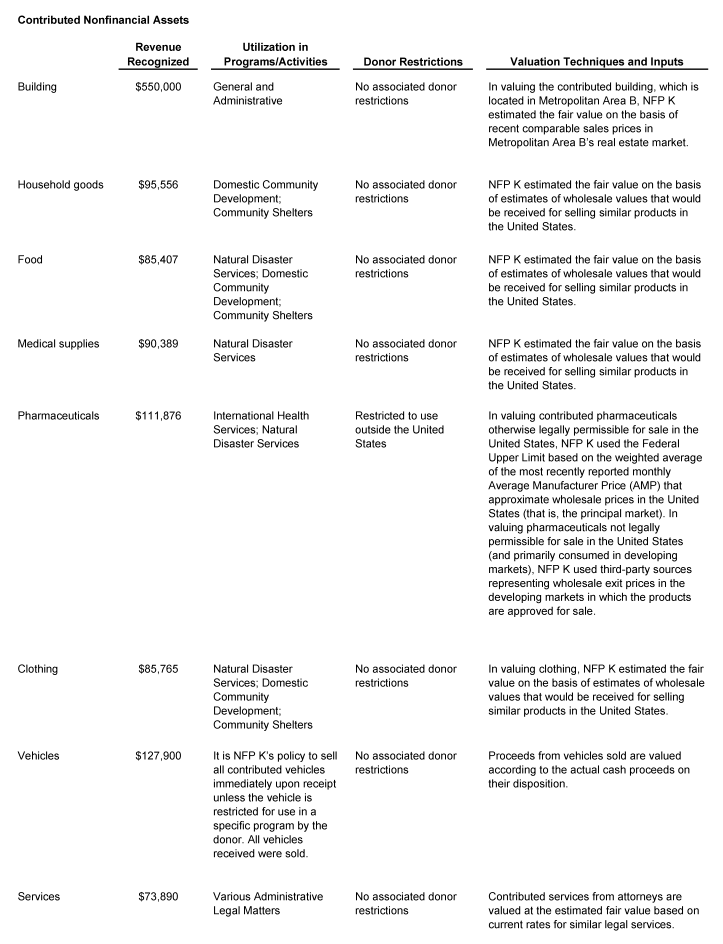
605-958-55-70W
The following table illustrates the disclosures in paragraph 958-605-55-70V for each category of contributed nonfinancial asset. It includes both amounts and narrative disclosure. For illustrative purposes, only one year is presented.
  • Contributed Nonfinancial Assets "Revenue Recognized" Utilization in Programs/Activities Donor Restrictions Valuation Techniques and Inputs Building "$550,000" General and Administrative No associated donor restrictions "In valuing the contributed building, which is located in Metropolitan Area B, NFP K estimated the fair value on the basis of recent comparable sales prices in Metropolitan Area B's real estate market. " Household goods "$95,556" Domestic Community Development; Community Shelters No associated donor restrictions NFP K estimated the fair value on the basis of estimates of wholesale values that would be received for selling similar products in the United States. Food "$85,407" Natural Disaster Services; Domestic Community Development; Community Shelters No associated donor restrictions NFP K estimated the fair value on the basis of estimates of wholesale values that would be received for selling similar products in the United States. Medical supplies "$90,389" Natural Disaster Services No associated donor restrictions NFP K estimated the fair value on the basis of estimates of wholesale values that would be received for selling similar products in the United States. Pharmaceuticals "$111,876" International Health Services; Natural Disaster Services Restricted to use outside the United States "In valuing contributed pharmaceuticals otherwise legally permissible for sale in the United States, NFP K used the Federal Upper Limit based on the weighted average of the most recently reported monthly Average Manufacturer Price (AMP), that approximate wholesale prices in the United States (that is, the principal market). In valuing pharmaceuticals not legally permissible for sale in the United States (and primarily consumed in developing markets), NFP K used third-party sources representing wholesale exit prices in the developing markets in which the products are approved for sale." Clothing "$85,765" Natural Disaster Services; Domestic Community Development; Community Shelters No associated donor restrictions "In valuing clothing, NFP K estimated the fair value on the basis of estimates of wholesale values that would be received for selling similar products in the United States. " Vehicles "$127,900" It is NFP K's policy to sell all contributed vehicles immediately upon receipt unless the vehicle is restricted for use in a specific program by the donor. All vehicles received were sold. No associated donor restrictions Proceeds from vehicles sold are valued according to the actual cash proceeds on their disposition. Services "$73,890" Various Administrative legal matters No associated donor restrictions Contributed services from attorneys are valued at the estimated fair value based on current rates for similar legal services.

Transfers of Assets to a Not-for-Profit Entity or Charitable Trust That Raises or Holds Contributions for Others

Implementation Guidance
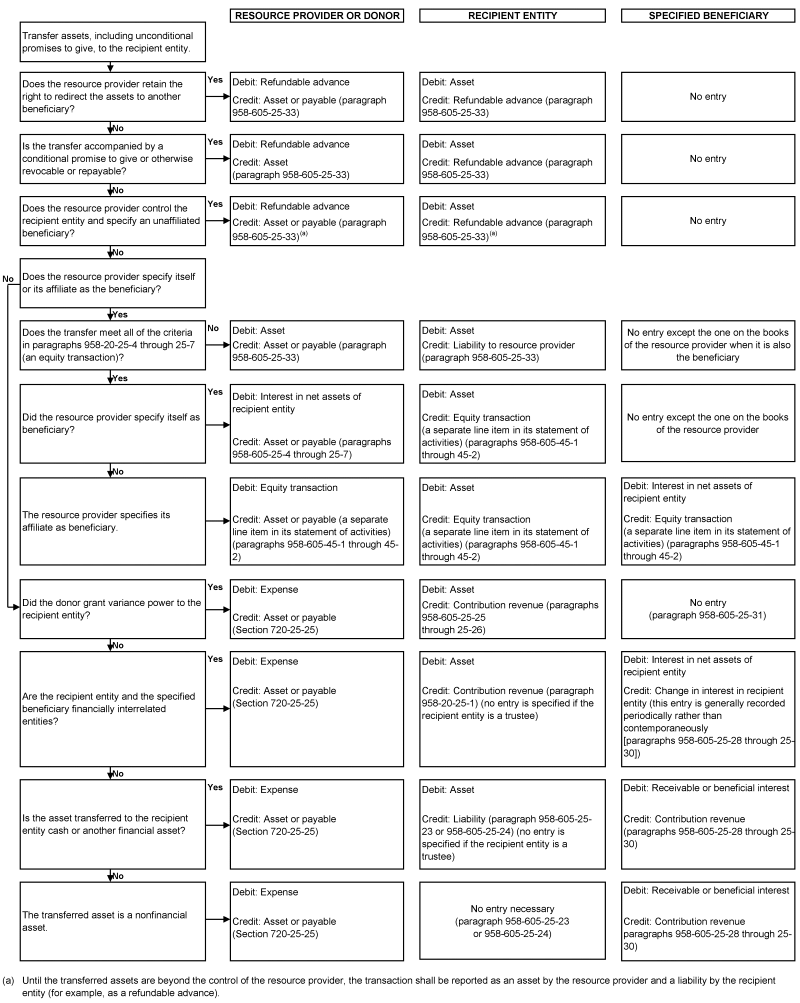
605-958-55-71
A transfer of assets may appear to be a contribution when a donor uses an agent, a trustee, or an intermediary to transfer assets to a donee. Receipts of resources as an agent, trustee, or intermediary of a donor are not contributions received to the agent because the recipient of assets who is an agent or trustee has little or no discretion in determining how the assets transferred will be used. For the same reason, deliveries of resources as an agent, trustee, or intermediary of a donor are not contributions made by the agent. Similarly, contributions of services (time, skills, or expertise) between donors and donees that are facilitated by an intermediary are not contributions received or contributions made by the intermediary.
605-958-55-72
Examples 1 through 11 (see paragraphs ) illustrate the need to assess the relevant facts and circumstances to distinguish between the receipt of resources as a donee and the receipt of resources as an agent, a trustee, or an intermediary organization.
605-958-55-73
The following flowchart is a visual supplement to the written standards. It should not be interpreted to alter any requirements of the Transfers of Assets to a Not-for-Profit Entity or Charitable Trust that Raises or Holds Contributions for Others Subsections or of Subtopic 958-20, nor should it be considered a substitute for those requirements. The relevant paragraphs of the standards are identified in the parenthetical notes. Examples 1 through 11 (see paragraphs ) illustrate the application of the standards in specific situations.
605-958-55-74
The diagram depicts the process for determining the appropriate accounting for a transfer of assets from a donor to a recipient entity that accepts the assets and agrees to use those assets on behalf of a beneficiary specified by the donor or transfer those assets, the return on investment of those assets, or both to a beneficiary specified by the donor. (For additional information about how a beneficiary is specified, see paragraphs .) The diagram also depicts the process for determining the appropriate accounting for a transfer from a resource provider that takes place in a similar manner but is not a contribution because the transfer is revocable, repayable, or reciprocal.
  • RESOURCE PROVIDER OR DONOR RECIPIENT ENTITY SPECIFIED BENEFICIARY "Transfer assets, including unconditional promises to give, to the recipient entity." Does the resource provider retain the right to redirect the assets to another beneficiary? Yes Debit: Refundable advance Debit: Asset No entry Credit: Asset or payable (paragraph 958-605-25-33) Credit: Refundable advance (paragraph 958-605-25-33) No Is the transfer accompanied by a conditional promise to give or otherwise revocable or repayable? Yes Debit: Refundable advance Debit: Asset No entry "Credit: Asset (paragraph 958-605-25-33)" Credit: Refundable advance (paragraph 958-605-25-33) No Does the resource provider control the recipient entity and specify an unaffiliated beneficiary? Yes Debit: Refundable advance Debit: Asset No entry Credit: Asset or payable (paragraph 958-605-25-33)(a) Credit: Refundable advance (paragraph 958-605-25-33)(a) No " No" Does the resource provider control the recipient entity and specify an unaffiliated beneficiary? Yes Does the transfer meet all of the criteria in paragraphs 958-605-25-4 through 25-7 (an equity transaction)? Yes Debit: Asset Debit: Asset No entry except the one on the books of the resource provider when it is also the beneficiary "Credit: Asset or payable (paragraph 958-605-25-33) " Credit: Liability to resource provider (paragraph 958-605-25-33) Yes Did the resource provider specify itself as beneficiary? Yes Debit: Interest in net assets of recipient entity Debit: Asset No entry except the one on the books of the resource provider "Credit: Equity transaction (a separate line item in its statement of activities) (paragraphs 958-605-45-1 through 45-2)" Credit: Asset or payable (paragraphs 958-605-25-4 through 25-7) No The resource provider specifies its affiliate as beneficiary. Debit: Equity transaction Debit: Asset Debit: Interest in net assets of recipient entity Credit: Credit: Asset or payable (a separate line item in its statement of activities) (paragraphs 958-605-45-1 through 45-2) "Credit: Equity transaction (a separate line item in its statement of activities) (paragraphs 958-605-45-1 through 45-2)" "Credit: Equity transaction (a separate line item in its statement of activities) (paragraphs 958-605-45-1 through 45-2)" Did the donor grant variance power to the recipient entity? Yes Debit: Expense Debit: Asset "No entry (paragraph 958-605-25-31)" "Credit: Asset or payable (Section 720-25-25)" "Credit: Contribution revenue (paragraphs 958-605-25-25 through 25-26)" No Are the recipient entity and the specified beneficiary financially interrelated entities? Yes Debit: Expense Debit: Asset Debit: Interest in net assets of recipient entity "Credit: Asset or payable (Section 720-25-25)" Credit: Contribution revenue (paragraph 958-20-25-1) (no entry is specified if the recipient entity is a trustee) "Credit: Change in interest in recipient entity (this entry is generally recorded periodically rather than contemporaneously [paragraphs 958-605-25-28 through 25-30])" No Is the asset transferred to the recipient entity cash or another financial asset? Yes Debit: Expense Debit: Asset Debit: Receivable or beneficial interest "Credit: Asset or payable (Section 720-25-25)" Credit: Liability (paragraph 958-605-25-23 or 958-605-25-24) (no entry is specified if the recipient entity is a trustee) Credit: Contribution revenue (paragraphs 958-605-25-28 through 25-30) No The transferred asset is a nonfinancial asset. Debit: Expense "No entry necessary (paragraph 958-605-25-23 or 958-605-25-24)" Debit: Receivable or beneficial interest "Credit: Asset or payable (Section 720-25-25)" Credit: Contribution revenue paragraphs 958-605-25-28 through 25-30) (a) "Until the transferred assets are beyond the control of the resource provider, the transaction shall be reported as an asset by the resource provider and a liability by the recipient entity (for example, as a refundable advance)."
605-958-55-75
Discretion to determine the timing of the distribution to the specified beneficiary, by itself, does not give the recipient entity discretion sufficient to recognize a contribution. That limited discretion is not sufficient. The ability to choose a payment date does not relieve an entity from its obligation to pay.
605-958-55-76
A recipient entity has discretion sufficient to recognize a contribution received if it can choose the beneficiaries of the assets. For example, if a recipient receives cash that it must disburse to any who meet guidelines specified by a resource provider or return the cash, those receipts may be deposits held by the recipient as an agent rather than contributions received as a donee. Similarly, if a recipient receives cash that it must disburse to individuals identified by a resource provider or return the cash, neither the receipt nor the disbursement is a contribution for the agent, trustee, or intermediary. In contrast, if a resource provider allows the recipient to establish, define, and carry out the programs that disburse the cash, products, or services to the recipient's beneficiaries, the recipient generally is involved in receiving and making contributions.
605-958-55-77
Thus, if a donor uses broad generalizations to describe beneficiaries or to indicate a field of interest, such as Midwestern flood victims, homeless individuals, or teenaged children, the recipient entity has the ability to choose the beneficiaries of the assets and is a donee. Similarly, the recipient entity has the ability to choose the beneficiaries if neither the language used by the donor nor the representations of the recipient entity cause the donor to believe that it can direct the gift to a specified beneficiary. For example, a recipient entity might request that a donor indicate a not-for-profit entity (NFP) that best serves the needs of the community and tell the donor that the information will be considered by the allocation committee when it makes its distributions to NFPs in the community. If that request is conveyed in a manner that leads a donor to reasonably conclude that its role is merely to propose a possible allocation, the recipient entity has the discretion to choose the beneficiary of the assets.
605-958-55-78
Conversely, if that request is conveyed in a manner that creates a donor's reasonable expectation that the gift will be used for the benefit of or will be transferred to the indicated beneficiary, the recipient entity does not have discretion to choose the beneficiary unless the donor explicitly grants variance power. (See the following paragraph and paragraph 958-605-25-25.) A donor may specify the beneficiary by name, by stating that all entities that meet a set of donor-defined criteria are beneficiaries, or by actions surrounding the transfer that make clear the identity of the beneficiary, such as by responding to a request from a recipient entity that exists to raise assets for the beneficiary.
605-958-55-79
A recipient entity may obtain the power to redirect the use of assets transferred to it through various means, including standard provisions in donor-choice forms or explicit donor stipulation in gift instruments. For example, a community foundation may obtain the unilateral power to redirect the use of assets transferred to them through explicit reference to the variance power granted to them by donors in written gift instruments. The variance power may be explicitly referred to in the terms of the gift instrument and further explained in the community foundation's declaration of trust, articles of incorporation, or governing instruments.

Illustrations

605-958-55-80
This Example illustrates the guidance in paragraphs . Not-for-Profit Entity A (NFP A) receives relief supplies from Individual with instructions to deliver the supplies to specified third-party beneficiaries. NFP A accepts responsibility for delivering those supplies because it has a distribution network and a mutual interest in serving the needs of the specified beneficiaries. NFP A has no discretion in determining the parties to be benefited; it must deliver the resources to the specified beneficiaries. Receipt of those goods is not a contribution received to NFP A, nor is the delivery of those goods to the beneficiaries a contribution made by NFP A. Rather, a contribution of goods is made by Individual and received by the third-party beneficiaries.
605-958-55-81
This Example illustrates the guidance in paragraph 958-605-25-23. Not-for-Profit Entity B (NFP B) develops and maintains a list of lawyers and law firms that are interested in providing services without charge to charitable organizations and certain individuals. NFP B encourages individuals in need of free legal services to contact NFP B for referral to lawyers in the individual's community that may be willing to serve them. The decision about whether and how to serve a specific individual rests with the lawyer. Under those circumstances, NFP B merely acts as an intermediary in bringing together a willing donor and donee. The free legal services are not a contribution received by NFP B.
605-958-55-83
This Example illustrates the guidance in paragraphs .
605-958-55-84
Federated Fundraising Organization D provides three choices to donors in its annual workplace campaign. Donors can give without restriction, direct their gifts to one of four community needs identified by Federated Fundraising Organization D, or specify that their gifts be transferred to an NFP of their choice. The campaign literature informs donors that if they choose to specify an NFP to which their gift should be transferred, the NFP must be a social welfare organization within the community that has tax-exempt status under Internal Revenue Code Section 501(c)(3). The campaign literature also provides a schedule of the administrative fees that will be deducted from all gifts that are to be transferred to the donor's chosen beneficiary.
605-958-55-85
Federated Fundraising Organization D would recognize the following transactions:
  1. a
    It would recognize the fair values of the gifts without donor restrictions as contribution revenue that increases net assets without donor restrictions.
  2. b
    It would recognize the fair values of the gifts targeted to the four specified community needs as contribution revenue that increases net assets with donor restrictions.
  3. c
    It would recognize the fair values of gifts that are to be transferred to beneficiaries chosen by the donors as increases in its assets and as liabilities to those specified beneficiaries (see paragraph 958-605-25-24).
  4. d
    It would recognize as revenue the administrative fees withheld from amounts to be transferred to the donors' chosen beneficiary.
However, if some of the gifts that are intended for specified beneficiaries are gifts of nonfinancial assets, Federated Fundraising Organization D would recognize those nonfinancial assets and its liability to transfer them to the specified beneficiaries if that were its policy; otherwise, it would recognize neither the nonfinancial assets nor a liability (see paragraph 958-605-25-24).
605-958-55-86
The beneficiaries chosen by the donors would recognize the fair value of the transferred assets as contribution revenue in accordance with the provisions of paragraph 958-605-45-6 for unconditional promises to give. Thus, the revenue would increase net assets with donor restrictions or net assets without donor restrictions, depending on the existence or absence of donor-imposed restrictions. For example, if a donor specified that the transferred assets must be maintained in perpetuity, the revenue would increase net assets with donor restrictions. However, if the donor specified that the transferred assets are for current-period use, the revenue would increase net assets without donor restrictions. In accordance with paragraph 958-220-45-14, the beneficiaries would report the gross amounts of the gifts as contribution revenue and the administrative fees withheld by Federated Fundraising Organization D as expenses. The net amount would be recognized as a receivable (see paragraph 958-605-25-28).
605-958-55-87
Instead of conducting the campaign as described in this Example, Federated Fundraising Organization D's campaign literature, including the form that donors use to specify a beneficiary, clearly states that if donors choose to give and specify a beneficiary, the allocation committee has the authority to redirect their gifts if the committee perceives needs elsewhere in the community that are greater. By giving under those terms, donors explicitly grant Federated Fundraising Organization D variance power. Thus, Federated Fundraising Organization D would recognize as contribution revenue without donor-imposed restrictions (see paragraph 958-605-25-25), and the specified beneficiaries would be precluded from recognizing their potential for future distributions from the assets (see paragraph 958-605-25-31).
605-958-55-88
This Example illustrates the guidance in paragraphs .
605-958-55-89
The governing board of City Botanical Society E decides to raise funds to build an endowment. The governing board signs an agreement to establish a fund at Community Foundation F. Community Foundation F and City Botanical Society E are not financially interrelated entities. City Botanical Society E solicits gifts to the fund. The campaign materials inform donors that the endowment will be owned and held by Community Foundation F. The materials explain that the gifts will be invested and that the return from their investment will be distributed to City Botanical Society E, subject to Community Foundation F's spending policy and to Community Foundation F's right to redirect the return to another beneficiary without the approval of the donor, City Botanical Society E, or any other party if distributions to City Botanical Society E become unnecessary, impossible, or inconsistent with the needs of the community. The donor-response card also clearly describes Community Foundation F's right to redirect the return of the fund. The campaign materials indicate that donors should send their contributions to Community Foundation F using a preaddressed envelope included for that purpose.
605-958-55-90
Community Foundation F would recognize the fair value of gifts received as assets and as contribution revenue. The donors explicitly granted variance power by using a donor-response card that clearly states that gifts are subject to Community Foundation F's unilateral power to redirect the return to another beneficiary (see paragraph 958-605-25-25).
605-958-55-91
City Botanical Society E is precluded from recognizing its potential rights to the assets held by Community Foundation F because the donors explicitly granted variance power (see paragraph 958-605-25-31). City Botanical Society E would recognize only its annual grants from Community Foundation F as contributions.
605-958-55-92
Whether a donor intended to make a contribution to Community Foundation F may not be clear if the donor responds to the campaign materials by sending a contribution and the donor-response card directly to City Botanical Society E. City Botanical Society E could resolve the ambiguity by a review of the facts and circumstances surrounding the gift, communications with the donor, or both. If it is ultimately determined that the donor intended to make a gift to the fund owned and held by Community Foundation F and to explicitly grant variance power, City Botanical Society E would be an agent responsible for transferring that gift to Community Foundation F (see paragraph 958-605-25-24).
605-958-55-93
This Example illustrates the guidance in paragraph 958-605-25-23.
605-958-55-94
Local Church G transfers cash to Seminary H and instructs Seminary H to use the money to grant a scholarship to Individual, who is a parishioner of Local Church G.
605-958-55-95
Seminary H would recognize the cash and a liability to Individual in the same amount because it merely is facilitating the cash transfer from Local Church G to Individual (see paragraph 958-605-25-23).
605-958-55-96
This Example illustrates the guidance in paragraph 958-605-15-9.
605-958-55-97
Individual transfers assets to National Bank J to establish an irrevocable charitable trust for the sole benefit of Museum I. National Bank J will serve as trustee. Individual sets forth in the trust agreement the policies that direct the economic activities of the trust. The trust term is five years. Each year, the income received on the investments of the trust will be distributed to Museum I. At the end of Year 5, the corpus of the trust (original assets and net appreciation on those assets) will be paid to Museum I.
605-958-55-98
The Contribution Received Subsections of this Subtopic do not establish standards for the trustee, National Bank J (see paragraph 958-605-15-9). Because Museum I is unable to influence the operating or financial decisions of the trustee, Museum I and National Bank are not financially interrelated entities. Therefore, Museum I would recognize its asset (a beneficial interest in the trust) and contribution revenue that increases net assets with donor restrictions (see paragraph 958-605-35-3). Museum I would measure its beneficial interest at fair value. That value generally can be measured by the fair value of the assets contributed to the trust.
605-958-55-99
This Example illustrates the guidance in paragraph 958-20-15-2.
605-958-55-100
Some foundations and associations raise contributions for a large number of unaffiliated NFPs, often referred to as member organizations. By virtue of their numbers, those member organizations generally do not individually influence the operating and financial decisions of the foundation (or association). Thus, any one member organization and the foundation (or association) are not financially interrelated entities (see paragraph 958-20-15-2[a]). Because the entities are not financially interrelated, the foundation (or association) recognizes a liability if a donor to the foundation (or association) specifies that the gift should be transferred to a particular member organization (see paragraph 958-605-25-4). The specified member organization would recognize a receivable and contribution revenue that increases net assets with donor restrictions or net assets without donor restrictions, depending on the existence or absence of donor-imposed restrictions.
605-958-55-101
This Example illustrates the guidance in paragraph 958-605-25-4.
605-958-55-102
Individual transfers a car to Federated Fundraising Organization K and requests that the car be transferred to Local Daycare Center L. Individual specifies that Federated Fundraising Organization K may use the car for one year before transferring it to Local Daycare Center L. Local Daycare Center L is a member organization of Federated Fundraising Organization K, but that status does not confer any ability to actively participate in the policymaking processes of Federated Fundraising Organization K.
605-958-55-103
Because Federated Fundraising Organization K and Local Daycare Center L are not financially interrelated entities, Federated Fundraising Organization K would recognize the car as an asset and a liability to Local Daycare Center L if its policy were to recognize nonfinancial assets; otherwise, it would recognize neither the nonfinancial assets nor a liability (see paragraph 958-605-25-24).
605-958-55-104
If, instead of refusing the gift of the use of the car, Federated Fundraising Organization K decides to use it for a year before transferring it to Local Daycare Center L, Federated Fundraising Organization K would recognize the fair value of the gift of one-year's use of the car in accordance with paragraph 958-605-30-2. The use of a car is a contributed asset and not a contributed service.
605-958-55-105
Local Daycare Center L would recognize a receivable and contribution revenue that increases net assets with donor restrictions (see paragraph 958-605-25-30). It would measure the contribution received at the fair value of the car; however, if Federated Fundraising Organization L chooses to use the car for a year before transferring it, the fair value would be reduced accordingly.
605-958-55-106
This Example illustrates the guidance in paragraph 958-605-25-33.
605-958-55-107
Symphony Orchestra M receives a large gift without donor restrictions of securities from Individual. Because it has no investment expertise, Symphony Orchestra M transfers the securities to Community Foundation N to establish an endowment fund. The agreement between Symphony Orchestra M and Community Foundation N states that the transfer is irrevocable and that the transferred assets will not be returned to Symphony Orchestra M. However, Community Foundation N will make annual distributions of the income earned on the endowment fund, subject to Community Foundation N's spending policy. The agreement also permits Community Foundation N to substitute another beneficiary in the place of Symphony Orchestra M if Symphony Orchestra M ceases to exist or if the governing board of Community Foundation N votes that support of Symphony Orchestra M either is no longer necessary or is inconsistent with the needs of the community. (That is, Symphony Orchestra M explicitly grants variance power to Community Foundation N.) The agreement does not permit either entity to appoint members to the other entity's governing board or otherwise participate in the policymaking processes of the other.
605-958-55-108
Community Foundation N would recognize the fair value of the transferred securities as an increase in investments and a liability to Symphony Orchestra M because Symphony Orchestra M transferred assets to Community Foundation N and specified itself as beneficiary (see paragraph 958-605-25-33(d)). The transfer is not an equity transaction because Community Foundation N and Symphony Orchestra M are not financially interrelated entities (see paragraph 958-20-25-4(b)). Symphony Orchestra M is unable to influence the operating or financial decisions of Community Foundation N (see paragraph 958-20-15-2(a)).
605-958-55-109
Symphony Orchestra M would recognize the fair value of the gift of securities from Individual as contribution revenue. When it transfers the securities to Community Foundation N, it would recognize the transfer as a decrease in investments and an increase in an asset, for example, as a beneficial interest in assets held by Community Foundation N (see paragraph 958-605-25-33(d)). Also, Symphony Orchestra M would disclose in its financial statements the identity of Community Foundation N, the terms under which Community Foundation N will distribute amounts to Symphony Orchestra M, a description of the variance power granted to Community Foundation N, and the aggregate amount reported in the statement of financial position and how that amount is described (see paragraph 958-605-50-6).
605-958-55-110
If a resource provider transfers assets to a recipient entity and specifies itself or its affiliate as the beneficiary, a presumption that the transfer is reciprocal, and therefore not a contribution, is necessary even if the resource provider explicitly grants the recipient entity variance power. Thus, Symphony Orchestra M would recognize an asset and Community Foundation N would recognize a liability because the transaction is deemed to be reciprocal. Symphony Orchestra M transfers its securities to Community Foundation N in exchange for future distributions. Community Foundation N, by its acceptance of the transfer, agrees that at the time of the transfer distributions to Symphony Orchestra M are capable of fulfillment and consistent with the foundation's mission. Although the fair value of those future distributions may not be commensurate with the fair value of the securities given up (because Symphony Orchestra M is at risk of cessation of the distributions), the transaction is accounted for as though those values are commensurate. In comparison, the donors to Community Foundation F in Example 5 (see paragraph 958-605-55-88) explicitly grant variance power to Community Foundation F in a nonreciprocal transfer. In that Example, it is clear that the donors have made a contribution because they retain no beneficial interests in the transferred assets. Because the donors in that Example explicitly grant variance power to Community Foundation F, it, rather than City Botanical Society E, is the recipient of that contribution.
605-958-55-111
This Example illustrates the guidance in paragraph 958-605-25-33.
605-958-55-112
The governing board of Private Elementary School O creates a foundation to hold and manage the school's investments. It transfers its investment portfolio to the newly created PES Foundation P. An agreement between Private Elementary School O and PES Foundation P allows the school to request distributions from both the original investments and the return on those investments, subject to approval by the governing board of PES Foundation P, which will not be unreasonably withheld. The agreement also permits Private Elementary School O to transfer additional investments in the future.
605-958-55-113
PES Foundation P would recognize the fair value of the investments as assets and a liability to Private Elementary School O because Private Elementary School O transferred assets to PES Foundation P and specified itself as beneficiary (see paragraph 958-605-25-33[d]). The transfer of assets is not an equity transaction because Private Elementary School O expects repayment of the transferred assets, and thus the transaction does not meet the criterion in paragraph 958-20-25-4(c).
605-958-55-114
Private Elementary School O would decrease its investments and recognize another asset, for example, a beneficial interest in assets held by PES Foundation P (see paragraph 958-605-25-33[d]). Also, Private Elementary School O would disclose in its financial statements the identity of PES Foundation P, the terms of the agreement under which it can receive future distributions, including the fact that the distributions are not subject to variance power, and the aggregate amount reported in the statement of financial position and how that amount is described (see paragraph 958-605-50-6).
605-958-55-115
See Subtopic 958-20 if Private Elementary School O and PES Foundation P are financially interrelated entities.

Related subtopics