ASC 310-958
Not-for-Profit Entities
310 Receivables
Source downloaded: .Record version 9d26d9a4d86f. Effective date must be checked in the source.
This subtopic governs contributions (promises to give) receivable — a receivable unique to not-for-profit entities — focusing on subsequent measurement, presentation, and disclosure after initial recognition under 958-605. Unconditional promises are recognized as an asset and revenue when received (with verifiable documentation), measured initially under 958-605-30-4 through 30-8, and thereafter either at fair value under the 825-10 fair value option or under the change-in-value rules in Section 35 (interest accretion is contribution revenue; decreases in expected assets are bad debt expense/loss; increases generally are not recognized except as recovery of previously recognized bad debts).
Key points (7)
- A promise to give is a written or oral agreement to contribute cash or other assets; an unconditional promise is recognized as revenue or gain and as an asset in the period received, but only with sufficient verifiable documentation (310-958-25-1; 958-605-25-2).
- An NFP may irrevocably elect the fair value option of Subtopic 825-10 for most receivables; if a present value technique is used, discount rate and other assumptions are updated each measurement date, and donor restrictions specific to the donee affect net asset classification, not fair value (310-958-35-1).
- Subsequent accruals of the interest element on promises measured at present value are reported as contribution revenue (835-30-35), and as an increase in net assets with donor restrictions if the underlying promise is donor restricted (310-958-35-6; 45-2).
- Decreases in value from changes in the quantity or nature of assets expected to be received are recognized in the period the expectation changes as bad debt expense or loss; increases are not recognized except as a recovery to the extent bad debt expense or loss was previously recognized (310-958-35-7 through 35-9).
- For promises to give securities with readily determinable fair values or debt securities, observed changes in the underlying fair value are recognized as increases or decreases in contribution revenue; for other noncash assets, only decreases are recognized — increases are not (310-958-35-11 through 35-13).
- Contributions receivable are reported net of the present value discount, with the discount separately disclosed on the face of the statement of financial position or in the notes (310-958-45-1).
- Required disclosures include amounts receivable in less than one year, one to five years, and more than five years, the allowance for uncollectible promises, the unamortized discount, and, for conditional promises, the total promised plus a description and amount of each group with similar characteristics (310-958-50-1; 50-4).
For students. Exam questions love the asymmetry: declines in the expected quantity/nature of promised assets (and declines in the future fair value of promised noncash assets) hit income, but increases generally do not — except as a recovery of previously recognized bad debt, or for promised marketable securities where both increases and decreases run through contribution revenue. A common mistake is reflecting donor-imposed restrictions in the fair value measurement instead of in the net asset classification.
Machine-generated study aid for ASC 310-958. Check the source paragraphs below.
310-958-00Status
Source downloaded: .Record version 25f25dcad36a. Effective date must be checked in the source.
310-958-05Overview and Background
Source downloaded: .Record version bcb3e931b207. Effective date must be checked in the source.
310-958-15Scope and Scope Exceptions
Source downloaded: .Record version ccb49dd6c26c. Effective date must be checked in the source.
Overall Guidance
310-958-25Recognition
Source downloaded: .Record version bb6acb35a203. Effective date must be checked in the source.
Contributions Receivable
310-958-30Initial Measurement
Source downloaded: .Record version 356a7e5dcd77. Effective date must be checked in the source.
Contributions Receivable
310-958-35Subsequent Measurement
Source downloaded: .Record version 1e68cb703d6c. Effective date must be checked in the source.
Fair Value Measurement
Receivables from Exchange Transactions
| Editor's Note: Paragraph 958-310-35-3 will be superseded upon transition, together with its heading. |
| > Receivables from Exchange Transactions |
Contributions Receivable
- aAccrual of the interest element for a promise to give measured using present value techniques
- bChanges in the quantity or nature of assets expected to be received (such as changes in the amounts of future cash flows)
- cChanges in the projected fair value of the underlying noncash assets at the date that those assets are expected to be received (referred to in this Section as the future fair value of underlying noncash assets)
- dChanges in the timing of assets expected to be received (This Subtopic does not provide guidance for changes in the timing of assets expected to be received.)
- eChanges in the time value of money.
310-958-45Other Presentation Matters
Source downloaded: .Record version b118eeb758a8. Effective date must be checked in the source.
Contributions Receivable—Statement of Financial Position
Contributions Receivable—Statement of Activities
310-958-50Disclosure
Source downloaded: .Record version aac933ed0b70. Effective date must be checked in the source.
Contributions Receivable
- a The amounts of promises receivable in less than one year, in one to five years, and in more than five years
- b The amount of the allowance for uncollectible promises receivable
- c The discount that arises if measuring a promise to give at present value, if that discount is not separately disclosed by reporting it as a deduction from contributions receivable on the face of a statement of financial position pursuant to paragraph 958-310-45-1.
- aDisclosures required by paragraphs and in the format described in paragraph 820-10-50-8
- bDisclosures required by paragraphs
- cDisclosures required by paragraph 825-10-50-32, if an election to report unconditional promises to give is made after initial recognition pursuant to paragraph 825-10-25-4(e).
Conditional Promises to Give
- a The total of the amounts promised
- b A description and amount for each group of promises having similar characteristics, such as amounts of promises conditioned on establishing new programs, completing a new building, and raising matching gifts by a specified date.
310-958-55Implementation Guidance and Illustrations
Source downloaded: .Record version 8b561a888590. Effective date must be checked in the source.
Illustrations
-
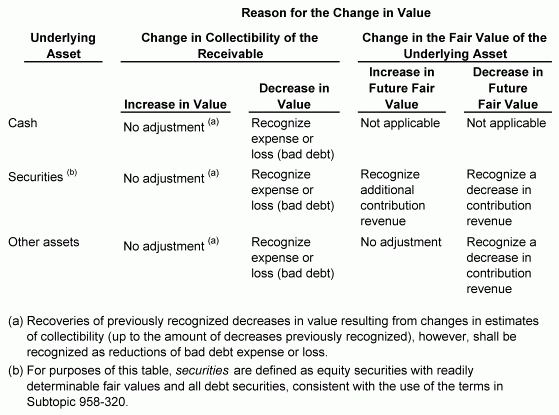 Reason for the Change in Fair Value Underlying Asset Change in Collectibility of the Receivable Change in the Fair Value of the Underlying Asset Increase in Fair Value Decrease in Fair Value Increase in Future Fair Value "Decrease in Future Fair Value" Cash No adjustment (a) Recognize expense or loss (bad debt) Not applicable Not applicable Securities (b) No adjustment (a) Recognize expense or loss (bad debt) Recognize additional contribution revenue Recognize a decrease in contribution revenue Other assets No adjustment (a) Recognize expense or loss (bad debt) No adjustment Recognize a decrease in contribution revenue (a) "Recoveries of previously recognized decreases in fair value resulting from changes in estimates of collectibility (up to the amount of decreases previously recognized), however, shall be recognized as reductions of bad debt expense or loss." (b) "For purposes of this table, securities are defined as equity securities with readily determinable fair values and all debt securities, consistent with the use of the terms in Subtopic 958-320."
Related subtopics
- 405-958 Not-for-Profit EntitiesLiabilities
- 605-958 Not-for-Profit EntitiesRevenue Recognition
- 720-25 Contributions MadeOther Expenses
- 325-958 Not-for-Profit EntitiesInvestments—Other
- 320-958 Not-for-Profit EntitiesInvestments—Debt Securities
- 205-958 Not-for-Profit EntitiesPresentation of Financial Statements