ASC 310-948
Financial Services—Mortgage Banking
310 Receivables
Source downloaded: .Record version c697e1284f72. Effective date must be checked in the source.
This subtopic governs how mortgage banking entities account for mortgage loans and mortgage-backed securities, including classification as held for sale versus held for long-term investment, related origination fees and costs, and transactions with affiliates. Loans held for sale are carried at the lower of amortized cost basis or fair value through a valuation allowance charged to income, while loans held for long-term investment are carried at amortized cost basis with credit losses measured under Subtopic 326-20. Transfers between classifications require reversal in earnings of any previously recorded allowance and re-measurement under the new classification.
Key points (7)
- A mortgage loan may be classified as a long-term investment only if the entity has both the ability and the intent to hold it for the foreseeable future or until maturity, and the transfer occurs on the transfer date (310-948-25-1); such loans are measured at amortized cost basis (310-948-30-4).
- For loans held for resale, origination fees and direct loan origination costs are deferred until the loan is sold; for loans held for investment they are deferred and recognized as a yield adjustment under 310-20-35-18 and 310-20-35-21 through 35-26 (310-948-25-3).
- Mortgage loans held for sale are reported at the lower of amortized cost basis or fair value at the balance sheet date, with any excess of amortized cost over fair value recorded as a valuation allowance whose changes flow through net income; purchase discounts are not amortized as interest revenue while held for sale (310-948-35-1; 310-948-35-2).
- Fair value of loans held for sale is measured by type of loan (residential and commercial separately, on an aggregate or individual basis), with committed loans valued based on investor commitments and uncommitted loans valued in the principal or most advantageous market under Topic 820 (310-948-35-3).
- On transfer from held-for-long-term-investment to held-for-sale, the entity reverses any allowance for credit losses in earnings, transfers the loan at amortized cost basis, and then assesses whether a valuation allowance is needed; the reverse process applies for transfers into held-for-long-term-investment (310-948-35-2A; 310-948-35-5A).
- Mortgage loans to be sold to an affiliate are adjusted to the lower of amortized cost basis or fair value as of the date management decides the sale will occur, with the adjustment charged to income; loans originated exclusively for an affiliate are transferred at the originator's acquisition cost because the originator acts as agent (310-948-30-1; 310-948-30-2).
- After securitization qualifying as a sale under 860-10-40-5, MBS received as proceeds are classified under Topic 320, except that MBS committed to be sold before or during securitization must be classified as trading (310-948-40-1); the balance sheet must distinguish held-for-sale from held-for-investment loans, transfer-related allowance amounts must be presented gross, and the aggregate-or-individual method must be disclosed (310-948-45-1; 310-948-45-2; 310-948-50-1).
For students. The classification decision (held for sale vs. held for long-term investment) drives everything: fee deferral, measurement basis, and whether you record a valuation allowance or a CECL allowance. A common misunderstanding is treating transfers between classifications as simple reclassifications — the prior allowance must be reversed in earnings and presented gross, not netted.
Machine-generated study aid for ASC 310-948. Check the source paragraphs below.
310-948-00Status
Source downloaded: .Record version 5d2abc8a941c. Effective date must be checked in the source.
310-948-05Overview and Background
Source downloaded: .Record version c28c1decfd7c. Effective date must be checked in the source.
310-948-15Scope and Scope Exceptions
Source downloaded: .Record version 20bb065ea064. Effective date must be checked in the source.
Overall Guidance
310-948-25Recognition
Source downloaded: .Record version 3f4278426728. Effective date must be checked in the source.
Loans Held as Long-Term Investments
Fees and Costs
310-948-30Initial Measurement
Source downloaded: .Record version 50f234b71f9c. Effective date must be checked in the source.
Affiliated Transactions
Loans Held as Long-Term Investments
310-948-35Subsequent Measurement
Source downloaded: .Record version 389841f4ad34. Effective date must be checked in the source.
Loans Held for Sale
- aCommitted loans. Mortgage loans covered by investor commitments shall be based on the fair values of the loans.
- bUncommitted loans. Fair value for uncommitted loans shall be based on principal market or, in the absence of a principal market, in the most advantageous market (see paragraphs 820-10-35-5 through 35-6C). That determination relies on the principles in Topic 820 and would include consideration of the following:
- 1Market prices and yields sought by market participants in the principal or most advantageous market
- 2Quoted Government National Mortgage Association (GNMA) security prices or other public market quotations for long-term mortgage loan rates
- 3Federal Home Loan Mortgage Corporation (FHLMC) and Federal National Mortgage Association (FNMA) current delivery prices.
- 1
- c
Loans Held as Long-Term Investments
Other Considerations
310-948-40Derecognition
Source downloaded: .Record version fe08dead982c. Effective date must be checked in the source.
Securitization of a Mortgage Loan Held for Sale
310-948-45Other Presentation Matters
Source downloaded: .Record version 46075faf8512. Effective date must be checked in the source.
310-948-50Disclosure
Source downloaded: .Record version d02a5b7ea317. Effective date must be checked in the source.
310-948-60Relationships
Source downloaded: .Record version 41979884208c. Effective date must be checked in the source.
Receivables
Not-for-Profit Entities
310-948-S00StatusSEC
Source downloaded: .Record version cf0bdad33b0d. Effective date must be checked in the source.
| Paragraph | Action | Accounting Standards Update | Date |
| 948-310-S99-1 | Amended | Accounting Standards Update No. 2019-07 | 07/26/2019 |
310-948-S50DisclosureSEC
Source downloaded: .Record version 7a1d8f46bd42. Effective date must be checked in the source.
Supplemental Schedule
310-948-S99SEC MaterialsSEC
Source downloaded: .Record version 9e8439f60bea. Effective date must be checked in the source.
SEC Rules, Regulations, and Interpretations
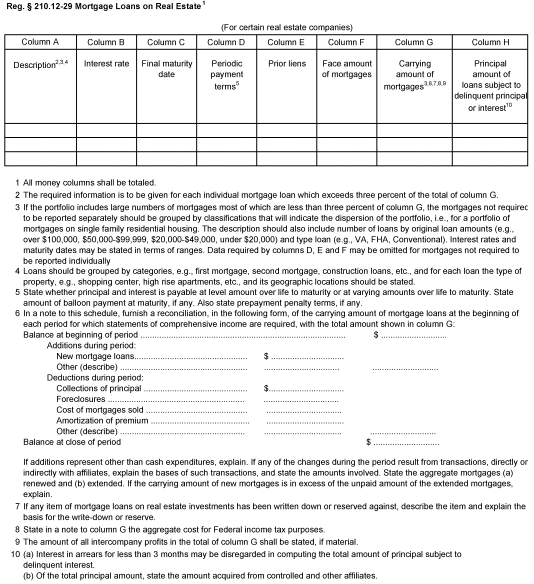 Reg. § 210.12-29 Mortgage Loans on Real Estate 1 (For certain real estate companies) Column A Column B Column C Column D Column E Column F Column G Column H "Description2,3,4" Interest rate Final maturity date Periodic payment terms5 Prior liens Face amount of mortgages "Carrying amount of mortgages3,6,7,8,9 " "Principal amount of loans subject to delinquent principal or interest10" 1 All money columns shall be totaled. 2 The required information is to be given for each individual mortgage loan which exceeds three percent of the total of column G. 3 "If the portfolio includes large numbers of mortgages most of which are less than three percent of column G, the mortgages not required to be reported separately should be grouped by classifications that will indicate the dispersion of the portfolio, i.e., for a portfolio of mortgages on single family residential housing. The description should also include number of loans by original loan amounts (e.g., over $100,000, $50,000-$99,999, $20,000-$49,000, under $20,000) and type loan (e.g., VA, FHA, Conventional). Interest rates and maturity dates may be stated in terms of ranges. Data required by columns D, E and F may be omitted for mortgages not required to be reported individually." 4 "Loans should be grouped by categories, e.g., first mortgage, second mortgage, construction loans, etc., and for each loan the type of property, e.g., shopping center, high rise apartments, etc., and its geographic locations should be stated." 5 "State whether principal and interest is payable at level amount over life to maturity or at varying amounts over life to maturity. State amount of balloon payment at maturity, if any. Also state prepayment penalty terms, if any." 6 "In a note to this schedule, furnish a reconciliation, in the following form, of the carrying amount of mortgage loans at the beginning of each period for which statements of comprehensive income are required, with the total amount shown in column G: Balance at beginning of period ....................................................................................... $ ............................ Additions during period: New mortgage loans................................................ $ ............................... Other (describe) ...................................................... ................................ ............................ Deductions during period: Collections of principal ............................................ $................................ Foreclosures .......................................................... ................................ Cost of mortgages sold ........................................... ................................ Amortization of premium .......................................... ................................. Other (describe) ..................................................... ................................. ............................ Balance at close of period $ ............................" "If additions represent other than cash expenditures, explain. If any of the changes during the period result from transactions, directly or indirectly with affiliates, explain the bases of such transactions, and state the amounts involved. State the aggregate mortgages (a) renewed and (b) extended. If the carrying amount of new mortgages is in excess of the unpaid amount of the extended mortgages, explain." 7 "If any item of mortgage loans on real estate investments has been written down or reserved against, describe the item and explain the basis for the write-down or reserve." 8 State in a note to column G the aggregate cost for Federal income tax purposes. 9 "The amount of all intercompany profits in the total of column G shall be stated, if material." 10 "(a) Interest in arrears for less than 3 months may be disregarded in computing the total amount of principal subject to delinquent interest. (b) Of the total principal amount, state the amount acquired from controlled and other affiliates."