ASC 310-976
Real Estate—Retail Land
310 Receivables
Source downloaded: .Record version 4ea4105f101f. Effective date must be checked in the source.
This subtopic governs the measurement, derecognition, and disclosure of receivables arising from retail land sales. Its core rule is that an allowance for contract cancellations must be provided for receivables not expected to be collected because of cancellation, estimated from historical collection data drawn from a representative, current sample covering an adequate period (310-976-35-1). Cancelled contract receivable balances are charged in full against that allowance (310-976-40-1), and specified receivable disclosures are required (310-976-50-1).
Key points (7)
- An allowance shall be provided for retail land sale receivables not expected to be collected because of cancellation in subsequent periods (310-976-35-1).
- The estimate must be based on historical data from a representative sample of receivables reflecting the latest available collection data and covering an adequate period of time (310-976-35-1).
- Sampled receivables with payments unpaid at the end of the sample period for the specified delinquency periods are treated as uncollectible, and the allowance for previously recognized sales is adjusted accordingly (310-976-35-1).
- The specified delinquency periods may be extended if the seller's recent experience has been better, or if the buyer has accepted or will accept personal liability on the debt and the buyer's ability to complete payment can be determined (310-976-35-2).
- When contracts are cancelled, the related receivable balances are charged in their entirety to the allowance for contract cancellations (310-976-40-1).
- Required disclosures are maturities of accounts receivable for each of the five years following the balance sheet date, delinquent accounts receivable and the method(s) of determining delinquency, and the weighted average and range of stated interest rates (310-976-50-1).
- Certain measurement paragraphs (310-976-30-1 and 35-3) were superseded by ASU 2014-09, which moved retail land sale revenue recognition into the ASC 606 framework.
For students. This is a narrow industry-specific pocket of guidance: the key idea is that cancellation risk on retail land contracts is handled through a dedicated allowance estimated from delinquency sampling, not through general credit-loss judgment. A common misunderstanding is thinking ASU 2014-09 wiped out the whole subtopic — it superseded the revenue-related measurement paragraphs, but the cancellation allowance, charge-off, and disclosure requirements remain.
Machine-generated study aid for ASC 310-976. Check the source paragraphs below.
310-976-00Status
Source downloaded: .Record version 60866be4a413. Effective date must be checked in the source.
| Paragraph | Action | Accounting Standards Update | Date |
| Full Accrual Method | Superseded | Accounting Standards Update No. 2014-09 | 05/28/2014 |
| 976-310-30-1 | Superseded | Accounting Standards Update No. 2014-09 | 05/28/2014 |
| 976-310-35-3 | Superseded | Accounting Standards Update No. 2014-09 | 05/28/2014 |
310-976-05Overview and Background
Source downloaded: .Record version 15f8d94d1ab3. Effective date must be checked in the source.
310-976-15Scope and Scope Exceptions
Source downloaded: .Record version f06aba9e4999. Effective date must be checked in the source.
Overall Guidance
310-976-20Glossary
Source downloaded: .Record version bf80daccfc71. Effective date must be checked in the source.
310-976-30Initial Measurement
Source downloaded: .Record version f64455299fa2. Effective date must be checked in the source.
310-976-35Subsequent Measurement
Source downloaded: .Record version 9374ee7f9ae4. Effective date must be checked in the source.
-
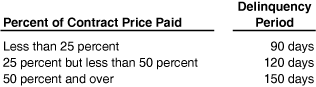 Percent of Contract Price Paid Delinquency Period Less than 25 percent 90 days 25 percent but less than 50 percent 120 days 50 percent and over 150 days
310-976-40Derecognition
Source downloaded: .Record version 61ecd7e92feb. Effective date must be checked in the source.
310-976-50Disclosure
Source downloaded: .Record version 864f10712175. Effective date must be checked in the source.
- aMaturities of accounts receivable for each of the five years following the date of the financial statements
- bDelinquent accounts receivable and the method(s) for determining delinquency
- cThe weighted average and range of stated interest rates of receivables.