ASC 310-946
Financial Services—Investment Companies
310 Receivables
Source downloaded: .Record version e6d05f03e652. Effective date must be checked in the source.
This Subtopic governs how an investment company presents receivables in its statement of assets and liabilities. Receivables must be listed separately at net realizable value by category — dividends and interest, investment securities sold, capital stock sold, and other accounts receivable (including related-party and affiliate expense-reimbursement receivables and variation margin on open futures contracts). Foreign-currency-denominated receivables are translated into the functional currency at current exchange rates and may be grouped with the corresponding functional currency receivables.
Key points (5)
- This Subtopic addresses an investment company's accounting for receivables (310-946-05-1) and follows the scope of Section 946-10-15 (310-946-15-1).
- Receivables shall be listed separately at net realizable value for categories including dividends and interest, investment securities sold, and capital stock sold (310-946-45-1(a)-(c)).
- Other accounts receivable — such as receivables from related parties, expense reimbursement receivables from affiliates, and variation margin on open futures contracts — must also be shown separately (310-946-45-1(d)).
- The listed categories are illustrative ('among others'), so other material receivable types warrant separate presentation as well (310-946-45-1).
- Receivables denominated in foreign currencies shall be converted into the functional currency at current exchange rates and may be categorized with the corresponding functional currency receivables (310-946-45-2).
For students. This is a short, presentation-focused subtopic: the exam point is the required disaggregation of investment company receivables at net realizable value, not a separate measurement or impairment model. A common misunderstanding is thinking the four listed categories are exhaustive — the text says "among others," so other significant receivables (e.g., affiliate reimbursements) also get their own line.
Machine-generated study aid for ASC 310-946. Check the source paragraphs below.
310-946-05Overview and Background
Source downloaded: .Record version f66ceeb9e64d. Effective date must be checked in the source.
310-946-15Scope and Scope Exceptions
Source downloaded: .Record version 7df5f58e3627. Effective date must be checked in the source.
Overall Guidance
310-946-45Other Presentation Matters
Source downloaded: .Record version fefb5626ab81. Effective date must be checked in the source.
Statement of Assets and Liabilities or Statement of Net Assets
- aDividends and interest
- bInvestment securities sold
- cCapital stock sold
- dOther accounts receivable, such as receivables from related parties, including expense reimbursement receivables from affiliates, and variation margin on open futures contracts.
310-946-S00StatusSEC
Source downloaded: .Record version 39219de6c78f. Effective date must be checked in the source.
| Paragraph | Action | Accounting Standards Update | Date |
| 946-310-S99-1 | Amended | Accounting Standards Update No. 2019-07 | 07/26/2019 |
310-946-S50DisclosureSEC
Source downloaded: .Record version 5663207c6e78. Effective date must be checked in the source.
Mortgage Loans on Real Estate and Interest Earned on Mortgages
310-946-S99SEC MaterialsSEC
Source downloaded: .Record version 3d76d3309cb6. Effective date must be checked in the source.
SEC Rules, Regulations, and Interpretations
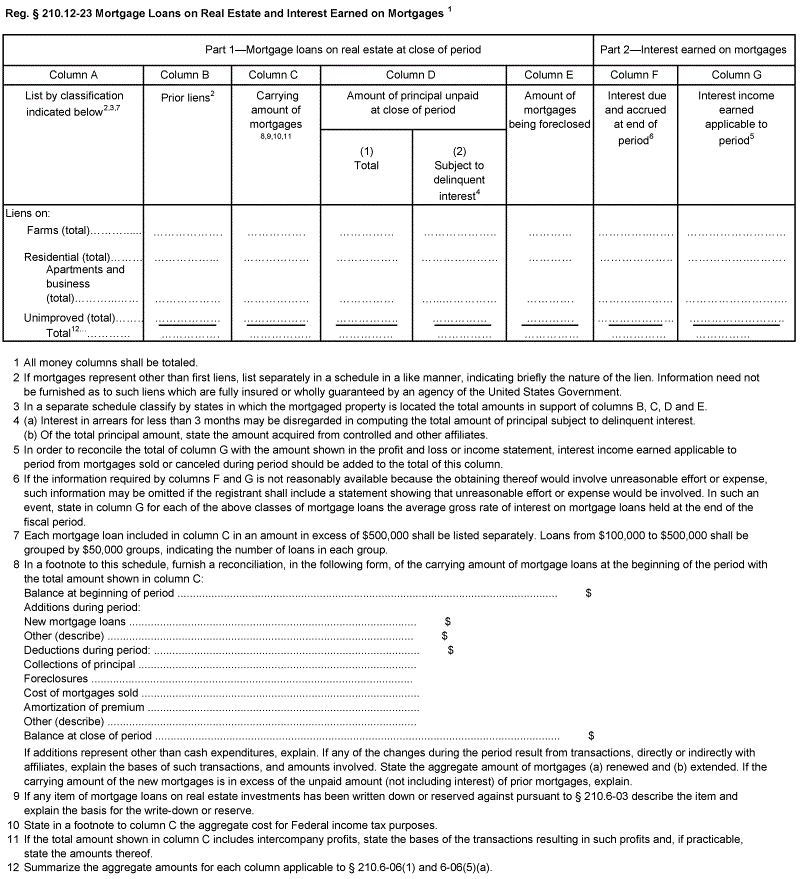 Reg. § 210.12-23 Mortgage Loans on Real Estate and Interest Earned on Mortgages 1 Part 1—Mortgage loans on real estate at close of period Part 2—Interest earned on mortgages Column A Column B Column C Column D Column E Column F Column G " List by classification indicated below2,3,7" Prior liens2 " Carrying amount of mortgages 8,9,10,11" "Amount of principal unpaid at close of period" Amount of mortgages being foreclosed " Interest due and accrued at end of period6 " "Interest income earned applicable to period5" " (1) Total " " (2) Subject to delinquent interest4" Liens on: ………………. ……………. …………… ……………….. ………… …………..……. ……………………… Farms (total)………....... Residential (total)…………… ……………... ……………… …………….. ………………… ………… ……………….. ……………..………. Apartments and business (total)………...……… ……………… ……………… …………… …...…………… …………. ………...……… …………………….… Unimproved (total)…….... ……………… ……………… …………….. …………… …………. ………………… …………………….. Total12…………… ……………. …………….. …………… …………… …………… …………… …………… 1 All money columns shall be totaled. 2 "If mortgages represent other than first liens, list separately in a schedule in a like manner, indicating briefly the nature of the lien. Information need not be furnished as to such liens which are fully insured or wholly guaranteed by an agency of the United States Government." 3 "In a separate schedule classify by states in which the mortgaged property is located the total amounts in support of columns B, C, D and E." 4 "(a) Interest in arrears for less than 3 months may be disregarded in computing the total amount of principal subject to delinquent interest. (b) Of the total principal amount, state the amount acquired from controlled and other affiliates." 5 "In order to reconcile the total of column G with the amount shown in the profit and loss or income statement, interest income earned applicable to period from mortgages sold or canceled during period should be added to the total of this column." 6 "If the information required by columns F and G is not reasonably available because the obtaining thereof would involve unreasonable effort or expense, such information may be omitted if the registrant shall include a statement showing that unreasonable effort or expense would be involved. In such an event, state in column G for each of the above classes of mortgage loans the average gross rate of interest on mortgage loans held at the end of the fiscal period." 7 "Each mortgage loan included in column C in an amount in excess of $500,000 shall be listed separately. Loans from $100,000 to $500,000 shall be grouped by $50,000 groups, indicating the number of loans in each group." 8 "In a footnote to this schedule, furnish a reconciliation, in the following form, of the carrying amount of mortgage loans at the beginning of the period with the total amount shown in column C: Balance at beginning of period ........................................................................................................................... $ Additions during period: New mortgage loans ............................................................................................. $ Other (describe) ................................................................................................... $ Deductions during period: ...................................................................................... $ Collections of principal .......................................................................................... Foreclosures ........................................................................................................ Cost of mortgages sold .......................................................................................... Amortization of premium ........................................................................................ Other (describe) .................................................................................................... Balance at close of period ................................................................................................................................... $ " "If additions represent other than cash expenditures, explain. If any of the changes during the period result from transactions, directly or indirectly with affiliates, explain the bases of such transactions, and amounts involved. State the aggregate amount of mortgages (a) renewed and (b) extended. If the carrying amount of the new mortgages is in excess of the unpaid amount (not including interest) of prior mortgages, explain." 9 If any item of mortgage loans on real estate investments has been written down or reserved against pursuant to § 210.6-03 describe the item and explain the basis for the write-down or reserve. 10 State in a footnote to column C the aggregate cost for Federal income tax purposes. 11 "If the total amount shown in column C includes intercompany profits, state the bases of the transactions resulting in such profits and, if practicable, state the amounts thereof." 12 Summarize the aggregate amounts for each column applicable to § 210.6-06(1) and 6-06(5)(a).