ASC 310-944
Financial Services—Insurance
310 Receivables
Source downloaded: .Record version a1762b7727eb. Effective date must be checked in the source.
ASC 310-944 tells insurance entities how to account for receivables: mortgage loans held as investments, reinsurance recoverables, and premium receivables on financial guarantee insurance contracts. Mortgage loans are recognized as assets at principal (or cost if bought at a discount/premium) and carried at amortized cost with an allowance for expected credit losses under Topic 326-20; reinsurance recoverables must be reported gross as assets (no netting against related liabilities absent a legal right of setoff). For financial guarantee contracts with installment premiums, the premium receivable is measured at the present value of premiums expected to be collected using a risk-free rate at inception, with the discount accreted to earnings.
Key points (7)
- Mortgage loans shall be recognized as assets (944-310-25-1), measured initially at outstanding principal if acquired at par or at cost if purchased at a discount or premium (944-310-30-1), and subsequently at outstanding principal or amortized cost with an allowance for estimated uncollectible amounts (944-310-35-1).
- Realized gains and losses on mortgage loan investments are reported pretax in other income in the statement of earnings (or disclosed in the notes), amortization goes to investment income, and changes in the allowance for credit losses follow Subtopic 326-20 (944-310-45-1 through 45-4; 944-310-50-1).
- Ceding entities must report estimated reinsurance recoverables separately as assets for both assumption-and-novation contracts and contracts where the ceding entity is not relieved of legal liability to the policyholder (944-310-25-2; 944-310-45-5).
- No single valuation method is prescribed for reinsurance recoverables; disputed amounts are contingent losses under Subtopic 450-20, while expected credit losses on recoverables follow Subtopic 326-20 (944-310-35-4).
- Receivables and payables between a ceding entity and an individual reinsurer may be offset only if a legal right of setoff exists under Subtopic 210-20, even for affiliates (though affiliate amounts are eliminated in consolidation) (944-310-45-7).
- For installment-premium financial guarantee insurance contracts, the premium receivable equals the present value of premiums due or expected to be collected discounted at the risk-free rate at inception over the contract period, with the discount accreted through earnings (944-310-25-3; 944-310-30-2).
- An expected (shorter) period may be used only if a homogenous pool of contractually prepayable assets underlies the insured obligation and prepayments are probable and reasonably estimable; this is an entity-wide accounting policy election, and changes in prepayment assumptions adjust premium receivable and unearned premium revenue by equal amounts with no earnings effect, updating the discount rate to a current risk-free rate (944-310-30-3; 944-310-35-5).
For students. Exam traps here are the gross-reporting rule for reinsurance recoverables (you cannot net them against reserves unless a legal right of setoff exists) and the fact that a change in prepayment assumptions on a financial guarantee premium receivable is a balance-sheet-only adjustment—the offsetting change to unearned premium revenue means no gain or loss at the date of change, only a revised revenue pattern going forward.
Machine-generated study aid for ASC 310-944. Check the source paragraphs below.
310-944-00Status
Source downloaded: .Record version 3e817be3a653. Effective date must be checked in the source.
310-944-05Overview and Background
Source downloaded: .Record version 03b71054738e. Effective date must be checked in the source.
- aGeneral
- bReinsurance Contracts
- cFinancial Guarantee Insurance Contracts.
Reinsurance Contracts
Financial Guarantee Insurance Contracts
310-944-15Scope and Scope Exceptions
Source downloaded: .Record version 8174d3d8890b. Effective date must be checked in the source.
Overall Guidance
Reinsurance Contracts
Instruments
Financial Guarantee Insurance Contracts
310-944-25Recognition
Source downloaded: .Record version de99a205770c. Effective date must be checked in the source.
Mortgage Loans
Reinsurance Contracts
Reinsurance Recoverables
- aReinsurance contracts that are legal replacements of one insurer by another (often referred to as assumption and novation)
- bReinsurance contracts in which a ceding entity is not relieved of the legal liability to its policyholder.
Financial Guarantee Insurance Contracts
310-944-30Initial Measurement
Source downloaded: .Record version ad32f9946464. Effective date must be checked in the source.
Mortgage Loans
Financial Guarantee Insurance Contracts
Receivable for Future Premiums
310-944-35Subsequent Measurement
Source downloaded: .Record version a2d68f3c454f. Effective date must be checked in the source.
Mortgage Loans
Reinsurance Contracts
Reinsurance Recoverables
Financial Guarantee Insurance Contracts
Unearned Premium Revenue
310-944-40Derecognition
Source downloaded: .Record version 48d6acf5e38f. Effective date must be checked in the source.
Mortgage Loans
310-944-45Other Presentation Matters
Source downloaded: .Record version 514251fa0360. Effective date must be checked in the source.
Mortgage Loans
Reinsurance Contracts
Reinsurance Recoverables
310-944-50Disclosure
Source downloaded: .Record version bfd7e3c584c5. Effective date must be checked in the source.
Mortgage Loans
Reinsurance Contracts
Reinsurance Recoverables
Financial Guarantee Insurance Contracts
- aFor financial guarantee insurance contracts where premiums are received as payments over the period of the contract, rather than at inception, all of the following:
- 1The premium receivable as of the date(s) of the statement of financial position and the line item in the statement of financial position where the amount is reported (if not presented separately)
- 2The unearned premium revenue as of the date(s) of the statement of financial position and the line item in the statement of financial position where the amount is reported (if not presented separately)
- 3The amount of accretion on the premium receivable and the line item in the statement of income where that amount is reported (if not presented separately)
- 4The weighted-average risk-free rate used to discount the premiums expected to be collected
- 5The weighted-average period of the premium receivable.
- 1
- bA schedule of premiums expected to be collected related to the premium receivable detailing both of the following:
- 1The four quarters of the subsequent annual period and each of the next four annual periods
- 2The remaining periods aggregated in five-year increments.
- 1
- cA rollforward of the premium receivable for the period, including all of the following:
- 1The beginning premium receivable
- 2Premium payments received
- 3New business written
- 4Adjustments to the premium receivable, including all of the following:
- iAdjustments for changes in the period of a financial guarantee insurance contract
- iiAn explanation of why the adjustments in item (c)(4)(i) occurred
- iiiAccretion of the premium receivable discount
- ivOther adjustments with explanations provided.
- i
- 5The ending premium receivable.
- 1
310-944-55Implementation Guidance and Illustrations
Source downloaded: .Record version 847f0d0589f4. Effective date must be checked in the source.
Financial Guarantee Insurance Contracts
Illustrations
-
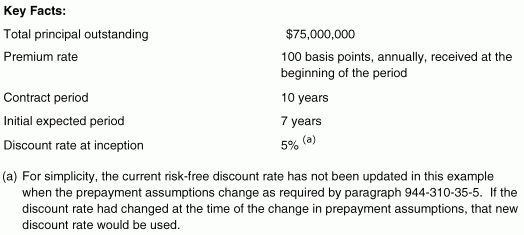 Key Facts: Total principal outstanding "$75,000,000" Premium rate "100 basis points, annually, received at the beginning of the period" Contract period 10 years Initial expected period 7 years Discount rate at inception 5% (a) (a) "For simplicity, the current risk-free discount rate has not been updated in this example when the prepayment assumptions change as required by paragraph 944-310-35-5. If the discount rate had changed at the time of the change in prepayment assumptions, that new discount rate would be used."
- a The expected insured principal amounts outstanding during each period
- b The expected insured principal payments
- c The expected premium payments
- d The present value of premiums expected.
-
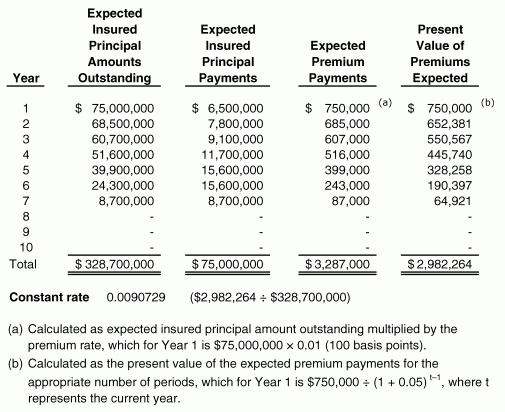 Table 1 Year "Expected Insured Principal Amounts Outstanding" "Expected Insured Principal Payments" "Expected Premium Payments" "Present Value of Premiums Expected" 1 " $75,000,000 " " $6,500,000 " " $750,000 " (a) " $750,000 " (b) 2 " 68,500,000 " " 7,800,000 " " 685,000 " " 652,381 " 3 " 60,700,000 " " 9,100,000 " " 607,000 " " 550,567 " 4 " 51,600,000 " " 11,700,000 " " 516,000 " " 445,740 " 5 " 39,900,000 " " 15,600,000 " " 399,000 " " 328,258 " 6 " 24,300,000 " " 15,600,000 " " 243,000 " " 190,397 " 7 " 8,700,000 " " 8,700,000 " " 87,000 " " 64,921 " 8 - - - - 9 - - - - 10 - - - - Total " $328,700,000 " " $75,000,000 " " $3,287,000 " " $2,982,264 " "Constant rate 0.0090729 ($2,982,264 ÷ $328,700,000)" (a) "Calculated as expected insured principal amount outstanding multiplied by the premium rate, which for Year 1 is $75,000,000 × 0.01 (100 basis points)." (b) "Calculated as the present value of the expected premium payments for the appropriate number of periods, which for Year 1 is $750,000 ÷ (1 + 0.05) t-1, where t represents the current year."
-
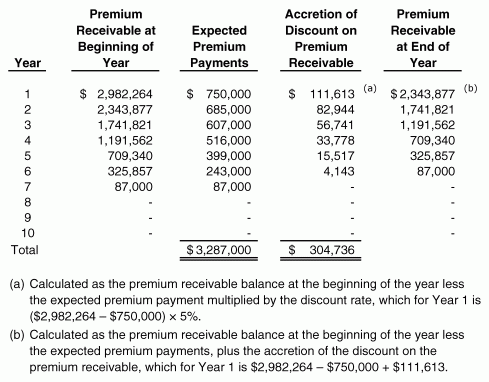 Year "Premium Receivable at Beginning of Year" "Expected Premium Payments" "Accretion of Discount on Premium Receivable" "Premium Receivable at End of Year" 1 " $2,982,264 " " $750,000 " " $111,613 " (a) " $2,343,877 " (b) 2 " 2,343,877 " " 685,000 " " 82,944 " " 1,741,821 " 3 " 1,741,821 " " 607,000 " " 56,741 " " 1,191,562 " 4 " 1,191,562 " " 516,000 " " 33,778 " " 709,340 " 5 " 709,340 " " 399,000 " " 15,517 " " 325,857 " 6 " 325,857 " " 243,000 " " 4,143 " " 87,000 " 7 " 87,000 " " 87,000 " - - 8 - - - - 9 - - - - 10 - - - - Total " $3,287,000 " " $304,736 " (a) "Calculated as the premium receivable balance at the beginning of the year less the expected premium payment multiplied by the discount rate, which for Year 1 is ($2,982,264 - $750,000) × 5%." (b) "Calculated as the premium receivable balance at the beginning of the year less the expected premium payments, plus the accretion of the discount on the premium receivable, which for Year 1 is $2,982,264 - $750,000 + $111,613."
-
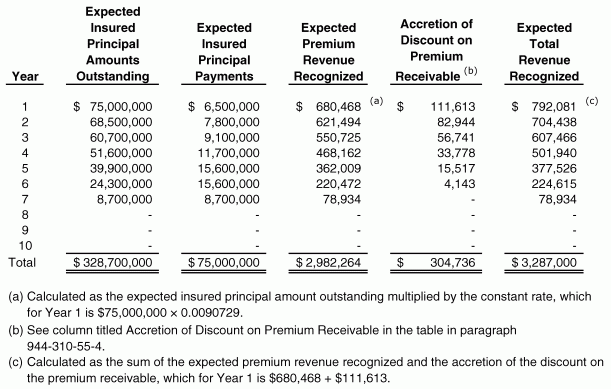 Year "Expected Insured Principal Amounts Outstanding" "Expected Insured Principal Payments" "Expected Premium Revenue Recognized" "Accretion of Discount on Premium Receivable (b)" "Expected Total Revenue Recognized" 1 " $75,000,000 " " $6,500,000 " " $680,468 " (a) " $111,613 " " $792,081 " (c) 2 " 68,500,000 " " 7,800,000 " " 621,494 " " 82,944 " " 704,438 " 3 " 60,700,000 " " 9,100,000 " " 550,725 " " 56,741 " " 607,466 " 4 " 51,600,000 " " 11,700,000 " " 468,162 " " 33,778 " " 501,940 " 5 " 39,900,000 " " 15,600,000 " " 362,009 " " 15,517 " " 377,526 " 6 " 24,300,000 " " 15,600,000 " " 220,472 " " 4,143 " " 224,615 " 7 " 8,700,000 " " 8,700,000 " " 78,934 " - " 78,934 " 8 - - - - - 9 - - - - - 10 - - - - - Total " $328,700,000 " " $75,000,000 " " $2,982,264 " " $304,736 " " $3,287,000 " (a) "Calculated as the expected insured principal amount outstanding multiplied by the constant rate, which for Year 1 is $75,000,000 × 0.0090729." (b) See column titled Accretion of Discount on Premium Receivable in the table in paragraph 944-310-55-4. (c) "Calculated as the sum of the expected premium revenue recognized and the accretion of the discount on the premium receivable, which for Year 1 is $680,468 + $111,613."
-
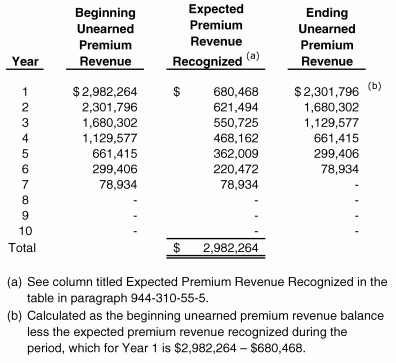 Year "Beginning Unearned Premium Revenue" "Expected Premium Revenue Recognized (a)" "Ending Unearned Premium Revenue" 1 " $2,982,264 " " $680,468 " " $2,301,796 " (b) 2 " 2,301,796 " " 621,494 " " 1,680,302 " 3 " 1,680,302 " " 550,725 " " 1,129,577 " 4 " 1,129,577 " " 468,162 " " 661,415 " 5 " 661,415 " " 362,009 " " 299,406 " 6 " 299,406 " " 220,472 " " 78,934 " 7 " 78,934 " " 78,934 " - 8 - - - 9 - - - 10 - - - Total " $2,982,264 " (a) See column titled Expected Premium Revenue Recognized in the table in paragraph 944-310-55-5. (b) "Calculated as the beginning unearned premium revenue balance less the expected premium revenue recognized during the period, which for Year 1 is $2,982,264 - $680,468."
-
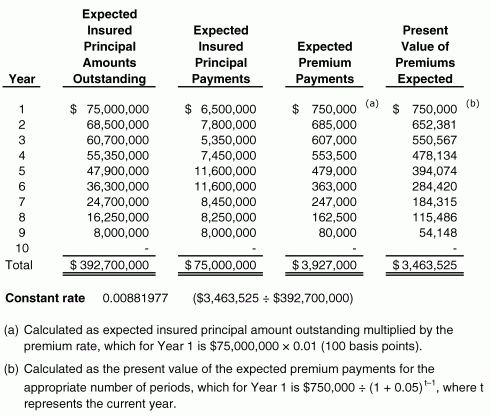 Year "Expected Insured Principal Amounts Outstanding" "Expected Insured Principal Payments" "Expected Premium Payments" "Present Value of Premiums Expected" 1 " $75,000,000 " " $6,500,000 " " $750,000 " (a) " $750,000 " (b) 2 " 68,500,000 " " 7,800,000 " " 685,000 " " 652,381 " 3 " 60,700,000 " " 5,350,000 " " 607,000 " " 550,567 " 4 " 55,350,000 " " 7,450,000 " " 553,500 " " 478,134 " 5 " 47,900,000 " " 11,600,000 " " 479,000 " " 394,074 " 6 " 36,300,000 " " 11,600,000 " " 363,000 " " 284,420 " 7 " 24,700,000 " " 8,450,000 " " 247,000 " " 184,315 " 8 " 16,250,000 " " 8,250,000 " " 162,500 " " 115,486 " 9 " 8,000,000 " " 8,000,000 " " 80,000 " " 54,148 " 10 - - - - Total " $392,700,000 " " $75,000,000 " " $3,927,000 " " $3,463,525 " "Constant rate 0.00881977 ($3,463,525 ÷ $392,700,000)" (a) "Calculated as expected insured principal amount outstanding multiplied by the premium rate, which for Year 1 is $75,000,000 × 0.01 (100 basis points)." (b) "Calculated as the present value of the expected premium payments for the appropriate number of periods, which for Year 1 is $750,000 ÷ (1 + 0.05) t-1, where t represents the current year."
-
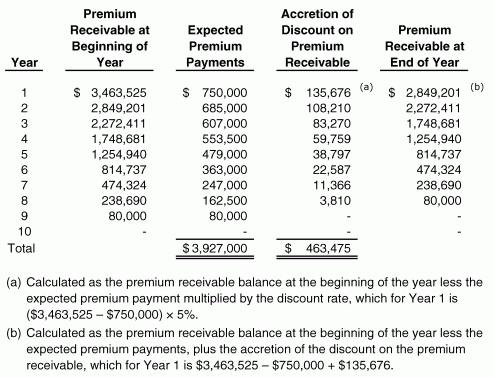 Year "Premium Receivable at Beginning of Year" "Expected Premium Payments" "Accretion of Discount on Premium Receivable" "Premium Receivable at End of Year" 1 " $3,463,525 " " $750,000 " " $135,676 " (a) " $2,849,201 " (b) 2 " 2,849,201 " " 685,000 " " 108,210 " " 2,272,411 " 3 " 2,272,411 " " 607,000 " " 83,270 " " 1,748,681 " 4 " 1,748,681 " " 553,500 " " 59,759 " " 1,254,940 " 5 " 1,254,940 " " 479,000 " " 38,797 " " 814,737 " 6 " 814,737 " " 363,000 " " 22,587 " " 474,324 " 7 " 474,324 " " 247,000 " " 11,366 " " 238,690 " 8 " 238,690 " " 162,500 " " 3,810 " " 80,000 " 9 " 80,000 " " 80,000 " - - 10 - - - - Total " $3,927,000 " " $463,475 " (a) "Calculated as the premium receivable balance at the beginning of the year less the expected premium payment multiplied by the discount rate, which for Year 1 is ($3,463,525 - $750,000) × 5%." (b) "Calculated as the premium receivable balance at the beginning of the year less the expected premium payments, plus the accretion of the discount on the premium receivable, which for Year 1 is $3,463,525 - $750,000 + $135,676."
-
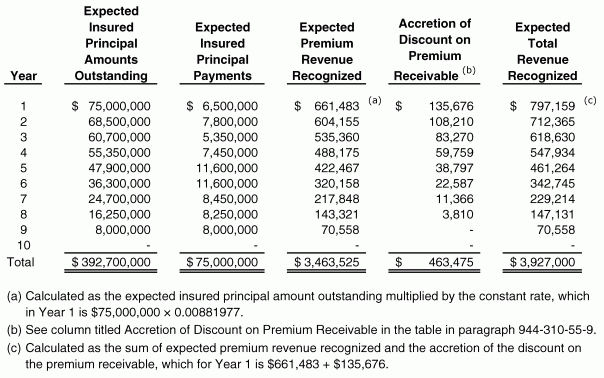 Year "Expected Insured Principal Amounts Outstanding" "Expected Insured Principal Payments" "Expected Premium Revenue Recognized" "Accretion of Discount on Premium Receivable (b)" "Expected Total Revenue Recognized" 1 " $75,000,000 " " $6,500,000 " " $661,483 " (a) " $135,676 " " $797,159 " (c) 2 " 68,500,000 " " 7,800,000 " " 604,155 " " 108,210 " " 712,365 " 3 " 60,700,000 " " 5,350,000 " " 535,360 " " 83,270 " " 618,630 " 4 " 55,350,000 " " 7,450,000 " " 488,175 " " 59,759 " " 547,934 " 5 " 47,900,000 " " 11,600,000 " " 422,467 " " 38,797 " " 461,264 " 6 " 36,300,000 " " 11,600,000 " " 320,158 " " 22,587 " " 342,745 " 7 " 24,700,000 " " 8,450,000 " " 217,848 " " 11,366 " " 229,214 " 8 " 16,250,000 " " 8,250,000 " " 143,321 " " 3,810 " " 147,131 " 9 " 8,000,000 " " 8,000,000 " " 70,558 " - " 70,558 " 10 - - - - - Total " $392,700,000 " " $75,000,000 " " $3,463,525 " " $463,475 " " $3,927,000 " (a) "Calculated as the expected insured principal amount outstanding multiplied by the constant rate, which in Year 1 is $75,000,000 × 0.00881977." (b) "See column titled Accretion of Discount on Premium Receivable in the table in paragraph 944-310-55-9." (c) "Calculated as the sum of expected premium revenue recognized and the accretion of the discount on the premium receivable, which for Year 1 is $661,483 + $135,676."
-
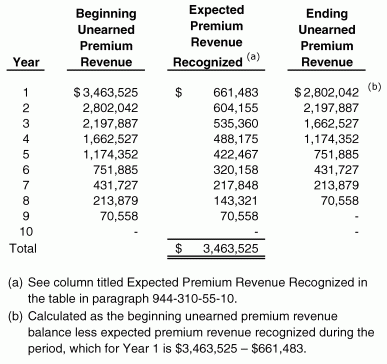 Year "Beginning Unearned Premium Revenue" "Expected Premium Revenue Recognized (a)" "Ending Unearned Premium Revenue" 1 " $3,463,525 " " $661,483 " " $2,802,042 " (b) 2 " 2,802,042 " " 604,155 " " 2,197,887 " 3 " 2,197,887 " " 535,360 " " 1,662,527 " 4 " 1,662,527 " " 488,175 " " 1,174,352 " 5 " 1,174,352 " " 422,467 " " 751,885 " 6 " 751,885 " " 320,158 " " 431,727 " 7 " 431,727 " " 217,848 " " 213,879 " 8 " 213,879 " " 143,321 " " 70,558 " 9 " 70,558 " " 70,558 " - 10 - - - Total " $3,463,525 " (a) See column titled Expected Premium Revenue Recognized in the table in paragraph 944-310-55-10. (b) "Calculated as the beginning unearned premium revenue balance less expected premium revenue recognized during the period, which for Year 1 is $3,463,525 - $661,483."
-
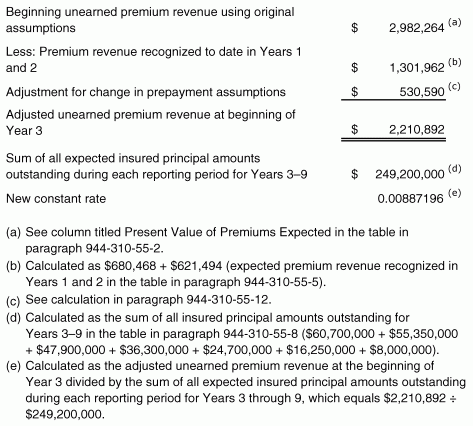 Beginning unearned premium revenue using original assumptions " $2,982,264 " (a) "Less: Premium revenue recognized to date in Years 1 and 2" " $1,301,962 " (b) Adjustment for change in prepayment assumptions " $530,590 " (c) "Adjusted unearned premium revenue at beginning of Year 3" " $2,210,892 " Sum of all expected insured principal amounts outstanding during each reporting period for Years 3-9 " $249,200,000 " (d) New constant rate 0.00887196 (e) (a) See column titled Present Value of Premiums Expected in the table in paragraph 944-330-55-2. (b) "Calculated as $680,468 + $621,494 (expected premium revenue recognized in Years 1 and 2 in the table in paragraph 944-310-55-5)." (c) See calculation in paragraph 944-310-55-12. (d) "Calculated as the sum of all insured principal amounts outstanding for Years 3-9 in the table in paragraph 944-310-55-8 ($60,700,000 + $55,350,000 + $47,900,000 + $36,300,000 + $24,700,000 + $16,250,000 + $8,000,000)." (e) "Calculated as the adjusted unearned premium revenue at the beginning of Year 3 divided by the sum of all expected insured principal amounts outstanding during each reporting period for Years 3 through 9, which equals $2,210,892 ÷ $249,200,000."
- a The actual premium revenue recognized and discount accreted on the premium receivable for Years 1 and 2
- b The revised expected premium revenue recognition and accretion on the premium receivable from Years 3-9 based on the new prepayment assumptions.
-
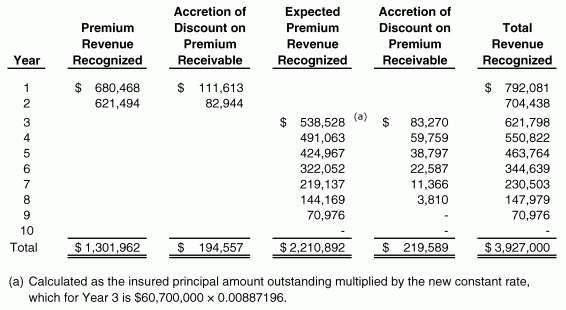 Year "Premium Revenue Recognized" "Accretion of Discount on Premium Receivable" "Expected Premium Revenue Recognized" "Accretion of Discount on Premium Receivable" "Total Revenue Recognized" 1 " $680,468 " " $111,613 " " $792,081 " 2 " 621,494 " " 82,944 " " 704,438 " 3 " $538,528 " (a) " $83,270 " " 621,798 " 4 " 491,063 " " 59,759 " " 550,822 " 5 " 424,967 " " 38,797 " " 463,764 " 6 " 322,052 " " 22,587 " " 344,639 " 7 " 219,137 " " 11,366 " " 230,503 " 8 " 144,169 " " 3,810 " " 147,979 " 9 " 70,976 " - " 70,976 " 10 - - - Total " $1,301,962 " " $194,557 " " $2,210,892 " " $219,589 " " $3,927,000 " (a) "Calculated as the insured principal amount outstanding multiplied by the new constant rate, which for Year 3 is $60,700,000 × 0.00887196."
Related subtopics
- 605-944 Financial Services—InsuranceRevenue Recognition
- 944-40 Claim Costs and Liabilities for Future Policy BenefitsFinancial Services—Insurance
- 340-30 Insurance Contracts That Do Not Transfer Insurance RiskOther Assets and Deferred Costs
- 944-60 Premium Deficiency and Loss RecognitionFinancial Services—Insurance
- 944-30 Acquisition CostsFinancial Services—Insurance
- 944-20 Insurance ActivitiesFinancial Services—Insurance