ASC 405-50
Liabilities—Supplier Finance Programs
405 Liabilities
Source downloaded: .Record version 84bf3acfed55. Effective date must be checked in the source.
ASC 405-50 is a disclosure-only subtopic requiring the buyer in a supplier finance program (also called reverse factoring, payables finance, or structured payables) to disclose qualitative and quantitative information about the program. A supplier finance program exists when the buyer agrees with a finance provider or intermediary, confirms supplier invoices as valid to that party, and the supplier can request early payment from a party other than the buyer (405-50-15-2). The subtopic does not address recognition, measurement, or balance sheet presentation of the obligation, or the accounting by other parties (405-50-10-2).
Key points (7)
- Scope: applies to all buyers using arrangements with the three characteristics in 405-50-15-2 — an agreement with a finance provider/intermediary, buyer confirmation of supplier invoices as valid, and the supplier's option to request early payment from a party other than the buyer.
- An indicator (not determinative) of a supplier finance program is a commitment to pay a party other than the supplier for a confirmed invoice without offset, deduction, or other defenses to payment (405-50-15-3); all available evidence, including buyer-supplier arrangements, must be considered (405-50-15-4).
- The subtopic is disclosure-only: it does not address the buyer's recognition, measurement, or financial statement presentation of the obligation, nor accounting by other parties to the program (405-50-10-2).
- Disclosure objective is to let users understand the nature, activity during the period, changes from period to period, and potential magnitude of the programs (405-50-50-1); multiple programs may be aggregated unless aggregation obscures useful information about programs with substantially different characteristics (405-50-50-2).
- Annually, disclose key terms — payment terms including payment timing and the basis for its determination, and assets pledged as security or other forms of guarantees for the committed payment (405-50-50-3(a)).
- Annually, disclose the amount of obligations confirmed as valid and unpaid at period-end, where they are presented in the balance sheet (by line item if more than one), and a rollforward showing beginning balance, additions, settlements, and ending balance (405-50-50-3(b)).
- In each interim reporting period, disclose the amount of confirmed obligations outstanding at the end of the period (405-50-50-4).
For students. This is a transparency rule born of concerns that reverse factoring lets companies stretch payment terms while still classifying the obligation as a trade payable rather than debt; the common misunderstanding is thinking ASC 405-50 dictates that classification — it does not, it only requires the buyer to disclose where the obligation is presented and how it moved during the period.
Machine-generated study aid for ASC 405-50. Check the source paragraphs below.
405-50-00Status
Source downloaded: .Record version cc05a60a85fb. Effective date must be checked in the source.
| Paragraph | Action | Accounting Standards Update | Date |
| 405-50-05-1 | Added | Accounting Standards Update No. 2022-04 | 09/29/2022 |
| 405-50-10-1 | Added | Accounting Standards Update No. 2022-04 | 09/29/2022 |
| 405-50-10-2 | Added | Accounting Standards Update No. 2022-04 | 09/29/2022 |
| Added | Accounting Standards Update No. 2022-04 | 09/29/2022 | |
| Added | Accounting Standards Update No. 2022-04 | 09/29/2022 | |
| Added | Accounting Standards Update No. 2022-04 | 09/29/2022 | |
| 405-50-65-1 | Added | Accounting Standards Update No. 2022-04 | 09/29/2022 |
405-50-05Overview and Background
Source downloaded: .Record version 6f0ecafb167b. Effective date must be checked in the source.
405-50-10Objectives
Source downloaded: .Record version e1fb71b49b81. Effective date must be checked in the source.
- aA buyer’s recognition, measurement, or financial statement presentation of an obligation in connection with a supplier finance program
- bThe accounting and disclosure for other parties involved in a supplier finance program.
405-50-15Scope and Scope Exceptions
Source downloaded: .Record version 6ce4b7a63776. Effective date must be checked in the source.
Entities
Transactions
- aAn entity enters into an agreement with a finance provider or an intermediary.
- bThe entity confirms supplier invoices as valid to the finance provider or intermediary under the agreement described in (a).
- cThe entity’s supplier has the option to request early payment from a party other than the entity for invoices that the entity has confirmed as valid.
405-50-50Disclosure
Source downloaded: .Record version 5cd487b2ec05. Effective date must be checked in the source.
- aThe key terms of the program, including, but not limited to:
- 1A description of the payment terms, including payment timing and the basis for its determination
- 2Assets pledged as security or other forms of guarantees provided for the committed payment to the finance provider or intermediary.
See paragraphs for an illustrative example. - 1
- bThe amount of obligations outstanding at the end of the reporting period that the entity has confirmed as valid to the finance provider or intermediary under the program (that is, the amount of obligations confirmed under the program that remains unpaid by the entity) and the following information about those obligations:
- 1Where those obligations are presented in the balance sheet. If those obligations are presented in more than one balance sheet line item, then the entity shall disclose the amount outstanding at the end of the reporting period in each line item.
- 2A rollforward of those obligations showing, at a minimum, all the following:
- iThe amount of those obligations outstanding at the beginning of the reporting period
- iiThe amount of those obligations added to the program during the reporting period
- iiiThe amount of those obligations settled during the reporting period
- ivThe amount of those obligations outstanding at the end of the reporting period.
- i
- 1
405-50-55Implementation Guidance and Illustrations
Source downloaded: .Record version 531807bbdccc. Effective date must be checked in the source.
Illustrations
- Under a supplier finance program, Entity A agrees to pay a bank the stated amount of confirmed invoices from its designated suppliers on the original maturity dates of the invoices, an annual subscription fee for the supplier finance platform, and service fees for related support. Entity A or the bank may terminate the agreement upon at least 90 days’ notice. The supplier invoices that have been confirmed as valid under the program require payment in full within 90 days of the invoice date.
- The rollforwards of Entity A’s outstanding obligations confirmed as valid under its supplier finance program for years ended December 31, 20X2, and 20X1, are as follows (in thousands):
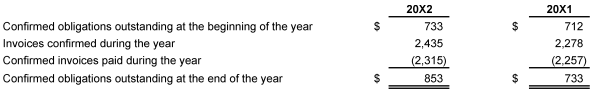 20X2 20X1 Confirmed obligations outstanding at the beginning of the year $ 733 $ 712 Invoices confirmed during the year "2,435 " "2,278 " Confirmed invoices paid during the year "(2,315)" "(2,257)" Confirmed obligations outstanding at the end of the year $ 853
405-50-65Transition and Open Effective Date Information
Source downloaded: .Record version b90753a0cb58. Effective date must be checked in the source.