ASC 440-10
Overall
440 Commitments
Source downloaded: .Record version d34fdf666a20. Effective date must be checked in the source.
ASC 440-10 is the general "Commitments" subtopic: it requires disclosure of certain contractual commitments (unused letters of credit, pledged assets, cumulative preferred dividends in arrears, plant acquisition commitments, obligations to reduce debt, maintain working capital, or restrict dividends) that are not otherwise more explicitly addressed elsewhere in the Codification. Its Unconditional Purchase Obligations Subsections require disclosure of off-balance-sheet take-or-pay and throughput contracts that are noncancelable, were negotiated as part of arranging financing for the supplier's facility, and have a remaining term over one year. The Topic is largely a disclosure standard—recognition of such obligations is governed by other Topics (842, 815, 330).
Key points (7)
- The Topic applies to all entities and provides general commitments guidance, while commitment guidance specific to a Topic or industry resides in that Topic (440-10-05-3, 440-10-15-2).
- Unconditional purchase obligations guidance excludes product financing arrangements within Section 470-40-15 and repurchase agreements within Topic 606 paragraphs 606-10-55-66 through 55-78 (440-10-15-4).
- Sequence of analysis: apply Section 842-10-15 first to see if the obligation is a lease, then apply Sections 815-10-15 and 815-15-15 (and paragraph 815-10-55-60) to any non-lease or embedded-derivative portion (440-10-25-2 through 25-3); accrued net losses on firm inventory purchase commitments are recognized under 330-10-35-17 through 35-18 (440-10-25-4).
- Regardless of more explicit disclosures elsewhere, entities must disclose unused letters of credit, leases, pledged/mortgaged assets, pension plans, cumulative preferred dividends in arrears, and commitments for plant acquisition, debt reduction, working capital maintenance, or dividend restrictions (440-10-50-1).
- An unconditional purchase obligation triggers disclosure only if it is (a) noncancelable (or cancelable only on a remote contingency, with the other party's permission, on signing a replacement agreement, or on a penalty making continuation reasonably assured), (b) negotiated as part of arranging financing for the facilities providing the goods or services, and (c) has a remaining term exceeding one year (440-10-50-2).
- For unrecognized obligations, disclose the nature and term, the fixed and determinable amount at the latest balance sheet date in aggregate and for each of the five succeeding fiscal years, the nature of variable components, and amounts purchased for each income statement period; omission is allowed only if the aggregate undisclosed commitment is immaterial (440-10-50-4).
- If the obligation is recognized on the balance sheet, disclose the aggregate payments for each of the five years following the latest balance sheet date (440-10-50-6); disclosing imputed interest to reduce the obligation to present value is encouraged but not required, using the effective initial rate of the facility financing or, if unknown, the purchaser's incremental borrowing rate (440-10-50-5).
For students. This is primarily a disclosure Topic, not a recognition Topic—the classic error is assuming an unconditional purchase obligation must be booked as a liability; instead you test it under Topic 842 first, then Topic 815, and if neither applies you only disclose. Memorize the three-part disclosure trigger in 440-10-50-2, especially the often-overlooked requirement that the obligation was negotiated as part of arranging financing for the supplier's facility.
Machine-generated study aid for ASC 440-10. Check the source paragraphs below.
440-10-00Status
Source downloaded: .Record version 033ced706556. Effective date must be checked in the source.
440-10-05Overview and Background
Source downloaded: .Record version 979accb3da10. Effective date must be checked in the source.
- aGeneral
- bUnconditional Purchase Obligations.
Unconditional Purchase Obligations
440-10-15Scope and Scope Exceptions
Source downloaded: .Record version 007f69d506b7. Effective date must be checked in the source.
Overall Guidance
Entities
Unconditional Purchase Obligations
Overall Guidance
Transactions
- aProduct financing arrangements, that are within the scope of Section 470-40-15. See paragraph 470-40-05-5 for a discussion of the distinction between a product financing arrangement and an unconditional purchase obligation.
- bRepurchase agreements that are within the scope of Topic 606, specifically in paragraphs .
440-10-25Recognition
Source downloaded: .Record version ae6d62483832. Effective date must be checked in the source.
Unconditional Purchase Obligations
440-10-50Disclosure
Source downloaded: .Record version 30280e349dba. Effective date must be checked in the source.
- a Unused letters of credit
- b Leases (see Section 842-20-50)
- c Assets pledged as security for loans
- d Pension plans (see Section 715-20-50)
- e The existence of cumulative preferred stock dividends in arrears
- f Commitments, including:
- 1 A commitment for plant acquisition
- 2 An obligation to reduce debts
- 3 An obligation to maintain working capital
- 4 An obligation to restrict dividends.
- 1
- a Unused letters of credit
- b Leases (see Section 842-20-50)
- c Assets mortgaged, pledged , or otherwise subject to lien; the approximate amounts of those assets; and the related obligations collateralized
- d Pension plans (see Section 715-20-50)
- e The existence of cumulative preferred stock dividends in arrears
- f Commitments, including:
- 1 A commitment for plant acquisition
- 2 An obligation to reduce debts
- 3 An obligation to maintain working capital
- 4 An obligation to restrict dividends.
- 1
Unconditional Purchase Obligations
- a It is noncancelable, or cancelable only in any of the following circumstances:
- 1 Upon the occurrence of some remote contingency
- 2 With the permission of the other party
- 3 If a replacement agreement is signed between the same parties
- 4 Upon payment of a penalty in an amount such that continuation of the agreement appears reasonably assured.
- 1
- b It was negotiated as part of arranging financing for the facilities that will provide the contracted goods or services or for costs related to those goods or services (for example, carrying costs for contracted goods). A purchaser is not required to investigate whether a supplier used an unconditional purchase obligation to help secure financing, if the purchaser would otherwise be unaware of that fact.
- c It has a remaining term in excess of one year
Unrecognized Commitments
- a The nature and term of the obligation(s)
- b The amount of the fixed and determinable portion of the obligation(s) as of the date of the latest balance sheet presented, in the aggregate and, if determinable, for each of the five succeeding fiscal years
- c The nature of any variable components of the obligation(s)
- d The amounts purchased under the obligation(s) (for example, the take-or-pay or throughput contract) for each period for which an income statement is presented.
Recognized Commitments
440-10-55Implementation Guidance and Illustrations
Source downloaded: .Record version aef58dbe7bae. Effective date must be checked in the source.
Unconditional Purchase Obligations
Illustrations
- To secure access to facilities to process chemical X, the entity has signed a processing agreement with a chemical supplier allowing the entity to submit 100,000 tons for processing annually for 20 years. Under the terms of the agreement, the entity may be required to advance funds against future processing charges if the chemical supplier is unable to meet its financial obligations. The aggregate amount of required payments at December 31, 19X1, is as follows (in thousands).
-
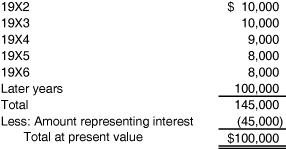 19X2 " $10,000 " 19X3 " 10,000 " 19X4 " 9,000 " 19X5 " 8,000 " 19X6 " 8,000 " Later years " 100,000 " Total " 145,000 " Less: Amount representing interest " (45,000)" Total at present value " $100,000 "
-
- In addition, the entity is required to pay a proportional share of the variable operating expenses of the plant. The entity's total processing charges under the agreement in each of the past 3 years have been $12 million.
440-10-60Relationships
Source downloaded: .Record version 4d0c8ff250d2. Effective date must be checked in the source.