ASC 440-954
Health Care Entities
440 Commitments
Source downloaded: .Record version 937150cd0ac9. Effective date must be checked in the source.
This subtopic governs the commitment of a continuing care retirement community (CCRC) to provide future services and the use of facilities to current residents under continuing-care contracts. The CCRC must recalculate that obligation annually and, if advance fees plus periodic fees are insufficient to cover the cost of future services and facilities, record a liability measured actuarially at the present value of future net cash flows, less deferred revenue (contract liability), plus depreciation of facilities to be charged to those contracts and any unamortized incremental costs of obtaining a contract. Extensive note disclosure about the contracts, liability, discount rate, escrow requirements, and refund policy is required.
Key points (7)
- A CCRC's obligation to provide future services and the use of facilities to current residents must be calculated/measured annually to determine whether a liability is reported (440-954-25-2; 440-954-35-1).
- A liability is recorded only when advance fees and periodic fees charged are insufficient to meet the costs of providing future services and facilities; it equals expected costs (resident-care, dietary, health care, facility, interest, depreciation, and amortization) over residents' remaining lives in excess of anticipated revenues, based on actuarial assumptions such as mortality and morbidity (440-954-35-2).
- Measurement formula: present value of future net cash flows, minus the balance of deferred revenue (contract liability) under Topic 606, plus depreciation of facilities to be charged to the contracts, plus any unamortized incremental costs of obtaining a contract under Subtopic 340-40 (440-954-35-3).
- The calculation is made by grouping contracts by type (for example, contracts with limits on annual fee increases versus contracts with unlimited fee increases) (440-954-35-3).
- Cash inflows include contractually committed revenue, monthly fees with contractual increases, third-party payments, committed investment income, donor pledges, and deferred nonrefundable advance fees; cash outflows are operating expenses including interest but excluding selling and general and administrative expenses; the expected inflation rate is considered in setting the discount rate, and life spans used must be the same as those used to recognize revenue (440-954-35-3).
- Contract types are all-inclusive, modified, and fee-for-service continuing-care contracts, with payment structured as advance fee only, advance fee with periodic fees, or periodic fees only (440-954-05-4; 440-954-05-6).
- Required disclosures for each year presented: description of the CCRC and nature of the continuing-care contracts, carrying amount of the present-value liability (if not shown separately on the balance sheet), the discount interest rate, statutory escrow or similar requirements, and the refund policy and general amount of refund obligation (440-954-50-1).
For students. This is the classic CCRC "future service obligation" test: it is a loss-recognition style calculation done annually, so no liability appears if fees are adequate. Students often forget that the deferred revenue balance and unamortized contract acquisition costs are backed out of (or added to) the present value computation, and that SG&A is excluded from the cash outflows.
Machine-generated study aid for ASC 440-954. Check the source paragraphs below.
440-954-00Status
Source downloaded: .Record version a1663cb0871a. Effective date must be checked in the source.
| Paragraph | Action | Accounting Standards Update | Date |
| Conditional Contribution | Added | Accounting Standards Update No. 2018-08 | 06/21/2018 |
| Contract Liability | Added | Accounting Standards Update No. 2014-09 | 05/28/2014 |
| Contribution | Amended | Accounting Standards Update No. 2018-08 | 06/21/2018 |
| Contribution | Amended | Accounting Standards Update No. 2010-07 | 01/28/2010 |
| Donor-Imposed Condition | Added | Accounting Standards Update No. 2018-08 | 06/21/2018 |
| Promise to Give | Added | Accounting Standards Update No. 2018-08 | 06/21/2018 |
| Added | Accounting Standards Update No. 2014-09 | 05/28/2014 | |
| 954-440-35-3 | Amended | Accounting Standards Update No. 2014-09 | 05/28/2014 |
| 954-440-55-1 | Amended | Accounting Standards Update No. 2014-09 | 05/28/2014 |
| 954-440-55-4 | Amended | Accounting Standards Update No. 2014-09 | 05/28/2014 |
440-954-05Overview and Background
Source downloaded: .Record version cfd927955f56. Effective date must be checked in the source.
Continuing Care Retirement Community
- aAn all-inclusive continuing-care contract includes residential facilities, meals, and other amenities. It also provides long-term nursing care for little or no increase in periodic fees, except to cover normal operating costs and inflation.
- bA modified continuing-care contract also includes residential facilities, meals, and other amenities. However, only a specified amount of long-term nursing care is provided for little or no increase in periodic fees, except to cover normal operating costs and inflation. After the specified amount of nursing care is used, residents pay either a discounted rate or the full per diem rates for required nursing care.
- cA fee-for-service continuing-care contract includes residential facilities, meals, and other amenities as well as emergency and infirmary nursing care. Access to long-term nursing care is guaranteed, but it may be required at full per diem rates.
- aEstimating the amount of the advance fee and other fees to be paid by a resident
- bDetermining whether such fees will be sufficient to cover the cost of providing a resident's required services and the use of facilities.
- aAdvance fee only. Under this method, a resident pays an advance fee in return for future services and the use of facilities. Such services generally include continuing care retirement community housing-related services (for example, meals, laundry, housekeeping, and social services) and health care. These services usually are provided to the resident for the remainder of his or her life or until the contract is terminated. Additional periodic fees are not paid, regardless of how long a resident lives or if the resident requires more services than anticipated. Generally, the resident receives no ownership interest in the facility.
- bAdvance fee with periodic fees. Under this method, a resident pays an advance fee and periodic fees for services and the use of facilities. Such periodic fees may be fixed, or they may be subject to adjustment for increases in operating costs or inflation or for other economic reasons.
- cPeriodic fees only. Under this method, a resident pays a fee at periodic intervals for services and the use of the facilities provided by the continuing care retirement community. Such fees may be either fixed or adjustable.
440-954-15Scope and Scope Exceptions
Source downloaded: .Record version a2f7cf80960b. Effective date must be checked in the source.
Overall Guidance
440-954-25Recognition
Source downloaded: .Record version 09cace5207aa. Effective date must be checked in the source.
Continuing Care Retirement Community
440-954-35Subsequent Measurement
Source downloaded: .Record version 85dba59cc220. Effective date must be checked in the source.
Continuing Care Retirement Community
440-954-50Disclosure
Source downloaded: .Record version 27dfe97652fc. Effective date must be checked in the source.
Continuing Care Retirement Community
- aA description of the continuing care retirement community and the nature of the related continuing-care contracts entered into by the continuing care retirement community
- bThe carrying amount of the liability to provide future services and the use of facilities related to continuing-care contracts that is presented at present value in the financial statements (if not separately disclosed in the balance sheet)
- cThe interest rate used to discount that liability to provide future services
- dThe statutory escrow or similar requirements
- eThe refund policy of the continuing care retirement community and the general amount of refund obligation under the existing contracts.
440-954-55Implementation Guidance and Illustrations
Source downloaded: .Record version 0fe3587c0c30. Effective date must be checked in the source.
Illustrations
- a All residents pay a $ 50,000 fee, which is refundable less 2 percent per month for the first 36 months. After that period, none of the fee is refundable. The continuing care retirement community opened on 1/1/X4.
- b An additional periodic fee of $1,000 is payable monthly with a 5 percent increase annually.
- c The asset recognized for the incremental cost of obtaining the contract on 12/31/X6 is assumed to be $17,000.
- d The deferred revenue (contract liability) on 12/31/X6 is assumed to be $27,027.
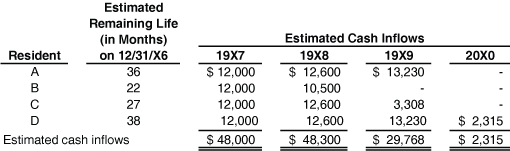 "Estimated Remaining Life (in Months) on 12/31/X6" Estimated Cash Inflows Resident 19X7 19X8 19X9 20X0 A 36 " $12,000 " " $12,600 " " $13,230 " - B 22 " 12,000 " " 10,500 " - - C 27 " 12,000 " " 12,600 " " 3,308 " - D 38 " 12,000 " " 12,600 " " 13,230 " " $2,315 " Estimated cash inflows " $48,000 " " $48,300 " " $29,768 " " $2,315 "
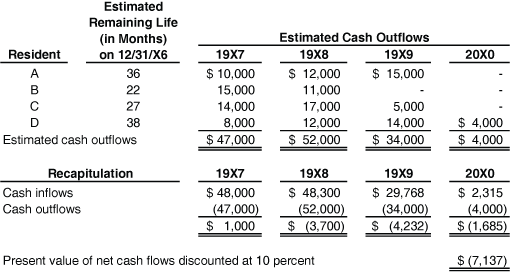 "Estimated Remaining Life (in Months) on 12/31/X6" Estimated Cash Outflows Resident 19X7 19X8 19X9 20X0 A 36 " $10,000 " " $12,000 " " $15,000 " - B 22 " 15,000 " " 11,000 " - - C 27 " 14,000 " " 17,000 " " 5,000 " - D 38 " 8,000 " " 12,000 " " 14,000 " " $4,000 " Estimated cash outflows " $47,000 " " $52,000 " " $34,000 " " $4,000 " Recapitulation 19X7 19X8 19X9 20X0 Cash inflows " $48,000 " " $48,300 " " $29,768 " " $2,315 " Cash outflows " (47,000)" " (52,000)" " (34,000)" " (4,000)" " $1,000 " " $(3,700)" " $(4,232)" " $(1,685)" Present value of net cash flows discounted at 10 percent " $(7,137)"
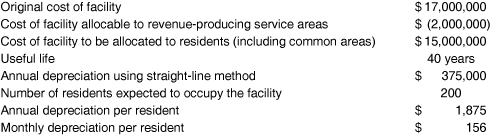 Original cost of facility " $17,000,000 " Cost of facility allocable to revenue-producing service areas " $(2,000,000)" Cost of facility to be allocated to residents (including common areas) " $15,000,000 " Useful life 40 years Annual depreciation using straight-line method " $375,000 " Number of residents expected to occupy the facility 200 Annual depreciation per resident " $1,875 " Monthly depreciation per resident $156
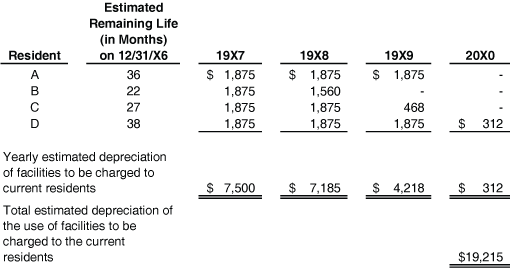 Resident "Estimated Remaining Life (in Months) on 12/31/X6" 19X7 19X8 19X9 20X0 A 36 " $1,875 " " $1,875 " " $1,875 " - B 22 " 1,875 " " 1,560 " - - C 27 " 1,875 " " 1,875 " 468 - D 38 " 1,875 " " 1,875 " " 1,875 " $312 Yearly estimated depreciation of facilities to be charged to current residents " $7,500 " " $7,185 " " $4,218 " $312 Total estimated depreciation of the use of facilities to be charged to the current residents " $19,215 "
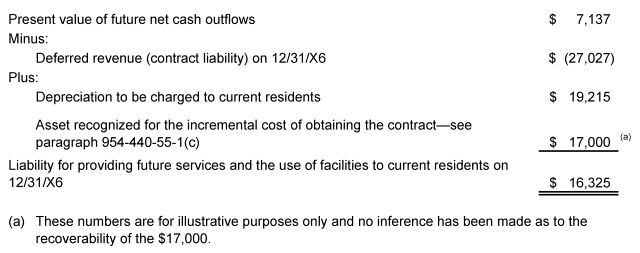 Present value of future net cash outflows " $7,137 " Minus: Deferred revenue (contract liability) on 12/31/X6 " $(27,027)" Plus: Depreciation to be charged to current residents " $19,215 " Asset recognized for the incremental cost of obtaining the contract—see paragraph 954-440-55-1(c) " $17,000 " (a) Liability for providing future services and the use of facilities to current residents on 12/31/X6 " $16,325 " (a) "These numbers are for illustrative purposes only and no inference has been made as to the recoverability of the $17,000."
440-954-60Relationships
Source downloaded: .Record version 038bb03abf16. Effective date must be checked in the source.
Related subtopics
- 605-944 Financial Services—InsuranceRevenue Recognition
- 410-20 Asset Retirement ObligationsAsset Retirement and Environmental Obligations
- 944-40 Claim Costs and Liabilities for Future Policy BenefitsFinancial Services—Insurance
- 405-954 Health Care EntitiesLiabilities
- 715-980 Regulated OperationsCompensation—Retirement Benefits
- 715-60 Defined Benefit Plans—Other PostretirementCompensation—Retirement Benefits