ASC 718-20
Awards Classified as Equity
718 Compensation—Stock Compensation
Source downloaded: .Record version 62c87311c221. Effective date must be checked in the source.
In brief
IntermediateStock compensationSubsequent measurementCompensation and benefitsDebt and equityASC 718-20 governs the subsequent measurement of share-based payment awards that are classified as equity (liability-classified awards go to 718-30, and general recognition/measurement rules stay in 718-10). Its core rules address awards whose grant-date fair value cannot be reasonably estimated (intrinsic value remeasurement through settlement), clawback and other contingent features (accounted for only when the contingent event occurs), and — most importantly — modification accounting, under which a modification is treated as an exchange of the original award for a new one, with incremental cost measured as the excess of the modified award's fair value over the original award's fair value immediately before modification. It also covers repurchases, cancellations, and cancellation-and-replacement transactions.
Key points (7)
- The Subtopic applies only to equity-classified share-based payment awards (718-20-15-2) and does not apply to equity instruments held by an ESOP (718-20-15-3).
- If fair value cannot be reasonably estimated at grant date, the instrument is remeasured at intrinsic value each reporting date through exercise or settlement, the final measure is intrinsic value at settlement, and the entity must continue the intrinsic value method even if fair value later becomes estimable (718-20-35-1).
- A clawback or similar contingent feature requiring the grantee to return earned instruments or gains is accounted for only if and when the contingent event occurs (718-20-35-2).
- Modification accounting is not required if all three conditions in 718-20-35-2A are met — unchanged fair value, unchanged vesting conditions, and unchanged equity/liability classification — but the 718-10-50 disclosures apply regardless.
- Otherwise a modification is an exchange of the original award for a new award: incremental cost equals the excess of the modified award's fair value over the original award's fair value immediately before modification, and total cost is that increment plus the grant-date fair value of the original award for which service is expected to be (or has been) rendered (718-20-35-3).
- Repurchase of an equity award is charged to equity up to the fair value of the instruments repurchased, with any excess recognized as additional compensation cost, and unrecognized grant-date cost is recognized at the repurchase date (718-20-35-7).
- Cancellation with a concurrent grant (or offer) of a replacement award or other valuable consideration is a modification (718-20-35-8); cancellation without replacement is a repurchase for no consideration, and previously unrecognized cost is recognized immediately (718-20-35-9).
For students. Modification accounting is the exam favorite here: remember total cost equals the original grant-date fair value expected to be earned PLUS incremental value at the modification date — a repricing never reduces previously measured cost, even if the modified award is worth less. A common error is assuming any change in terms triggers modification accounting; 718-20-35-2A exempts changes that leave fair value, vesting conditions, and classification all unchanged.
Machine-generated study aid for ASC 718-20. Check the source paragraphs below.
718-20-00Status
Source downloaded: .Record version 887f359d8ec9. Effective date must be checked in the source.
718-20-05Overview and Background
Source downloaded: .Record version 8d21851271ff. Effective date must be checked in the source.
718-20-15Scope and Scope Exceptions
Source downloaded: .Record version cedf13345ccb. Effective date must be checked in the source.
Overall Guidance
Transactions
718-20-35Subsequent Measurement
Source downloaded: .Record version 3f1c09867ccf. Effective date must be checked in the source.
Fair Value Not Reasonably Estimable
Contingent Features
Modification of an Award
- a The fair value (or calculated value or intrinsic value, if such an alternative measurement method is used) of the modified award is the same as the fair value (or calculated value or intrinsic value, if such an alternative measurement method is used) of the original award immediately before the original award is modified. If the modification does not affect any of the inputs to the valuation technique that the entity uses to value the award, the entity is not required to estimate the value immediately before and after the modification.
- b The vesting conditions of the modified award are the same as the vesting conditions of the original award immediately before the original award is modified.
- c The classification of the modified award as an equity instrument or a liability instrument is the same as the classification of the original award immediately before the original award is modified.
- a Incremental compensation cost shall be measured as the excess, if any, of the fair value of the modified award determined in accordance with the provisions of this Topic over the fair value of the original award immediately before its terms are modified, measured based on the share price and other pertinent factors at that date. As indicated in paragraph 718-10-30-20, references to fair value throughout this Topic shall be read also to encompass calculated value. The effect of the modification on the number of instruments expected to vest also shall be reflected in determining incremental compensation cost. The estimate at the modification date of the portion of the award expected to vest shall be subsequently adjusted, if necessary, in accordance with paragraph 718-10-35-1D or 718-10-35-3 and other guidance in Examples 14 through 15 (see paragraphs ).
- b Total recognized compensation cost for an equity award shall at least equal the fair value of the award at the grant date unless at the date of the modification the performance or service conditions of the original award are not expected to be satisfied. Thus, the total compensation cost measured at the date of a modification shall be the sum of the following:
- 1 The portion of the grant-date fair value of the original award for which the promised good is expected to be delivered (or has already been delivered) or the service is expected to be rendered (or has already been rendered) at that date
- 2 The incremental cost resulting from the modification.
Compensation cost shall be subsequently adjusted, if necessary, in accordance with paragraph 718-10-35-1D or 718-10-35-3 and other guidance in Examples 14 through 15 (see paragraphs ). - 1
- c A change in compensation cost for an equity award measured at intrinsic value in accordance with paragraph 718-20-35-1 shall be measured by comparing the intrinsic value of the modified award, if any, with the intrinsic value of the original award, if any, immediately before the modification.
718-20-55Implementation Guidance and Illustrations
Source downloaded: .Record version 3d22c1f933ef. Effective date must be checked in the source.
Implementation Guidance
Illustrations
- aShare options with cliff vesting and forfeitures estimated in initial accruals of compensation cost (Case A)
- bShare options with graded vesting and forfeitures estimated in initial accruals of compensation cost (Case B)
- cShare options with cliff vesting and forfeitures recognized when they occur (Case C).
- a The assumptions in paragraphs
- b Total compensation cost considerations (including estimates of forfeitures) in paragraphs
- c Changes in the estimation of forfeitures in paragraphs
- d Exercise or expiration considerations in paragraphs and 718-20-55-23.
- a In Case C, Entity T has an accounting policy to account for forfeitures when they occur in accordance with paragraph 718-10-35-3.
- b In Cases A and B, Entity T has an accounting policy to estimate the number of forfeitures expected to occur, also in accordance with paragraph 718-10-35-3.
- c In Case B, the share options have graded vesting.
- d In Cases A and C, the share options have cliff vesting.
-
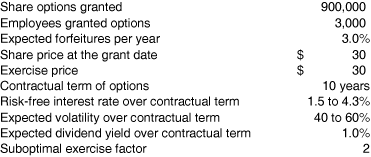 Share options granted "900,000 " Employees granted options "3,000 " Expected forfeitures per year 3.0% Share price at the grant date $30 Exercise price $30 Contractual term of options 10 years Risk-free interest rate over contractual term 1.5 to 4.3% Expected volatility over contractual term 40 to 60% Expected dividend yield over contractual term 1.0% Suboptimal exercise factor 2
-
 Compensation cost " $4,022,151 " Additional paid-in capital " $4,022,151 "
- To recognize compensation cost.
-
-
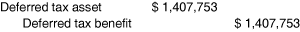 Deferred tax asset " $1,407,753 " Deferred tax benefit " $1,407,753 "
- To recognize the deferred tax asset for the temporary difference related to compensation cost ($4,022,151 ×.35 = $1,407,753).
-
- At December 31, 20X6, to adjust for new forfeiture rate.
-
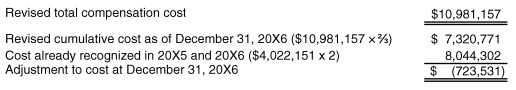 Revised total compensation cost " $10,981,157 " "Revised cumulative cost as of December 31, 20X6 ($10,981,157 × ⅔)" " $7,320,771 " "Cost already recognized in 20X5 and 20X6 ($4,022,151 x 2)" " 8,044,302 " "Adjustment to cost at December 31, 20X6" " $(723,531)"
-
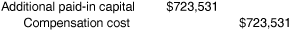 Additional paid-in capital " $723,531 " Compensation cost " $723,531 "
- To adjust previously recognized compensation cost and equity to reflect a higher estimated forfeiture rate.
-
-
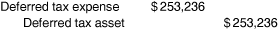 Deferred tax expense " $253,236 " Deferred tax asset " $253,236 "
- To adjust the deferred tax accounts to reflect the tax effect of increasing the estimated forfeiture rate ($723,531 ×.35 = $253,236).
-
-
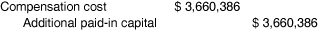 Compensation cost " $3,660,386 " Additional paid-in capital " $3,660,386 "
- To recognize compensation cost ($10,981,157 ÷ 3 = $3,660,386).
-
-
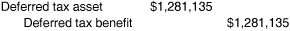 Deferred tax asset " $1,281,135 " Deferred tax benefit " $1,281,135 "
- To recognize the deferred tax asset for additional compensation cost ($3,660,386 ×.35 = $1,281,135).
-
-
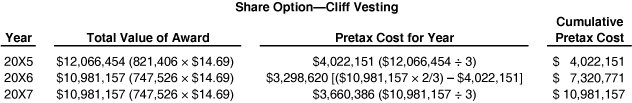 Share Option—Cliff Vesting Year Total Value of Award Pretax Cost for Year Cumulative Pretax Cost 20X5 "$12,066,454 (821,406 × $14.69)" "$4,022,151 ($12,066,454 ÷ 3)" " $4,022,151 " 20X6 "$10,981,157 (747,526 × $14.69)" "$3,298,620 [($10,981,157 × 2/3) - $4,022,151]" " $7,320,771 " 20X7 "$10,981,157 (747,526 × $14.69)" "$3,660,386 ($10,981,157 ÷ 3)" " $10,981,157 "
-
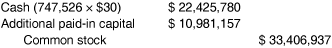 "Cash (747,526 × $30)" " $22,425,780 " Additional paid-in capital " $10,981,157 " Common stock " $33,406,937 "
- To recognize the issuance of common stock upon exercise of share options and to reclassify previously recorded paid-in capital.
-
-
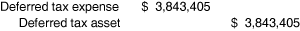 Deferred tax expense " $3,843,405 " Deferred tax asset " $3,843,405 "
- To write off the deferred tax asset related to deductible share options at exercise ($10,981,157 ×.35 = $3,843,405).
-
-
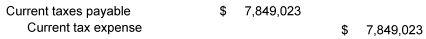 Current taxes payable " $7,849,023 " Current tax expense " $7,849,023 "
- To adjust current tax expense and current taxes payable to recognize the current tax benefit from deductible compensation cost upon exercise of share options.
-
- a On a straight-line basis over the requisite service period for each separately vesting portion of the award as if the award was, in-substance, multiple awards (graded vesting attribution method)
- b On a straight-line basis over the requisite service period for the entire award (that is, over the requisite service period of the last separately vesting portion of the award), subject to the limitation noted in paragraph 718-10-35-8.
-
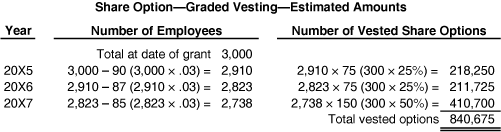 Share Option—Graded Vesting—Estimated Amounts Year Number of Employees Number of Vested Share Options Total at date of grant " 3,000 " 20X5 "3,000 - 90 (3,000 × .03) = " " 2,910 " "2,910 × 75 (300 × 25%) =" " 218,250 " 20X6 "2,910 - 87 (2,910 × .03) = " " 2,823 " "2,823 × 75 (300 × 25%) = " " 211,725 " 20X7 "2,823 - 85 (2,823 × .03) = " " 2,738 " "2,738 × 150 (300 × 50%) = " " 410,700 " Total vested options " 840,675 "
-
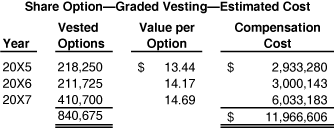 Share Option—Graded Vesting—Estimated Cost Year Vested Options Value per Option Compensation Cost 20X5 "218,250 " $13.44 " $2,933,280 " 20X6 "211,725 " 14.17 " 3,000,143 " 20X7 "410,700 " 14.69 " 6,033,183 " "840,675 " " $11,966,606 "
-
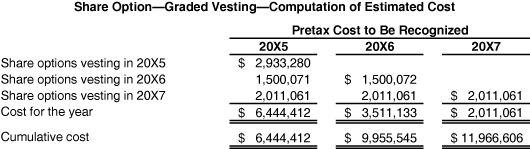 Share Option—Graded Vesting—Computation of Estimated Cost Pretax Cost to Be Recognized 20X5 20X6 20X7 Share options vesting in 20X5 " $2,933,280 " Share options vesting in 20X6 " 1,500,071 " " $1,500,072 " Share options vesting in 20X7 " 2,011,061 " " 2,011,061 " " $2,011,061 " Cost for the year " $6,444,412 " " $3,511,133 " " $2,011,061 " Cumulative cost " $6,444,412 " " $9,955,545 " " $11,966,606 "
-
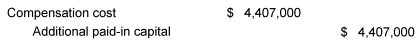 Compensation cost " $4,407,000 " Additional paid-in capital " $4,407,000
- To recognize compensation cost excluding the effect of forfeitures for 20X5.
-
-
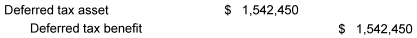 Deferred tax asset " $1,542,450 " Deferred tax benefit " $1,542,450 "
- To recognize the deferred tax asset for the temporary difference related to compensation cost ($4,407,000 × .35).
-
-
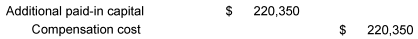 Additional paid-in capital " $220,350 " Compensation cost " $220,350 "
- To recognize the effect of forfeitures on compensation cost when they occur for 20X5.
-
-
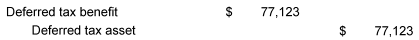 Deferred tax benefit " $77,123 " Deferred tax asset " $77,123 "
- To reverse the deferred tax asset related to the forfeited awards ($220,350 × .35).
-
-
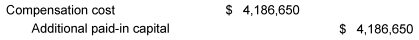 Compensation cost " $4,186,650 " Additional paid-in capital " $4,186,650 "
- To recognize compensation cost excluding the effect of awards that forfeited during 20X6.
-
-
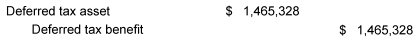 Deferred tax asset " $1,465,328 " Deferred tax benefit " $1,465,328 "
- To recognize the deferred tax asset for the temporary difference related to compensation cost ($4,186,650 × .35).
-
-
 Additonal paid-capital " $463,656 " Compensation cost " $463,656 "
- To recognize the effect of the forfeitures on compensation cost when they occur for 20X6.
-
-
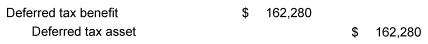 Deferred tax benefit " $162,280 " Deferred tax asset " $162,280 "
- To reverse the deferred tax asset related to the forfeited awards ($463,656 × .35).
-
- a Certain valuation assumptions in paragraph 718-20-55-36
- b Total compensation cost considerations provided in paragraphs (that is, an entity must consider if it is probable that specific performance conditions will be achieved for an award with a specified time period for vesting and performance conditions)
- c Forfeiture adjustments in paragraph 718-20-55-40.
-
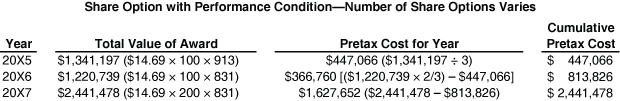 Share Option with Performance Condition—Number of Share Options Varies Year Total Value of Award Pretax Cost for Year Cumulative Pretax Cost 20X5 "$1,341,197 ($14.69 × 100 × 913)" "$447,066 ($1,341,197 ÷ 3)" " $447,066 " 20X6 "$1,220,739 ($14.69 × 100 × 831)" "$366,760 [($1,220,739 × 2/3) - $447,066]" " $813,826 " 20X7 "$2,441,478 ($14.69 × 200 × 831)" "$1,627,652 ($2,441,478 - $813,826)" " $2,441,478 "
- a Certain valuation assumptions in paragraphs
- b The total compensation cost considerations provided in paragraphs (that is, an entity must consider if it is probable that specific performance conditions will be achieved).
-
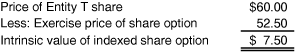 Price of Entity T share $60.00 Less: Exercise price of share option 52.50 Intrinsic value of indexed share option $7.50
-
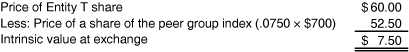 Price of Entity T share $60.00 Less: Price of a share of the peer group index (.0750 × $700) 52.50 Intrinsic value at exchange $7.50
-
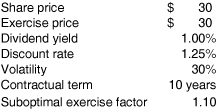 Share price $30 Exercise price $30 Dividend yield 1.00% Discount rate 1.25% Volatility 30% Contractual term 10 years Suboptimal exercise factor 1.10
- a The performance conditions in paragraph 718-20-55-62
- b Concepts about valuation, compensation cost reversal, and total compensation cost that should be recognized (that is, the consideration of whether it is probable that performance conditions will be achieved) in paragraphs 718-20-55-63 and .
- a If Entity T's share price has appreciated by a percentage that exceeds the percentage appreciation of the S&P 500 index by at least 10 percent (that is, the relative percentage increase is at least 10 percent), each share unit converts into 3 shares of Entity T stock.
- b If the relative percentage increase is less than 10 percent but greater than zero percent, each share unit converts into 2 shares of Entity T stock.
- c If the relative percentage increase is less than or equal to zero percent, each share unit converts into 1 share of Entity T stock.
- d If Entity T's share price has depreciated, each share unit converts into zero shares of Entity T stock.
-
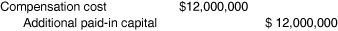 Compensation cost " $12,000,000 " Additional paid-in capital " $12,000,000 "
- To recognize compensation cost.
-
-
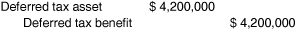 Deferred tax asset " $4,200,000 " Deferred tax benefit " $4,200,000 "
- To recognize the deferred tax asset for the temporary difference related to compensation cost ($12,000,000 ×.35 = $4,200,000).
-
-
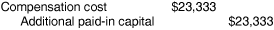 Compensation cost " $23,333 " Additional paid-in capital " $23,333 "
- To recognize compensation cost.
-
-
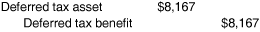 Deferred tax asset " $8,167 " Deferred tax benefit " $8,167 "
- To recognize the deferred tax asset for the temporary difference related to compensation cost ($23,333 ×.35 = $8,167).
-
-
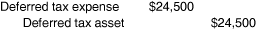 Deferred tax expense " $24,500 " Deferred tax asset " $24,500 "
- To write off deferred tax asset related to deductible share award at vesting ($70,000 ×.35 = $24,500).
-
-
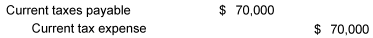 Current taxes payable $70,000 Current tax expense $70,000
- To adjust current tax expense and current taxes payable to recognize the current tax benefit from deductible compensation cost upon vesting of share award.
-
-
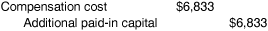 Compensation cost " $6,833 " Additional paid-in capital " $6,833 "
- To recognize compensation cost.
-
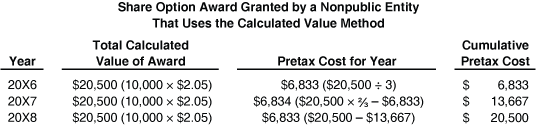 Share Option Award Granted by a Nonpublic Entity That Uses the Calculated Value Method Year "Total Calculated Value of Award" Pretax Cost for Year Cumulative Pretax Cost 20X6 " $20,500 (10,000 × $2.05) " " $6,833 ($20,500 ÷ 3) " " $6,833 " 20X7 " $20,500 (10,000 × $2.05) " " $6,834 ($20,500 × ⅔ - $6,833) " " $13,667 " 20X8 " $20,500 (10,000 × $2.05) " " $6,833 ($20,500 - $13,667) " " $20,500 "
- At exercise the journal entry is as follows.
-
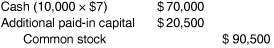 "Cash (10,000 × $7)" " $70,000 " Additional paid-in capital " $20,500 " Common stock " $90,500 "
- To recognize the issuance of shares upon exercise of options and to reclassify previously recognized paid-in capital.
-
-
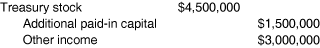 Treasury stock " $4,500,000 " Additional paid-in capital " $1,500,000 " Other income " $3,000,000 "
- To recognize the receipt of consideration as a result of the clawback feature.
-
-
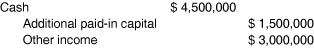 Cash " $4,500,000 " Additional paid-in capital " $1,500,000 " Other income " $3,000,000 "
- To recognize the receipt of consideration as a result of the clawback feature.
-
- a Modification of vested share options (Case A)
- b Share settlement of vested share options (Case B)
- c Modification of nonvested share options (Case C)
- d Cash settlement of nonvested share options (Case D).
-
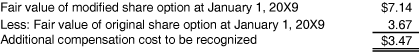 "Fair value of modified share option at January 1, 20X9" $7.14 "Less: Fair value of original share option at January 1, 20X9" 3.67 Additional compensation cost to be recognized $3.47
-
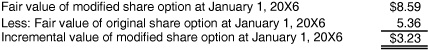 "Fair value of modified share option at January 1, 20X6" $8.59 "Less: Fair value of original share option at January 1, 20X6" 5.36 "Incremental value of modified share option at January 1, 20X6" $3.23
-
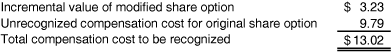 Incremental value of modified share option $3.23 Unrecognized compensation cost for original share option 9.79 Total compensation cost to be recognized $13.02
- aOriginal award contains antidilution provisions (Case A).
- bOriginal award does not contain antidilution provisions (Case B).
- cOriginal award does not contain an antidilution provision but is modified on the date of equity restructuring (Case C).
- a The awards ultimately vest under the modified vesting conditions
- b The awards ultimately would have vested under the original vesting conditions.
- a Type I probable to probable modification (Case A)
- b Type II probable to improbable modification (Case B)
- c Type III improbable to probable modification (Case C)
- d Type IV improbable to improbable modification (Case D).
- a Outcome 1—achievement of the modified sales target. In Outcome 1, all 10,000 share options vest because the salespeople sold at least 154,000 units of Product A. In that outcome, Entity T would recognize cumulative compensation cost of $146,900.
- b Outcome 2—achievement of the original sales target. In Outcome 2, no share options vest because the salespeople sold more than 150,000 units of Product A but less than 154,000 units (the modified sales target is not achieved). In that outcome, Entity T would recognize cumulative compensation cost of $146,900 because the share options would have vested under the original terms and conditions of the award.
- c Outcome 3—failure to achieve either sales target. In Outcome 3, no share options vest because the modified sales target is not achieved; additionally, no share options would have vested under the original terms and conditions of the award. In that case, Entity T would recognize cumulative compensation cost of $0.
-
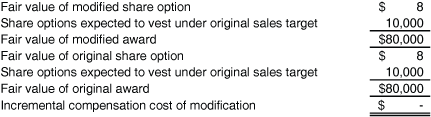 Fair value of modified share option $8 Share options expected to vest under original sales target " 10,000 " Fair value of modified award " $80,000 " Fair value of original share option $8 Share options expected to vest under original sales target " 10,000 " Fair value of original award " $80,000 " Incremental compensation cost of modification $-
- a Outcome 1—achievement of the modified sales target. In Outcome 1, all 10,000 share options vest because the salespeople sold at least 170,000 units of Product A. In that outcome, Entity T would recognize cumulative compensation cost of $146,900.
- b Outcome 2—achievement of the original sales target. In Outcome 2, no share options vest because the salespeople sold more than 150,000 units of Product A but less than 170,000 units (the modified sales target is not achieved). In that outcome, Entity T would recognize cumulative compensation cost of $146,900 because the share options would have vested under the original terms and conditions of the award.
- c Outcome 3—failure to achieve either sales target. In Outcome 3, no share options vest because the modified sales target is not achieved; additionally, no share options would have vested under the original terms and conditions of the award. In that case, Entity T would recognize cumulative compensation cost of $0.
-
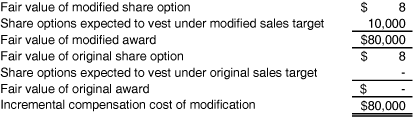 Fair value of modified share option $8 Share options expected to vest under modified sales target " 10,000 " Fair value of modified award " $80,000 " Fair value of original share option $8 Share options expected to vest under original sales target - Fair value of original award $- Incremental compensation cost of modification " $80,000 "
- a Outcome 1—achievement of the modified sales target. In Outcome 1, all 10,000 share options vest because the salespeople sold at least 120,000 units of Product A. In that outcome, Entity T would recognize cumulative compensation cost of $80,000.
- b Outcome 2—achievement of the original sales target and the modified sales target. In Outcome 2, Entity T would recognize cumulative compensation cost of $80,000 because in a Type III modification the original vesting condition is generally not relevant (that is, the modified award generally vests at a lower threshold of service or performance).
- c Outcome 3—failure to achieve either sales target. In Outcome 3, no share options vest because the modified sales target is not achieved; in that case, Entity T would recognize cumulative compensation cost of $0.
- a Outcome 1—achievement of the modified sales target. In Outcome 1, all 10,000 share options vest because the salespeople sold at least 130,000 units of Product A. In that outcome, Entity T would recognize cumulative compensation cost of $80,000 (10,000 × $8).
- b Outcome 2—achievement of the original sales target and the modified sales target. In Outcome 2, Entity T would recognize cumulative compensation cost of $80,000 because in a Type IV modification the original vesting condition is generally not relevant (that is, the modified award generally vests at a lower threshold of service or performance).
- c Outcome 3—failure to achieve either sales target. In Outcome 3, no share options vest because the modified sales target is not achieved; in that case, Entity T would recognize cumulative compensation cost of $0.
- a Equity to liability modification (share-settled share options to cash-settled share options) (Case A)
- b Equity to equity modification (share options to shares) (Case B)
- c Liability to equity modification (cash-settled to share-settled stock appreciation rights) (Case C)
- d Liability to liability modification (cash-settled to cash-settled stock appreciation rights) (Case D)
- e Equity to liability modification (share options to fixed cash payment) (Case E).
-
 Additional paid-in capital " $1,916,614 " Share-based compensation liability " $1,916,614 "
- To recognize the share-based compensation liability.
-
- a The grant-date fair value of the original equity award
- b The fair value of the modified liability award when it is settled.
-
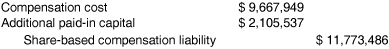 Compensation cost " $9,667,949 " Additional paid-in capital " $2,105,537 " Share-based compensation liability " $11,773,486 "
- To increase the share-based compensation liability to $13,690,100 and recognize compensation cost of $9,667,949 ($13,690,100 - $4,022,151).
-
-
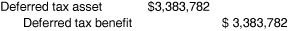 Deferred tax asset " $3,383,782 " Deferred tax benefit " $3,383,782 "
- To recognize the deferred tax asset for additional compensation cost ($9,667,949 ×.35 = $3,383,782).
-
-
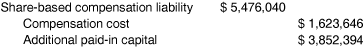 Share-based compensation liability " $5,476,040 " Compensation cost " $1,623,646 " Additional paid-in capital " $3,852,394 "
- To recognize a share-based compensation liability of $8,214,060, a reduction of compensation cost of $1,623,646 ($13,690,100 - $12,066,454), and additional paid-in capital of $3,852,394 ($12,066,454 - $8,214,060).
-
-
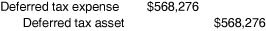 Deferred tax expense " $568,276 " Deferred tax asset " $568,276 "
- To reduce the deferred tax asset for the reduction in compensation cost ($1,623,646 ×.35 = $568,276).
-
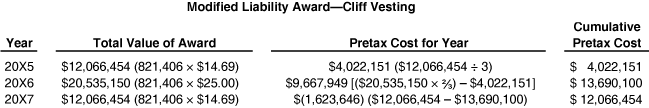 Modified Liability Award—Cliff Vesting Year Total Value of Award Pretax Cost for Year Cumulative Pretax Cost 20X5 " $12,066,454 (821,406 × $14.69) " " $4,022,151 ($12,066,454 ÷ 3) " " $4,022,151 " 20X6 " $20,535,150 (821,406 × $25.00) " " $9,667,949 [($20,535,150 × ⅔) - $4,022,151] " " $13,690,100 " 20X7 " $12,066,454 (821,406 × $14.69) " " $(1,623,646) ($12,066,454 - $13,690,100) " " $12,066,454 "
-
 Share-based compensation liability " $8,214,060 " "Cash ($10 × 821,406)" " $8,214,060 "
- To recognize the cash paid to settle share options.
-
-
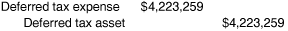 Deferred tax expense " $4,223,259 " Deferred tax asset " $4,223,259 "
- To write off deferred tax asset related to compensation cost ($12,066,454 ×.35 = $4,223,259).
-
-
 Current taxes payable " $2,874,921 " Additional paid-in capital " $1,348,338 " Current tax expense " $4,223,259 "
- To adjust current tax expense and current taxes payable for the tax benefit from deductible compensation cost upon settlement of share options.
-
-
 Compensation cost " $2,738,020 " Share-based compensation liability " $2,738,020 "
- To recognize compensation cost.
-
-
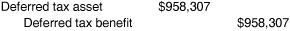 Deferred tax asset " $958,307 " Deferred tax benefit " $958,307 "
- To recognize the deferred tax asset for the temporary difference related to compensation cost ($2,738,020 ×.35 = $958,307).
-
-
 Share-based compensation liability " $2,738,020 " Additional paid-in capital " $2,738,020 "
- To reclassify the award as equity.
-
-
 Compensation cost " $1,369,010 " Share-based compensation liability " $1,369,010 "
- To recognize compensation cost.
-
-
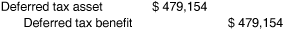 Deferred tax asset " $479,154 " Deferred tax benefit " $479,154 "
- To recognize the deferred tax asset for the temporary difference related to compensation cost ($1,369,010 ×.35 = $479,154).
-
-
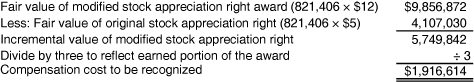 "Fair value of modified stock appreciation right award (821,406 × $12)" " $9,856,872 " "Less: Fair value of original stock appreciation right (821,406 × $5)" " 4,107,030 " Incremental value of modified stock appreciation right " 5,749,842 " Divide by three to reflect earned portion of the award ÷ 3 Compensation cost to be recognized " $1,916,614 "
-
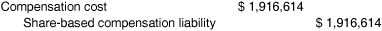 Compensation cost " $1,916,614 " Share-based compensation liability " $1,916,614 "
- To recognize incremental compensation cost.
-
-
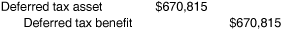 Deferred tax asset " $670,815 " Deferred tax benefit " $670,815 "
- To recognize the deferred tax asset for the temporary difference related to additional compensation cost ($1,916,614 ×.35 = $670,815).
-
718-20-65Transition and Open Effective Date Information
Source downloaded: .Record version 220f54d6b5a0. Effective date must be checked in the source.
Related subtopics
- 718-10 OverallCompensation—Stock Compensation
- 718-30 Awards Classified as LiabilitiesCompensation—Stock Compensation
- 718-740 Income TaxesCompensation—Stock Compensation
- 718-40 Employee Stock Ownership PlansCompensation—Stock Compensation
- 805-30 Goodwill or Gain from Bargain Purchase, Including Consideration TransferredBusiness Combinations
- 718-50 Employee Share Purchase PlansCompensation—Stock Compensation