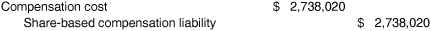ASC

ASC 718-30

Awards Classified as Liabilities

718 Compensation—Stock Compensation

Download JSONDownload Markdown39 paragraphs · 8 sectionsIncludes SEC contentJump to summary

Source downloaded: .Record version d8d386cfcfca. Effective date must be checked in the source.

ASC 718-30 governs share-based payment awards that are classified as liabilities rather than equity (e.g., cash-settled stock appreciation rights). Liability awards use the same grant-date measurement objective as equity awards, but the measurement date is the settlement date, so the liability is remeasured at fair value (or intrinsic value if a nonpublic entity so elects) at every reporting date through settlement. Changes in value during the requisite service (or nonemployee vesting) period are recognized as compensation cost in proportion to service rendered; changes after that period are expensed immediately in the period of change.

Key points (7)
  • The Subtopic applies to awards classified as liabilities by the grantor under paragraphs 718-10-25-6 through 25-19A, and does not apply to equity instruments held by an ESOP (718-30-15-2 through 15-3).
  • The grant-date measurement objective for liabilities is the same as for equity instruments (718-10-30-6), but the measurement date for liability instruments is the date of settlement (718-30-30-1).
  • A nonpublic entity makes a policy election to measure all liability-classified awards (employee and nonemployee) at fair value or at intrinsic value, except that awards that are consideration payable to a customer under 606-10-32-25 must be measured at fair value initially and subsequently (718-30-30-2; 718-30-35-4).
  • Liabilities incurred in share-based payment transactions are remeasured at the end of each reporting period through settlement (718-30-35-1; 718-30-35-3; 718-30-35-4).
  • During the requisite service period (employee) or vesting period (nonemployee), the accrued liability equals the percentage of fair (or intrinsic) value corresponding to the percentage of service rendered; value changes after that period are compensation cost of the period in which they occur (718-30-35-2).
  • Any difference between the settlement amount and the award's fair value at settlement date is an adjustment of compensation cost in the period of settlement (718-30-35-2).
  • A modification of a liability award is treated as an exchange of the original award for a new award, but no special guidance is needed if the award remains a liability because it is already remeasured each period (718-30-35-5); the fair-value-based method is preferable for a Topic 250 change in accounting principle (718-30-35-4).

For students. The exam trap is forgetting that liability awards are NOT frozen at grant-date fair value the way equity awards are — they are marked to fair value (or intrinsic value for electing nonpublic entities) every period until cash settlement, so compensation cost swings up and down with the stock price. Also remember the two-step math: liability = current value × % of requisite service rendered, and expense = change in that liability balance.

Machine-generated study aid for ASC 718-30. Check the source paragraphs below.

718-30-00Status

Source downloaded: .Record version e18ecb08dbe1. Effective date must be checked in the source.

718-30-00-1
The following table identifies the changes made to this Subtopic.
ParagraphActionAccounting Standards UpdateDate
AwardAmendedAccounting Standards Update No. 2018-0706/20/2018
Employee (2nd def.)AmendedAccounting Standards Update No. 2024-0311/04/2024
Grant DateAmendedAccounting Standards Update No. 2019-0811/11/2019
Grant DateAmendedAccounting Standards Update No. 2018-0706/20/2018
ModificationAmendedAccounting Standards Update No. 2017-0905/10/2017
Service Inception DateAmendedAccounting Standards Update No. 2018-0706/20/2018
Share OptionAmendedAccounting Standards Update No. 2018-0706/20/2018
VestAmendedAccounting Standards Update No. 2018-0706/20/2018
VolatilitySupersededAccounting Standards Update No. 2018-0706/20/2018
718-30-05-1AmendedAccounting Standards Update No. 2018-0706/20/2018
718-30-15-2AmendedAccounting Standards Update No. 2018-0706/20/2018
718-30-30-1 through 30-2AAmendedAccounting Standards Update No. 2018-0706/20/2018
718-30-30-2AmendedAccounting Standards Update No. 2019-0811/11/2019
718-30-30-2AAddedAccounting Standards Update No. 2016-0903/30/2016
AmendedAccounting Standards Update No. 2018-0706/20/2018
718-30-35-2AmendedAccounting Standards Update No. 2019-0811/11/2019
718-30-35-4AmendedAccounting Standards Update No. 2019-0811/11/2019
718-30-55-1AAddedAccounting Standards Update No. 2018-0706/20/2018
718-30-55-1BAddedAccounting Standards Update No. 2018-0706/20/2018
718-30-55-2AmendedAccounting Standards Update No. 2016-0903/30/2016
718-30-55-9AmendedAccounting Standards Update No. 2016-0903/30/2016
718-30-55-12AAddedAccounting Standards Update No. 2018-0706/20/2018
718-30-55-12BAddedAccounting Standards Update No. 2018-0706/20/2018

718-30-05Overview and Background

Source downloaded: .Record version f73798016a46. Effective date must be checked in the source.

718-30-05-1
Share-based payment awards may be classified as either equity or liabilities. This Subtopic addresses instruments classified as liabilities. It is closely intertwined with Subtopic 718-10, which contains guidance applicable to instruments classified as either equity or liabilities issued in share-based payment transactions. It may also be necessary in some cases to refer to the guidance contained in Subtopic 718-20.

718-30-15Scope and Scope Exceptions

Source downloaded: .Record version 8866095319d9. Effective date must be checked in the source.

Overall Guidance

718-30-15-1
This Subtopic follows the same Scope and Scope Exceptions as outlined in the Overall Subtopic, see Section 718-10-15, with specific transaction qualifications noted below.

Transactions

718-30-15-2
The guidance in this Subtopic applies to share-based payment awards that are classified as liabilities by the grantor (see paragraphs 718-10-25-6 through 25-19A for a description of what is classified as liability).
718-30-15-3
The guidance in this Subtopic does not apply to equity instruments held by an employee stock ownership plan.

718-30-30Initial Measurement

Source downloaded: .Record version 8648ba5ca6e1. Effective date must be checked in the source.

Measurement Objective and Measurement Date

718-30-30-1
At the grant date, the measurement objective for liabilities incurred under share-based compensation arrangements is the same as the measurement objective for equity instruments awarded to grantees as described in paragraph 718-10-30-6. However, the measurement date for liability instruments is the date of settlement.
718-30-30-2
A nonpublic entity shall make a policy decision of whether to measure all of its liabilities incurred under share-based payment arrangements (for employee and nonemployee awards) issued in exchange for distinct goods or services at fair value or at intrinsic value. However, a nonpublic entity shall initially and subsequently measure awards determined to be consideration payable to a customer (as described in paragraph 606-10-32-25) at fair value.

718-30-35Subsequent Measurement

Source downloaded: .Record version 62e5814bafa0. Effective date must be checked in the source.

Measurement

718-30-35-1
The fair value of liabilities incurred in share-based payment transactions shall be remeasured at the end of each reporting period through settlement.
718-30-35-2
Changes in the fair value (or intrinsic value for a nonpublic entity that elects that method) of a liability incurred under a share-based payment arrangement issued in exchange for goods or services that occur during the employee's requisite service period or the nonemployee's vesting period shall be recognized as compensation cost over that period. The percentage of the fair value (or intrinsic value) that is accrued as compensation cost at the end of each period shall equal the percentage of the requisite service that has been rendered for an employee award or the percentage that would have been recognized had the grantor paid cash for the goods or services instead of paying with a nonemployee award at that date. Changes in the fair value (or intrinsic value) of a liability issued in exchange for goods or services that occur after the end of the employee's requisite service period or the nonemployee's vesting period are compensation cost of the period in which the changes occur. Any difference between the amount for which a liability award issued in exchange for goods or services is settled and its fair value at the settlement date as estimated in accordance with the provisions of this Subtopic is an adjustment of compensation cost in the period of settlement. Example 1 (see paragraph 718-30-55-1) provides an illustration of accounting for a liability award issued in exchange for service from the grant date through its settlement.
718-30-35-3
A public entity shall measure a liability award under a share-based payment arrangement based on the award's fair value remeasured at each reporting date until the date of settlement. Compensation cost for each period until settlement shall be based on the change (or a portion of the change, depending on the percentage of the requisite service that has been rendered for an employee award or the percentage that would have been recognized had the grantor paid cash for the goods or services instead of paying with a nonemployee award at the reporting date) in the fair value of the instrument for each reporting period. Example 1 (see paragraph 718-30-55-1) provides an illustration of accounting for an instrument classified as a liability using the fair-value-based method.
718-30-35-4
Regardless of the measurement method initially selected under paragraph 718-10-30-20, a nonpublic entity shall remeasure its liabilities under share-based payment arrangements at each reporting date until the date of settlement. The fair-value-based method is preferable for purposes of justifying a change in accounting principle under Topic 250. Example 1 (see paragraph 718-30-55-1) provides an illustration of accounting for an instrument classified as a liability using the fair-value-based method. Example 2 (see paragraph 718-30-55-12) provides an illustration of accounting for an instrument classified as a liability using the intrinsic value method. A nonpublic entity shall subsequently measure awards determined to be consideration payable to a customer (as described in paragraph 606-10-32-25) at fair value.

Modification of an Award

718-30-35-5
A modification of a liability award is accounted for as the exchange of the original award for a new award. However, because liability awards are remeasured at their fair value (or intrinsic value for a nonpublic entity that elects that method) at each reporting date, no special guidance is necessary in accounting for a modification of a liability award that remains a liability after the modification (see Example 15, Case C [paragraph718-20-55-135] for what happens when the modification causes the award to no longer be a liability).

718-30-55Implementation Guidance and Illustrations

Source downloaded: .Record version af8d4a931ab3. Effective date must be checked in the source.

Illustrations

718-30-55-1
This Example illustrates the guidance in paragraphs and .
718-30-55-1A
This Example (see paragraphs ) describes employee awards. However, the principles on how to account for the various aspects of employee awards, except for the compensation cost attribution and certain inputs to valuation, are the same for nonemployee awards. Consequently, the concepts about valuation and forfeiture estimation and remeasurement of awards, exercise, and expiration in paragraphs are equally applicable to nonemployee awards with the same features as the awards in this Example (that is, awards with a specified period of time for vesting classified as liabilities). Therefore, the guidance in those paragraphs may serve as implementation guidance for similar nonemployee awards.
718-30-55-1B
Compensation cost attribution for awards to nonemployees may be the same or different for employee awards. That is because an entity is required to recognize compensation cost for nonemployee awards in the same manner as if the entity had paid cash in accordance with paragraph 718-10-25-2C. Additionally, valuation amounts used in this Example could be different because an entity may elect to use the contractual term as the expected term of share options and similar instruments when valuing nonemployee share-based payment transactions.
718-30-55-2
Entity T, a public entity, grants share appreciation rights with the same terms and conditions as those described in Example 1 (see paragraph 718-20-55-4). As in Example 1, Case A, Entity T makes an accounting policy election in accordance with paragraph 718-10-35-3 to estimate the number of forfeitures expected to occur and includes that estimate in its initial accrual of compensation costs. Each stock appreciation right entitles the holder to receive an amount in cash equal to the increase in value of 1 share of Entity T stock over $30. Entity T determines the grant-date fair value of each stock appreciation right in the same manner as a share option and uses the same assumptions and option-pricing model used to estimate the fair value of the share options in that Example; consequently, the grant-date fair value of each stock appreciation right is $14.69 (see paragraphs ). The awards cliff-vest at the end of three years of service (an explicit and requisite service period of three years). The number of stock appreciation rights for which the requisite service is expected to be rendered is estimated at the grant date to be 821,406 (900,000 ×.973). Thus, the fair value of the award as of January 1, 20X5, is $12,066,454 (821,406 × $14.69). For simplicity, this Example assumes that estimated forfeitures equal actual forfeitures.
718-30-55-3
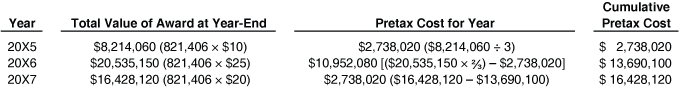
Paragraph 718-30-35-4 permits a nonpublic entity to measure share-based payment liabilities at either fair value (or, in some cases, calculated value) or intrinsic value. If a nonpublic entity elects to measure those liabilities at fair value, the accounting demonstrated in this Example would be applicable. Paragraph 718-30-35-3 requires that share-based compensation liabilities be recognized at fair value or a portion thereof (depending on the percentage of requisite service rendered at the reporting date) and be remeasured at each reporting date through the date of settlement; consequently, compensation cost recognized during each year of the three-year vesting period (as well as during each year thereafter through the date of settlement) will vary based on changes in the award's fair value. As of December 31, 20X5, the assumed fair value is $10 per stock appreciation right; hence, the fair value of the award is $8,214,060 (821,406 × $10). The share-based compensation liability as of December 31, 20X5, is $2,738,020 ($8,214,060 ÷ 3) to account for the portion of the award related to the service rendered in 20X5 (1 year of the 3-year requisite service period). For convenience, this Example assumes that journal entries to account for the award are performed at year-end. The journal entries for 20X5 are as follows.
  • Compensation cost " $2,738,020 " Share-based compensation liability " $2,738,020 "
    • To recognize compensation cost.
  • Deferred tax asset " $958,307 " Deferred tax benefit " $958,307 "
    • To recognize the deferred tax asset for the temporary difference related to compensation cost ($2,738,020 ×.35 = $958,307).
718-30-55-4
As of December 31, 20X6, the fair value is assumed to be $25 per stock appreciation right; hence, the award's fair value is $20,535,150 (821,406 × $25), and the corresponding liability at that date is $13,690,100 ($20,535,150 × 2/3) because service has been provided for 2 years of the 3-year requisite service period. Compensation cost recognized for the award in 20X6 is $10,952,080 ($13,690,100 - $2,738,020). Entity T recognizes the following journal entries for 20X6.
  • Compensation cost " $10,952,080 " Share-based compensation liability " $10,952,080 "
    • To recognize a share-based compensation liability of $13,690,100 and associated compensation cost.
  • Deferred tax asset " $3,833,228 " Deferred tax benefit " $3,833,228 "
    • To recognize the deferred tax asset for additional compensation cost ($10,952,080 ×.35 = $3,833,228).
718-30-55-5
As of December 31, 20X7, the fair value is assumed to be $20 per stock appreciation right; hence, the award's fair value is $16,428,120 (821,406 × $20), and the corresponding liability at that date is $16,428,120 ($16,428,120 × 1) because the award is fully vested. Compensation cost recognized for the liability award in 20X7 is $2,738,020 ($16,428,120 - $13,690,100). Entity T recognizes the following journal entries for 20X7.
  • Compensation cost " $2,738,020 " Share-based compensation liability " $2,738,020 "
    • To recognize a share-based compensation liability of $16,428,120 and associated compensation cost.
  • Deferred tax asset " $958,307 " Deferred tax benefit " $958,307 "
    • To recognize the deferred tax asset for additional compensation cost ($2,738,020 ×.35 = $958,307).
718-30-55-6
The share-based liability award is as follows.
  • Year Total Value of Award at Year-End Pretax Cost for Year Cumulative Pretax Cost 20X5 " $8,214,060 (821,406 × $10) " " $2,738,020 ($8,214,060 ÷ 3) " " $2,738,020 " 20X6 " $20,535,150 (821,406 × $25) " " $10,952,080 [($20,535,150 × ⅔) - $2,738,020] " " $13,690,100 " 20X7 " $16,428,120 (821,406 × $20) " " $2,738,020 ($16,428,120 - $13,690,100) " " $16,428,120 "
718-30-55-7
For simplicity, this Example assumes that all of the stock appreciation rights are exercised on the same day, that the liability award's fair value is $20 per stock appreciation right, and that Entity T has already recognized its income tax expense for the year without regard to the effects of the exercise of the employee stock appreciation rights. In other words, current tax expense and current taxes payable were recognized based on taxable income and deductions before consideration of additional deductions from exercise of the stock appreciation rights. The amount credited to cash for the exercise of the stock appreciation rights is equal to the share-based compensation liability of $16,428,120.
718-30-55-8
At exercise the journal entry is as follows.
  • Share-based compensation liability " $16,428,120 " "Cash (821,406 × $20)" " $16,428,120 "
    • To recognize the cash payment to employees from stock appreciation right exercise.
718-30-55-9
The cash paid to the employees on the date of exercise is deductible for tax purposes. The tax benefit is $5,749,842 ($16,428,120 ×.35).
718-30-55-10
At exercise the journal entry is as follows.
  • Deferred tax expense " $5,749,842 " Deferred tax asset " $5,749,842 "
    • To write off the deferred tax asset related to the stock appreciation rights.
  • Current taxes payable " $5,749,842 " Current tax expense " $5,749,842 "
    • To adjust current tax expense and current taxes payable to recognize the current tax benefit from deductible compensation cost.
718-30-55-11
If the stock appreciation rights had expired worthless, the share-based compensation liability account and deferred tax asset account would have been adjusted to zero through the income statement as the award's fair value decreased.
718-30-55-12
This Example illustrates the guidance in paragraphs 718-30-35-4 and .
718-30-55-12A
This Example (see paragraphs ) describes employee awards. However, the principles on how to account for the various aspects of employee awards, except for the compensation cost attribution and certain inputs to valuation, are the same for nonemployee awards. Consequently, a nonpublic entity can make the accounting policy election in paragraph 718-30-30-2 to change its measurement of all liability-classified nonemployee awards from fair value to intrinsic value and remeasure those awards each reporting period as illustrated in this Example. Therefore, the guidance in this Example may serve as implementation guidance for similar liability-classified nonemployee awards.
718-30-55-12B
Compensation cost attribution for awards to nonemployees may be the same or different for liability-classified employee awards. That is because an entity is required to recognize compensation cost for nonemployee awards in the same manner as if the entity had paid cash in accordance with paragraph 718-10-25-2C. Additionally, valuation amounts used in this Example could be different because an entity may elect to use the contractual term as the expected term of share options and similar instruments when valuing nonemployee share-based payment transactions.
718-30-55-13
On January 1, 20X6, Entity W, a nonpublic entity that has chosen the accounting policy of using the intrinsic value method of accounting for share-based payments that are classified as liabilities in accordance with paragraphs 718-30-30-2 and 718-30-35-4, grants 100 cash-settled stock appreciation rights with a 5-year life to each of its 100 employees. Each stock appreciation right entitles the holder to receive an amount in cash equal to the increase in value of 1 share of Entity W's stock over $7. The awards cliff-vest at the end of three years of service (an explicit and requisite service period of three years). For simplicity, the Example assumes that no forfeitures occur during the vesting period and does not reflect the accounting for income tax consequences of the awards.
718-30-55-14
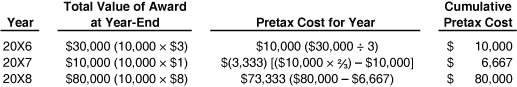
Because of Entity W's accounting policy decision to use intrinsic value, all of its share-based payments that are classified as liabilities are recognized at intrinsic value (or a portion thereof, depending on the percentage of requisite service that has been rendered) at each reporting date through the date of settlement; consequently, the compensation cost recognized in each year of the three-year requisite service period will vary based on changes in the liability award's intrinsic value. As of December 31, 20X6, Entity W stock is valued at $10 per share; hence, the intrinsic value is $3 per stock appreciation right ($10 - $7), and the intrinsic value of the award is $30,000 (10,000 × $3). The compensation cost to be recognized for 20X6 is $10,000 ($30,000 ÷ 3), which corresponds to the service provided in 20X6 (1 year of the 3-year service period). For convenience, this Example assumes that journal entries to account for the award are performed at year-end. The journal entry for 20X6 is as follows.
  • Compensation cost " $10,000 " Share-based compensation liability " $10,000 "
    • To recognize compensation cost.
718-30-55-15
As of December 31, 20X7, Entity W stock is valued at $8 per share; hence, the intrinsic value is $1 per stock appreciation right ($8 - $7), and the intrinsic value of the award is $10,000 (10,000 × $1). The decrease in the intrinsic value of the award is $20,000 ($10,000 - $30,000). Because services for 2 years of the 3-year service period have been rendered, Entity W must recognize cumulative compensation cost for two-thirds of the intrinsic value of the award, or $6,667 ($10,000 × 2/3); however, Entity W recognized compensation cost of $10,000 in 20X5. Thus, Entity W must recognize an entry in 20X7 to reduce cumulative compensation cost to $6,667.
  • Share-based compensation liability " $3,333 " Compensation cost " $3,333 "
    • To adjust cumulative compensation cost ($6,667 - $10,000).
718-30-55-16
As of December 31, 20X8, Entity W stock is valued at $15 per share; hence, the intrinsic value is $8 per stock appreciation right ($15 - $7), and the intrinsic value of the award is $80,000 (10,000 × $8). The cumulative compensation cost recognized as of December 31, 20X8, is $80,000 because the award is fully vested. The journal entry for 20X8 is as follows.
  • Compensation cost " $73,333 " Share-based compensation liability " $73,333 "
    • To recognize compensation cost ($80,000 - $6,667).
718-30-55-17
The share-based liability award at intrinsic value is as follows.
  • Year Total Value of Award at Year-End Pretax Cost for Year Cumulative Pretax Cost 20X6 " $30,000 (10,000 × $3) " " $10,000 ($30,000 ÷ 3) " " $10,000 " 20X7 " $10,000 (10,000 × $1) " " $(3,333) [($10,000 × ⅔) - $10,000] " " $6,667 " 20X8 " $80,000 (10,000 × $8) " " $73,333 ($80,000 - $6,667) " " $80,000 "
718-30-55-18
For simplicity, this Example assumes that all of the stock appreciation rights are settled on the day that they vest, December 31, 20X8, when the share price is $15 and the intrinsic value is $8 per share. The cash paid to settle the stock appreciation rights is equal to the share-based compensation liability of $80,000.
718-30-55-19
At exercise the journal entry is as follows.
  • Share-based compensation liability " $80,000 " "Cash (10,000 × $8)" " $80,000 "
    • To recognize the cash payment to employees for settlement of stock appreciation rights.
718-30-55-20
If the stock appreciation rights had not been settled, Entity W would continue to remeasure those remaining awards at intrinsic value at each reporting date through the date they are exercised or otherwise settled.

718-30-S00StatusSEC

Source downloaded: .Record version c9b05c1e1546. Effective date must be checked in the source.

718-30-S00-1
The following table identifies the changes made to this Subtopic.
ParagraphActionAccounting Standards UpdateDate
718-30-S55-1AmendedAccounting Standards Update No. 2009-0408/26/2009

718-30-S55Implementation Guidance and IllustrationsSEC

Source downloaded: .Record version a0a0ec959608. Effective date must be checked in the source.

Certain Redeemable Financial Instruments Issued in Conjunction with Share-Based Payment Arrangements

718-30-S55-1
See paragraph 718-10-S99-1, SAB Topic 14.E, and paragraph 480-10-S99-3A, SEC Staff Announcement: Classification and Measurement of Redeemable Securities, for SEC Staff views on awards with redemption features issued in conjunction with share-based payment arrangements.

Related subtopics