ASC 718-40
Employee Stock Ownership Plans
718 Compensation—Stock Compensation
Source downloaded: .Record version c13828137699. Effective date must be checked in the source.
ASC 718-40 governs the employer's (sponsor's) accounting for employee stock ownership plans (ESOPs), distinguishing leveraged from nonleveraged plans. For leveraged ESOPs, the employer records the ESOP's outside debt as its own debt, charges shares issued to the ESOP to a contra-equity account ("unearned ESOP shares"), and recognizes compensation cost at the fair value of shares as they are committed to be released; for nonleveraged ESOPs, compensation cost equals the contribution called for in the period. It also prescribes dividend treatment (allocated shares to retained earnings; unallocated shares as debt reduction or compensation cost), EPS treatment, termination accounting, and disclosures.
Key points (7)
- An employer reports shares issued or treasury shares sold to an ESOP when the transaction occurs, with a corresponding charge to unearned ESOP shares, a contra-equity account presented separately in the balance sheet (718-40-25-10; 718-40-45-2).
- Debt of a leveraged ESOP owed to an outside lender (direct or indirect loan) is reported as the employer's debt with accrued interest cost, but an employer loan to its own ESOP is not reported as a note receivable/payable and generates no interest income or cost (718-40-25-9).
- Compensation cost and settlement of liabilities are recognized when shares are 'committed to be released' (which may precede legal release), measured at the fair value of those shares, generally using average fair value for shares released ratably as service is rendered (718-40-25-13; 718-40-30-1; 718-40-30-2).
- Unearned ESOP shares are credited at the ESOP's cost of the shares, and the difference between fair value and cost is charged or credited to shareholders' equity in the same manner as gains and losses on sales of treasury stock, generally additional paid-in capital (718-40-30-3).
- Dividends on allocated shares are charged to retained earnings, while dividends on unallocated shares are not dividends for reporting purposes—they reduce debt/accrued interest if used for debt service or are compensation cost if paid to participants (718-40-25-16; 718-40-25-17).
- For a nonleveraged ESOP, compensation cost equals the contribution called for in the period measured at the fair value of shares or cash contributed, and all shares held are treated as outstanding for EPS except pension reversion suspense shares (718-40-25-19; 718-40-30-5; 718-40-45-9).
- For EPS, only ESOP shares committed to be released are considered outstanding; uncommitted shares (including uncommitted convertible preferred) are excluded from basic and if-converted diluted computations, and required disclosures include allocated, committed-to-be-released, and suspense share counts, compensation cost, fair value of unearned shares, and any repurchase obligation (718-40-45-3; 718-40-45-6; 718-40-50-1).
For students. The classic trap is timing and measurement: compensation cost is recognized when shares are *committed to be released* (not legally released) and is measured at the shares' *fair value*, while unearned ESOP shares are relieved at the ESOP's original *cost*, with the difference plugged to additional paid-in capital. Also remember that dividends on unallocated shares are not treated as dividends—they reduce debt or become compensation cost.
Machine-generated study aid for ASC 718-40. Check the source paragraphs below.
718-40-00Status
Source downloaded: .Record version a2ea8833ce4e. Effective date must be checked in the source.
718-40-05Overview and Background
Source downloaded: .Record version ccb32bddff79. Effective date must be checked in the source.
- aGeneral
- bLeveraged employee stock ownership plans
- cNonleveraged employee stock ownership plans.
- aTo fund a matching program for a sponsor's 401(k) saving plan, formula-based profit-sharing plan, and other employee benefits
- bTo raise new capital or to create a marketplace for the existing stock
- cTo replace lost benefits from the termination of other retirement plans or provide benefits under postretirement benefit plans, particularly medical benefits
- dTo be part of the financing package in leveraged buy-outs
- eTo provide a tax-advantaged means for owners to terminate their ownership
- fTo be part of a long-term program to restructure the equity section of a plan sponsor's balance sheet
- gTo defend the entity against hostile takeovers.
Leveraged Employee Stock Ownership Plans
Nonleveraged Employee Stock Ownership Plans
718-40-15Scope and Scope Exceptions
Source downloaded: .Record version 9cd9c7c2882e. Effective date must be checked in the source.
Overall Guidance
Entities
Transactions
Other Considerations
- aFinancial reporting by employee stock ownership plans.
Leveraged Employee Stock Ownership Plans
Overall Guidance
Nonleveraged Employee Stock Ownership Plans
718-40-25Recognition
Source downloaded: .Record version 31777c6f290b. Effective date must be checked in the source.
- aStock with a put option or a guaranteed redemption price (treasury stock recognition)
- bPension reversion employee stock ownership plans (recognition of assets transferred from the pension plan).
Stock with a Put Option or a Guaranteed Redemption Price
Pension Reversion Employee Stock Ownership Plans
Leveraged Employee Stock Ownership Plans
- aDebt financing
- bPurchase of shares by a leveraged employee stock ownership plan
- cRelease of leveraged employee stock ownership plan shares
- dDividends on employee stock ownership plan shares
Debt Financing
- aEmployers that sponsor an employee stock ownership plan with a direct loan shall report the obligations of the employee stock ownership plan to the outside lender as debt. Furthermore, employers shall accrue interest cost on the debt and shall report cash payments to the employee stock ownership plan that are used by the employee stock ownership plan to service debt, regardless of whether the source of cash is employer contributions or dividends, as reductions of the debt and accrued interest payable when the employee stock ownership plan makes the payments to the outside lender.
- bEmployers that sponsor an employee stock ownership plan with an indirect loan shall report outside loans as debt. Employers shall not report a loan receivable from the employee stock ownership plan as an asset and shall, therefore, not recognize interest income on such receivable. Employers shall accrue interest cost on the outside loan and shall report loan payments as reductions of the principal and accrued interest payable. Contributions to the employee stock ownership plan and the concurrent payments from the employee stock ownership to the employer for debt service would not be recognized in the employer's financial statements.
- cEmployee stock ownership plans with indirect loans and employer loans are often referred to as internally leveraged.
- dEmployers that sponsor an employee stock ownership plan with an employer loan shall not report the employee stock ownership plan's note payable and the employer's note receivable in the employer's balance sheet. Accordingly, employers shall not recognize interest cost or interest income on an employer loan.
Purchase of Shares by a Leveraged Employee Stock Ownership Plan
Release of Leveraged Employee Stock Ownership Plan Shares
- aTo compensate employees directly
- bTo settle employer liabilities for other employee benefits
- cTo replace dividends on allocated shares that are used for debt service.
- aCompensation cost
- bDividends payable
- cCompensation liabilities.
Dividends on Employee Stock Ownership Plan Shares
Nonleveraged Employee Stock Ownership Plans
- aContribution of shares to the employee stock ownership plan
- bDividends on employee stock ownership plan shares
- cShares allocated by year-end
Contribution of Shares to the Employee Stock Ownership Plan
Dividends on Employee Stock Ownership Plan Shares
Shares Allocated by Year-End
718-40-30Initial Measurement
Source downloaded: .Record version 376ade4cc0d4. Effective date must be checked in the source.
Leveraged Employee Stock Ownership Plans
Nonleveraged Employee Stock Ownership Plans
718-40-35Subsequent Measurement
Source downloaded: .Record version 45002f3ec875. Effective date must be checked in the source.
Leveraged Employee Stock Ownership Plans
Debt Repayment
718-40-40Derecognition
Source downloaded: .Record version c1e0085233a7. Effective date must be checked in the source.
Leveraged Employee Stock Ownership Plans
Plan Termination
718-40-45Other Presentation Matters
Source downloaded: .Record version 0febae411796. Effective date must be checked in the source.
EPS
Issuance of Shares or the Sale of Shares to an Employee Stock Ownership Plan
Leveraged Employee Stock Ownership Plans
EPS
- aThe shares issuable at the stated conversion rate
- bThe shares issuable if the participants were to withdraw the shares from their accounts.
Nonleveraged Employee Stock Ownership Plans
718-40-50Disclosure
Source downloaded: .Record version 8279cefeeae1. Effective date must be checked in the source.
- aA description of the plan, the basis for determining contributions, including the employee groups covered, and the nature and effect of significant matters affecting comparability of information for all periods presented. For leveraged employee stock ownership plans and pension reversion employee stock ownership plans, the description shall include the basis for releasing shares and how dividends on allocated and unallocated shares are used.
- bA description of the accounting policies followed for employee stock ownership plan transactions, including the method of measuring compensation, the classification of dividends on employee stock ownership plan shares, and the treatment of employee stock ownership plan shares for earnings per share (EPS) computations. If the employer has both old employee stock ownership plan shares for which it does not adopt the guidance in this Subtopic and new employee stock ownership plan shares for which the guidance in this Subtopic is required, the accounting policies for both blocks of shares shall be described.
- cThe amount of compensation cost recognized during the period.
- dThe number of allocated shares, committed-to-be-released shares, and suspense shares held by the employee stock ownership plan at the balance-sheet date. This disclosure shall be made separately for shares accounted for under this Subtopic and for grandfathered employee stock ownership plan shares.
- eThe fair value of unearned employee stock ownership plan shares at the balance-sheet date for shares accounted for under this Subtopic. (Future tax deductions will be allowed only for the employee stock ownership plan's cost of unearned employee stock ownership plan shares.) This disclosure need not be made for old employee stock ownership plan shares for which the employer does not apply the guidance in this Subtopic.
- fThe existence and nature of any repurchase obligation, including disclosure of the fair value (see paragraph 718-40-30-4) of the shares allocated as of the balance sheet date, which are subject to a repurchase obligation.
- gThe amount and treatment in the EPS computation of the tax benefit related to dividends paid to any employee stock ownership plan, if material.
718-40-55Implementation Guidance and Illustrations
Source downloaded: .Record version 9468a7d23a3c. Effective date must be checked in the source.
Illustrations
Leveraged Employee Stock Ownership Plans
- aA common-stock leveraged employee stock ownership plan with a direct loan (Case A)
- bA common-stock leveraged employee stock ownership plan used to fund the employer's match of a 401(k) savings plan with an indirect loan (Case B)
- cA convertible-preferred-stock leveraged employee stock ownership plan with a direct loan (Case C).
- a On January 1, Year 1, Entity A establishes a leveraged employee stock ownership plan.
- b The employee stock ownership plan borrows $1,000,000 from an outside lender at 10 percent for 5 years and uses the proceeds to buy 100,000 shares of newly issued common stock of the sponsor for $10 per share, which is the market price of those shares on the date of issuance.
- c Debt service is funded by cash contributions and dividends on employer stock held by the employee stock ownership plan.
- d Dividends on all shares held by the employee stock ownership plan are used for debt service.
- e Cash contributions are made at the end of each year.
- f The year-end and average market values of a share of common stock follow.
-
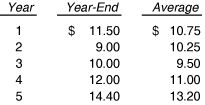 Year Year-End Average 1 $11.50 $10.75 2 9.00 10.25 3 10.00 9.50 4 12.00 11.00 5 14.40 13.20
-
- g The common stock pays normal dividends at the end of each quarter of 12.5 cents per share ($50,000 for the employee stock ownership plan's shares each year). Accordingly, in this Case, the average fair value of shares is used to determine the number of shares used to satisfy the employers' obligation to replace dividends on allocated shares used for debt service.
- h Principal and interest are payable in equal annual installments at the end of each year. Debt service is as follows.
-
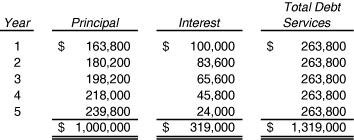 Year Principal Interest Total Debt Services 1 " $163,800 " " $100,000 " " $263,800 " 2 " 180,200 " " 83,600 " " 263,800 " 3 " 198,200 " " 65,600 " " 263,800 " 4 " 218,000 " " 45,800 " " 263,800 " 5 " 239,800 " " 24,000 " " 263,800 " " $1,000,000 " " $319,000 " " $1,319,000 "
-
- i The number of shares released each year is as follows.
-
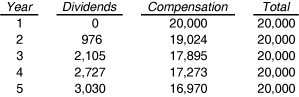 Year Dividends Compensation Total 1 0 "20,000" "20,000" 2 976 "19,024" "20,000" 3 "2,105" "17,895" "20,000" 4 "2,727" "17,273" "20,000" 5 "3,030" "16,970" "20,000"
-
- j The number of shares released for dividends is determined by dividing the amount of dividends on allocated shares by the average fair value of a share of common stock (for Year 2: $10,000 divided by $10.25 equals 976 shares). In this illustration, the remaining shares are released for compensation (for Year 2: 20,000 less 976 equals 19,024 shares).
- k Shares are released from the suspense account for allocation to participants' accounts based on a principal-plus-interest formula. The released shares are allocated to participant accounts the following year. Shares released and allocated follow.
-
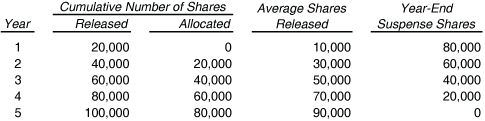 Cumulative Number of Shares Average Shares Released Year-End Suspense Shares Year Released Allocated 1 " 20,000" 0 "10,000 " "80,000 " 2 " 40,000" "20,000 " "30,000 " "60,000 " 3 " 60,000" "40,000 " "50,000 " "40,000 " 4 " 80,000" "60,000 " "70,000 " "20,000 " 5 "100,000 " "80,000 " "90,000 " 0
-
- l Income before employee stock ownership plan related charges is as follows.
-
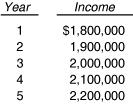 Year Income 1 " $1,800,000 " 2 " 1,900,000 " 3 " 2,000,000 " 4 " 2,100,000 " 5 " 2,200,000 "
-
- m All interest cost and compensation cost are charged to expense each year.
- n Excluding employee stock ownership plan shares, 1,000,000 shares are outstanding on average each year.
- o Entity A follows the guidance in Subtopic 740-10.
- p Entity A's combined statutory tax rate is 40 percent each year.
- q Entity A's only book-tax differences are those associated with its employee stock ownership plan.
- r No valuation allowance is necessary for deferred tax assets.
-
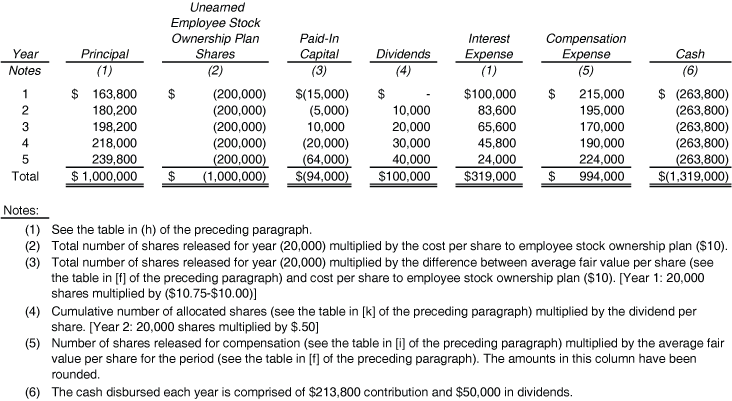 Year Principal Unearned Employee Stock Ownership Plan Shares Paid-In Capital Dividends Interest Expense Compensation Expense Cash Notes (1) (2) (3) (4) (1) (5) (6) 1 " $163,800 " " $(200,000)" " $(15,000)" $- " $100,000 " " $215,000 " " $(263,800)" 2 " 180,200 " " (200,000)" " (5,000)" " 10,000 " " 83,600 " " 195,000 " " (263,800)" 3 " 198,200 " " (200,000)" " 10,000 " " 20,000 " " 65,600 " " 170,000 " " (263,800)" 4 " 218,000 " " (200,000)" " (20,000)" " 30,000 " " 45,800 " " 190,000 " " (263,800)" 5 " 239,800 " " (200,000)" " (64,000)" " 40,000 " " 24,000 " " 224,000 " " (263,800)" Total " $1,000,000 " " $(1,000,000)" " $(94,000)" " $100,000 " " $319,000 " " $994,000 " " $(1,319,000)" Notes: (1) See the table in (h) of the preceding paragraph. (2) "Total number of shares released for year (20,000) multiplied by the cost per share to employee stock ownership plan ($10)." (3) "Total number of shares released for year (20,000) multiplied by the difference between average fair value per share (see the table in [f] of the preceding paragraph) and cost per share to employee stock ownership plan ($10). [Year 1: 20,000 shares multiplied by ($10.75-$10.00)]" (4) "Cumulative number of allocated shares (see the table in [k] of the preceding paragraph) multiplied by the dividend per share. [Year 2: 20,000 shares multiplied by $.50]" (5) Number of shares released for compensation (see the table in [i] of the preceding paragraph) multiplied by the average fair value per share for the period (see the table in [f] of the preceding paragraph). The amounts in this column have been rounded. (6) "The cash disbursed each year is comprised of $213,800 contribution and $50,000 in dividends."
-
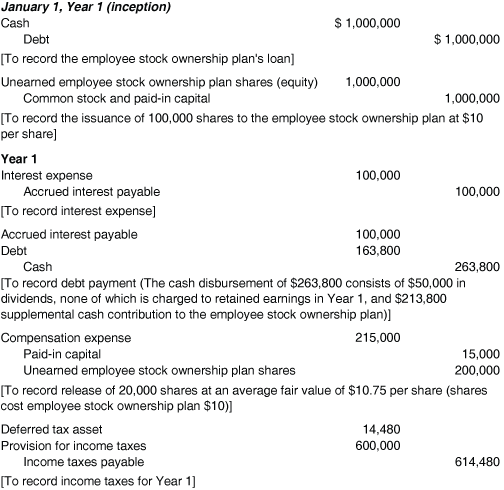 "January 1, Year 1 (inception)" Cash " $1,000,000 " Debt " $1,000,000 " [To record the employee stock ownership plan's loan] Unearned employee stock ownership plan shares (equity) " 1,000,000 " Common stock and paid-in capital " 1,000,000 " "[To record the issuance of 100,000 shares to the employee stock ownership plan at $10 per share]" Year 1 Interest expense " 100,000 " Accrued interest payable " 100,000 " [To record interest expense] Accrued interest payable " 100,000 " Debt " 163,800 " Cash " 263,800 " "[To record debt payment (The cash disbursement of $263,800 consists of $50,000 in dividends, none of which is charged to retained earnings in Year 1, and $213,800 supplemental cash contribution to the employee stock ownership plan)]" Compensation expense " 215,000 " Paid-in capital " 15,000 " Unearned employee stock ownership plan shares " 200,000 " "[To record release of 20,000 shares at an average fair value of $10.75 per share (shares cost employee stock ownership plan $10)]" Deferred tax asset " 14,480 " Provision for income taxes " 600,000 " Income taxes payable " 614,480 " [To record income taxes for Year 1]
-
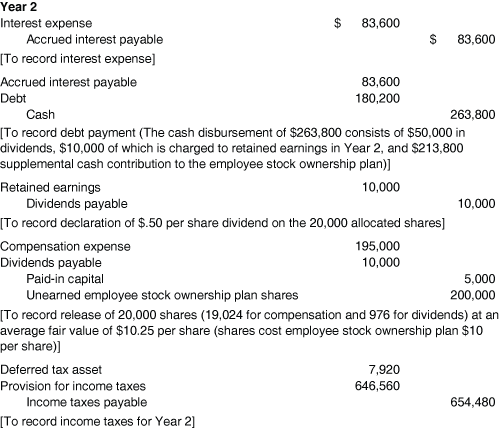 Year 2 Interest expense " $83,600 " Accrued interest payable " $83,600 " [To record interest expense] Accrued interest payable " 83,600 " Debt " 180,200 " Cash " 263,800 " "[To record debt payment (The cash disbursement of $263,800 consists of $50,000 in dividends, $10,000 of which is charged to retained earnings in Year 2, and $213,800 supplemental cash contribution to the employee stock ownership plan)]" Retained earnings " 10,000 " Dividends payable " 10,000 " "[To record declaration of $.50 per share dividend on the 20,000 allocated shares]" Compensation expense " 195,000 " Dividends payable " 10,000 " Paid-in capital " 5,000 " Unearned employee stock ownership plan shares " 200,000 " "[To record release of 20,000 shares (19,024 for compensation and 976 for dividends) at an average fair value of $10.25 per share (shares cost employee stock ownership plan $10 per share)]" Deferred tax asset " 7,920 " Provision for income taxes " 646,560 " Income taxes payable " 654,480 " [To record income taxes for Year 2]
-
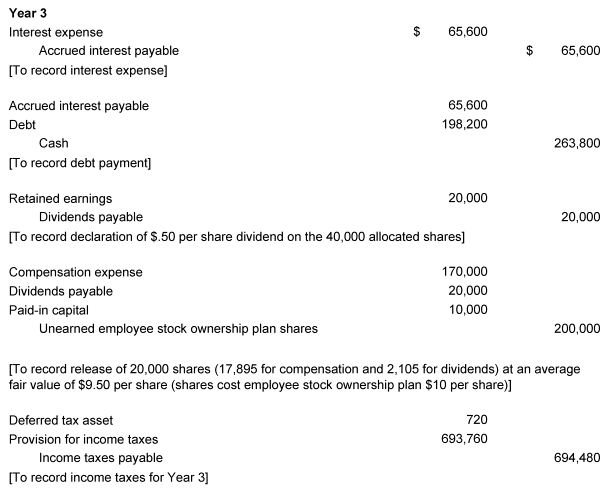 Year 3 Interest expense " $65,600 " Accrued interest payable " $65,600 " [To record interest expense] Accrued interest payable " 65,600 " Debt " 198,200 " Cash " 263,800 " [To record debt payment] Retained earnings " 20,000 " Dividends payable " 20,000 " "[To record declaration of $.50 per share dividend on the 40,000 allocated shares]" Compensation expense " 170,000 " Dividends payable " 20,000 " Paid-in capital " 10,000 " Unearned employee stock ownership plan shares " 200,000 " "[To record release of 20,000 shares (17,895 for compensation and 2,105 for dividends) at an average fair value of $9.50 per share (shares cost employee stock ownership plan $10 per share)]" Deferred tax asset 720 Provision for income taxes " 697,760 " Paid-in capital " 4,000 " Income taxes payable " 694,480 " [To record income taxes for Year 3]
-
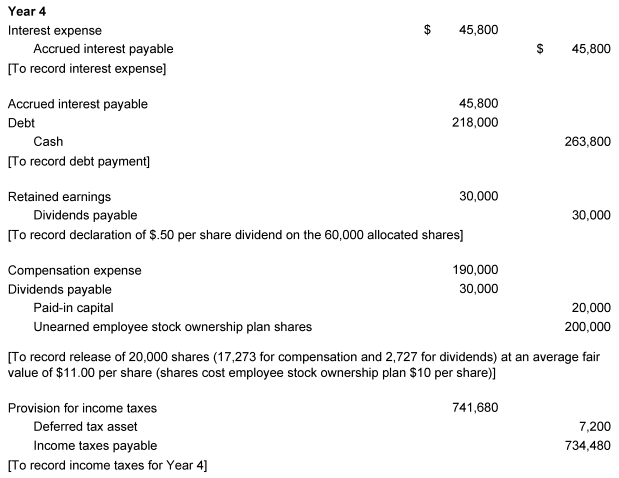 Year 4 Interest expense " $45,800 " Accrued interest payable " $45,800 " [To record interest expense] Accrued interest payable " 45,800 " Debt " 218,000 " Cash " 263,800 " [To record debt payment] Retained earnings " 30,000 " Dividends payable " 30,000 " "[To record declaration of $.50 per share dividend on the 60,000 allocated shares]" Compensation expense " 190,000 " Dividends payable " 30,000 " Paid-in capital " 20,000 " Unearned employee stock ownership plan shares " 200,000 " "[To record release of 20,000 shares (17,273 for compensation and 2,727 for dividends) at an average fair value of $11.00 per share (shares cost employee stock ownership plan $10 per share)]" Provision for income taxes " 737,680 " Paid-in capital " 4,000 " Deferred tax asset " 7,200 " Income taxes payable " 734,480 " [To record income taxes for Year 4]
-
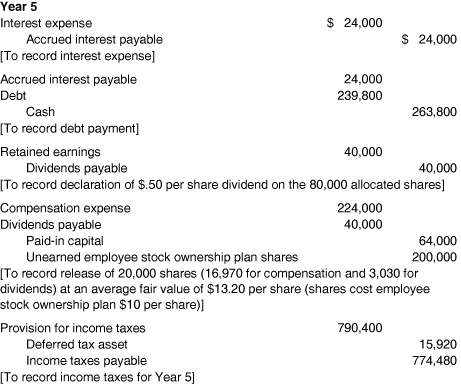 Year 5 Interest expense " $24,000 " Accrued interest payable " $24,000 " [To record interest expense] Accrued interest payable " 24,000 " Debt " 239,800 " Cash " 263,800 " [To record debt payment] Retained earnings " 40,000 " Dividends payable " 40,000 " "[To record declaration of $.50 per share dividend on the 80,000 allocated shares]" Compensation expense " 224,000 " Dividends payable " 40,000 " Paid-in capital " 64,000 " Unearned employee stock ownership plan shares " 200,000 " "[To record release of 20,000 shares (16,970 for compensation and 3,030 for dividends) at an average fair value of $13.20 per share (shares cost employee stock ownership plan $10 per share)]" Provision for income taxes " 790,400 " Deferred tax asset " 15,920 " Income taxes payable " 774,480 " [To record income taxes for Year 5]
-
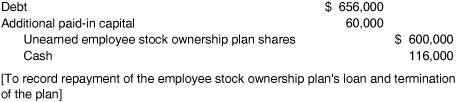 Debt " $656,000 " Additional paid-in capital " 60,000 " Unearned employee stock ownership plan shares " $600,000 " Cash " 116,000 " [To record repayment of the employee stock ownership plan's loan and termination of the plan]
-
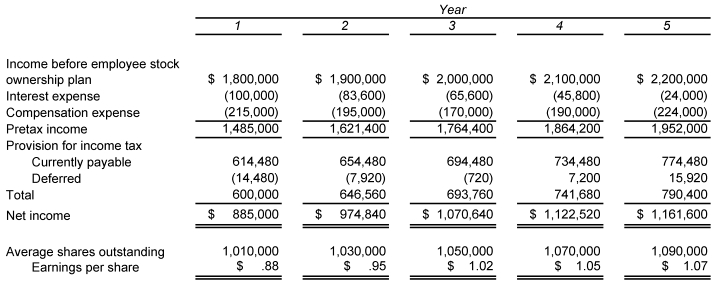 Year 1 2 3 4 5 Income before employee stock ownership plan " $1,800,000 " " $1,900,000 " " $2,000,000 " " $2,100,000 " " $2,200,000 " Interest expense " (100,000)" " (83,600)" " (65,600)" " (45,800)" " (24,000)" Compensation expense " (215,000)" " (195,000)" " (170,000)" " (190,000)" " (224,000)" Pretax income " 1,485,000 " " 1,621,400 " " 1,764,400 " " 1,864,200 " " 1,952,000 " Provision for income tax Currently payable " 614,480 " " 654,480 " " 694,480 " " 734,480 " " 774,480 " Deferred " (14,480)" " (7,920)" (720) " 7,200 " " 15,920 " Total " 600,000 " " 646,560 " " 693,760 " " 741,680 " " 790,400 " Net income " $885,000 " " $974,840 " " $1,070,640 " " $1,122,520 " " $1,161,600 " Average shares outstanding " 1,010,000 " " 1,030,000 " " 1,050,000 " " 1,070,000 " " 1,090,000 " Earnings per share $.88 $.95 $1.02 $1.05 $1.07
-
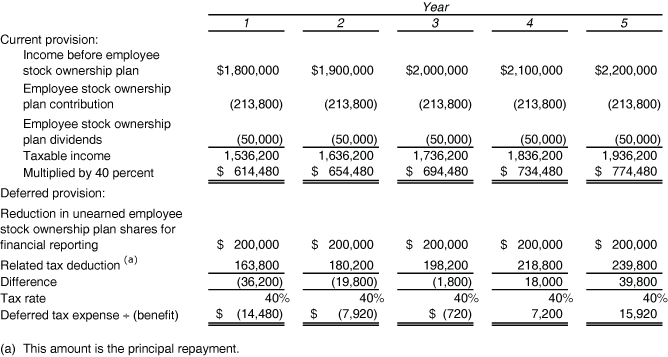 Year 1 2 3 4 5 Current provision: Income before employee stock ownership plan " $1,800,000 " " $1,900,000 " " $2,000,000 " " $2,100,000 " " $2,200,000 " Employee stock ownership plan contribution " (213,800)" " (213,800)" " (213,800)" " (213,800)" " (213,800)" Employee stock ownership plan dividends " (50,000)" " (50,000)" " (50,000)" " (50,000)" " (50,000)" Taxable income " 1,536,200 " " 1,636,200 " " 1,736,200 " " 1,836,200 " " 1,936,200 " Multiplied by 40 percent " $614,480 " " $654,480 " " $694,480 " " $734,480 " " $774,480 " Deferred provision: Reduction in unearned employee stock ownership plan shares for financial reporting " $200,000 " " $200,000 " " $200,000 " " $200,000 " " $200,000 " Related tax deduction (a) " 163,800 " " 180,200 " " 198,200 " " 218,800 " " 239,800 " Difference " (36,200)" " (19,800)" " (1,800)" " 18,000 " " 39,800 " Tax rate 40% 40% 40% 40% 40% Deferred tax expense ÷ (benefit) " $(14,480)" " $(7,920)" $ (720) " 7,200 " " 15,920 " (a) This amount is the principal repayment.
-
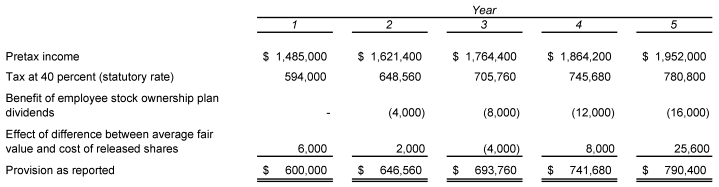 Year 1 2 3 4 5 Pretax income " $1,485,000 " " $1,621,400 " " $1,764,400 " " $1,864,200 " " $1,952,000 " Tax at 40 percent (statutory rate) " 594,000 " " 648,560 " " 705,760 " " 745,680 " " 780,800 " Benefit of employee stock ownership plan dividends - " (4,000)" " (8,000)" " (12,000)" " (16,000)" Effect of difference between average fair value and cost of released shares " 6,000 " " 2,000 " - " 4,000 " " 25,600 " Provision as reported " $600,000 " " $646,560 " " $693,760 " " $741,680 " " $790,400 "
- The entity sponsors a leveraged employee stock ownership plan that covers all U.S. employees who work 20 or more hours per week. The entity makes annual contributions to the employee stock ownership plan equal to the employee stock ownership plan's debt service less dividends received by the employee stock ownership plan. All dividends received by the employee stock ownership plan are used to pay debt service. The employee stock ownership plan shares initially were pledged as collateral for its debt. As the debt is repaid, shares are released from collateral and allocated to active employees, based on the proportion of debt service paid in the year. The entity accounts for its employee stock ownership plan in accordance with this Subtopic. Accordingly, the debt of the employee stock ownership plan is recorded as debt and the shares pledged as collateral are reported as unearned employee stock ownership plan shares in the statement of financial position. As shares are released from collateral, the entity reports compensation expense equal to the current market price of the shares, and the shares become outstanding for EPS computations. Dividends on allocated employee stock ownership plan shares are recorded as a reduction of retained earnings; dividends on unallocated employee stock ownership plan shares are recorded as a reduction of debt and accrued interest. Employee stock ownership plan compensation expense was $170,000, $195,000, and $215,000 for Years 3, 2, and 1, respectively. The employee stock ownership plan shares as of December 31 were as follows.
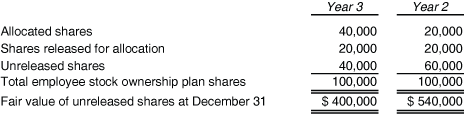 Year 3 Year 2 Allocated shares "40,000 " "20,000 " Shares released for allocation "20,000 " "20,000 " Unreleased shares "40,000 " "60,000 " Total employee stock ownership plan shares "100,000 " "100,000 " Fair value of unreleased shares at December 31 " $400,000 " " $540,000 "
- a Entity B loaned its employee stock ownership plan $1,000,000 and concurrently obtained a related loan. The terms of both lending arrangements are the same as for Case A's outside loan.
- b Entity B uses shares released by the employee stock ownership plan to satisfy its matching obligation of 50 percent of voluntary employee contributions to the savings plan. The average fair value of the shares for each year is used to determine the number of shares necessary to satisfy the matching obligation.
- c If the fair value of the shares released is less than Entity B's matching obligation, Entity B contributes additional newly issued shares to the employee stock ownership plan to satisfy the remaining obligation.
- d Shares used to replace dividends on allocated shares used to service debt do not count toward the employer's match.
- e The employee contributions, required employer match, and the number of shares needed to fund the employee match follow.
-
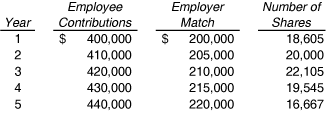 Year Employee Contributions Employer Match Number of Shares 1 " $400,000 " " $200,000 " "18,605" 2 " 410,000 " " 205,000 " "20,000" 3 " 420,000 " " 210,000 " "22,105" 4 " 430,000 " " 215,000 " "19,545" 5 " 440,000 " " 220,000 " "16,667"
Note that the number of shares needed to satisfy the employer's matching obligation is determined by dividing the matching obligation by the average fair value of a share of common stock (for Year 1: $200,000 divided by $10.75 [see above table for average fair values] equals 18,605 shares). -
-
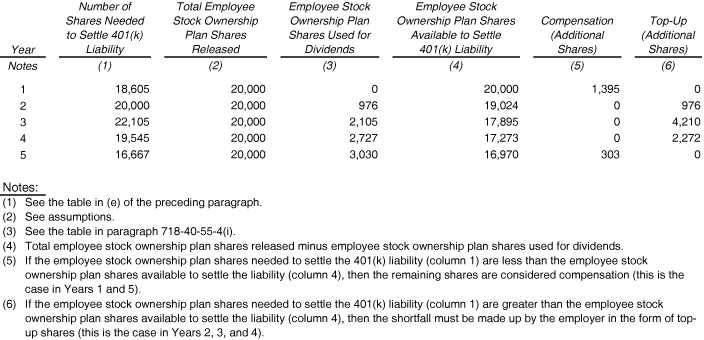 Year Number of Shares Needed to Settle 401(k) Liability Total Employee Stock Ownership Plan Shares Released Employee Stock Ownership Plan Shares Used for Dividends Employee Stock Ownership Plan Shares Available to Settle 401(k) Liability Compensation (Additional Shares) Top-Up (Additional Shares) Notes (1) (2) (3) (4) (5) (6) 1 "18,605 " "20,000 " 0 "20,000 " "1,395 " 0 2 "20,000 " "20,000 " 976 "19,024 " 0 976 3 "22,105 " "20,000 " "2,105 " "17,895 " 0 "4,210 " 4 "19,545 " "20,000 " "2,727 " "17,273 " 0 "2,272 " 5 "16,667 " "20,000 " "3,030 " "16,970 " 303 0 Notes: (1) See the table in (e) of the preceding paragraph. (2) See assumptions. (3) See the table in paragraph 718-40-55-4(i). (4) Total employee stock ownership plan shares released minus employee stock ownership plan shares used for dividends. (5) "If the employee stock ownership plan shares needed to settle the 401(k) liability (column 1) are less than the employee stock ownership plan shares available to settle the liability (column 4), then the remaining shares are considered compensation (this is the case in Years 1 and 5)." (6) "If the employee stock ownership plan shares needed to settle the 401(k) liability (column 1) are greater than the employee stock ownership plan shares available to settle the liability (column 4), then the shortfall must be made up by the employer in the form of top-up shares (this is the case in Years 2, 3, and 4)."
-
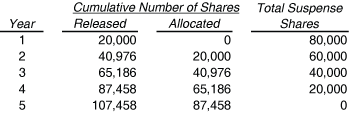 Year Cumulative Number of Shares Total Suspense Shares Released Allocated 1 " 20,000" 0 "80,000" 2 " 40,976" "20,000" "60,000" 3 " 65,186" "40,976" "40,000" 4 " 87,458" "65,186" "20,000" 5 "107,458" "87,458" 0
-
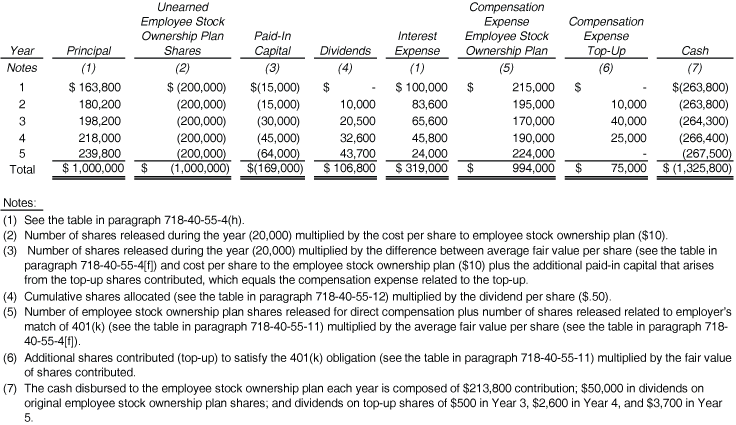 Year Principal Unearned Employee Stock Ownership Plan Shares Paid-In Capital Dividends Interest Expense Compensation Expense Employee Stock Ownership Plan "Compensation Expense Top-Up" Cash Notes (1) (2) (3) (4) (1) (5) (6) (7) 1 " $ 163,800 " " $ (200,000) " " $(15,000) " $- " $100,000 " " $215,000 " $- " $(263,800) " 2 " 180,200 " " (200,000) " " (15,000) " " 10,000 " " 83,600 " " 195,000 " " 10,000 " " (263,800) " 3 " 198,200 " " (200,000) " " (30,000) " " 20,500 " " 65,600 " " 170,000 " " 40,000 " " (264,300) " 4 " 218,000 " " (200,000) " " (45,000) " " 32,600 " " 45,800 " " 190,000 " " 25,000 " " (266,400) " 5 " 239,800 " " (200,000) " " (64,000) " " 43,700 " " 24,000 " " 224,000 " - " (267,500)" Total " $1,000,000 " " $(1,000,000)" " $(169,000)" " $106,800 " " $319,000 " " $994,000 " " $75,000 " " $(1,325,800)" Notes: (1) See the table in paragraph 718-40-55-4(h). (2) "Number of shares released during the year (20,000) multiplied by the cost per share to employee stock ownership plan ($10)." (3) " Number of shares released during the year (20,000) multiplied by the difference between average fair value per share (see the table in paragraph 718-40-55-4[f]) and cost per share to the employee stock ownership plan ($10) plus the additional paid-in capital that arises from the top-up shares contributed, which equals the compensation expense related to the top-up." (4) Cumulative shares allocated (see the table in paragraph 718-40-55-12) multiplied by the dividend per share ($.50). (5) Number of employee stock ownership plan shares released for direct compensation plus number of shares released related to employer's match of 401(k) (see the table in paragraph 718-40-55-11) multiplied by the average fair value per share (see the table in paragraph 718-40-55-4[f]). (6) Additional shares contributed (top-up) to satisfy the 401(k) obligation (see the table in paragraph 718-40-55-11) multiplied by the fair value of shares contributed. (7) "The cash disbursed to the employee stock ownership plan each year is composed of $213,800 contribution; $50,000 in dividends on original employee stock ownership plan shares; and dividends on top-up shares of $500 in Year 3, $2,600 in Year 4, and $3,700 in Year 5."
-
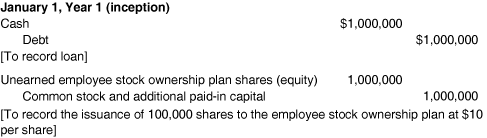 "January 1, Year 1 (inception)" Cash " $1,000,000 " Debt " $1,000,000 " [To record loan] Unearned employee stock ownership plan shares (equity) " 1,000,000 " Common stock and additional paid-in capital " 1,000,000 " "[To record the issuance of 100,000 shares to the employee stock ownership plan at $10 per share]"
-
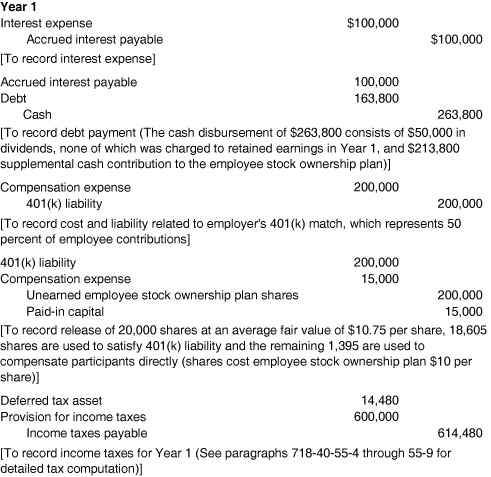 Year 1 Interest expense " $100,000 " Accrued interest payable " $100,000 " [To record interest expense] Accrued interest payable " 100,000 " Debt " 163,800 " Cash " 263,800 " "[To record debt payment (The cash disbursement of $263,800 consists of $50,000 in dividends, none of which was charged to retained earnings in Year 1, and $213,800 supplemental cash contribution to the employee stock ownership plan)]" Compensation expense " 200,000 " 401(k) liability " 200,000 " "[To record cost and liability related to employer's 401(k) match, which represents 50 percent of employee contributions]" 401(k) liability " 200,000 " Compensation expense " 15,000 " Unearned employee stock ownership plan shares " 200,000 " Paid-in capital " 15,000 " "[To record release of 20,000 shares at an average fair value of $10.75 per share, 18,605 shares are used to satisfy 401(k) liability and the remaining 1,395 are used to compensate participants directly (shares cost employee stock ownership plan $10 per share)]" Deferred tax asset " 14,480 " Provision for income taxes " 600,000 " Income taxes payable " 614,480 " [To record income taxes for Year 1 (See paragraphs 718-40-55-4 through 55-9 for detailed tax computation)]
-
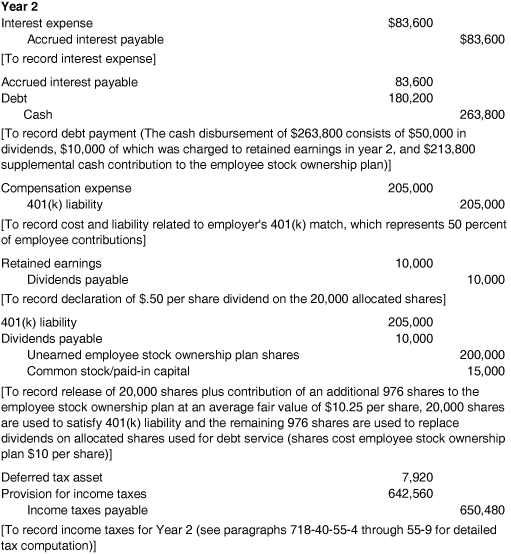 Year 2 Interest expense " $83,600 " Accrued interest payable " $83,600 " [To record interest expense] Accrued interest payable " 83,600 " Debt " 180,200 " Cash " 263,800 " "[To record debt payment (The cash disbursement of $263,800 consists of $50,000 in dividends, $10,000 of which was charged to retained earnings in year 2, and $213,800 supplemental cash contribution to the employee stock ownership plan)]" Compensation expense " 205,000 " 401(k) liability " 205,000 " "[To record cost and liability related to employer's 401(k) match, which represents 50 percent of employee contributions]" Retained earnings " 10,000 " Dividends payable " 10,000 " "[To record declaration of $.50 per share dividend on the 20,000 allocated shares]" 401(k) liability " 205,000 " Dividends payable " 10,000 " Unearned employee stock ownership plan shares " 200,000 " Common stock/paid-in capital " 15,000 " "[To record release of 20,000 shares plus contribution of an additional 976 shares to the employee stock ownership plan at an average fair value of $10.25 per share, 20,000 shares are used to satisfy 401(k) liability and the remaining 976 shares are used to replace dividends on allocated shares used for debt service (shares cost employee stock ownership plan $10 per share)]" Deferred tax asset " 7,920 " Provision for income taxes " 642,560 " Income taxes payable " 650,480 " [To record income taxes for Year 2 (see paragraphs 718-40-55-4 through 55-9 for detailed tax computation)]
-
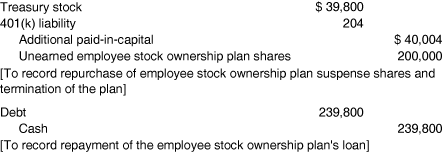 Treasury stock " $39,800 " 401(k) liability 204 Additional paid-in-capital " $40,004 " Unearned employee stock ownership plan shares " 200,000 " [To record repurchase of employee stock ownership plan suspense shares and termination of the plan] Debt " 239,800 " Cash " 239,800 " [To record repayment of the employee stock ownership plan's loan]
-
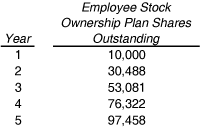 Year Employee Stock Ownership Plan Shares Outstanding 1 "10,000" 2 "30,488" 3 "53,081" 4 "76,322" 5 "97,458"
- The entity sponsors a 401(k) savings plan under which eligible U.S. employees may choose to save up to 6 percent of salary income on a pretax basis, subject to certain Internal Revenue Service (IRS) limits. The entity matches 50 percent of employee contributions with entity common stock. The shares for this purpose are provided principally by the entity's employee stock ownership plan, supplemented as needed by newly issued shares. The entity makes annual contributions to the employee stock ownership plan equal to the employee stock ownership plan's debt service less dividends received by the employee stock ownership plan. All dividends received by the employee stock ownership plan are used to pay debt service. The employee stock ownership plan shares initially were pledged as collateral for its debt. As the debt is repaid, shares are released from collateral and allocated to employees who made 401(k) contributions that year, based on the proportion of debt service paid in the year. The entity accounts for its employee stock ownership plan in accordance with this Subtopic. Accordingly, the shares pledged as collateral are reported as unearned employee stock ownership plan shares in the statement of financial position. As shares are released from collateral, the entity reports compensation expense equal to the current market price of the shares, and the shares become outstanding for EPS computations. Dividends on allocated employee stock ownership plan shares are recorded as a reduction of retained earnings; dividends on unallocated employee stock ownership plan shares are recorded as a reduction of debt and accrued interest.
- Compensation expense for the 401(k) match and the employee stock ownership plan was $210,000, $205,000, and $215,000 for Years 3, 2, and 1, respectively. The employee stock ownership plan shares as of December 31 were as follows.
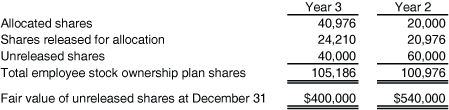 Year 3 Year 2 Allocated shares "40,976" "20,000" Shares released for allocation "24,210" "20,976" Unreleased shares " 40,000" " 60,000" Total employee stock ownership plan shares " 105,186" " 100,976" Fair value of unreleased shares at December 31 " $400,000 " " $540,000 "
- a The borrowing, debt service, earnings, and tax assumptions are the same as those for Entity A outlined in Case A.
- b On January 1, Year 1, the employee stock ownership plan used the proceeds of the debt to buy 80,000 shares of newly issued convertible preferred stock of Entity D for $12.50 per share.
- c The preferred stock pays dividends quarterly at an annual rate of $1.25 per share ($100,000 each year for the employee stock ownership plan shares). Accordingly, in this Case the average fair value of the shares is used to determine the number of shares used to satisfy the employer's obligation to replace dividends on allocated shares used for debt service.
- d All dividends on employee stock ownership plan shares are used for debt service.
- e The preferred stock is convertible into common stock at 1:1 ratio.
- f Participants may not withdraw the convertible preferred stock from the employee stock ownership plan. When participants become eligible to withdraw shares from their account, they must either convert to common stock or redeem the preferred shares.
- g The preferred stock has a guaranteed minimum redemption value of $12.50 per share, to be paid in shares of common stock.
- h The preferred stock is callable at $13.00 per share.
- i There is one vote per preferred share.
- j The year-end and average fair values of a share of preferred stock (fair value is assumed to be greater than or equal to minimum value) follow.
-
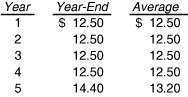 Year Year-End Average 1 $12.50 $12.50 2 12.50 12.50 3 12.50 12.50 4 12.50 12.50 5 14.40 13.20
-
-
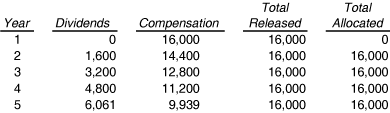 Year Dividends Compensation Total Released Total Allocated 1 0 "16,000" "16,000" 0 2 "1,600" "14,400" "16,000" "16,000" 3 "3,200" "12,800" "16,000" "16,000" 4 "4,800" "11,200" "16,000" "16,000" 5 "6,061" " 9,939" "16,000" "16,000"
-
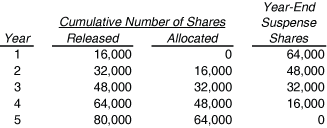 Cumulative Number of Shares Year-End Suspense Shares Year Released Allocated 1 "16,000" 0 "64,000" 2 "32,000" "16,000" "48,000" 3 "48,000" "32,000" "32,000" 4 "64,000" "48,000" "16,000" 5 "80,000" "64,000" 0
-
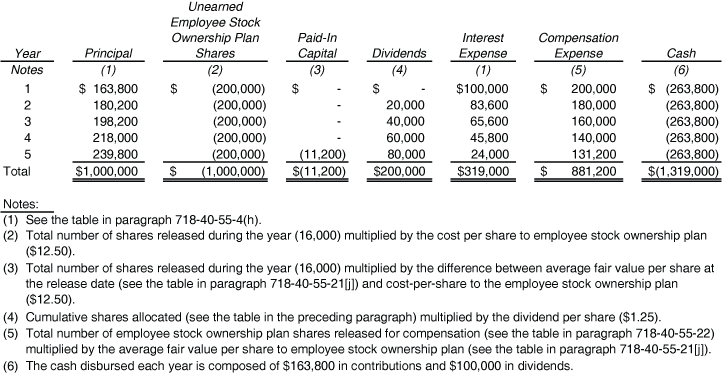 Year Principal Unearned Employee Stock Ownership Plan Shares Paid-In Capital Dividends Interest Expense Compensation Expense Cash Notes (1) (2) (3) (4) (1) (5) (6) 1 " $163,800 " " $(200,000)" $- $- " $100,000 " " $200,000 " " $(263,800)" 2 " 180,200 " " (200,000)" - " 20,000 " " 83,600 " " 180,000 " " (263,800)" 3 " 198,200 " " (200,000)" - " 40,000 " " 65,600 " " 160,000 " " (263,800)" 4 " 218,000 " " (200,000)" - " 60,000 " " 45,800 " " 140,000 " " (263,800)" 5 " 239,800 " " (200,000)" " (11,200)" " 80,000 " " 24,000 " " 131,200 " " (263,800)" Total "$1,000,000 " " $(1,000,000)" " $(11,200)" " $200,000 " " $319,000 " " $881,200 " " $(1,319,000)" Notes: (1) See the table in paragraph 718-40-55-4(h). (2) "Total number of shares released during the year (16,000) multiplied by the cost per share to employee stock ownership plan ($12.50)." (3) "Total number of shares released during the year (16,000) multiplied by the difference between average fair value per share at the release date (see the table in paragraph 718-40-55-21[j]) and cost-per-share to the employee stock ownership plan ($12.50)." (4) Cumulative shares allocated (see the table in the preceding paragraph) multiplied by the dividend per share ($1.25). (5) Total number of employee stock ownership plan shares released for compensation (see the table in paragraph 718-40-55-22) multiplied by the average fair value per share to employee stock ownership plan (see the table in paragraph 718-40-55-21[j]). (6) "The cash disbursed each year is composed of $163,800 in contributions and $100,000 in dividends."
-
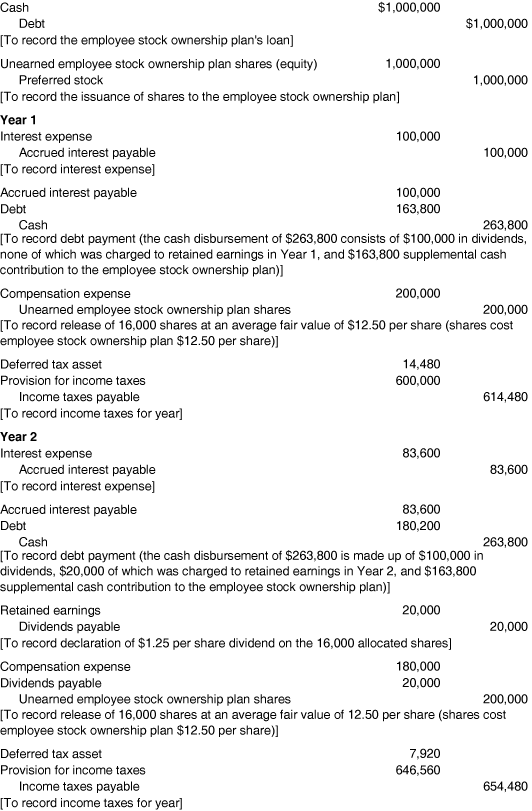 Cash " $1,000,000 " Debt " $1,000,000 " [To record the employee stock ownership plan's loan] Unearned employee stock ownership plan shares (equity) " 1,000,000 " Preferred stock " 1,000,000 " [To record the issuance of shares to the employee stock ownership plan] Year 1 Interest expense " 100,000 " Accrued interest payable " 100,000 " [To record interest expense] Accrued interest payable " 100,000 " Debt " 163,800 " Cash " 263,800 " "[To record debt payment (the cash disbursement of $263,800 consists of $100,000 in dividends, none of which was charged to retained earnings in Year 1, and $163,800 supplemental cash contribution to the employee stock ownership plan)]" Compensation expense " 200,000 " Unearned employee stock ownership plan shares " 200,000 " "[To record release of 16,000 shares at an average fair value of $12.50 per share (shares cost employee stock ownership plan $12.50 per share)]" Deferred tax asset " 14,480 " Provision for income taxes " 600,000 " Income taxes payable " 614,480 " [To record income taxes for year] Year 2 Interest expense " 83,600 " Accrued interest payable " 83,600 " [To record interest expense] Accrued interest payable " 83,600 " Debt " 180,200 " Cash " 263,800 " "[To record debt payment (the cash disbursement of $263,800 is made up of $100,000 in dividends, $20,000 of which was charged to retained earnings in Year 2, and $163,800 supplemental cash contribution to the employee stock ownership plan)]" Retained earnings " 20,000 " Dividends payable " 20,000 " "[To record declaration of $1.25 per share dividend on the 16,000 allocated shares]" Compensation expense " 180,000 " Dividends payable " 20,000 " Unearned employee stock ownership plan shares " 200,000 " "[To record release of 16,000 shares at an average fair value of 12.50 per share (shares cost employee stock ownership plan $12.50 per share)]" Deferred tax asset " 7,920 " Provision for income taxes " 646,560 " Income taxes payable " 654,480 " [To record income taxes for year]
-
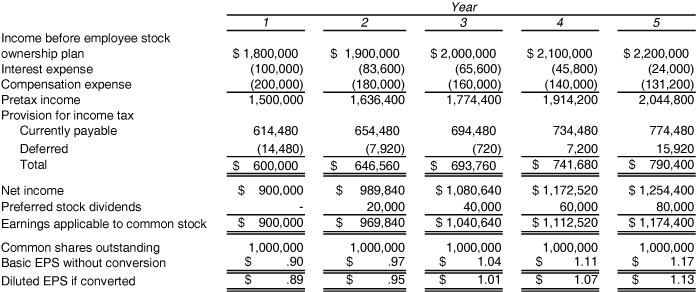 Year 1 2 3 4 5 Income before employee stock ownership plan " $1,800,000 " " $1,900,000 " " $2,000,000 " " $2,100,000 " " $2,200,000 " Interest expense " (100,000)" " (83,600)" " (65,600)" " (45,800)" " (24,000)" Compensation expense " (200,000)" " (180,000)" " (160,000)" " (140,000)" " (131,200)" Pretax income " 1,500,000 " " 1,636,400 " " 1,774,400 " " 1,914,200 " " 2,044,800 " Provision for income tax Currently payable " 614,480 " " 654,480 " " 694,480 " " 734,480 " " 774,480 " Deferred " (14,480) " " (7,920) " (720) " 7,200 " " 15,920 " Total " $600,000 " " $646,560 " " $693,760 " " $741,680 " " $790,400 " Net income " $900,000 " " $989,840 " " $1,080,640 " " $1,172,520 " " $1,254,400 " Preferred stock dividends - " 20,000 " " 40,000 " " 60,000 " " 80,000 " Earnings applicable to common stock " $900,000 " " $969,840 " " $1,040,640 " " $1,112,520 " " $1,174,400 " Common shares outstanding " 1,000,000 " " 1,000,000 " " 1,000,000 " " 1,000,000 " " 1,000,000 " Basic EPS without conversion $ .90 $ .97 $ 1.04 $ 1.11 $ 1.17 Diluted EPS if converted $ .89 $ .95 $ 1.01 $ 1.07 $ 1.13
-
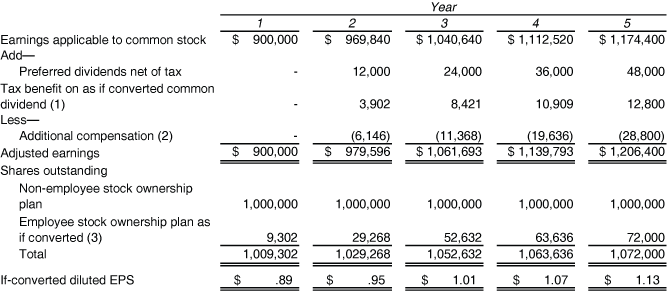 Year 1 2 3 4 5 Earnings applicable to common stock " $900,000 " " $969,840 " " $1,040,640 " " $1,112,520 " " $1,174,400 " Add— Preferred dividends net of tax - " 12,000 " " 24,000 " " 36,000 " " 48,000 " Tax benefit on as if converted common dividend (1) - " 3,902 " " 8,421 " " 10,909 " " 12,800 " Less— Additional compensation (2) - " (6,146) " " (11,368) " " (19,636) " " (28,800) " Adjusted earnings " $900,000 " " $979,596 " " $1,061,693 " " $1,139,793 " " $1,206,400 " Shares outstanding Non-employee stock ownership plan " 1,000,000 " " 1,000,000 " " 1,000,000 " " 1,000,000 " " 1,000,000 " Employee stock ownership plan as if converted (3) " 9,302 " " 29,268 " " 52,632 " " 63,636 " " 72,000 " Total " 1,009,302 " " 1,029,268 " " 1,052,632 " " 1,063,636 " " 1,072,000 " If-converted diluted EPS $ .89 $ .95 $ 1.01 $ 1.07 $ 1.13
-
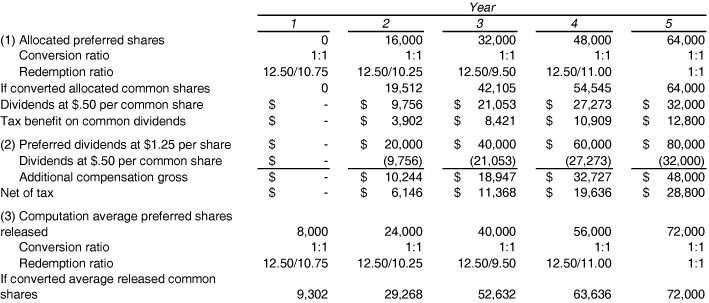 Year 1 2 3 4 5 (1) Allocated preferred shares 0 "16,000" "32,000" "48,000" "64,000" Conversion ratio 1:1 1:1 1:1 1:1 1:1 Redemption ratio 12.50/10.75 12.50/10.25 12.50/9.50 12.50/11.00 1:1 If converted allocated common shares 0 "19,512" "42,105" "54,545" "64,000" Dividends at $.50 per common share $- " $9,756 " " $21,053 " " $27,273 " " $32,000 " Tax benefit on common dividends $- " $3,902 " " $8,421 " " $10,909 " " $12,800 " (2) Preferred dividends at $1.25 per share $- " $20,000 " " $40,000 " " $60,000 " " $80,000 " Dividends at $.50 per common share $- " (9,756) " " (21,053)" " (27,273) " " (32,000) " Additional compensation gross $- " $10,244 " " $18,947 " " $32,727 " " $48,000 " Net of tax $- " $6,146 " " $11,368 " " $19,636 " " $28,800 " (3) Computation average preferred shares released "8,000" "24,000" "40,000" "56,000" "72,000" Conversion ratio 1:1 1:1 1:1 1:1 1:1 Redemption ratio 12.50/10.75 12.50/10.25 12.50/9.50 12.50/11.00 1:1 If converted average released common shares "9,302" "29,268" "52,632" "63,636" "72,000"
-
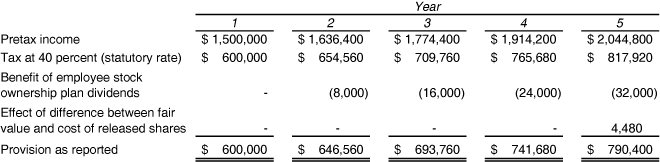 Year 1 2 3 4 5 Pretax income " $1,500,000 " " $1,636,400 " " $1,774,400 " " $1,914,200 " " $2,044,800 " Tax at 40 percent (statutory rate) " $600,000 " " $654,560 " " $709,760 " " $765,680 " " $817,920 " Benefit of employee stock ownership plan dividends - " (8,000)" " (16,000)" " (24,000)" " (32,000)" Effect of difference between fair value and cost of released shares - - - - " 4,480 " Provision as reported " $600,000 " " $646,560 " " $693,760 " " $741,680 " " $790,400 "
- a On January 1, Year 1, Entity E established a leveraged employee stock ownership plan with convertible preferred stock.
- b The employee stock ownership plan borrowed $1,000,000 from the employer at 10 percent for 5 years and used the proceeds to buy 80,000 shares of newly issued convertible preferred stock of Entity E for $12.50 per share.
- c Debt service is funded by cash contributions and dividends on employer stock held by the employee stock ownership plan.
- d Dividends on all of the original 80,000 shares held by the employee stock ownership plan are used for debt service.
- e Cash contributions are made at the end of each year.
- f The preferred stock pays dividends quarterly at an annual rate of $1.25 per share ($100,000 each year for the employee stock ownership plan's shares). Accordingly, in this Example, the average fair value of the shares is used to determine the number of shares used to satisfy the employer's obligation to replace dividends on allocated shares used for debt service.
- g The preferred stock is convertible at a 1:1 ratio into common stock.
- h Participants may not withdraw the convertible preferred stock from the employee stock ownership plan. When participants become eligible to withdraw shares from their account, they must either convert to common stock or redeem the preferred shares.
- i The preferred stock has a guaranteed minimum redemption value of $12.50 per share, to be paid in shares of common stock.
- j The preferred stock is callable at $13.00 per share.
- k There is one vote per preferred share.
- l The year-end and average fair values of a share of preferred stock (fair value is assumed to be greater than or equal to minimum value) follow.
-
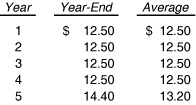 Year Year-End Average 1 $12.50 $12.50 2 12.50 12.50 3 12.50 12.50 4 12.50 12.50 5 14.40 13.20
-
- m Entity E uses shares released by the employee stock ownership plan to satisfy its matching obligation of 50 percent of voluntary employee contributions to the savings plan. The fair value of the shares at the end of each month is used to determine the number of shares necessary to satisfy the matching obligation. (Accordingly, in this Example, average fair values are used to determine the number of shares needed to satisfy the employer's liabilities.)
- n If the fair value of the shares released is less than Entity E's matching obligation, Entity E contributes additional newly issued shares (top-up shares) to the employee stock ownership plan to satisfy the remaining obligation. The top-up shares are issued at the end of the year. Dividends on the top-up shares are paid in cash.
- o Shares that replace dividends on allocated shares used to service debt do not count toward the employer's match.
- p The employee contributions, required employer match, and the number of shares needed to fund the employee match follow.
-
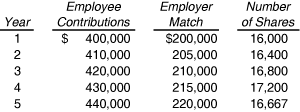 Year Employee Contributions Employer Match Number of Shares 1 " $400,000 " " $200,000 " "16,000" 2 " 410,000 " " 205,000 " "16,400" 3 " 420,000 " " 210,000 " "16,800" 4 " 430,000 " " 215,000 " "17,200" 5 " 440,000 " " 220,000 " "16,667"
Note that the number of shares needed to satisfy the employer's matching obligation is determined by dividing the matching obligation by the average fair value of a share of common stock (for Year 1: $200,000 divided by $12.50 equals 16,000 shares). -
- q Principal and interest are payable in annual installments at the end of each year. Debt service is as follows.
-
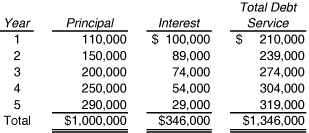 Year Principal Interest Total Debt Service 1 " $ 110,000 " " $ 100,000 " " $ 210,000 " 2 " 150,000 " " 89,000 " " 239,000 " 3 " 200,000 " " 74,000 " " 274,000 " 4 " 250,000 " " 54,000 " " 304,000 " 5 " 290,000 " " 29,000 " " 319,000 " Total " $1,000,000 " " $346,000 " " $1,346,000 "
-
- r Shares are released from the suspense account for allocation to participants' accounts based on a principal-plus-interest formula. The released shares are allocated to participants' accounts at the beginning of the following year. Shares are assumed to be released ratably throughout the year.
- s The shares released each year follow.
-
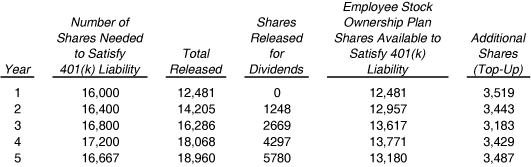 Year Number of Shares Needed to Satisfy 401(k) Liability Total Released Shares Released for Dividends Employee Stock Ownership Plan Shares Available to Satisfy 401(k) Liability Additional Shares (Top-Up) 1 "16,000" "12,481" 0 "12,481" "3,519" 2 "16,400" "14,205" 1248 "12,957" "3,443" 3 "16,800" "16,286" 2669 "13,617" "3,183" 4 "17,200" "18,068" 4297 "13,771" "3,429" 5 "16,667" "18,960" 5780 "13,180" "3,487"
Note that the number of shares released for dividends is determined by dividing the amount of dividends on allocated shares (12,481 multiplied by $1.25 in Year 2; 26,686 multiplied by $1.25 in Year 3, and so forth) by the average fair value of a share of preferred stock ($12.50 in Years 2 and 3). In this example, the remaining shares are released for compensation (14,205 less 1,248 in Year 2; 16,286 less 2,669 in Year 3, and so forth). -
- t Additional share information follows.
-
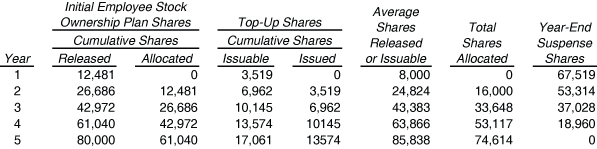 Initial Employee Stock Ownership Plan Shares Top-Up Shares Average Shares Released or Issuable Total Shares Allocated Year-End Suspense Shares Cumulative Shares Cumulative Shares Year Released Allocated Issuable Issued 1 "12,481" 0 " 3,519" 0 " 8,000" 0 "67,519" 2 "26,686" "12,481" " 6,962" " 3,519" "24,824" "16,000" "53,314" 3 "42,972" "26,686" "10,145" " 6,962" "43,383" "33,648" "37,028" 4 "61,040" "42,972" "13,574" 10145 "63,866" "53,117" "18,960" 5 "80,000" "61,040" "17,061" 13574 "85,838" "74,614" 0
-
- u The pre-employee stock ownership plan income, shares outstanding, and income tax assumptions are the same as for Example 1 (see paragraph 718-40-55-3).
-
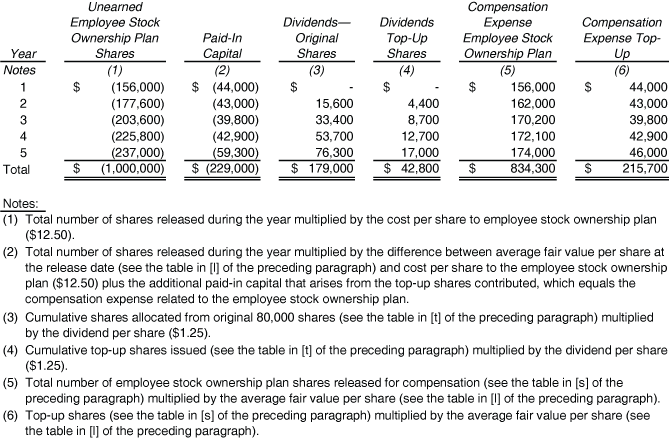 Year Unearned Employee Stock Ownership Plan Shares Paid-In Capital Dividends— Original Shares Dividends Top-Up Shares Compensation Expense Employee Stock Ownership Plan Compensation Expense Top-Up Notes (1) (2) (3) (4) (5) (6) 1 " $(156,000)" " $(44,000)" $- $- " $156,000 " " $44,000 " 2 " (177,600)" " (43,000)" " 15,600 " " 4,400 " " 162,000 " " 43,000 " 3 " (203,600)" " (39,800)" " 33,400 " " 8,700 " " 170,200 " " 39,800 " 4 " (225,800)" " (42,900)" " 53,700 " " 12,700 " " 172,100 " " 42,900 " 5 " (237,000) " " (59,300) " " 76,300 " " 17,000 " " 174,000 " " 46,000 " Total " $(1,000,000)" " $(229,000)" " $179,000 " " $42,800 " " $834,300 " " $215,700 " Notes: (1) Total number of shares released during the year multiplied by the cost per share to employee stock ownership plan ($12.50). (2) "Total number of shares released during the year multiplied by the difference between average fair value per share at the release date (see the table in [l] of the preceding paragraph) and cost per share to the employee stock ownership plan ($12.50) plus the additional paid-in capital that arises from the top-up shares contributed, which equals the compensation expense related to the employee stock ownership plan." (3) "Cumulative shares allocated from original 80,000 shares (see the table in [t] of the preceding paragraph) multiplied by the dividend per share ($1.25)." (4) Cumulative top-up shares issued (see the table in [t] of the preceding paragraph) multiplied by the dividend per share ($1.25). (5) Total number of employee stock ownership plan shares released for compensation (see the table in [s] of the preceding paragraph) multiplied by the average fair value per share (see the table in [l] of the preceding paragraph). (6) Top-up shares (see the table in [s] of the preceding paragraph) multiplied by the average fair value per share (see the table in [l] of the preceding paragraph).
-
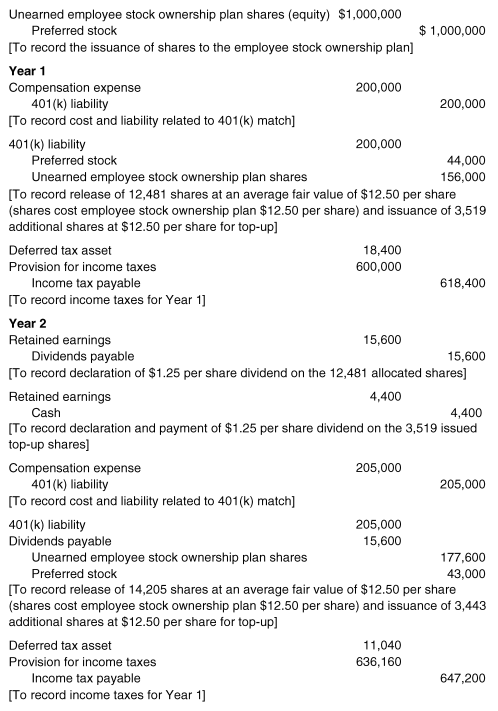 Unearned employee stock ownership plan shares (equity) " $1,000,000 " Preferred stock " $1,000,000 " [To record the issuance of shares to the employee stock ownership plan] Year 1 Compensation expense " 200,000 " 401(k) liability " 200,000 " [To record cost and liability related to 401(k) match] 401(k) liability " 200,000 " Preferred stock " 44,000 " Unearned employee stock ownership plan shares " 156,000 " "[To record release of 12,481 shares at an average fair value of $12.50 per share (shares cost employee stock ownership plan $12.50 per share) and issuance of 3,519 additional shares at $12.50 per share for top-up]" Deferred tax asset " 18,400 " Provision for income taxes " 600,000 " Income tax payable " 618,400 " [To record income taxes for Year 1] Year 2 Retained earnings " 15,600 " Dividends payable " 15,600 " "[To record declaration of $1.25 per share dividend on the 12,481 allocated shares]" Retained earnings " 4,400 " Cash " 4,400 " "[To record declaration and payment of $1.25 per share dividend on the 3,519 issued top-up shares]" Compensation expense " 205,000 " 401(k) liability " 205,000 " [To record cost and liability related to 401(k) match] 401(k) liability " 205,000 " Dividends payable " 15,600 " Unearned employee stock ownership plan shares " 177,600 " Preferred stock " 43,000 " "[To record release of 14,205 shares at an average fair value of $12.50 per share (shares cost employee stock ownership plan $12.50 per share) and issuance of 3,443 additional shares at $12.50 per share for top-up]" Deferred tax asset " 11,040 " Provision for income taxes " 636,160 " Income tax payable " 647,200 " [To record income taxes for Year 1]
-
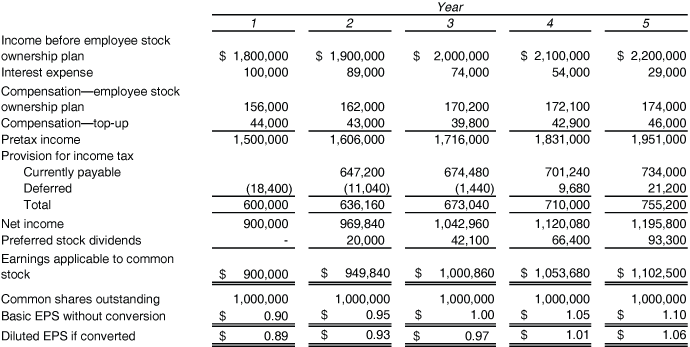 Year 1 2 3 4 5 Income before employee stock ownership plan " $1,800,000 " " $1,900,000 " " $2,000,000 " " $2,100,000 " " $2,200,000 " Interest expense " 100,000 " " 89,000 " " 74,000 " " 54,000 " " 29,000 " Compensation—employee stock ownership plan " 156,000 " " 162,000 " " 170,200 " " 172,100 " " 174,000 " Compensation—top-up " 44,000 " " 43,000 " " 39,800 " " 42,900 " " 46,000 " Pretax income " 1,500,000 " " 1,606,000 " " 1,716,000 " " 1,831,000 " " 1,951,000 " Provision for income tax Currently payable " 647,200 " " 674,480 " " 701,240 " " 734,000 " Deferred " (18,400)" " (11,040)" " (1,440)" " 9,680 " " 21,200 " Total " 600,000 " " 636,160 " " 673,040 " " 710,000 " " 755,200 " Net income " 900,000 " " 969,840 " " 1,042,960 " " 1,120,080 " " 1,195,800 " Preferred stock dividends - " 20,000 " " 42,100 " " 66,400 " " 93,300 " Earnings applicable to common stock " $900,000 " " $949,840 " " $1,000,860 " " $1,053,680 " " $1,102,500 " Common shares outstanding " 1,000,000 " " 1,000,000 " " 1,000,000 " " 1,000,000 " " 1,000,000 " Basic EPS without conversion $0.90 $0.95 $1.00 $1.05 $1.10 Diluted EPS if converted $0.89 $0.93 $0.97 $1.01 $1.06
-
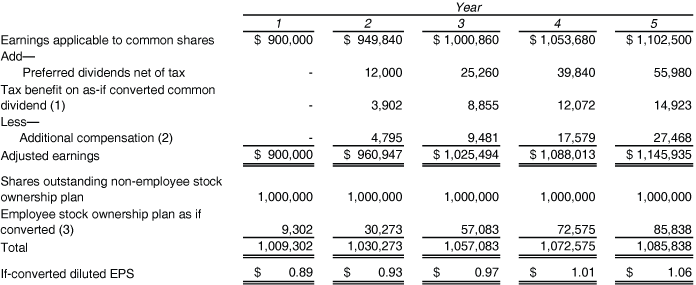 Year 1 2 3 4 5 Earnings applicable to common shares " $900,000 " " $949,840 " " $1,000,860 " " $1,053,680 " " $1,102,500 " Add— Preferred dividends net of tax - " 12,000 " " 25,260 " " 39,840 " " 55,980 " Tax benefit on as-if converted common dividend (1) - " 3,902 " " 8,855 " " 12,072 " " 14,923 " Less— Additional compensation (2) - " 4,795 " " 9,481 " " 17,579 " " 27,468 " Adjusted earnings " $900,000 " " $960,947 " " $1,025,494 " " $1,088,013 " " $1,145,935 " Shares outstanding non-employee stock ownership plan " 1,000,000 " " 1,000,000 " " 1,000,000 " " 1,000,000 " " 1,000,000 " Employee stock ownership plan as if converted (3) " 9,302 " " 30,273 " " 57,083 " " 72,575 " " 85,838 " Total " 1,009,302 " " 1,030,273 " " 1,057,083 " " 1,072,575 " " 1,085,838 " If-converted diluted EPS $0.89 $0.93 $0.97 $1.01 $1.06
-
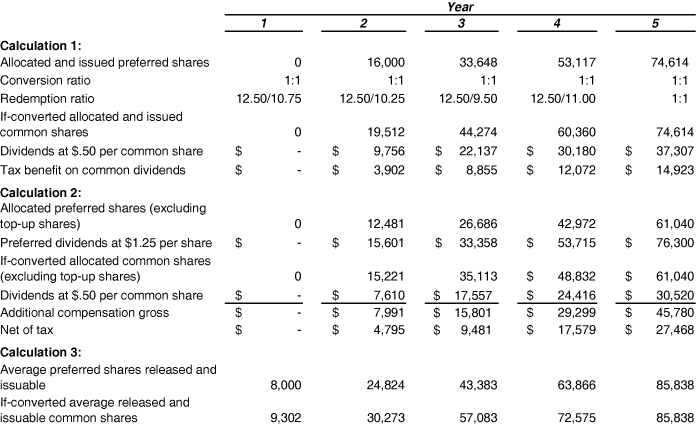 Year 1 2 3 4 5 Calculation 1: Allocated and issued preferred shares 0 " 16,000 " " 33,648 " " 53,117 " " 74,614 " Conversion ratio 1:1 1:1 1:1 1:1 1:1 Redemption ratio 12.50/10.75 12.50/10.25 12.50/9.50 12.50/11.00 1:1 If-converted allocated and issued common shares 0 " 19,512 " " 44,274 " " 60,360 " " 74,614 " Dividends at $.50 per common share $- " $9,756 " " $22,137 " " $30,180 " " $37,307 " Tax benefit on common dividends $- " $3,902 " " $8,855 " " $12,072 " " $14,923 " Calculation 2: Allocated preferred shares (excluding top-up shares) 0 " 12,481 " " 26,686 " " 42,972 " " 61,040 " Preferred dividends at $1.25 per share $- " $15,601 " " $33,358 " " $53,715 " " $76,300 " If-converted allocated common shares (excluding top-up shares) 0 " 15,221 " " 35,113 " " $48,832 " " $61,040 " Dividends at $.50 per common share $- " $7,610 " " $17,557 " " $24,416 " " $30,520 " Additional compensation gross $- " $7,991 " " $15,801 " " $29,299 " " $45,780 " Net of tax $- " $4,795 " " $9,481 " " $17,579 " " $27,468 " Calculation 3: Average preferred shares released and issuable " 8,000 " " 24,824 " " 43,383 " " 63,866 " " 85,838 " If-converted average released and issuable common shares " 9,302 " " 30,273 " " 57,083 " " 72,575 " " 85,838 "
-
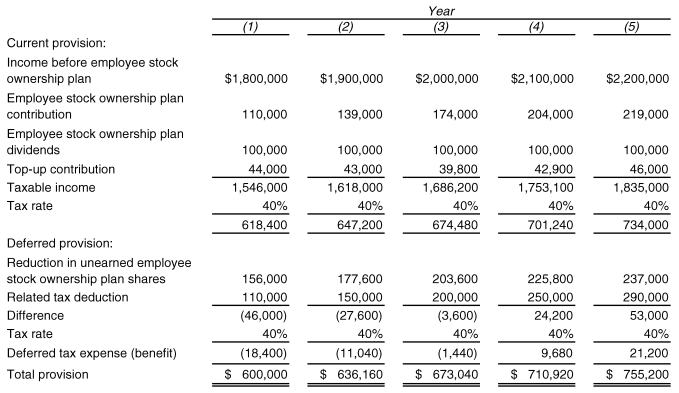 Year (1) (2) (3) (4) (5) Current provision: Income before employee stock ownership plan " $1,800,000 " " $1,900,000 " " $2,000,000 " " $2,100,000 " " $2,200,000 " Employee stock ownership plan contribution " 110,000 " " 139,000 " " 174,000 " " 204,000 " " 219,000 " Employee stock ownership plan dividends " 100,000 " " 100,000 " " 100,000 " " 100,000 " " 100,000 " Top-up contribution " 44,000 " " 43,000 " " 39,800 " " 42,900 " " 46,000 " Taxable income " 1,546,000 " " 1,618,000 " " 1,686,200 " " 1,753,100 " " 1,835,000 " Tax rate 40% 40% 40% 40% 40% " 618,400 " " 647,200 " " 674,480 " " 701,240 " " 734,000 " Deferred provision: Reduction in unearned employee stock ownership plan shares " 156,000 " " 177,600 " " 203,600 " " 225,800 " " 237,000 " Related tax deduction " 110,000 " " 150,000 " " 200,000 " " 250,000 " " 290,000 " Difference " (46,000)" " (27,600)" " (3,600)" " 24,200 " " 53,000 " Tax rate 40% 40% 40% 40% 40% Deferred tax expense (benefit) " (18,400)" " (11,040)" " (1,440)" " 9,680 " " 21,200 " Total provision " $600,000 " " $636,160 " " $673,040 " " $710,920 " " $755,200 "
-
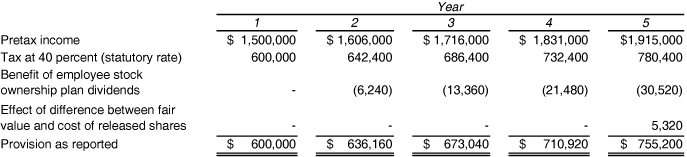 Year 1 2 3 4 5 Pretax income " $1,500,000 " " $1,606,000 " " $1,716,000 " " $1,831,000 " " $1,915,000 " Tax at 40 percent (statutory rate) " 600,000 " " 642,400 " " 686,400 " " 732,400 " " 780,400 " Benefit of employee stock ownership plan dividends - " (6,240)" " (13,360)" " (21,480)" " (30,520)" Effect of difference between fair value and cost of released shares - - - - " 5,320 " Provision as reported " $600,000 " " $636,160 " " $673,040 " " $710,920 " " $755,200 "
Nonleveraged Employee Stock Ownership Plans
- aOn January 1, Year 1, Entity C established a nonleveraged employee stock ownership plan
- bEntity C contributed 10 percent of pretax profit before employee stock ownership plan related charges to the employee stock ownership plan at the end of each of Years 1 through 5; the employee stock ownership plan bought newly issued employer stock with the contribution.
- cThe number of shares, earnings, tax, and other relevant assumptions are the same as those for Example 1, Case A (see paragraph 718-40-55-4).
-
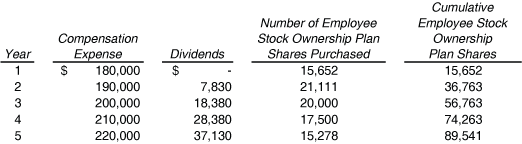 Year Compensation Expense Dividends Number of Employee Stock Ownership Plan Shares Purchased "Cumulative Employee Stock Ownership Plan Shares" 1 " $180,000 " $- "15,652" "15,652" 2 " 190,000 " " 7,830 " "21,111" "36,763" 3 " 200,000 " " 18,380 " "20,000" "56,763" 4 " 210,000 " " 28,380 " "17,500" "74,263" 5 " 220,000 " " 37,130 " "15,278" "89,541"
-
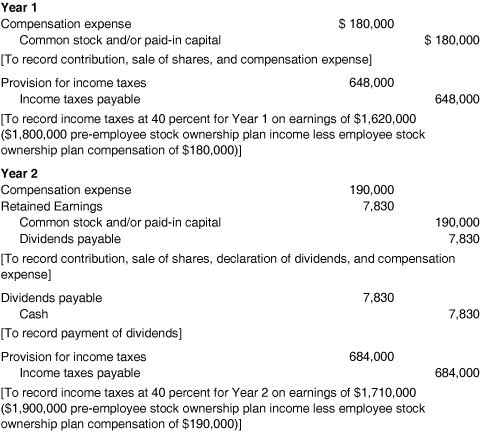 Year 1 Compensation expense " $180,000 " Common stock and/or paid-in capital " $180,000 " "[To record contribution, sale of shares, and compensation expense]" Provision for income taxes " 648,000 " Income taxes payable " 648,000 " "[To record income taxes at 40 percent for Year 1 on earnings of $1,620,000 ($1,800,000 pre-employee stock ownership plan income less employee stock ownership plan compensation of $180,000)]" Year 2 Compensation expense " 190,000 " Retained Earnings " 7,830 " Common stock and/or paid-in capital " 190,000 " Dividends payable " 7,830 " "[To record contribution, sale of shares, declaration of dividends, and compensation expense]" Dividends payable " 7,830 " Cash " 7,830 " [To record payment of dividends] Provision for income taxes " 684,000 " Income taxes payable " 684,000 " "[To record income taxes at 40 percent for Year 2 on earnings of $1,710,000 ($1,900,000 pre-employee stock ownership plan income less employee stock ownership plan compensation of $190,000)]"
718-40-60Relationships
Source downloaded: .Record version be70e9206816. Effective date must be checked in the source.
Compensation—Stock Compensation
718-40-65Transition and Open Effective Date Information
Source downloaded: .Record version 85434d0a7913. Effective date must be checked in the source.
Related subtopics
- 718-20 Awards Classified as EquityCompensation—Stock Compensation
- 718-50 Employee Share Purchase PlansCompensation—Stock Compensation
- 718-740 Income TaxesCompensation—Stock Compensation
- 260-10 OverallEarnings Per Share
- 710-10 OverallCompensation—General
- 325-962 Plan Accounting—Defined Contribution Pension PlansInvestments—Other