ASC 944-80
Separate Accounts
944 Financial Services—Insurance
Source downloaded: .Record version 3c5db535133f. Effective date must be checked in the source.
ASC 944-80 governs how an insurance entity accounts for and presents separate accounts — pools of assets and liabilities maintained to fund variable annuity, variable life, pension and similar contracts where the contract holder generally bears the investment risk. If a separate account arrangement meets the four criteria in 944-80-25-2 (legal recognition, legal insulation from general account liabilities, contract-holder-directed investment, and full pass-through of investment performance), the contract holder portion is measured at fair value and reported as a single summary total asset with an equivalent summary total liability, with investment performance and amounts credited offset to zero. If any criterion fails (e.g., guaranteed interest or market value adjusted "spread" products), the assets and liabilities are accounted for and presented as ordinary general account items.
Key points (7)
- Separate account assets and liabilities are included in the financial statements of the insurance entity that owns the assets and is contractually obligated to pay the liabilities (944-80-25-1; 944-80-45-1).
- Separate account accounting applies only if all four conditions in 944-80-25-2 are met: legal recognition, legal insulation from general account liabilities, contract-holder-directed investment, and pass-through of all investment performance net of fees (a minimum guarantee is permitted, but a ceiling is not).
- When the criteria are met, the contract holder portion is measured initially and subsequently at fair value (944-80-30-1; 944-80-35-2), presented as summary totals (944-80-45-2), and related investment performance and amounts credited to contract holders are offset within the same statement of operations line netting to zero (944-80-45-3); minimum guarantee and insurance benefit liabilities in excess of separate account fair value are general account liabilities (944-80-25-3(b)).
- If the criteria are not met — as with fixed account options, market value adjusted contracts, guaranteed investment contracts, and indexed contracts — the assets, liabilities, revenues, and expenses are measured and presented as general account items (944-80-25-4 through 25-5; 944-80-55-20).
- The insurer's own proportionate interest (seed money) does not qualify for separate account accounting; the insurer looks through and accounts for those underlying assets as if held directly by the general account (944-80-25-6 through 25-7), unless its interest is under 20 percent and all underlying investments are securities or cash equivalents, in which case it may report an equity security investment under Subtopic 321-10 (944-80-25-11).
- For consolidation, a qualifying separate account is treated as a subsidiary for retention of specialized investment accounting (810-10-25-15); separate account interests held for policy holders are not treated as the insurer's interests and are not combined with general account interests, except for related-party policy holders under the VIE Subsections (944-80-25-3(d) through (f)).
- Assets transferred from the general account to a qualifying separate account are recognized at fair value to the extent of third-party contract holders' proportionate interests, with the related gain recognized immediately in general account earnings only if risks and rewards have transferred (944-80-40-1; a guarantee or repurchase commitment precludes gain under 944-80-35-5); disclosures include contract nature and minimum guarantees, basis of presentation, aggregate fair value by major asset category, transfer gains and losses (944-80-50-1), and a disaggregated liability rollforward with cash surrender values and reconciliation (944-80-50-2).
For students. The exam trap is assuming that anything a regulator labels a "separate account" gets separate account presentation — it does not; guaranteed interest, market value adjusted, and indexed options fail the full pass-through test in 944-80-25-2(d) and are reported as general account assets and liabilities. Also remember the insurer's own seed money never gets separate account treatment; it is looked through and accounted for as if held directly in the general account.
Machine-generated study aid for ASC 944-80. Check the source paragraphs below.
944-80-00Status
Source downloaded: .Record version 0f63a7566a18. Effective date must be checked in the source.
944-80-05Overview and Background
Source downloaded: .Record version 9801d61f138a. Effective date must be checked in the source.
- aA variable life insurance contract offered through an insurance entity's high return separate account
- bA contract holder's allocation of a portion of the contract holder's deposit in a deferred variable annuity to a growth equity fund.
944-80-15Scope and Scope Exceptions
Source downloaded: .Record version f31fafcd02f2. Effective date must be checked in the source.
Overall Guidance
944-80-25Recognition
Source downloaded: .Record version 1e22b30b42da. Effective date must be checked in the source.
Overall
- aThe separate account is recognized legally; that is, the separate account is established, approved, and regulated under special rules such as state insurance laws, federal securities laws, or similar foreign laws.
- bThe separate account assets supporting the contract liabilities are insulated legally from the general account liabilities of the insurance entity; that is, the contract holder is not subject to insurer default risk to the extent of the assets held in the separate account.
- cThe insurer must, as a result of contractual, statutory, or regulatory requirements, invest the contract holder's funds within the separate account as directed by the contract holder in designated investment alternatives or in accordance with specific investment objectives or policies.
- dAll investment performance, net of contract fees and assessments, must as a result of contractual, statutory, or regulatory requirements be passed through to the individual contract holder. Contracts may specify conditions under which there may be a minimum guarantee, but not a ceiling, as a ceiling would prohibit all investment performance from being passed through to the contract holder.
- aThe portion of separate account assets representing contract holder funds shall be reported in the insurance entity's financial statements as a summary total, with an equivalent summary total reported for related liabilities.
- bAny liabilities related to minimum guarantees (including market risk benefits) and insurance benefit liabilities under the contracts in excess of the fair value of separate account assets representing contract holder funds shall be recognized as general account liabilities.
- cContract fees and assessments shall be reported in accordance with paragraph 944-605-25-5.
- dFor the purpose of evaluating the retention of specialized accounting for investments in consolidation as described in paragraph 810-10-25-15, a separate account arrangement shall be considered a subsidiary. An insurer is not required to consolidate an investment in which a separate account holds a controlling financial interest if the investment is not or would not be consolidated in the standalone financial statements of the separate account.
- eExcept as described in paragraph (f), the insurer shall not do either of the following when assessing whether the insurer is required to consolidate an investment held by a separate account:
- 1Consider any separate account interests held for the benefit of policy holders to be the insurer's interests
- 2Combine any separate account interests held for the benefit of policy holders with the insurer's general account interest in the same investment.
- 1
- fSeparate account interests held for the benefit of a related party policy holder shall be combined with the insurer's general account interest when the Variable Interest Entities Subsections of Subtopic 810-10 require the consideration of related parties. For this purpose, a related party includes any party identified in paragraph 810-10-25-43 other than:
- 1An employee of the decision maker or service provider (and its other related parties), except if the employee is used in an effort to circumvent the provisions of Subtopic 810-10
- 2An employee benefit plan of the decision maker or service provider (and its other related parties), except if the employee benefit plan is used in an effort to circumvent the provisions of Subtopic 810-10.
- 1
- aAssets representing contract holder funds under the arrangement shall be measured and presented the same as other general account assets as prescribed in this Topic.
- bAny related liability shall be accounted for as a general account liability.
- cRevenue and expenses related to such arrangements shall be recognized within the respective revenue and expense lines in the statement of operations.
Proportionate Interest in a Separate Account
- aThe terms of the contract allow the contract holder to invest in additional units in the separate account.
- bThe insurance entity is marketing contracts that permit funds to be invested in the separate account.
- aFor a debt security, the guidance in Topic 326 shall be followed for the measurement of credit losses.
- bThe guidance in Subtopic 360-10 shall be followed for both real estate that is held for sale and real estate that is not held for sale. For real estate that does not meet that Subtopic's held-for-sale criteria, the impairment test shall be performed solely using undiscounted cash flows assuming immediate disposition.
- aAn insurance entity's interest in the separate account represents 20 percent or greater of the separate account interest.
- bThe underlying investments are other than those that meet the definition of any of the following:
- 1
- 2
- 3Cash and cash equivalents.
- aThe insurance entity's proportionate interest in the separate account is less than 20 percent of the separate account.
- bAll of the underlying investments of the separate account meet the definition of any of the following:
- 1
- 2
- 3Cash and cash equivalents.
Consolidation of an Investment Fund When Separate Accounts Are Involved
- aThe portion of the fund assets representing the contract holder's interests shall be included as separate account assets and liabilities in accordance with paragraph 944-80-25-3.
- bThe remaining portion of the fund assets (including the portion owned by any other investors) shall be included in the general account of the insurer on a line-by-line basis. For example, if the consolidated fund held debt and equity securities, those amounts would be included in the debt and securities lines.
- cNoncontrolling interests should not be included in the separate account liability but rather classified as a liability or equity based on other applicable guidance.
944-80-30Initial Measurement
Source downloaded: .Record version 5e814ab609bd. Effective date must be checked in the source.
944-80-35Subsequent Measurement
Source downloaded: .Record version 10019b5d8023. Effective date must be checked in the source.
Overall
Transfers to Separate Accounts
944-80-40Derecognition
Source downloaded: .Record version 4210e6f79421. Effective date must be checked in the source.
Transfers to Separate Accounts
944-80-45Other Presentation Matters
Source downloaded: .Record version f3229634d714. Effective date must be checked in the source.
Overall
944-80-50Disclosure
Source downloaded: .Record version 68e1c3dec5e6. Effective date must be checked in the source.
- aThe general nature of the contracts reported in separate accounts, including the extent and terms of minimum guarantees (including market risk benefits)
- bThe basis of presentation for both of the following:
- 1Separate account assets and liabilities
- 2Related separate account activity.
- 1
- c
- d
- eThe aggregate fair value of assets, by major investment asset category, supporting separate accounts as of each date for which a statement of financial position is presented
- fThe amount of gains and losses recognized on assets transferred to separate accounts for the periods presented.
- aA year-to-date disaggregated tabular rollforward of the beginning balance to the ending balance disaggregated in accordance with paragraph 944-40-50-5A
- bFor each separate account liability rollforward presented, the related cash surrender values
- cA reconciliation of the separate account liability rollforwards to the aggregated ending carrying amount of the liability in the statement of financial position.
944-80-55Implementation Guidance and Illustrations
Source downloaded: .Record version 825e48a1cf1b. Effective date must be checked in the source.
Illustrations
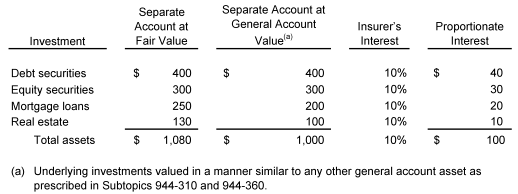 Investment Separate Account at Fair Value Separate Account at General Account Value(a) Insurer's Interest Proportionate Interest Debt securities $400 $400 10% $40 Equity securities 300 300 10% 30 Mortgage loans 250 200 10% 20 Real estate 130 100 10% 10 Total assets " $1,080 " " $1,000 " 10% $100 (a) Underlying investments valued in a manner similar to any other general account asset as prescribed in Subtopics 944-310 and 944-360.
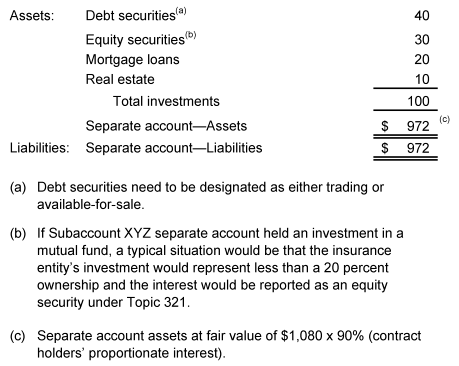 Assets: Debt securities(a) 40 "Equity securities(a), (b)" 30 Mortgage loans 20 Real estate 10 Total investments 100 Separate account—Assets $972 (c) Liabilities: Separate account—Liabilities $972 (a) Debt securities need to be designated as either trading or available-for-sale. (b) "If Subaccount XYZ separate account held an investment in a mutual fund, a typical situation would be that the insurance entity's investment would represent less than a 20 percent ownership and the interest would be reported as an equity security under Topic 321." (c) "Separate account assets at fair value of $1,080 x 90% (contract holders' proportionate interest)."
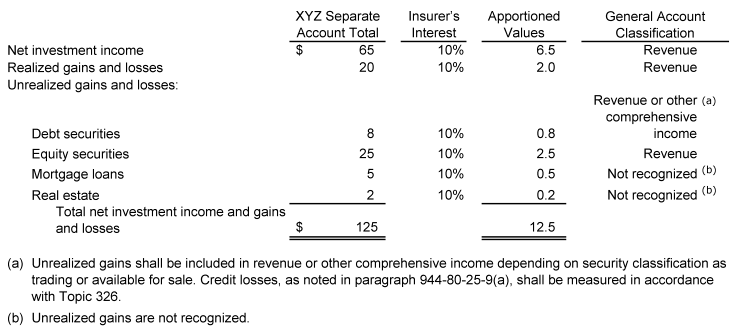 XYZ Separate Account Total Insurer's Interest Apportioned Values General Account Classification Net investment income $65 10% 6.5 Revenue Realized gains and losses 20 10% 2.0 Revenue Unrealized gains and losses: Debt securities 8 10% 0.8 Revenue or other comprehensive income (a) Equity securities 25 10% 2.5 Revenue Mortgage loans 5 10% 0.5 Not recognized (b) Real estate 2 10% 0.2 Not recognized (b) Total net investment income and gains and losses $125 12.5 (a) "Unrealized gains shall be included in revenue or other comprehensive income depending on security classification as trading or available for sale. Credit losses, as noted in paragraph 944-80-25-9(a), shall be measured in accordance with Topic 326. " (b) Unrealized gains are not recognized.
- aInsurer interest is lowered to 5 percent on the last day of the first quarter.
- bAt the time of dilution:
- 1Separate account at fair value was $ 1,090.
- 2Separate account at general account value was $ 1,007.
- 1
- cFair value of each investment increases 1 percent.
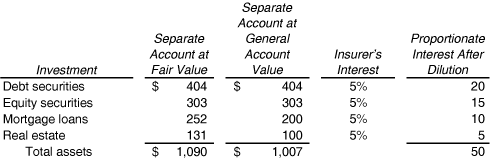 Investment Separate Account at Fair Value Separate Account at General Account Value Insurer's Interest Proportionate Interest After Dilution Debt securities $404 $404 5% 20 Equity securities 303 303 5% 15 Mortgage loans 252 200 5% 10 Real estate 131 100 5% 5 Total assets " $1,090 " " $1,007 " 50
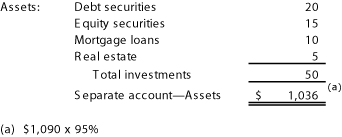 Assets: Debt securities 20 Equity securities 15 Mortgage loans 10 Real estate 5 Total investments 50 Separate account—Assets " $1,036 " (a) (a) "$1,090 x 95%"
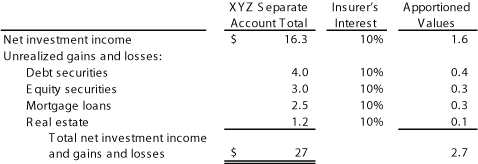 XYZ Separate Account Total Insurer's Interest Apportioned Values Net investment income $16.3 10% 1.6 Unrealized gains and losses: Debt securities 4.0 10% 0.4 Equity securities 3.0 10% 0.3 Mortgage loans 2.5 10% 0.3 Real estate 1.2 10% 0.1 Total net investment income and gains and losses $27 2.7
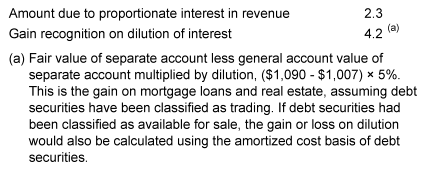 Amount due to proportionate interest in revenue 2.3 Gain recognition on dilution of interest 4.2 (a) (a) "Fair value of separate account less general account value of separate account multiplied by dilution, ($1,090 - $1,007) × 5%. This is the gain on mortgage loans and real estate, assuming debt securities have been classified as trading. If debt securities had been classified as available for sale, the gain or loss on dilution would also be calculated using the amortized cost basis of debt securities."
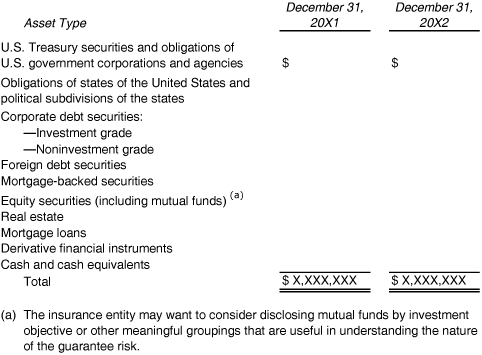 Asset Type "December 31, 20X1" "December 31, 20X2" U.S. Treasury securities and obligations of U.S. government corporations and agencies $ $ Obligations of states of the United States and political subdivisions of the states Corporate debt securities: —Investment grade —Noninvestment grade Foreign debt securities Mortgage-backed securities Equity securities (including mutual funds) (a) Real estate Mortgage loans Derivative financial instruments Cash and cash equivalents Total "$ X,XXX,XXX" "$ X,XXX,XXX" (a) The insurance entity may want to consider disclosing mutual funds by investment objective or other meaningful groupings that are useful in understanding the nature of the guarantee risk.
- Note X: Separate Account Liability
- The balances of and changes in separate account liabilities follow.
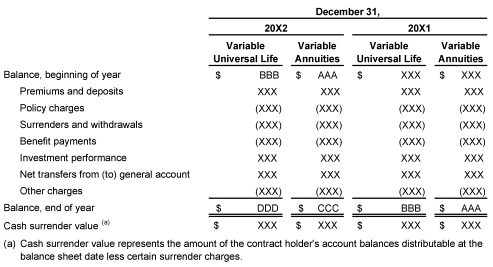 "December 31," 20X2 20X1 Variable Universal Life Variable Annuities Variable Universal Life Variable Annuities "Balance, beginning of year" $BBB $AAA $XXX $XXX Premiums and deposits XXX XXX XXX XXX Policy charges (XXX) (XXX) (XXX) (XXX) Surrenders and withdrawals (XXX) (XXX) (XXX) (XXX) Benefit payments (XXX) (XXX) (XXX) (XXX) Investment performance XXX XXX XXX XXX Net transfers from (to) general account XXX XXX XXX XXX Other charges (XXX) (XXX) (XXX) (XXX) "Balance, end of year" $DDD $CCC $BBB $AAA Cash surrender value (a) $XXX $XXX $XXX $XXX (a) Cash surrender value represents the amount of the contract holder's account balances distributable at the balance sheet date less certain surrender charges.
- The reconciliation of separate account liabilities to the separate account liability balance in the consolidated statement of financial position follows.
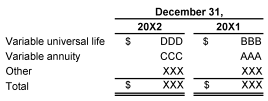 "December 31, " 20X2 20X1 Variable universal life $DDD $BBB Variable annuity CCC AAA Other XXX XXX Total $XXX $XXX
944-80-65Transition and Open Effective Date Information
Source downloaded: .Record version 09e0393f7892. Effective date must be checked in the source.
Related subtopics
- 815-944 Financial Services—InsuranceDerivatives and Hedging
- 325-965 Plan Accounting—Health and Welfare Benefit PlansInvestments—Other
- 805-944 Financial Services—InsuranceBusiness Combinations
- 944-20 Insurance ActivitiesFinancial Services—Insurance
- 944-40 Claim Costs and Liabilities for Future Policy BenefitsFinancial Services—Insurance
- 944-10 OverallFinancial Services—Insurance