ASC 505-944
Financial Services—Insurance
505 Equity
Source downloaded: .Record version 69223024c1a8. Effective date must be checked in the source.
This Subtopic sets the equity-related disclosure requirements for insurance entities, focusing on statutory capital and surplus and how statutory accounting practices constrain dividends. Entities must disclose statutory capital and surplus, the amount needed to meet regulatory requirements, and restrictions on retained earnings available for dividends (505-944-50-1). When state-prescribed or permitted statutory accounting practices differ from NAIC statutory accounting practices and produce a significantly different statutory surplus or risk-based capital, the entity must describe the practice and quantify its monetary effect on statutory surplus (505-944-50-2 through 50-3).
Key points (7)
- Insurance entities must disclose the amount of statutory capital and surplus, the amount necessary to satisfy regulatory requirements if significant in relation to statutory capital and surplus, and the nature of statutory dividend restrictions plus retained earnings unavailable for dividends (505-944-50-1).
- The prescribed/permitted practice disclosures apply to annual and complete sets of interim GAAP financial statements, and are triggered only if the practices cause a significant difference in reported statutory surplus or risk-based capital versus NAIC statutory accounting practices AND state-prescribed or permitted practices differ from NAIC (or state-prescribed) practices (505-944-50-2).
- If triggered, the entity discloses at each financial statement date a description of the prescribed or permitted statutory accounting practice and the related monetary effect on statutory surplus (505-944-50-3).
- These disclosures apply to a U.S. insurance entity, a U.S. entity with a U.S. insurance subsidiary, and a foreign entity with a U.S. insurance subsidiary that prepares U.S. GAAP financial statements (505-944-50-4).
- A foreign insurance entity without a U.S. insurance subsidiary that prepares (or is included in a parent's consolidated) U.S. GAAP financial statements must disclose permitted regulatory accounting practices that significantly differ from its regulator's prescribed practices and their monetary effects (505-944-50-5).
- If risk-based capital would have triggered a regulatory event but for a permitted practice, that fact must be disclosed (505-944-50-6).
- Section 55 illustrates compliant note disclosures (e.g., immediate goodwill write-off as a prescribed practice and carrying home office property at fair value as a permitted practice, with quantified surplus effects) (505-944-55-1 through 55-2).
For students. Remember this is a disclosure-only subtopic: statutory accounting (SAP) is not GAAP, but GAAP financial statements of insurers must reveal SAP-based surplus and the dividend limits it imposes. The common misunderstanding is thinking the monetary-effect disclosure adjusts GAAP equity — it only quantifies the effect on statutory surplus, and only when the two-part trigger in 505-944-50-2 is met.
Machine-generated study aid for ASC 505-944. Check the source paragraphs below.
505-944-05Overview and Background
Source downloaded: .Record version e08c709905e4. Effective date must be checked in the source.
505-944-15Scope and Scope Exceptions
Source downloaded: .Record version 6d88c763bc9b. Effective date must be checked in the source.
Overall Guidance
505-944-50Disclosure
Source downloaded: .Record version 946e410697a6. Effective date must be checked in the source.
- aThe amount of statutory capital and surplus
- bThe amount of statutory capital and surplus necessary to satisfy regulatory requirements (based on the entity's current operations) if significant in relation to the entity's statutory capital and surplus
- cThe nature of statutory restrictions on the payment of dividends and the amount of retained earnings that is not available for the payment of dividends to stockholders.
- aThe use of prescribed or permitted statutory accounting practices (individually or in the aggregate) results in reported statutory surplus or risk-based capital that is significantly different from the statutory surplus or risk-based capital that would have been reported had National Association of Insurance Commissioners' statutory accounting practices been followed.
- bEither of the following conditions is met:
- 1State-prescribed statutory accounting practices differ from National Association of Insurance Commissioners' statutory accounting practices.
- 2Permitted state statutory accounting practices differ from either state-prescribed statutory accounting practices or National Association of Insurance Commissioners' statutory accounting practices.
- 1
- aA description of the prescribed or permitted statutory accounting practice
- bThe related monetary effect on statutory surplus of using an accounting practice that differs from either state-prescribed statutory accounting practices or National Association of Insurance Commissioners' statutory accounting practices.
- aA U.S. insurance entity
- bA U.S. entity with a U.S. insurance subsidiary
- cA foreign entity with a U.S. insurance subsidiary.
505-944-55Implementation Guidance and Illustrations
Source downloaded: .Record version 02cbd0d548f5. Effective date must be checked in the source.
Illustrations
- Note X. Statutory Accounting Practices
- The Entity's statutory financial statements are presented on the basis of accounting practices prescribed or permitted by the [state of domicile] Insurance Department. [State of domicile] has adopted the National Association of Insurance Commissioners' statutory accounting practices as the basis of its statutory accounting practices, except that it has retained the prescribed practice of writing off goodwill immediately to statutory surplus in the year of acquisition.
- In addition, the commissioner of [state of domicile] Insurance Department has the right to permit other specific practices that may deviate from prescribed practices. The commissioner has permitted the Entity to record its home office property at estimated fair value instead of at depreciated cost, as required by National Association of Insurance Commissioners' statutory accounting practices. This accounting practice increased statutory capital and surplus by $2.5 million and $2.3 million at December 31, 20X2 and 20X1, respectively, over what it would have been had the permitted practice not been allowed. The Entity's statutory capital and surplus, including the effects of the permitted practice, was $30.0 million and $27.9 million at December 31, 20X2 and 20X1, respectively.
- Had the Entity amortized its goodwill over 10 years and recorded its home office property at depreciated cost, in accordance with National Association of Insurance Commissioners' statutory accounting practices, the Entity's capital and surplus would have been $29.9 million and $27.7 million at December 31, 20X2, and 20X1, respectively.
- Note X. Statutory Accounting Practices
- The Entity's statutory financial statements are presented on the basis of accounting practices prescribed or permitted by the [state of domicile] Insurance Department. [State of domicile] has adopted the National Association of Insurance Commissioners' statutory accounting practices as the basis of its statutory accounting practices, except that it has retained the prescribed practice of writing off goodwill immediately to statutory surplus in the year of acquisition.
- In addition, the commissioner of the [state of domicile] Insurance Department has the right to permit other specific practices that may deviate from prescribed practices. The commissioner has permitted the Entity to record its home office property at estimated fair value instead of at depreciated cost, as required by National Association of Insurance Commissioners' statutory accounting practices.
- The monetary effect on statutory capital and surplus of using accounting practices prescribed or permitted by the [state of domicile] Insurance Department is as follows.
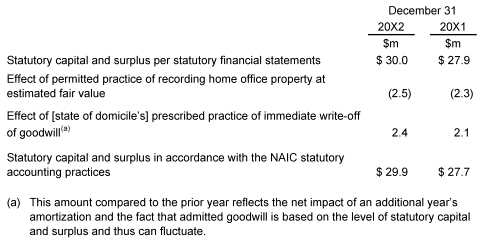 December 31 20X2 20X1 $m $m Statutory capital and surplus per statutory financial statements $30.0 $27.9 Effect of permitted practice of recording home office property at estimated fair value (2.5) (2.3) Effect of [state of domicile's] prescribed practice of immediate write-off of goodwill(a) 2.4 2.1 Statutory capital and surplus in accordance with the NAIC statutory accounting practices $29.9 $27.7 (a) This amount compared to the prior year reflects the net impact of an additional year's amortization and the fact that admitted goodwill is based on the level of statutory capital and surplus and thus can fluctuate.
Related subtopics
- 210-944 Financial Services—InsuranceBalance Sheet
- 944-10 OverallFinancial Services—Insurance
- 220-944 Financial Services—InsuranceIncome Statement—Reporting Comprehensive Income
- 210-942 Financial Services—Depository and LendingBalance Sheet
- 235-944 Financial Services—InsuranceNotes to Financial Statements
- 942-10 OverallFinancial Services—Depository and Lending