ASC 505-60
Spinoffs and Reverse Spinoffs
505 Equity
Source downloaded: .Record version b9e674f0a489. Effective date must be checked in the source.
ASC 505-60 governs the pro rata distribution of nonmonetary assets that constitute a business to an entity's owners (a spinoff). Such distributions are recorded at the carrying (recorded) amount of the distributed business, reduced for any indicated impairment, and are never accounted for as a sale of the spinnee followed by a distribution of proceeds — even if the spun-off operations are sold immediately afterward. When the substance of the transaction differs from its legal form, the legal spinnee is treated as the accounting spinnor (reverse spinoff accounting).
Key points (7)
- The Subtopic applies only to distributions of nonmonetary assets to owners that constitute a business; distributions of nonmonetary assets that do not constitute a business are outside its scope (505-60-15-2 through 15-3).
- Per paragraph 845-10-30-10, as applied in 505-60-25-2, a spinoff of a wholly owned or consolidated subsidiary is recorded at the subsidiary's carrying value (after reduction for any indicated impairment of value), and the transaction is not accounted for as a sale of the accounting spinnee followed by a distribution of proceeds, regardless of an immediate post-spinoff sale.
- In a reverse spinoff, the legal spinnee is treated as the spinnor for accounting purposes (the accounting spinnor) because in substance the legal spinnor disposed of its own operations and continued the legal spinnee's operations (505-60-25-4 through 25-5).
- A presumption exists that a spinoff is accounted for based on its legal form (legal spinnor = accounting spinnor); that presumption may be overcome only by judgment based on all relevant facts and circumstances (505-60-25-7 through 25-8).
- The four indicators of reverse spinoff accounting — relative size (assets, revenues, earnings), relative fair value, retention of senior management, and length of time to be held (a concurrent plan of sale suggests that entity is the accounting spinnee) — are evaluated together, and no single indicator is presumptive or determinative (505-60-25-8(a) through (d)).
- The identification of the accounting spinnee matters for reporting: the accounting spinnee is reported as a discontinued operation by the accounting spinnor if it qualifies and meets the conditions in 205-20-45-1A through 45-1C (505-60-45-1).
- Compensation consequences of exchanging or modifying share options or other equity instruments in connection with an equity restructuring are addressed in Topic 718 (505-60-60-1).
For students. Exam traps: (1) no gain is recognized — the distributed business comes off the books at carrying value, even if the shareholders sell it the next day; and (2) the "reverse" label is not optional dressing — if the legal spinnee is bigger, more valuable, keeps senior management, and the legal spinnor is slated for sale, you must flip the accounting so the legal spinnor's operations are shown as disposed (often as a discontinued operation).
Machine-generated study aid for ASC 505-60. Check the source paragraphs below.
505-60-00Status
Source downloaded: .Record version e00263b2abf7. Effective date must be checked in the source.
| Paragraph | Action | Accounting Standards Update | Date |
| Business | Amended | Accounting Standards Update No. 2017-01 | 01/05/2017 |
| 505-60-15-1 | Amended | Accounting Standards Update No. 2016-19 | 12/14/2016 |
| 505-60-45-1 | Amended | Accounting Standards Update No. 2014-08 | 04/10/2014 |
505-60-05Overview and Background
Source downloaded: .Record version cfbbe59034d6. Effective date must be checked in the source.
505-60-15Scope and Scope Exceptions
Source downloaded: .Record version e1c208332f09. Effective date must be checked in the source.
Entities
Transactions
505-60-25Recognition
Source downloaded: .Record version 9b9afd3a1d86. Effective date must be checked in the source.
Required Accounting for Spinoffs, Including Reverse Spinoffs
Determining the Accounting Spinnor and Spinnee
- aThe size of the legal spinnor and the legal spinnee. All other factors being equal, in a reverse spinoff, the accounting spinnor (legal spinnee) is larger than the accounting spinnee (legal spinnor). The determination of which entity is larger is based on a comparison of the assets, revenues, and earnings of the two entities. There are no established bright lines that shall be used to determine which entity is the larger of the two.
- bThe fair value of the legal spinnor and the legal spinnee. All other factors being equal, in a reverse spinoff, the fair value of the accounting spinnor (legal spinnee) is greater than that of the accounting spinnee (legal spinnor).
- cSenior management. All other factors being equal, in a reverse spinoff, the accounting spinnor (legal spinnee) retains the senior management of the formerly combined entity. Senior management generally consists of the chairman of the board, chief executive officer, chief operating officer, chief financial officer, and those divisional heads reporting directly to them, or the executive committee if one exists.
- dLength of time to be held. All other factors being equal, in a reverse spinoff, the accounting spinnor (legal spinnee) is held for a longer period than the accounting spinnee (legal spinnor). A proposed or approved plan of sale for one of the separate entities concurrent with the spinoff may identify that entity as the accounting spinnee.
505-60-45Other Presentation Matters
Source downloaded: .Record version 573bcf10c376. Effective date must be checked in the source.
505-60-55Implementation Guidance and Illustrations
Source downloaded: .Record version 194616d4cba4. Effective date must be checked in the source.
Illustrations
- a Retail Company, a retail store chain, has a wholly owned restaurant subsidiary. The retail and restaurant operations are operated independently with a small executive management team overseeing both. Because the two have unrelated operations, the shareholders believe that the two operations should be separated by way of a spinoff. They believe that this will allow those separate entities to pursue opportunities in their respective industries and maximize their individual value.
- b In order to accomplish the spinoff, Retail Company creates a new legal entity, Restaurant Company, into which the assets and operations of the restaurant subsidiary are transferred. The shares of Restaurant Company are then distributed to the shareholders of Retail Company on a pro rata basis.
- c The executive management team of Retail Company will be divided between the two entities. A comparison of the two entities is as follows.
-
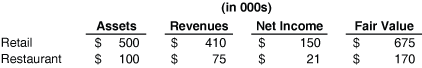 (In 000s) Assets Revenues Net Income Fair Value Retail $500 $410 $150 $675 Restaurant $100 $75 $21 $170
-
- a Retail Company has substantially larger operations than Restaurant Company.
- b The fair value of Retail Company is greater than Restaurant Company.
- c The management team is allocated between the two operations.
- d There are no planned or likely disposals of either Retail Company or Restaurant Company.
- aRetail Company, a retail store chain, has a wholly owned restaurant subsidiary. The retail and restaurant operations are operated independently, with a small executive management team overseeing both. While the restaurant subsidiary has grown rapidly, the retail operations have deteriorated steadily due to increased competition. The shareholders believe that the two operations should be separated by way of a spinoff. Management intends to dispose of the retail operations.
- bIn order to accomplish the spinoff, Retail Company creates a new legal entity, Restaurant Company, into which the assets and operations of the restaurant subsidiary are transferred. The shares of Restaurant Company are then distributed to the shareholders of Retail Company on a pro rata basis.
- cThe executive management team of the combined entity will be assigned primarily to Restaurant Company, as the intent is to dispose of Retail Company (now solely comprising the retail operations). A comparison of certain statistics of the two entities is as follows.
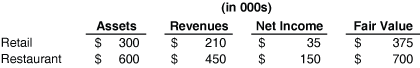 (In 000s) Assets Revenues Net Income Fair Value Retail $300 $210 $35 $375 Restaurant $600 $450 $150 $700
- a Restaurant Company has substantially larger operations than Retail Company.
- b The fair value of Restaurant Company is greater than that of Retail Company.
- c The management team is primarily assigned to Restaurant Company.
- d Management intends to dispose of Retail Company upon finalizing the spinoff.
505-60-60Relationships
Source downloaded: .Record version 80619ecb7a36. Effective date must be checked in the source.
Compensation—Stock Compensation
505-60-S00StatusSEC
Source downloaded: .Record version d9f139ec199b. Effective date must be checked in the source.
| Paragraph | Action | Accounting Standards Update | Date |
| 505-60-S99-1 | Amended | Accounting Standards Update No. 2012-03 | 08/27/2012 |
505-60-S45Other Presentation MattersSEC
Source downloaded: .Record version f3d73fc55ced. Effective date must be checked in the source.
Accounting for the Spinoff of a Subsidiary
505-60-S99SEC MaterialsSEC
Source downloaded: .Record version de0ec0b79dec. Effective date must be checked in the source.
SEC Staff Guidance
- Facts: A Company disposes of a business through the distribution of a subsidiary's stock to the Company's shareholders on a pro rata basis in a transaction that is referred to as a spin-off.
- Question: May the Company elect to characterize the spin-off transaction as resulting in a change in the reporting entity and restate its historical financial statements as if the Company never had an investment in the subsidiary, in the manner specified by FASB ASC Topic 250, Accounting Changes and Error Corrections?
- Interpretive Response: Not ordinarily. If the Company was required to file periodic reports under the Exchange Act within one year prior to the spin-off, the staff believes the Company should reflect the disposition in conformity with FASB ASC Topic 360. This presentation most fairly and completely depicts for investors the effects of the previous and current organization of the Company. However, in limited circumstances involving the initial registration of a company under the Exchange Act or Securities Act, the staff has not objected to financial statements that retroactively reflect the reorganization of the business as a change in the reporting entity if the spin-off transaction occurs prior to effectiveness of the registration statement. This presentation may be acceptable in an initial registration if the Company and the subsidiary are in dissimilar businesses, have been managed and financed historically as if they were autonomous, have no more than incidental common facilities and costs, will be operated and financed autonomously after the spin-off, and will not have material financial commitments, guarantees, or contingent liabilities to each other after the spin-off. This exception to the prohibition against retroactive omission of the subsidiary is intended for companies that have not distributed widely financial statements that include the spun-off subsidiary. Also, dissimilarity contemplates substantially greater differences in the nature of the businesses than those that would ordinarily distinguish reportable segments as defined by FASB ASC paragraph 280-10-50-10 (Segment Reporting Topic).