ASC 505-946
Financial Services—Investment Companies
505 Equity
Source downloaded: .Record version 5a6b76e12d4c. Effective date must be checked in the source.
This Subtopic governs equity transactions and reporting for investment companies, focusing on capital share transactions and distributions to shareholders. It requires per-class disclosure of net asset value per share and the components of the net change in net assets from capital share transactions, along with tax-basis components of dividends paid. Return of capital is determined only at the fund level, not per class.
Key points (7)
- Net asset value per share must be disclosed for each class of shares (505-946-50-1).
- The net change in net assets from capital share transactions must be disclosed by class, showing the number and value of shares sold, shares issued in reinvestment of distributions, the number and cost of shares reacquired, and the net change (505-946-50-2).
- Net assets at the beginning and end of the year must be disclosed, and the ending balance must agree with the statement of assets and liabilities or statement of net assets (505-946-50-3).
- For financial reporting, a return of capital is not determined at the class level, and distributable earnings is disclosed only at the fund level (505-946-50-4).
- Notes must disclose the tax-basis components of dividends paid: ordinary income distributions, long-term capital gains distributions, and return of capital distributions (505-946-50-5).
- Notes must explain the primary reasons for any significant difference between GAAP net investment income and net realized gain and actual distributions (505-946-50-6).
- Scope follows the Overall Investment Companies Subtopic scope in Section 946-10-15 (505-946-15-1); Section 55 illustrates the record-share, actual-income-available, and simultaneous-equations methods for calculating distributions from net investment income.
For students. Mutual fund financial statements live or die on the statement of changes in net assets; know that share-transaction detail (sold, reinvested, reacquired, net change) is required class-by-class. A common misunderstanding is assuming return of capital and distributable earnings are computed per class — under 505-946-50-4 they are fund-level determinations only.
Machine-generated study aid for ASC 505-946. Check the source paragraphs below.
505-946-05Overview and Background
Source downloaded: .Record version 0c1a27a32e09. Effective date must be checked in the source.
505-946-15Scope and Scope Exceptions
Source downloaded: .Record version c01fe4341005. Effective date must be checked in the source.
Overall Guidance
505-946-50Disclosure
Source downloaded: .Record version ce6abab83795. Effective date must be checked in the source.
Net Asset Value per Share
Capital Share Transactions
- aThe number and value of shares sold
- bThe number and value of shares issued in reinvestment of distributions
- cThe number and cost of shares reacquired
- dThe net change.
Capital Contributions
Multiple-Class Funds
Dividends Paid
- aOrdinary income distributions
- bLong-term capital gains distributions
- cReturn of capital distributions.
Difference Between Net Investment Income and Net Realized Gain and Actual Distributions
505-946-55Implementation Guidance and Illustrations
Source downloaded: .Record version 6501d7fd0319. Effective date must be checked in the source.
Illustrations
-
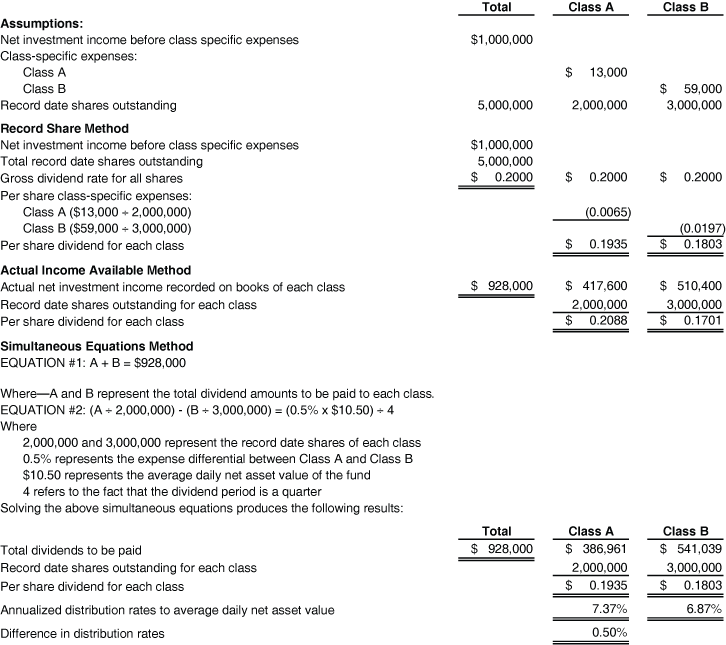 Total Class A Class B Assumptions: Net investment income before class specific expenses " $1,000,000 " Class-specific expenses: Class A " $13,000 " Class B " $59,000 " Record date shares outstanding " 5,000,000 " " 2,000,000 " " 3,000,000 " Record Share Method Net investment income before class specific expenses " $1,000,000 " Total record date shares outstanding " 5,000,000 " Gross dividend rate for all shares $0.2000 $0.2000 $0.2000 Per share class-specific expenses: "Class A ($13,000 ÷ 2,000,000)" (0.0065) "Class B ($59,000 ÷ 3,000,000)" (0.0197) Per share dividend for each class $0.1935 $0.1803 Actual Income Available Method Actual net investment income recorded on books of each class " $928,000 " " $417,600 " " $510,400 " Record date shares outstanding for each class " 2,000,000 " " 3,000,000 " Per share dividend for each class $0.2088 $0.1701 Simultaneous Equations Method "EQUATION #1: A + B = $928,000" Where—A and B represent the total dividend amounts to be paid to each class. "EQUATION #2: (A ÷ 2,000,000) - (B ÷ 3,000,000) = (0.5% x $10.50) ÷ 4" Where "2,000,000 and 3,000,000 represent the record date shares of each class" 0.5% represents the expense differential between Class A and Class B $10.50 represents the average daily net asset value of the fund 4 refers to the fact that the dividend period is a quarter Solving the above simultaneous equations produces the following results: Total Class A Class B Total dividends to be paid " $928,000 " " $386,961 " " $541,039 " Record date shares outstanding for each class " 2,000,000 " " 3,000,000 " Per share dividend for each class $0.1935 $0.1803 Annualized distribution rates to average daily net asset value 7.37% 6.87% Difference in distribution rates 0.50%
505-946-S50DisclosureSEC
Source downloaded: .Record version a3e0ff49ea3b. Effective date must be checked in the source.
Issuance and Repurchase by a Registered Investment Company of Its Own Securities
Related subtopics
- 235-946 Financial Services—Investment CompaniesNotes to Financial Statements
- 220-946 Financial Services—Investment CompaniesIncome Statement—Reporting Comprehensive Income
- 946-20 Investment Company ActivitiesFinancial Services—Investment Companies
- 321-10 OverallInvestments—Equity Securities
- 210-942 Financial Services—Depository and LendingBalance Sheet
- 321-958 Not-for-Profit EntitiesInvestments—Equity Securities