ASC 235-946
Financial Services—Investment Companies
235 Notes to Financial Statements
Source downloaded: .Record version 27f989a5dfdd. Effective date must be checked in the source.
This Subtopic sets the note disclosure requirements for investment companies with complex capital structures — multiple-class funds, master-feeder arrangements, and funds of funds. Multiple-class funds must describe each class, the income/expense and gain/loss allocation method, class-specific fee arrangements, capital share transactions by class, and sales charges paid to affiliates. Feeder funds must describe the master-feeder structure, their percentage ownership of the master, and the master's accounting policies affecting them, while funds of funds must describe the structure and the valuation policy based on investee-reported values.
Key points (7)
- Management investment companies with multiple classes of shares or master-feeder structures apply this disclosure guidance (235-946-50-1).
- Multiple-class funds must disclose a description of each class (sales charges, shareholder servicing fees, distribution fees), the allocation method for income, expenses, and realized/unrealized gains and losses, class-specific distribution plan and affiliate expense arrangements, capital share transactions by class if not shown in the statement of changes in net assets, and total sales charges paid to affiliates by class (235-946-50-2).
- Each feeder fund's notes must give a general description of the master-feeder structure, its percentage ownership of the master at the reporting date, a statement that it invests all investable assets in a corresponding open-end management investment company with the same investment objectives, and a reference to the master's financial statements including the portfolio of investments (235-946-50-3).
- Feeder fund notes must disclose or reference the master fund's accounting policies that affect feeders, such as valuation of the master's investments (235-946-50-3(d)).
- Information on purchases and sales of investments and gross unrealized appreciation/depreciation on a tax basis is not applicable to a feeder's financial statements (235-946-50-3).
- Fund management must consider whether and to what extent disclosure of investee funds' investment policies is appropriate (235-946-50-4).
- A fund of funds must disclose a general description of the fund of funds structure and its valuation policy, noting that values are generally based on information reported by the investee funds (235-946-50-5).
For students. These disclosures are how readers of a fund's financials figure out which economics belong to which share class or to the master versus the feeder; a common misunderstanding is assuming a feeder must present its own portfolio of investments and tax-basis appreciation data, when the guidance instead directs a reference to the master's statements.
Machine-generated study aid for ASC 235-946. Check the source paragraphs below.
235-946-05Overview and Background
Source downloaded: .Record version 150a2e597752. Effective date must be checked in the source.
235-946-15Scope and Scope Exceptions
Source downloaded: .Record version 281f6474773d. Effective date must be checked in the source.
Overall Guidance
235-946-50Disclosure
Source downloaded: .Record version 09ba71ef030b. Effective date must be checked in the source.
Complex Capital Structures
- aDescription of each class of shares, including sales charges, shareholder servicing fees, and distribution fees
- bDisclosure of the method used to allocate income and expenses, and realized and unrealized capital gains and losses, to each class
- cDescription of fee arrangements for class-specific distribution plans and for any other class-level expenses paid to affiliates
- dDisclosure of capital share transactions (if not disclosed separately in the statement of changes in net assets) for each class
- eDisclosure of total sales charges paid to any affiliates for each class.
- aA general description of the master and feeder structure
- bThe feeder's percentage ownership share of the particular master fund at the reporting date
- cA statement that the feeder invests all of its investable assets in a corresponding open-end management investment company having the same investment objectives as the feeder, and a reference to the financial statements of the master fund, including the portfolio of investments
- dDisclosure of or reference to the accounting policies of the master fund that affect the feeders (such as valuation of investments of the master fund).
- aA general description of the fund of funds structure
- bDisclosure of valuation policy-values generally based on information reported by investee funds.
235-946-S00StatusSEC
Source downloaded: .Record version aa8d3281c5c3. Effective date must be checked in the source.
| Paragraph | Action | Accounting Standards Update | Date |
| Amended | Accounting Standards Update No. 2019-07 | 07/26/2019 |
235-946-S50DisclosureSEC
Source downloaded: .Record version a0ccaafa97c3. Effective date must be checked in the source.
Qualified Assets
Restricted Securities
Supplemental Schedules
235-946-S99SEC MaterialsSEC
Source downloaded: .Record version 9ff4fbc0f013. Effective date must be checked in the source.
SEC Rules, Regulations, and Interpretations
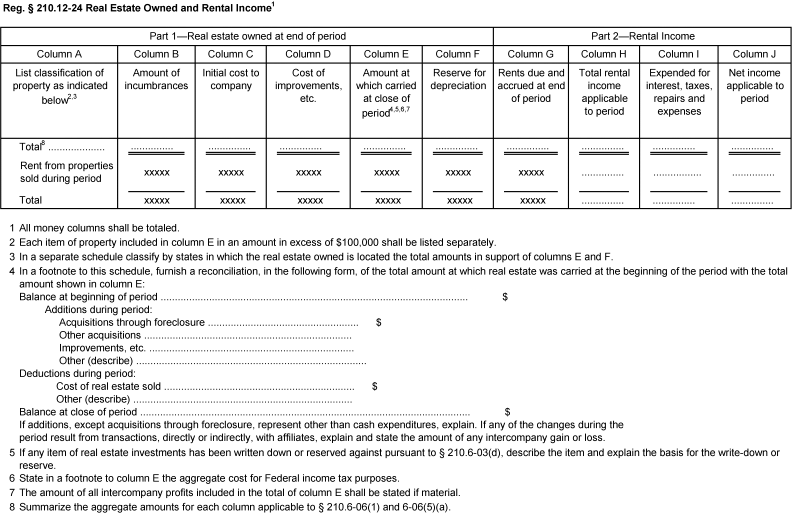 Reg. § 210.12-24 Real Estate Owned and Rental Income1 Part 1—Real estate owned at end of period Part 2—Rental Income Column A Column B Column C Column D Column E Column F Column G Column H Column I Column J "List classification of property as indicated below2,3 " Amount of incumbrances Initial cost to company "Cost of improvements, etc. " "Amount at which carried at close of period4,5,6,7 " Reserve for depreciation Rents due and accrued at end of period "Total rental income applicable to period " "Expended for interest, taxes, repairs and expenses " Net income applicable to period Total8 .................... ............... ............... ............... ............... ............... ............... ............... ............... ............... Rent from properties sold during period xxxxx xxxxx xxxxx xxxxx xxxxx xxxxx ............... ................. ............... Total xxxxx xxxxx xxxxx xxxxx xxxxx xxxxx ............... ............... ............... 1 All money columns shall be totaled. 2 "Each item of property included in column E in an amount in excess of $100,000 shall be listed separately." 3 In a separate schedule classify by states in which the real estate owned is located the total amounts in support of columns E and F. 4 "In a footnote to this schedule, furnish a reconciliation, in the following form, of the total amount at which real estate was carried at the beginning of the period with the total amount shown in column E: Balance at beginning of period ............................................................................................................ $ Additions during period: Acquisitions through foreclosure ..................................................... $ Other acquisitions ......................................................................... Improvements, etc. ........................................................................ Other (describe) ................................................................................. Deductions during period: Cost of real estate sold ................................................................... $ Other (describe) ............................................................................. Balance at close of period .................................................................................................................... $ If additions, except acquisitions through foreclosure, represent other than cash expenditures, explain. If any of the changes during the period result from transactions, directly or indirectly, with affiliates, explain and state the amount of any intercompany gain or loss." 5 "If any item of real estate investments has been written down or reserved against pursuant to § 210.6-03(d), describe the item and explain the basis for the write-down or reserve." 6 State in a footnote to column E the aggregate cost for Federal income tax purposes. 7 The amount of all intercompany profits included in the total of column E shall be stated if material. 8 Summarize the aggregate amounts for each column applicable to § 210.6-06(1) and 6-06(5)(a).
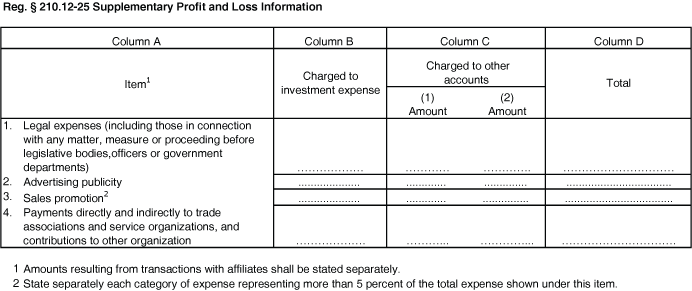 Reg. § 210.12-25 Supplementary Profit and Loss Information Column A Column B Column C Column D Item1 Charged to investment expense " Charged to other accounts" Total "(1) Amount" "(2) Amount" 1. "Legal expenses (including those in connection with any matter, measure or proceeding before legislative bodies,officers or government departments)" ……………… ………… …………. ………………………… 2. Advertising publicity .................... ............. .............. .................................. 3. Sales promotion2 .................... ............. ............... ................................... 4. "Payments directly and indirectly to trade associations and service organizations, and contributions to other organization" ………………. ………... …………... …………………………. 1 Amounts resulting from transactions with affiliates shall be stated separately. 2 State separately each category of expense representing more than 5 percent of the total expense shown under this item.
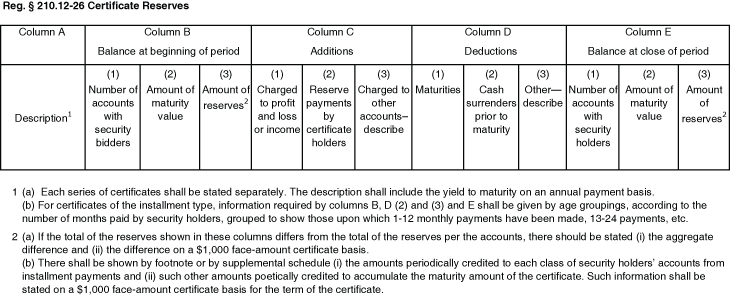 Reg. § 210.12-26 Certificate Reserves Column A Column B Column C Column D Column E Balance at beginning of period Additions Deductions Balance at close of period Description1 (1) (2) (3) (1) (2) (3) (1) (2) (3) (1) (2) (3) Number of accounts with security bidders Amount of maturity value Amount of reserves2 Charged to profit and loss or income Reserve payments by certificate holders Charged to other accounts-describe Maturities Cash surrenders prior to maturity "Other— describe" Number of accounts with security holders Amount of maturity value Amount of reserves2 1 "(a) Each series of certificates shall be stated separately. The description shall include the yield to maturity on an annual payment basis. (b) For certificates of the installment type, information required by columns B, D (2) and (3) and E shall be given by age groupings, according to the number of months paid by security holders, grouped to show those upon which 1-12 monthly payments have been made, 13-24 payments, etc." 2 "(a) If the total of the reserves shown in these columns differs from the total of the reserves per the accounts, there should be stated (i) the aggregate difference and (ii) the difference on a $1,000 face-amount certificate basis. (b) There shall be shown by footnote or by supplemental schedule (i) the amounts periodically credited to each class of security holders' accounts from installment payments and (ii) such other amounts poetically credited to accumulate the maturity amount of the certificate. Such information shall be stated on a $1,000 face-amount certificate basis for the term of the certificate."
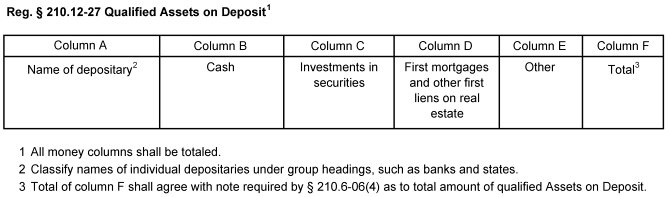 Reg. § 210.12-27 Qualified Assets on Deposit1 Column A Column B Column C Column D Column E Column F Name of depositary2 Cash Investments in securities First mortgages and other first liens on real estate Other Total3 1 All money columns shall be totaled. 2 "Classify names of individual depositaries under group headings, such as banks and states." 3 Total of column F shall agree with note required by § 210.6-06(4) as to total amount of qualified Assets on Deposit.
Related subtopics
- 946-10 OverallFinancial Services—Investment Companies
- 205-946 Financial Services—Investment CompaniesPresentation of Financial Statements
- 220-946 Financial Services—Investment CompaniesIncome Statement—Reporting Comprehensive Income
- 210-942 Financial Services—Depository and LendingBalance Sheet
- 946-20 Investment Company ActivitiesFinancial Services—Investment Companies
- 235-942 Financial Services—Depository and LendingNotes to Financial Statements