ASC 830-10
Overall
830 Foreign Currency Matters
Source downloaded: .Record version df02e5d4ef40. Effective date must be checked in the source.
In brief
IntermediateForeign currencySubsequent measurementConsolidationFinancial statement presentationASC 830-10 sets the scope and foundational framework for foreign currency accounting: it requires each foreign entity's assets, liabilities, and operations to be measured in that entity's functional currency—the currency of the primary economic environment in which it operates (830-10-45-2)—before amounts are translated into the reporting currency. It supplies the economic indicators (cash flow, sales price, sales market, expense, financing, and intra-entity indicators in 830-10-55-5) that management weighs to identify the functional currency, mandates remeasurement of books of record not kept in the functional currency using historical rates for specified nonmonetary items (830-10-45-17 through 45-18), and requires entities in highly inflationary economies (cumulative 3-year inflation ≈100% or more) to be remeasured as if the reporting currency were the functional currency (830-10-45-11).
Key points (7)
- The Topic applies to all entities, to all foreign currency transactions, and to all foreign currency statements incorporated by consolidation, combination, or the equity method; convenience translations for readers are outside its scope (830-10-15-2 through 15-7).
- Translation must both reflect the expected economic effects of rate changes on the reporting entity's cash flows and equity and preserve the results and relationships measured in each entity's functional currency under U.S. GAAP (830-10-10-2).
- The functional currency is the currency of the primary economic environment in which the entity primarily generates and expends cash; it is a matter of fact requiring management judgment weighing cash flow, sales price, sales market, expense, financing, and intra-entity indicators (830-10-45-2, 45-6, 830-10-55-5).
- A single entity with distinct and separable operations in different economic environments may have different functional currencies for each operation (830-10-45-5, 830-10-55-6).
- Once determined, the functional currency is used consistently unless significant changes in economic facts clearly indicate a change; prior financial statements are never restated, and changes to/from the reporting currency follow 830-10-45-9 and 45-10 (830-10-45-7).
- Financial statements of a foreign entity in a highly inflationary economy (cumulative inflation of approximately 100% or more over three years) are remeasured as if the functional currency were the reporting currency (830-10-45-11 through 45-13); when the economy ceases to be highly inflationary, reporting currency amounts are translated at the current rate to establish the new functional currency basis for nonmonetary items (830-10-45-15).
- If books of record are not kept in the functional currency, remeasurement precedes translation: listed nonmonetary items (inventories at cost, PP&E and accumulated depreciation, prepaids, intangibles, goodwill, common stock, related cost of sales, depreciation, amortization) use historical rates, all other items use the current rate, and remeasurement gains and losses on nonfunctional-currency monetary items go to income (830-10-45-17 through 45-18).
For students. Exam questions almost always turn on identifying the functional currency first: get that wrong and every downstream answer (remeasurement gains in income vs. translation adjustments in OCI) is wrong. A common misunderstanding is conflating remeasurement (books not in functional currency; historical rates for nonmonetary items; gains/losses to earnings) with translation into the reporting currency (current rate; adjustment to OCI), and forgetting that a highly inflationary economy forces the reporting currency to be treated as the functional currency.
Machine-generated study aid for ASC 830-10. Check the source paragraphs below.
830-10-00Status
Source downloaded: .Record version e0e0c15e0652. Effective date must be checked in the source.
830-10-05Overview and Background
Source downloaded: .Record version 9829791515c3. Effective date must be checked in the source.
- aOverall
- bForeign Currency Transactions
- cTranslation of Financial Statements
- dStatement of Cash Flows
- eIncome Taxes.
830-10-10Objectives
Source downloaded: .Record version f66fe3d1b82e. Effective date must be checked in the source.
Objectives of Translation
- aProvide information that is generally compatible with the expected economic effects of a rate change on a reporting entity's cash flows and equity
- bReflect in consolidated statements the financial results and relationships of the individual consolidated entities as measured in their functional currencies in conformity with U.S. generally accepted accounting principles (GAAP).
830-10-15Scope and Scope Exceptions
Source downloaded: .Record version 3c1ec5b33c07. Effective date must be checked in the source.
Overall Guidance
Entities
Transactions
Other Considerations
830-10-45Other Presentation Matters
Source downloaded: .Record version 15d325c16a58. Effective date must be checked in the source.
- aThe functional currency
- bThe functional currency in highly inflationary economies
- cRemeasurement of books of record into the functional currency
- d
The Functional Currency
- a In the first class are foreign operations that are relatively self-contained and integrated within a particular country or economic environment. The day-to-day operations are not dependent on the economic environment of the parent's functional currency; the foreign operation primarily generates and expends foreign currency. The foreign currency net cash flows that it generates may be reinvested or converted and distributed to the parent. For this class, the foreign currency is the functional currency.
- b In the second class are foreign operations that are primarily a direct and integral component or extension of the parent entity's operations. Significant assets may be acquired from the parent entity or otherwise by expending dollars and, similarly, the sale of assets may generate dollars that are available to the parent. Financing is primarily by the parent or otherwise from dollar sources. In other words, the day-to-day operations are dependent on the economic environment of the parent's currency, and the changes in the foreign entity's individual assets and liabilities impact directly on the cash flows of the parent entity in the parent's currency. For this class, the dollar is the functional currency.
The Functional Currency in Highly Inflationary Economies
- a The reporting currency amounts at the date of change shall be translated into the local currency at current exchange rates.
- b The translated amounts shall become the new functional currency accounting basis for the nonmonetary assets and liabilities.
Remeasurement of the Books of Record Into the Functional Currency
- a Equity securities without readily determinable fair values accounted for in accordance with paragraph 321-10-35-2. The historical rate to be used shall be the exchange rate as of the later of the acquisition date or the most recent date on which the equity security was adjusted to fair value in accordance with paragraphs , if applicable.
- 1
- 2
- b Inventories carried at cost
- c Prepaid expenses such as insurance, advertising, and rent
- d Property, plant, and equipment
- e Accumulated depreciation on property, plant, and equipment
- f Patents, trademarks, licenses, and formulas
- g Goodwill
- h Other intangible assets
- i Deferred charges and credits, except policy acquisition costs for life insurance companies
- j Deferred income
- k Common stock
- l Preferred stock carried at issuance price
- m Revenues and expenses related to nonmonetary items, for example:
- 1 Cost of goods sold
- 2 Depreciation of property, plant, and equipment
- 3 Amortization of intangible items such as patents, licenses, and so forth
- 4 Amortization of deferred charges or credits except policy acquisition costs for life insurance entities.
- 1
830-10-55Implementation Guidance and Illustrations
Source downloaded: .Record version 03fde39898e1. Effective date must be checked in the source.
Implementation Guidance
- a Cash flow indicators, for example:
- 1 Foreign currency. Cash flows related to the foreign entity's individual assets and liabilities are primarily in the foreign currency and do not directly affect the parent entity's cash flows.
- 2 Parent's currency. Cash flows related to the foreign entity's individual assets and liabilities directly affect the parent's cash flows currently and are readily available for remittance to the parent entity.
- 1
- b Sales price indicators, for example:
- 1 Foreign currency. Sales prices for the foreign entity's products are not primarily responsive on a short-term basis to changes in exchange rates but are determined more by local competition or local government regulation.
- 2 Parent's currency. Sales prices for the foreign entity's products are primarily responsive on a short-term basis to changes in exchange rates; for example, sales prices are determined more by worldwide competition or by international prices.
- 1
- c Sales market indicators, for example:
- 1 Foreign currency. There is an active local sales market for the foreign entity's products, although there also might be significant amounts of exports.
- 2 Parent's currency. The sales market is mostly in the parent's country or sales contracts are denominated in the parent's currency.
- 1
- d Expense indicators, for example:
- 1 Foreign currency. Labor, materials, and other costs for the foreign entity's products or services are primarily local costs, even though there also might be imports from other countries.
- 2 Parent's currency. Labor, materials, and other costs for the foreign entity's products or services continually are primarily costs for components obtained from the country in which the parent entity is located.
- 1
- e Financing indicators, for example:
- 1 Foreign currency. Financing is primarily denominated in foreign currency, and funds generated by the foreign entity's operations are sufficient to service existing and normally expected debt obligations.
- 2 Parent's Currency—Financing is primarily from the parent or other dollar-denominated obligations, or funds generated by the foreign entity's operations are not sufficient to service existing and normally expected debt obligations without the infusion of additional funds from the parent entity. Infusion of additional funds from the parent entity for expansion is not a factor, provided funds generated by the foreign entity's expanded operations are expected to be sufficient to service that additional financing.
- 1
- f Intra-entity transactions and arrangements indicators, for example:
- 1 Foreign currency. There is a low volume of intra-entity transactions and there is not an extensive interrelationship between the operations of the foreign entity and the parent entity. However, the foreign entity's operations may rely on the parent's or affiliates' competitive advantages, such as patents and trademarks.
- 2 Parent's currency. There is a high volume of intra-entity transactions and there is an extensive interrelationship between the operations of the foreign entity and the parent entity. Additionally, the parent's currency generally would be the functional currency if the foreign entity is a device or shell corporation for holding investments, obligations, intangible assets, and so forth, that could readily be carried on the parent's or an affiliate's books.
- 1
Illustrations
- aHistorical cost in functional currency exceeds net realizable value in functional currency (Case A)
- 1
- 2
- bNet realizable value in functional currency exceeds historical cost in functional currency (Case B).
- a BR is the currency in which the books of record are maintained.
- b FC is the functional currency.
- c When the rate is BR 1 = FC 2.40, a foreign subsidiary of a U.S. entity purchases a unit of inventory at a cost of BR 500 (measured in functional currency, FC 1,200).
- d At the foreign subsidiary's balance sheet date, the current rate is BR 1 = FC 2.00.
- aThe cumulative 3-year inflation rate exceeds 100 percent (Case A).
- bThe cumulative 3-year inflation rate drops below 100 percent but no evidence suggests that drop is other than temporary (Case B).
- cThe cumulative 3-year inflation rate drops below 100 percent after having spiked above 100 percent (Case C).
-
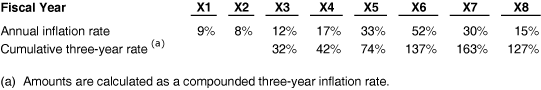 Fiscal Year X1 X2 X3 X4 X5 X6 X7 X8 Annual inflation rate 9% 8% 12% 17% 33% 52% 30% 15% Cumulative three-year rate (a) 32% 42% 74% 137% 163% 127% (a) Amounts are calculated as a compounded three-year inflation rate.
-
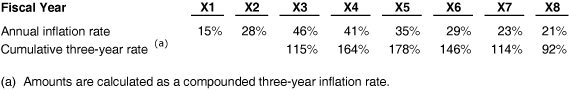 Fiscal Year X1 X2 X3 X4 X5 X6 X7 X8 Annual inflation rate 15% 28% 46% 41% 35% 29% 23% 21% Cumulative three-year rate (a) 115% 164% 178% 146% 114% 92% (a) Amounts are calculated as a compounded three-year inflation rate.
-
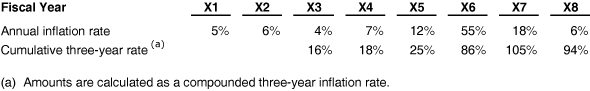 Fiscal Year X1 X2 X3 X4 X5 X6 X7 X8 Annual inflation rate 5% 6% 4% 7% 12% 55% 18% 6% Cumulative three-year rate (a) 16% 18% 25% 86% 105% 94% (a) Amounts are calculated as a compounded three-year inflation rate.
830-10-60Relationships
Source downloaded: .Record version 49a3abff357a. Effective date must be checked in the source.
Income Taxes
Related subtopics
- 830-30 Translation of Financial StatementsForeign Currency Matters
- 740-830 Foreign Currency MattersIncome Taxes
- 830-20 Foreign Currency TransactionsForeign Currency Matters
- 250-10 OverallAccounting Changes and Error Corrections
- 255-10 OverallChanging Prices
- 230-830 Foreign Currency MattersStatement of Cash Flows