ASC 830-946
Financial Services—Investment Companies
830 Foreign Currency Matters
Source downloaded: .Record version ec2c846e11ab. Effective date must be checked in the source.
This Subtopic tells investment companies how to compute and report foreign currency transaction gains and losses on foreign-currency-denominated securities, cash, forward contracts, receivables/payables, income, and expenses. Ongoing revaluation of unsettled foreign-currency items produces unrealized foreign currency gain or loss, which is reclassified to realized gain or loss upon settlement (830-946-45-1). Critically, a fund is permitted—but not required—to separately isolate the foreign currency component of realized and unrealized gains and losses on investments, and it must disclose whichever practice it follows (830-946-45-4; 830-946-50-1).
Key points (7)
- Revaluation of investments and unsettled foreign currency receivables/payables is unrealized foreign currency gain or loss; on actual cash settlement it becomes realized gain or loss (830-946-45-1, 45-23).
- Separate reporting of the foreign currency portion of changes in fair value and realized gains on investments is optional, but if elected must follow this Subtopic's formulas, and the entity must disclose its inclusion/exclusion practice (830-946-45-4, 45-36, 830-946-50-1).
- If separate reporting is elected: (fair value in FC − cost in FC) × valuation-date spot rate = unrealized fair value appreciation/depreciation, and (cost in FC × valuation-date spot rate) − cost in functional currency = unrealized foreign currency gain or loss; substitute sale proceeds and sale trade date for sales (830-946-45-17, 45-20).
- Foreign currency cash is treated like a security: receipts are recorded at the receipt-date spot rate (no gain or loss on acquisition), disbursements release cost (specific identification, FIFO, or average) and produce realized foreign currency gain or loss, with balances retranslated each valuation date (830-946-45-7 through 45-9).
- Forward exchange contracts are recorded at inception at the forward rate and subsequently measured at fair value daily, with unrealized gain or loss equal to the difference between the forward-rate value and the original contracted value, reclassified to realized at settlement; a hedged security purchase and its payable are still recorded at the trade-date spot rate (830-946-45-10 through 45-12).
- Interest, discount accretion/premium amortization, dividends (recorded on the ex-date), and expenses are accrued daily in the foreign currency and translated at daily spot rates (weekly or monthly averages acceptable if rates are not volatile), with the related receivable/payable retranslated daily (830-946-45-25, 45-28, 45-31, 45-35).
- Nonreclaimable withholding tax is accrued with the related income when the rate is fixed and known and shown parenthetically or as a contra item in the income section; reclaimable tax is recorded as a receivable, not an expense (830-946-45-34, 45-39).
For students. Exam questions here hinge on the elective nature of "isolating" the currency component of investment gains—many students wrongly assume separation is mandatory, when the rule is only that the fund disclose which practice it uses. Also remember that acquiring foreign currency never creates a gain or loss; only disbursement (or revaluation) does.
Machine-generated study aid for ASC 830-946. Check the source paragraphs below.
830-946-00Status
Source downloaded: .Record version 186c64721f41. Effective date must be checked in the source.
| Paragraph | Action | Accounting Standards Update | Date |
| Spot Rate | Added | Accounting Standards Update No. 2014-06 | 03/14/2014 |
| 946-830-05-2 | Amended | Accounting Standards Update No. 2012-04 | 10/01/2012 |
| 946-830-45-4 | Amended | Accounting Standards Update No. 2012-04 | 10/01/2012 |
| 946-830-45-7 | Amended | Accounting Standards Update No. 2014-06 | 03/14/2014 |
| 946-830-45-10 | Amended | Accounting Standards Update No. 2012-04 | 10/01/2012 |
| Amended | Accounting Standards Update No. 2012-04 | 10/01/2012 | |
| 946-830-45-19 | Amended | Accounting Standards Update No. 2012-04 | 10/01/2012 |
| 946-830-45-20 | Amended | Accounting Standards Update No. 2012-04 | 10/01/2012 |
| 946-830-50-2 | Amended | Accounting Standards Update No. 2012-04 | 10/01/2012 |
| 946-830-55-4 | Amended | Accounting Standards Update No. 2012-04 | 10/01/2012 |
| 946-830-55-7 | Amended | Accounting Standards Update No. 2012-04 | 10/01/2012 |
| 946-830-55-8 | Amended | Accounting Standards Update No. 2012-04 | 10/01/2012 |
| 946-830-55-13 | Amended | Accounting Standards Update No. 2012-04 | 10/01/2012 |
830-946-05Overview and Background
Source downloaded: .Record version add4678deb34. Effective date must be checked in the source.
- aInvest in securities denominated or expected to settle in currencies other than the U.S. dollar
- bInvest in currencies other than the U.S. dollar
- cHave foreign currency transactions.
- aThe cost of securities held versus their carrying value based on current exchange rates
- bPayables or receivables for securities bought or sold at the transaction date versus actual amounts at settlement date or payable or receivable based on current exchange rates
- cInterest, dividends, and withholding taxes accrued versus the amount received or receivable based on current exchange rates
- dExpenses accrued versus the amount paid or payable in foreign currency, based on current exchange rates
- eForward exchange contracts or foreign exchange futures contracts subsequently measured at fair value.
Withholding Tax
830-946-15Scope and Scope Exceptions
Source downloaded: .Record version 95384cda2b9d. Effective date must be checked in the source.
Overall Guidance
830-946-45Other Presentation Matters
Source downloaded: .Record version 197a9593e893. Effective date must be checked in the source.
Overall Guidance
- a Foreign exchange rate changes
- b Changes in market prices.
- aCash
- bDerivative instruments—forward exchange contracts
- cSecurities
- dReceivables and payables
- eIncome
- fExpenses
- gFinancial statement presentation.
Cash
Derivative Instruments—Forward Exchange Contracts
Securities
- aPurchased interest
- bSubsequently measuring at fair value
- cSale of securities
- dSale of interest.
- a Changes in the fair value of securities before translation
- b Movement in foreign currency rate.
- a (Fair value in foreign currency - original cost in foreign currency) x valuation date spot rate = unrealized fair value appreciation or depreciation.
- b (Cost in foreign currency times valuation date spot rate) - cost in functional currency = the unrealized foreign currency gain or loss.
- a Be a departure from the method required for federal income tax reporting for realized foreign currency gains or losses on debt securities
- b Represent a departure from the practice of those investment companies that presently separately report in their financial statements the effects of foreign exchange on securities gains or losses.
- a (Sale proceeds in foreign currency - original cost in foreign currency) x sale trade date spot rate = realized fair value gain or loss on sale of security.
- b (Cost in foreign currency x sale trade date spot rate) - cost in functional currency = realized foreign currency gain or loss.
Receivables and Payables
Income
- aInterest
- bAccretion and amortization
- cDividends
- dWithholding tax.
Expenses
Financial Statement Presentation
- a The combination of the net realized gains or losses from investments with net realized gains or losses from foreign currency transactions
- b The combination of the net unrealized appreciation (depreciation) on investments with the net unrealized appreciation (depreciation) on translation of assets and liabilities in foreign currencies.
-
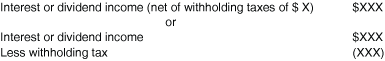 Interest or dividend income (net of withholding taxes of $ X) $XXX or Interest or dividend income $XXX Less withholding tax (XXX)
830-946-50Disclosure
Source downloaded: .Record version ee9b31bdc450. Effective date must be checked in the source.
- aLiquidity. Because certain foreign markets are illiquid, market prices may not necessarily represent fair value.
- bSize. If market capitalization is low, a fund's share in the entire market (particularly if single-country funds are involved) or in specific securities may be proportionately very large, and the fair value, consistent with Topic 820, may not be representative of the price that would be received if the fund sold its large proportion of the specific security ("block") at the measurement date.
- cValuation. Because of liquidity problems as well as other factors, such as securities that are unlisted or securities that are traded in inactive markets, funds are required to develop procedures consistent with Topic 820 for measuring the fair values of such securities. Doing so may be difficult in a foreign environment; while others may perform the research and provide supporting documentation for fair values, the ultimate responsibility for determining the fair values of securities rests with the management.
830-946-55Implementation Guidance and Illustrations
Source downloaded: .Record version 3f8e0f9d2e8f. Effective date must be checked in the source.
Illustrations
-
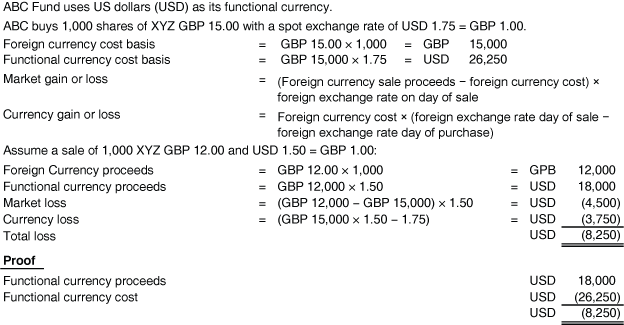 ABC Fund uses US dollars (USD) as its functional currency. "ABC buys 1,000 shares of XYZ GBP 15.00 with a spot exchange rate of USD 1.75 = GBP 1.00." Foreign currency cost basis = " GBP 15.00 × 1,000 " = GBP " 15,000 " Functional currency cost basis = " GBP 15,000 × 1.75 " = USD " 26,250 " Market gain or loss = (Foreign currency sale proceeds − foreign currency cost) × foreign exchange rate on day of sale Currency gain or loss = Foreign currency cost × (foreign exchange rate day of sale − foreign exchange rate day of purchase) "Assume a sale of 1,000 XYZ GBP 12.00 and USD 1.50 = GBP 1.00:" Foreign Currency proceeds = "GBP 12.00 × 1,000" = GPB " 12,000 " Functional currency proceeds = "GBP 12,000 × 1.50" = USD " 18,000 " Market loss = "(GBP 12,000 − GBP 15,000) × 1.50" = USD " (4,500)" Currency loss = "(GBP 15,000 × 1.50 − 1.75)" = USD " (3,750)" Total loss USD " (8,250)" Proof Functional currency proceeds USD " 18,000 " Functional currency cost USD " (26,250)" USD " (8,250)"
-
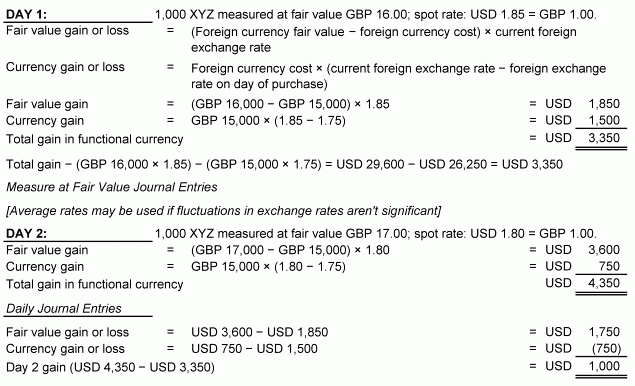 DAY 1: "1,000 XYZ measured at fair value GBP 16.00; spot rate: USD 1.85 = GBP 1.00." Fair value gain or loss = (Foreign currency fair value − foreign currency cost) × current foreign exchange rate Currency gain or loss = Foreign currency cost × (current foreign exchange rate − foreign exchange rate on day of purchase) Fair value gain = "(GBP 16,000 − GBP 15,000) × 1.85" = USD " 1,850 " Currency gain = "GBP 15,000 × (1.85 − 1.75)" = USD " 1,500 " Total gain in functional currency = USD " 3,350 " "Total gain − (GBP 16,000 × 1.85) − (GBP 15,000 × 1.75) = USD 29,600 − USD 26,250 = USD 3,350" Measure at Fair Value Journal Entries [Average rates may be used if fluctuations in exchange rates aren't significant] DAY 2: "1,000 XYZ measured at fair value GBP 17.00; spot rate: USD 1.80 = GBP 1.00." Fair value gain = "(GBP 17,000 − GBP 15,000) × 1.80" = USD " 3,600 " Currency gain = "GBP 15,000 × (1.80 − 1.75)" = USD 750 Total gain in functional currency USD " 4,350 " Daily Journal Entries Fair value gain or loss = "USD 3,600 − USD 1,850" = USD " 1,750 " Currency gain or loss = "USD 750 − USD 1,500" = USD (750) "Day 2 gain (USD 4,350 − USD 3,350)" = USD " 1,000 "
-
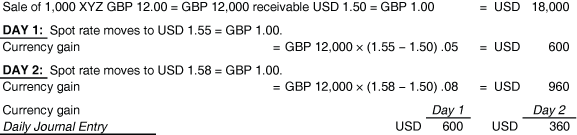 "Sale of 1,000 XYZ GBP 12.00 = GBP 12,000 receivable USD 1.50 = GBP 1.00 " = USD " 18,000 " DAY 1: Spot rate moves to USD 1.55 = GBP 1.00. Currency gain = "GBP 12,000 × (1.55 − 1.50) .05" = USD 600 DAY 2: Spot rate moves to USD 1.58 = GBP 1.00. Currency gain = "GBP 12,000 × (1.58 − 1.50) .08 " = USD 960 Currency gain Day 1 Day 2 Daily Journal Entry USD 600 USD 360
-
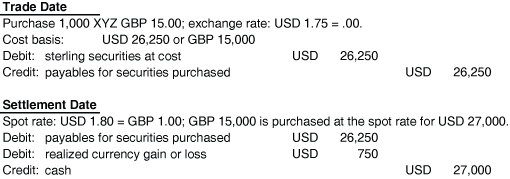 Trade Date "Purchase 1,000 XYZ GBP 15.00; exchange rate: USD 1.75 = .00." Cost basis: "USD 26,250 or GBP 15,000" Debit: sterling securities at cost USD " 26,250 " Credit: payables for securities purchased USD " 26,250 " Settlement Date "Spot rate: USD 1.80 = GBP 1.00; GBP 15,000 is purchased at the spot rate for USD 27,000." Debit: payables for securities purchased USD " 26,250 " Debit: realized currency gain or loss USD 750 Credit: cash USD " 27,000 "
-
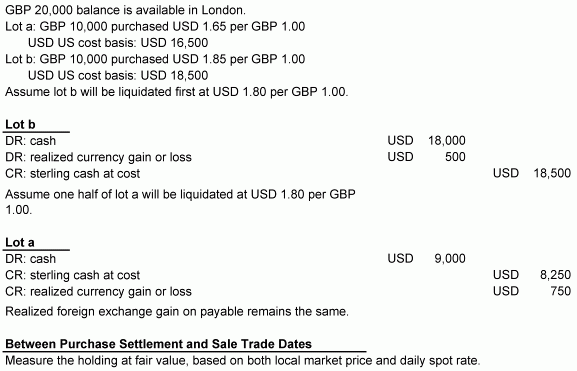 "GBP 20,000 balance is available in London." "Lot a: GBP 10,000 purchased USD 1.65 per GBP 1.00" "USD US cost basis: USD 16,500" "Lot b: GBP 10,000 purchased USD 1.85 per GBP 1.00" "USD US cost basis: USD 18,500" Assume lot b will be liquidated first at USD 1.80 per GBP 1.00. Lot b DR: cash USD " 18,000 " DR: realized currency gain or loss USD 500 CR: sterling cash at cost USD " 18,500 " Assume one half of lot a will be liquidated at USD 1.80 per GBP 1.00. Lot a DR: cash USD " 9,000 " CR: sterling cash at cost USD " 8,250 " CR: realized currency gain or loss USD 750 Realized foreign exchange gain on payable remains the same. Between Purchase Settlement and Sale Trade Dates "Measure the holding at fair value, based on both local market price and daily spot rate."
-
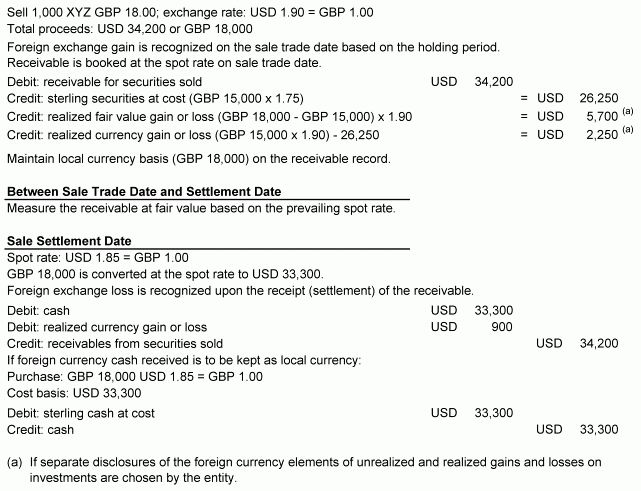 "Sell 1,000 XYZ GBP 18.00; exchange rate: USD 1.90 = GBP 1.00" "Total proceeds: USD 34,200 or GBP 18,000" Foreign exchange gain is recognized on the sale trade date based on the holding period. Receivable is booked at the spot rate on sale trade date. Debit: receivable for securities sold USD " 34,200 " "Credit: sterling securities at cost (GBP 15,000 x 1.75)" = USD " 26,250 " "Credit: realized fair value gain or loss (GBP 18,000 - GBP 15,000) x 1.90" = USD " 5,700 " (a) "Credit: realized currency gain or loss (GBP 15,000 x 1.90) - 26,250" = USD " 2,250 " (a) "Maintain local currency basis (GBP 18,000) on the receivable record." Between Sale Trade Date and Settlement Date Mark the receivable at fair value based on the prevailing spot rate. Sale Settlement Date Spot rate: USD 1.85 = GBP 1.00 "GBP 18,000 is converted at the spot rate to USD 33,300." Foreign exchange loss is recognized upon the receipt (settlement) of the receivable. Debit: cash USD " 33,300 " Debit: realized currency gain or loss USD 900 Credit: receivables from securities sold USD " 34,200 " If foreign currency cash received is to be kept as local currency: "Purchase: GBP 18,000 USD 1.85 = GBP 1.00" "Cost basis: USD 33,300" Debit: sterling cash at cost USD " 33,300 " Credit: cash USD " 33,300 " (a) If separate disclosures of the foreign currency elements of unrealized and realized gains and losses on investments are chosen by the entity.
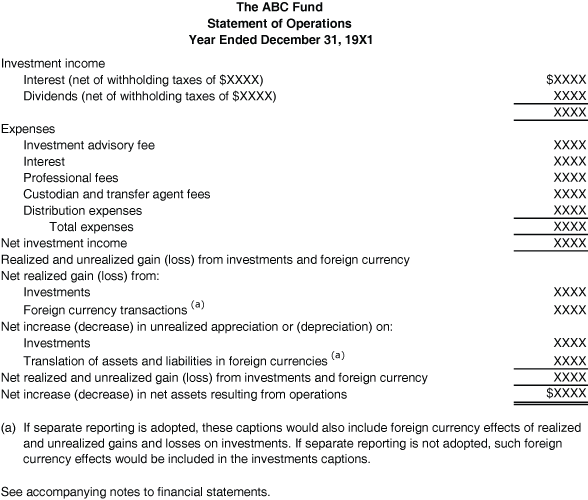 The ABC Fund Statement of Operations "Year Ended December 31, 19X1" Investment income Interest (net of withholding taxes of $XXXX) $XXXX Dividends (net of withholding taxes of $XXXX) XXXX XXXX Expenses Investment advisory fee XXXX Interest XXXX Professional fees XXXX Custodian and transfer agent fees XXXX Distribution expenses XXXX Total expenses XXXX Net investment income XXXX Realized and unrealized gain (loss) from investments and foreign currency Net realized gain (loss) from: Investments XXXX Foreign currency transactions (a) XXXX Net increase (decrease) in unrealized appreciation or (depreciation) on: Investments XXXX Translation of assets and liabilities in foreign currencies (a) XXXX Net realized and unrealized gain (loss) from investments and foreign currency XXXX Net increase (decrease) in net assets resulting from operations $XXXX (a) "If separate reporting is adopted, these captions would also include foreign currency effects of realized and unrealized gains and losses on investments. If separate reporting is not adopted, such foreign currency effects would be included in the investments captions." See accompanying notes to financial statements.
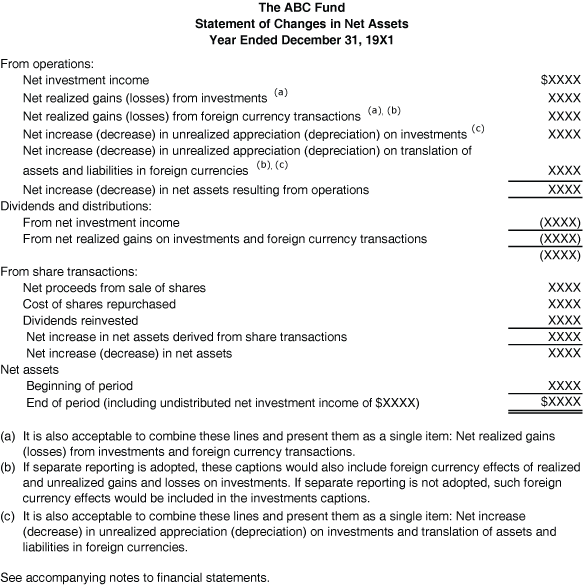 "The ABC Fund " Statement of Changes in Net Assets "Year Ended December 31, 19X1" From operations: Net investment income $XXXX Net realized gains (losses) from investments (a) XXXX "Net realized gains (losses) from foreign currency transactions (a), (b)" XXXX Net increase (decrease) in unrealized appreciation (depreciation) on investments (c) XXXX "Net increase (decrease) in unrealized appreciation (depreciation) on translation of assets and liabilities in foreign currencies (b), (c)" XXXX Net increase (decrease) in net assets resulting from operations XXXX Dividends and distributions: From net investment income (XXXX) From net realized gains on investments and foreign currency transactions (XXXX) (XXXX) From share transactions: Net proceeds from sale of shares XXXX Cost of shares repurchased XXXX Dividends reinvested XXXX Net increase in net assets derived from share transactions XXXX Net increase (decrease) in net assets XXXX Net assets Beginning of period XXXX End of period (including undistributed net investment income of $XXXX) $XXXX (a) It is also acceptable to combine these lines and present them as a single item: Net realized gains (losses) from investments and foreign currency transactions. (b) "If separate reporting is adopted, these captions would also include foreign currency effects of realized and unrealized gains and losses on investments. If separate reporting is not adopted, such foreign currency effects would be included in the investments captions." (c) It is also acceptable to combine these lines and present them as a single item: Net increase (decrease) in unrealized appreciation (depreciation) on investments and translation of assets and liabilities in foreign currencies. See accompanying notes to financial statements.
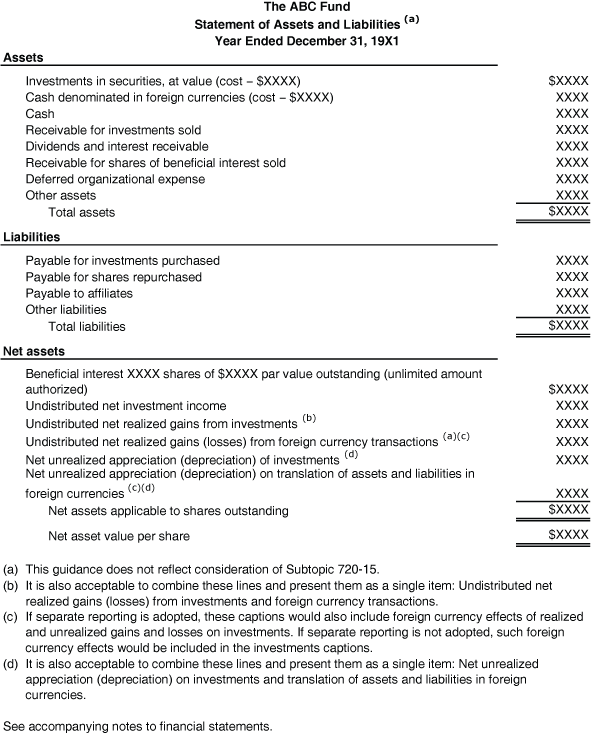 The ABC Fund Statement of Assets and Liabilities (a) "Year Ended December 31, 19X1" Assets "Investments in securities, at value (cost − $XXXX)" $XXXX Cash denominated in foreign currencies (cost − $XXXX) XXXX Cash XXXX Receivable for investments sold XXXX Dividends and interest receivable XXXX Receivable for shares of beneficial interest sold XXXX Deferred organizational expense XXXX Other assets XXXX Total assets $XXXX Liabilities Payable for investments purchased XXXX Payable for shares repurchased XXXX Payable to affiliates XXXX Other liabilities XXXX Total liabilities $XXXX Net assets Beneficial interest XXXX shares of $XXXX par value outstanding (unlimited amount authorized) $XXXX Undistributed net investment income XXXX Undistributed net realized gains from investments (b) XXXX Undistributed net realized gains (losses) from foreign currency transactions (a)(c) XXXX Net unrealized appreciation (depreciation) of investments (d) XXXX Net unrealized appreciation (depreciation) on translation of assets and liabilities in foreign currencies (c)(d) XXXX Net assets applicable to shares outstanding $XXXX Net asset value per share $XXXX (a) This guidance does not reflect consideration of Subtopic 720-15. (b) It is also acceptable to combine these lines and present them as a single item: Undistributed net realized gains (losses) from investments and foreign currency transactions. (c) "If separate reporting is adopted, these captions would also include foreign currency effects of realized and unrealized gains and losses on investments. If separate reporting is not adopted, such foreign currency effects would be included in the investments captions." (d) It is also acceptable to combine these lines and present them as a single item: Net unrealized appreciation (depreciation) on investments and translation of assets and liabilities in foreign currencies. See accompanying notes to financial statements.
- Foreign Currency. Amounts denominated in or expected to settle in foreign currencies are translated into U.S. dollars at rates reported by a major New York City bank on the following basis:
- aFair value of investment securities, other assets, and liabilities—at the closing rate of exchange at the balance sheet date
- bPurchases and sales of investment securities, income, and expenses—at the rate of exchange prevailing on the respective dates of such transactions (or at an average rate if significant rate fluctuations have not occurred).
- a
- The Fund isolates that portion of the results of operations resulting from changes in foreign exchange rates on investments from the fluctuations arising from changes in market prices of securities held.
- Reported net realized foreign exchange gains or losses arise from sales of portfolio securities, sales and maturities of short-term securities, sales of foreign currencies, currency gains or losses realized between the trade and settlement dates on securities transactions, the difference between the amounts of dividends, interest, and foreign withholding taxes recorded on the Fund's books, and the U.S. dollar equivalent of the amounts actually received or paid. Net unrealized foreign exchange gains and losses arise from changes in the value of assets and liabilities including investments in securities at fiscal year end, resulting from changes in the exchange rate.
- The Fund does not isolate that portion of the results of operations resulting from changes in foreign exchange rates on investments from the fluctuations arising from changes in market prices of securities held. Such fluctuations are included with the net realized and unrealized gain or loss from investments. Reported net realized foreign exchange gains or losses arise from sales and maturities of short-term securities, sales of foreign currencies, currency gains or losses realized between the trade and settlement dates on securities transactions, the difference between the amounts of dividends, interest, and foreign withholding taxes recorded on the Fund's books, and the U.S. dollar equivalent of the amounts actually received or paid. Net unrealized foreign exchange gains and losses arise from changes in the value of assets and liabilities other than investments in securities at fiscal year end, resulting from changes in the exchange rate.
- The Fund has obtained the approval of the Central Bank for the registration and conversion into foreign currency of all proceeds of the offering to be invested in the ABC country securities markets, which by its terms ensures repatriation of such investment and the remittance of profits and dividends accruing on the investment. Notwithstanding the foregoing, the right of the Fund to repatriate its investments in ABC country securities and to receive profits, capital gains, and dividends in foreign exchange is subject to the power of the Central Bank, with the approval of the President of the ABC country, to restrict the availability of foreign exchange in the imminence of, or during, an exchange crisis or in times of national emergency.
- The Fund has significant investments in the equity securities of entities located in the ABC country. Future economic and political developments in the country could adversely affect the liquidity or value, or both, of the ABC country securities in which the Fund is invested.
- There are nationality restrictions on the ownership of certain equity securities of the ABC country entities. Based on confirmations that the Fund received from the ABC country's governmental authorities, the Fund believes that it is permitted to make certain investments through the ABC country's Trust that are otherwise available only to the ABC country.
Related subtopics
- 830-20 Foreign Currency TransactionsForeign Currency Matters
- 830-30 Translation of Financial StatementsForeign Currency Matters
- 220-946 Financial Services—Investment CompaniesIncome Statement—Reporting Comprehensive Income
- 946-20 Investment Company ActivitiesFinancial Services—Investment Companies
- 320-10 OverallInvestments—Debt Securities
- 310-942 Financial Services—Depository and LendingReceivables