ASC 230-830
Foreign Currency Matters
230 Statement of Cash Flows
Source downloaded: .Record version fd836a241c29. Effective date must be checked in the source.
This subtopic tells an entity with foreign currency transactions or foreign operations how to translate cash flows in the statement of cash flows. Foreign currency cash flows are reported at the reporting currency equivalent using the exchange rates in effect at the time of the cash flows (a weighted-average rate may be used if the result is substantially the same). The effect of exchange rate changes on cash, cash equivalents, and restricted cash held in foreign currencies is shown as a separate part of the reconciliation of the change in total cash for the period.
Key points (6)
- A statement of cash flows of an entity with foreign currency transactions or foreign operations shall report the reporting currency equivalent of foreign currency cash flows using the exchange rates in effect at the time of the cash flows (230-830-45-1).
- An appropriately weighted average exchange rate for the period may be used if the result is substantially the same as using the rates at the dates of the cash flows; 830-30-45-3 applies to cash receipts and payments (230-830-45-1).
- The effect of exchange rate changes on cash, cash equivalents, and amounts generally described as restricted cash or restricted cash equivalents held in foreign currencies is reported as a separate part of the reconciliation of the change in the total of those amounts during the period (230-830-45-1).
- The exchange rate effect line is not classified as an operating, investing, or financing activity; it reconciles the change in total cash.
- The Subtopic follows the same scope and scope exceptions as Section 830-10-15 (230-830-15-1).
- Example 1 (830-230-55-1 through 55-15) illustrates a direct-method consolidating statement of cash flows for a U.S. parent with one subsidiary whose local currency is the functional currency and one in a highly inflationary economy whose functional currency is the U.S. dollar.
For students. Exam questions often test that the exchange-rate effect on foreign-currency cash balances is a separate reconciling item, not an operating, investing, or financing cash flow. A common misunderstanding is translating foreign cash flows at the year-end (current) rate; the rule is the rate at the date of the cash flow, with a weighted average allowed only as an approximation.
Machine-generated study aid for ASC 230-830. Check the source paragraphs below.
230-830-00Status
Source downloaded: .Record version dcb58f2d86ce. Effective date must be checked in the source.
| Paragraph | Action | Accounting Standards Update | Date |
| Cash Equivalents | Added | Accounting Standards Update No. 2014-06 | 03/14/2014 |
| 830-230-45-1 | Amended | Accounting Standards Update No. 2016-18 | 11/17/2016 |
| 830-230-45-1 | Amended | Accounting Standards Update No. 2014-06 | 03/14/2014 |
| 830-230-55-12 | Amended | Maintenance Update 2018-12 (PDF) | 09/10/2018 |
230-830-05Overview and Background
Source downloaded: .Record version ff66d31dea3f. Effective date must be checked in the source.
230-830-15Scope and Scope Exceptions
Source downloaded: .Record version db2f44423b30. Effective date must be checked in the source.
Overall Guidance
230-830-45Other Presentation Matters
Source downloaded: .Record version 95f024146277. Effective date must be checked in the source.
230-830-55Implementation Guidance and Illustrations
Source downloaded: .Record version bcf7a8ecda62. Effective date must be checked in the source.
Illustrations
-
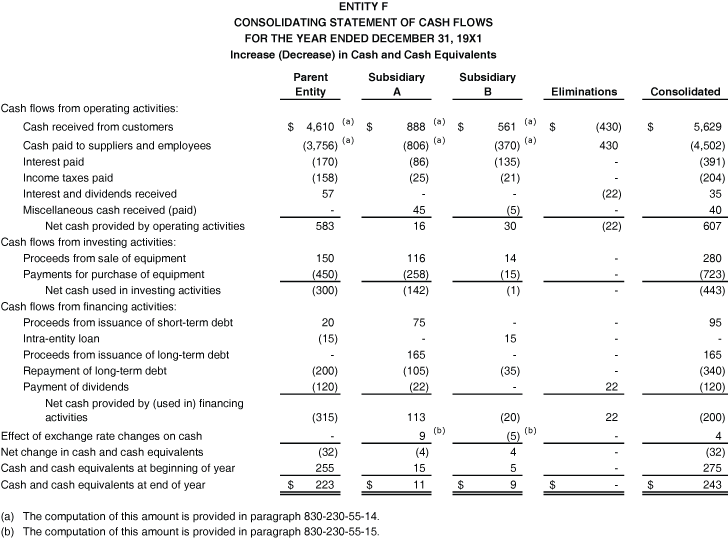 ENTITY F CONSOLIDATING STATEMENT OF CASH FLOWS "FOR THE YEAR ENDED DECEMBER 31, 19X1" Increase (Decrease) in Cash and Cash Equivalents Parent Entity Subsidiary A Subsidiary B Eliminations Consolidated Cash flows from operating activities: Cash received from customers " $4,610 " (a) $888 (a) $561 (a) $(430) " $5,629 " Cash paid to suppliers and employees " (3,756)" (a) (806) (a) (370) (a) 430 " (4,502)" Interest paid (170) (86) (135) - (391) Income taxes paid (158) (25) (21) - (204) Interest and dividends received 57 - - (22) 35 Miscellaneous cash received (paid) - 45 (5) - 40 Net cash provided by operating activities 583 16 30 (22) 607 Cash flows from investing activities: Proceeds from sale of equipment 150 116 14 - 280 Payments for purchase of equipment (450) (258) (15) - (723) Net cash used in investing activities (300) (142) (1) - (443) Cash flows from financing activities: Proceeds from issuance of short-term debt 20 75 - - 95 Intra-entity loan (15) - 15 - - Proceeds from issuance of long-term debt - 165 - - 165 Repayment of long-term debt (200) (105) (35) - (340) Payment of dividends (120) (22) - 22 (120) Net cash provided by (used in) financing activities (315) 113 (20) 22 (200) Effect of exchange rate changes on cash - 9 (b) (5) (b) - 4 Net change in cash and cash equivalents (32) (4) 4 - (32) Cash and cash equivalents at beginning of year 255 15 5 - 275 Cash and cash equivalents at end of year $223 $11 $9 $- $243 (a) The computation of this amount is provided in paragraph 830-230-55-14. (b) The computation of this amount is provided in paragraph 830-230-55-15.
-
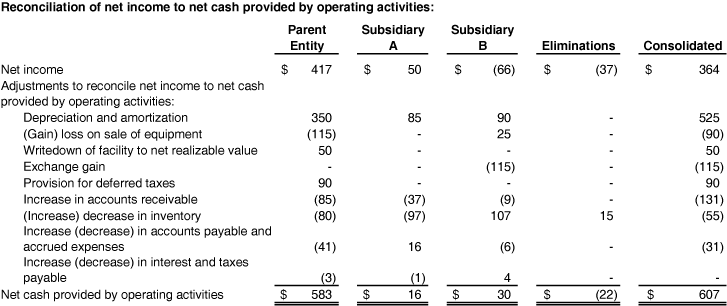 Reconciliation of net income to net cash provided by operating activities: Parent Entity Subsidiary A Subsidiary B Eliminations Consolidated Net income $417 $50 $(66) $(37) $364 Adjustments to reconcile net income to net cash provided by operating activities: Depreciation and amortization 350 85 90 - 525 (Gain) loss on sale of equipment (115) - 25 - (90) Writedown of facility to net realizable value 50 - - - 50 Exchange gain - - (115) - (115) Provision for deferred taxes 90 - - - 90 Increase in accounts receivable (85) (37) (9) - (131) (Increase) decrease in inventory (80) (97) 107 15 (55) Increase (decrease) in accounts payable and accrued expenses (41) 16 (6) - (31) Increase (decrease) in interest and taxes payable (3) (1) 4 - - Net cash provided by operating activities $583 $16 $30 $(22) $607
- Cash in excess of daily requirements is invested in marketable securities consisting of U.S. Treasury bills with maturities of three months or less. Such investments are deemed to be cash equivalents for purposes of the statement of cash flows.
-
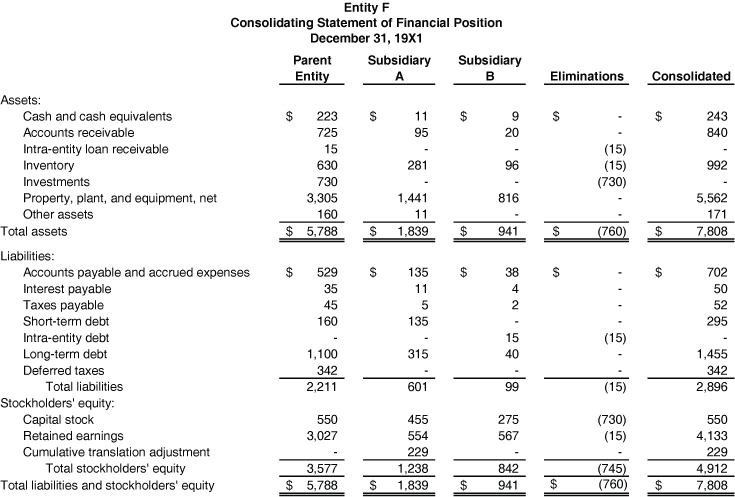 Entity F Consolidating Statement of Financial Position "December 31, 19X1" Parent Entity Subsidiary A Subsidiary B Eliminations Consolidated Assets: Cash and cash equivalents $223 $11 $9 $- $243 Accounts receivable 725 95 20 - 840 Intra-entity loan receivable 15 - - (15) - Inventory 630 281 96 (15) 992 Investments 730 - - (730) - "Property, plant, and equipment, net" " 3,305 " " 1,441 " 816 - " 5,562 " Other assets 160 11 - - 171 Total assets " $5,788 " " $1,839 " $941 $(760) " $7,808 " Liabilities: Accounts payable and accrued expenses $529 $135 $38 $- $702 Interest payable 35 11 4 - 50 Taxes payable 45 5 2 - 52 Short-term debt 160 135 - - 295 Intra-entity debt - - 15 (15) - Long-term debt " 1,100 " 315 40 - " 1,455 " Deferred taxes 342 - - - 342 Total liabilities " 2,211 " 601 99 (15) " 2,896 " Stockholders' equity: Capital stock 550 455 275 (730) 550 Retained earnings " 3,027 " 554 567 (15) " 4,133 " Cumulative translation adjustment - 229 - - 229 Total stockholders' equity " 3,577 " " 1,238 " 842 (745) " 4,912 " Total liabilities and stockholders' equity " $5,788 " " $1,839 " $941 $(760) " $7,808 "
-
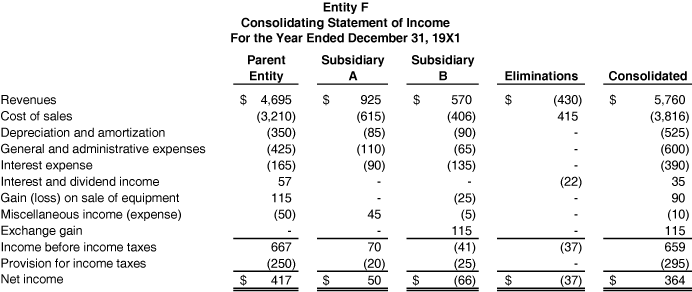 Entity F Consolidating Statement of Income "For the Year Ended December 31, 19X1" Parent Entity Subsidiary A Subsidiary B Eliminations Consolidated Revenues " $4,695 " $925 $570 $(430) " $5,760 " Cost of sales " (3,210)" (615) (406) 415 " (3,816)" Depreciation and amortization (350) (85) (90) - (525) General and administrative expenses (425) (110) (65) - (600) Interest expense (165) (90) (135) - (390) Interest and dividend income 57 - - (22) 35 Gain (loss) on sale of equipment 115 - (25) - 90 Miscellaneous income (expense) (50) 45 (5) - (10) Exchange gain - - 115 - 115 Income before income taxes 667 70 (41) (37) 659 Provision for income taxes (250) (20) (25) - (295) Net income $417 $50 $(66) $(37) $364
-
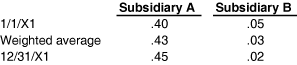 Subsidiary A Subsidiary B 1/1/X1 .40 .05 Weighted average .43 .03 12/31/X1 .45 .02
-
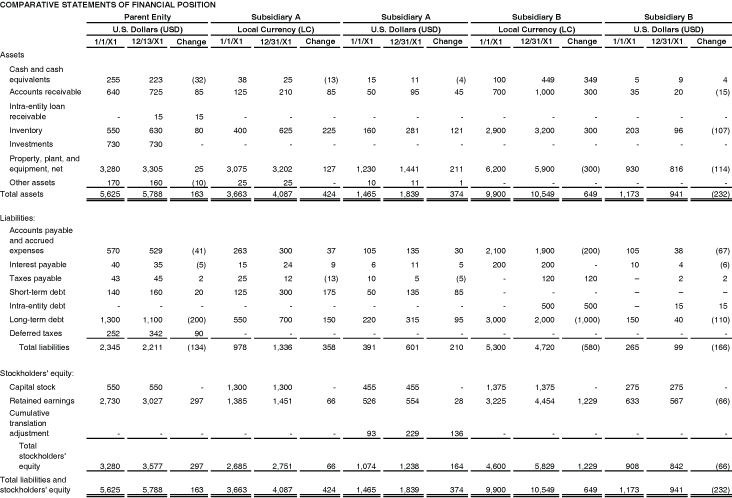 COMPARATIVE STATEMENTS OF FINANCIAL POSITION Parent Enity Subsidiary A Subsidiary A Subsidiary B Subsidiary B U.S. Dollars (USD) Local Currency (LC) U.S. Dollars (USD) Local Currency (LC) U.S. Dollars (USD) 1/1/X1 12/13/X1 Change 1/1/X1 12/31/X1 Change 1/1/X1 12/31/X1 Change 1/1/X1 12/31/X1 Change 1/1/X1 12/31/X1 Change Assets Cash and cash equivalents 255 223 (32) 38 25 (13) 15 11 (4) 100 449 349 5 9 4 Accounts receivable 640 725 85 125 210 85 50 95 45 700 " 1,000 " 300 35 20 (15) Intra-entity loan receivable - 15 15 - - - - - - - - - - - - Inventory 550 630 80 400 625 225 160 281 121 " 2,900 " " 3,200 " 300 203 96 (107) Investments 730 730 - - - - - - - - - - - - - "Property, plant, and equipment, net" " 3,280 " " 3,305 " 25 " 3,075 " " 3,202 " 127 " 1,230 " " 1,441 " 211 " 6,200 " " 5,900 " (300) 930 816 (114) Other assets 170 160 (10) 25 25 - 10 11 1 - - - - - - Total assets " 5,625 " " 5,788 " 163 " 3,663 " " 4,087 " 424 " 1,465 " " 1,839 " 374 " 9,900 " " 10,549 " 649 " 1,173 " 941 (232) Liabilities: Accounts payable and accrued expenses 570 529 (41) 263 300 37 105 135 30 " 2,100 " " 1,900 " (200) 105 38 (67) Interest payable 40 35 (5) 15 24 9 6 11 5 200 200 - 10 4 (6) Taxes payable 43 45 2 25 12 (13) 10 5 (5) - 120 120 - 2 2 Short-term debt 140 160 20 125 300 175 50 135 85 - - - - - - Intra-entity debt - - - - - - - - - - 500 500 - 15 15 Long-term debt " 1,300 " " 1,100 " (200) 550 700 150 220 315 95 " 3,000 " " 2,000 " " (1,000)" 150 40 (110) Deferred taxes 252 342 90 - - - - - - - - - - - - Total liabilities " 2,345 " " 2,211 " (134) 978 " 1,336 " 358 391 601 210 " 5,300 " " 4,720 " (580) 265 99 (166) Stockholders' equity: Capital stock 550 550 - " 1,300 " " 1,300 " - 455 455 - " 1,375 " " 1,375 " - 275 275 - Retained earnings " 2,730 " " 3,027 " 297 " 1,385 " " 1,451 " 66 526 554 28 " 3,225 " " 4,454 " " 1,229 " 633 567 (66) Cumulative translation adjustment - - - - - - 93 229 136 - - - - - - Total stockholders' equity " 3,280 " " 3,577 " 297 " 2,685 " " 2,751 " 66 " 1,074 " " 1,238 " 164 " 4,600 " " 5,829 " " 1,229 " 908 842 (66) Total liabilities and stockholders' equity " 5,625 " " 5,788 " 163 " 3,663 " " 4,087 " 424 " 1,465 " " 1,839 " 374 " 9,900 " " 10,549 " 649 " 1,173 " 941 (232)
-
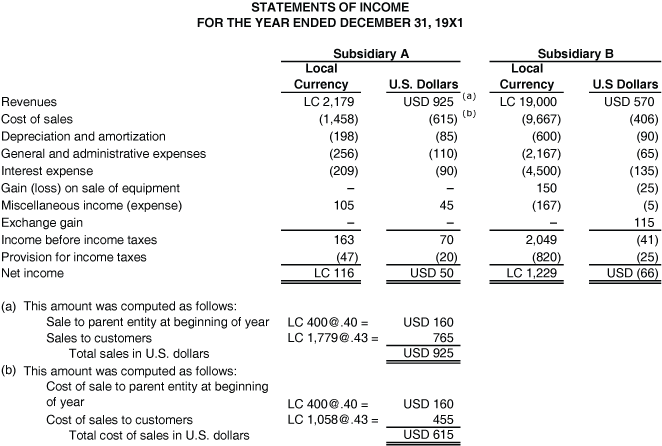 STATEMENTS OF INCOME "FOR THE YEAR ENDED DECEMBER 31, 19X1" Subsidiary A Subsidiary B Local Currency U.S. Dollars Local Currency U.S Dollars Revenues " LC 2,179 " USD 925 (a) " LC 19,000 " USD 570 Cost of sales " (1,458)" (615) (b) " (9,667)" (406) Depreciation and amortization (198) (85) (600) (90) General and administrative expenses (256) (110) " (2,167)" (65) Interest expense (209) (90) " (4,500)" (135) Gain (loss) on sale of equipment - - 150 (25) Miscellaneous income (expense) 105 45 (167) (5) Exchange gain - - - 115 Income before income taxes 163 70 " 2,049 " (41) Provision for income taxes (47) (20) (820) (25) Net income LC 116 USD 50 " LC 1,229 " USD (66) (a) This amount was computed as follows: Sale to parent entity at beginning of year LC 400@.40 = USD 160 Sales to customers " LC 1,779@.43 = " 765 Total sales in U.S. dollars USD 925 (b) This amount was computed as follows: Cost of sale to parent entity at beginning of year LC 400@.40 = USD 160 Cost of sales to customers " LC 1,058@.43 = " 455 Total cost of sales in U.S. dollars USD 615
- a The parent entity invested cash in excess of daily requirements in U.S. Treasury bills. Interest earned on such investments totaled USD 35.
- b The parent entity sold excess property with a net book value of USD 35 for USD 150.
- c The parent entity's capital expenditures totaled USD 450.
- d The parent entity wrote down to its estimated net realizable value of USD 25 a facility with a net book value of USD 75.
- e The parent entity's short-term debt consisted of commercial paper with maturities not exceeding 60 days.
- f The parent entity repaid long-term notes of USD 200.
- g The parent entity's depreciation totaled USD 340, and amortization of intangible assets totaled USD 10.
- h The parent entity's provision for income taxes included deferred taxes of USD 90.
- i Because of a change in product design, the parent entity purchased all of Subsidiary A's beginning inventory for its book value of USD 160. All of the inventory was subsequently sold by the parent entity.
- j The parent entity received a dividend of USD 22 from Subsidiary A. The dividend was credited to the parent entity's income.
- k The parent entity purchased from Subsidiary B USD 270 of merchandise of which USD 45 remained in the parent entity's inventory at year-end. Intra-entity profit on the remaining inventory totaled USD 15.
- l The parent entity loaned USD 15, payable in U.S. dollars, to Subsidiary B.
- m Entity F paid dividends totaling USD 120 to shareholders.
- a Because of a change in product design, Subsidiary A sold all of its beginning inventory to the parent entity for its book value of LC 400 (USD 160).
- b Subsidiary A sold equipment for its book value of LC 275 (USD 116) and purchased new equipment at a cost of LC 600 (USD 258).
- c Subsidiary A issued an additional LC 175 (USD 75) of 30-day notes and renewed the notes at each maturity date.
- d Subsidiary A issued long-term debt of LC 400 (USD 165) and repaid long-term debt of LC 250 (USD 105).
- e Subsidiary A paid a dividend to the parent entity of LC 50 (USD 22).
- a Subsidiary B had sales to the parent entity as follows.
-
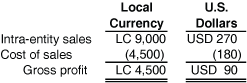 Local Currency U.S. Dollars Intra-entity sales " LC 9,000 " USD 270 Cost of sales " (4,500)" (180) Gross profit " LC 4,500 " USD 90
-
- b Subsidiary B sold equipment with a net book value of LC 200 (USD 39) for LC 350 (USD 14). New equipment was purchased at a cost of LC 500 (USD 15).
- c Subsidiary B borrowed USD 15 (LC 500), payable in U.S. dollars, from the parent entity.
- d Subsidiary B repaid LC 1,000 (USD 35) of long-term debt.
-
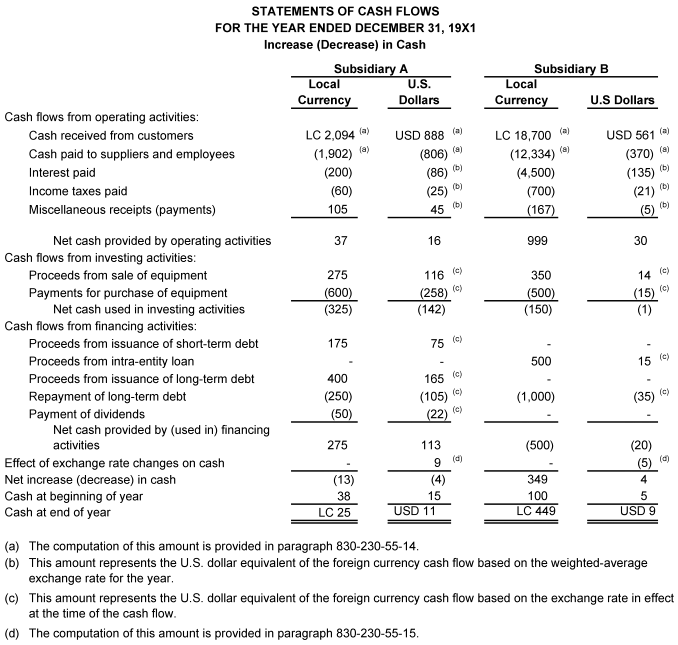 STATEMENTS OF CASH FLOWS "FOR THE YEAR ENDED DECEMBER 31, 19X1" Increase (Decrease) in Cash Subsidiary A Subsidiary B Local Currency U.S. Dollars Local Currency U.S Dollars Cash flows from operating activities: Cash received from customers " LC 2,094 " (a) USD 888 (a) " LC 18,700 " (a) USD 561 (a) Cash paid to suppliers and employees " (1,902)" (a) (806) (a) " (12,334)" (a) (370) (a) Interest paid (200) (86) (b) " (4,500)" (135) (b) Income taxes paid (60) (25) (b) (700) (21) (b) Miscellaneous receipts (payments) 105 45 (b) (167) (5) (b) Net cash provided by operating activities 37 16 999 30 Cash flows from investing activities: Proceeds from sale of equipment 275 116 (c) 350 14 (c) Payments for purchase of equipment (600) (258) (c) (500) (15) (c) Net cash used in investing activities (325) (142) (150) (1) Cash flows from financing activities: Proceeds from issuance of short-term debt 175 75 (c) - - Proceeds from intra-entity loan - - 500 15 (c) Proceeds from issuance of long-term debt 400 165 (c) - - Repayment of long-term debt (250) (105) (c) " (1,000)" (35) (c) Payment of dividends (50) (22) (c) - - Net cash provided by (used in) financing activities 275 113 (500) (20) Effect of exchange rate changes on cash - 9 (d) - (5) (d) Net increase (decrease) in cash (13) (4) 349 4 Cash at beginning of year 38 15 100 5 Cash at end of year LC 25 USD 11 LC 449 USD 9 (a) The computation of this amount is provided in paragraph 830-230-55-14. (b) This amount represents the U.S. dollar equivalent of the foreign currency cash flow based on the weighted-average exchange rate for the year. (c) This amount represents the U.S. dollar equivalent of the foreign currency cash flow based on the exchange rate in effect at the time of the cash flow. (d) The computation of this amount is provided in paragraph 830-230-55-15.
-
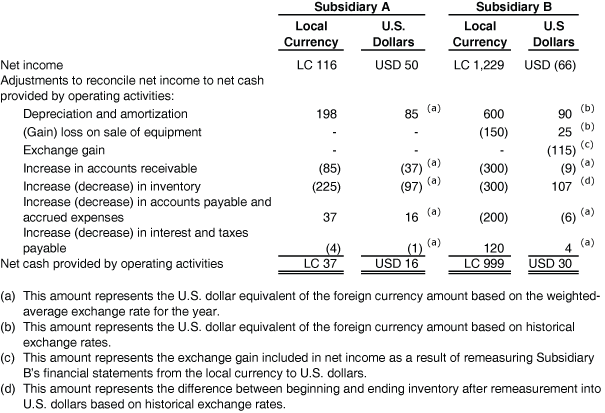 Subsidiary A Subsidiary B Local Currency U.S. Dollars Local Currency U.S Dollars Net income LC 116 USD 50 " LC 1,229 " USD (66) Adjustments to reconcile net income to net cash provided by operating activities: Depreciation and amortization 198 85 (a) 600 90 (b) (Gain) loss on sale of equipment - - (150) 25 (b) Exchange gain - - - (115) (c) Increase in accounts receivable (85) (37) (a) (300) (9) (a) Increase (decrease) in inventory (225) (97) (a) (300) 107 (d) Increase (decrease) in accounts payable and accrued expenses 37 16 (a) (200) (6) (a) Increase (decrease) in interest and taxes payable (4) (1) (a) 120 4 (a) Net cash provided by operating activities LC 37 USD 16 LC 999 USD 30 (a) This amount represents the U.S. dollar equivalent of the foreign currency amount based on the weighted-average exchange rate for the year. (b) This amount represents the U.S. dollar equivalent of the foreign currency amount based on historical exchange rates. (c) This amount represents the exchange gain included in net income as a result of remeasuring Subsidiary B's financial statements from the local currency to U.S. dollars. (d) This amount represents the difference between beginning and ending inventory after remeasurement into U.S. dollars based on historical exchange rates.
-
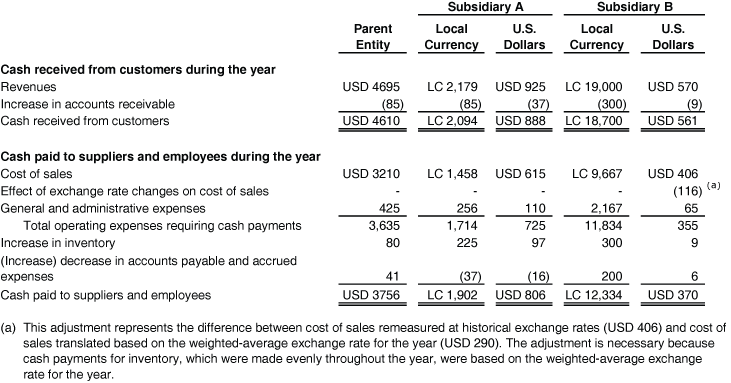 Subsidiary A Subsidiary B Parent Entity Local Currency U.S. Dollars Local Currency U.S. Dollars Cash received from customers during the year Revenues USD 4695 " LC 2,179 " USD 925 " LC 19,000 " USD 570 Increase in accounts receivable (85) (85) (37) (300) (9) Cash received from customers USD 4610 " LC 2,094 " USD 888 " LC 18,700 " USD 561 Cash paid to suppliers and employees during the year Cost of sales USD 3210 " LC 1,458 " USD 615 " LC 9,667 " USD 406 Effect of exchange rate changes on cost of sales - - - - (116) (a) General and administrative expenses 425 256 110 " 2,167 " 65 Total operating expenses requiring cash payments " 3,635 " " 1,714 " 725 " 11,834 " 355 Increase in inventory 80 225 97 300 9 (Increase) decrease in accounts payable and accrued expenses 41 (37) (16) 200 6 Cash paid to suppliers and employees USD 3756 " LC 1,902 " USD 806 " LC 12,334 " USD 370 (a) "This adjustment represents the difference between cost of sales remeasured at historical exchange rates (USD 406) and cost of sales translated based on the weighted-average exchange rate for the year (USD 290). The adjustment is necessary because cash payments for inventory, which were made evenly throughout the year, were based on the weighted-average exchange rate for the year."
-
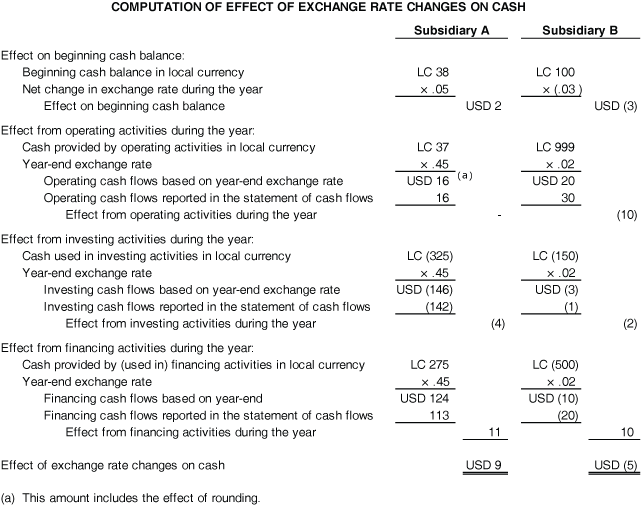 COMPUTATION OF EFFECT OF EXCHANGE RATE CHANGES ON CASH Subsidiary A Subsidiary B Effect on beginning cash balance: Beginning cash balance in local currency LC 38 LC 100 Net change in exchange rate during the year × .05 × (.03 ) Effect on beginning cash balance USD 2 USD (3) Effect from operating activities during the year: Cash provided by operating activities in local currency LC 37 LC 999 Year-end exchange rate × .45 × .02 Operating cash flows based on year-end exchange rate USD 16 (a) USD 20 Operating cash flows reported in the statement of cash flows 16 30 Effect from operating activities during the year - (10) Effect from investing activities during the year: Cash used in investing activities in local currency LC (325) LC (150) Year-end exchange rate × .45 × .02 Investing cash flows based on year-end exchange rate USD (146) USD (3) Investing cash flows reported in the statement of cash flows (142) (1) Effect from investing activities during the year (4) (2) Effect from financing activities during the year: Cash provided by (used in) financing activities in local currency LC 275 LC (500) Year-end exchange rate × .45 × .02 Financing cash flows based on year-end USD 124 USD (10) Financing cash flows reported in the statement of cash flows 113 (20) Effect from financing activities during the year 11 10 Effect of exchange rate changes on cash USD 9 USD (5) (a) This amount includes the effect of rounding.
Related subtopics
- 830-30 Translation of Financial StatementsForeign Currency Matters
- 830-20 Foreign Currency TransactionsForeign Currency Matters
- 230-942 Financial Services—Depository and LendingStatement of Cash Flows
- 830-10 OverallForeign Currency Matters
- 230-10 OverallStatement of Cash Flows
- 740-830 Foreign Currency MattersIncome Taxes