ASC 230-942
Financial Services—Depository and Lending
230 Statement of Cash Flows
Source downloaded: .Record version cf57a906ddfb. Effective date must be checked in the source.
This Subtopic tailors the statement of cash flows to banks, savings institutions, and credit unions. Its core rule is a net-reporting exception: these institutions need not report gross cash receipts and payments for deposits placed with or withdrawn from other financial institutions, time deposits accepted and repaid, and loans made to customers and principal collections on those loans (230-942-45-1). It also requires that principal payments received under sales-type and direct financing leases be classified as investing activities (230-942-45-4) and provides a full direct-method illustration in Section 55.
Key points (7)
- Banks, savings institutions, and credit unions may report net (rather than gross) cash receipts and payments for deposits placed with and withdrawn from other financial institutions, time deposits accepted and repaid, and customer loans made and principal collected (230-942-45-1).
- When such an institution is part of a consolidated entity, the net amounts for its deposit or lending activities must be presented separately from gross amounts for other investing and financing activities of the consolidated group, including those of a non-bank subsidiary of the institution (230-942-45-2).
- Principal payments received under sales-type leases and direct financing leases are classified as investing activities (230-942-45-4).
- General cash flow presentation guidance in Section 230-10-45 continues to apply (230-942-45-3), and the scope follows 942-10-15 (230-942-15-1).
- Section 55 illustrates a direct-method statement of cash flows for a financial institution, applying 230-10-45-25 through 45-26 and 45-28 through 45-32; the level of detail shown exceeds what is required and other formats may be appropriate (230-942-55-1).
- The example shows that net reporting is elective—Financial Institution, Inc. chose to report gross receipts and payments for certificates of deposit of all maturities (230-942-55-5(f)).
- Interest paid includes amounts credited directly to demand deposit, NOW, and savings accounts, consistent with the definition of cash (230-942-55-5(m)).
For students. Exam questions often test the exception itself: unlike most entities, depository institutions may net loan and deposit flows because turnover is quick and amounts are large. The common misunderstanding is thinking netting is mandatory or that it can be blended with the gross amounts of other consolidated entities—it is permissive, and in consolidation the net amounts must be shown separately.
Machine-generated study aid for ASC 230-942. Check the source paragraphs below.
230-942-00Status
Source downloaded: .Record version 49b74470af7c. Effective date must be checked in the source.
| Paragraph | Action | Accounting Standards Update | Date |
| 942-230-45-4 | Added | Accounting Standards Update No. 2019-01 | 03/05/2019 |
| 942-230-55-2 | Amended | Maintenance Update 2017-06 (PDF) | 04/07/2017 |
| 942-230-55-2 | Amended | Accounting Standards Update No. 2016-13 | 06/16/2016 |
| 942-230-55-3 | Superseded | Maintenance Update 2017-06 (PDF) | 04/07/2017 |
| 942-230-55-4 | Amended | Accounting Standards Update No. 2016-13 | 06/16/2016 |
230-942-05Overview and Background
Source downloaded: .Record version 5e7f6305e2a3. Effective date must be checked in the source.
230-942-15Scope and Scope Exceptions
Source downloaded: .Record version e30be56c1e73. Effective date must be checked in the source.
Overall Guidance
230-942-45Other Presentation Matters
Source downloaded: .Record version 6631ae9a69b3. Effective date must be checked in the source.
- a Deposits placed with other financial institutions and withdrawals of deposits
- b Time deposits accepted and repayments of deposits
- c Loans made to customers and principal collections of loans.
230-942-55Implementation Guidance and Illustrations
Source downloaded: .Record version 0a1e3dce23e3. Effective date must be checked in the source.
Illustrations
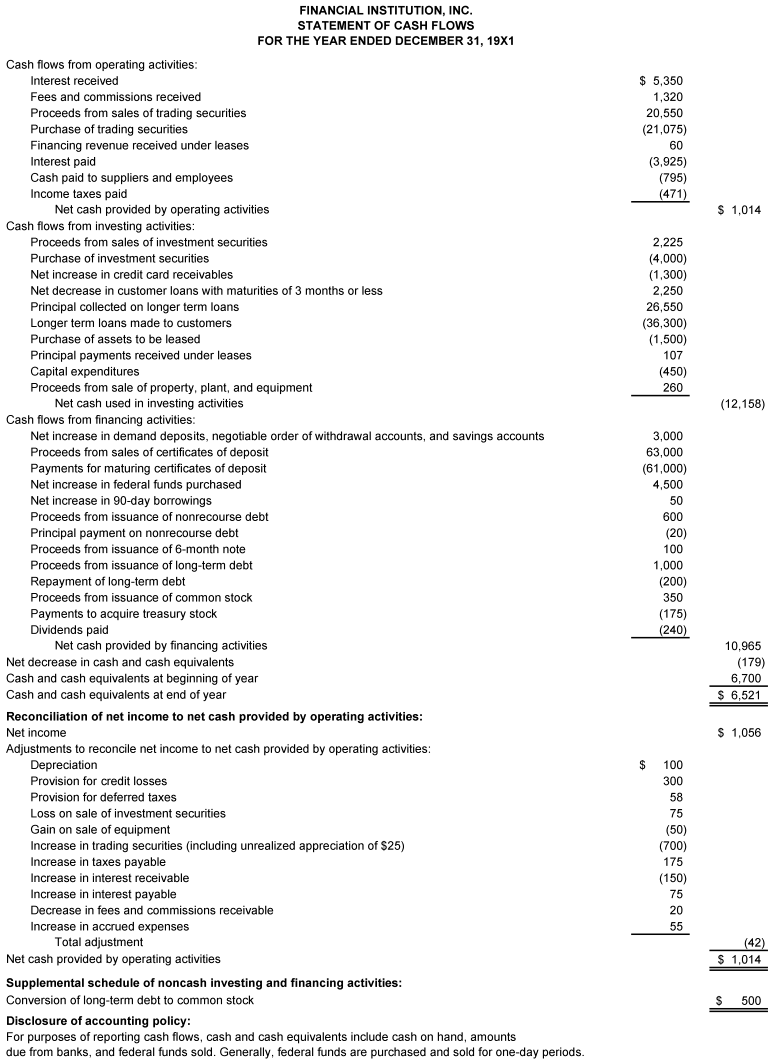 "FINANCIAL INSTITUTION, INC." STATEMENT OF CASH FLOWS "FOR THE YEAR ENDED DECEMBER 31, 19X1" Cash flows from operating activities: Interest received " $5,350 " Fees and commissions received " 1,320 " Proceeds from sales of trading securities " 20,550 " Purchase of trading securities " (21,075)" Financing revenue received under leases 60 Interest paid " (3,925)" Cash paid to suppliers and employees (795) Income taxes paid (471) Net cash provided by operating activities " $1,014 " Cash flows from investing activities: Proceeds from sales of investment securities " 2,225 " Purchase of investment securities " (4,000)" Net increase in credit card receivables " (1,300)" Net decrease in customer loans with maturities of 3 months or less " 2,250 " Principal collected on longer term loans " 26,550 " Longer term loans made to customers " (36,300)" Purchase of assets to be leased " (1,500)" Principal payments received under leases 107 Capital expenditures (450) "Proceeds from sale of property, plant, and equipment" 260 Net cash used in investing activities " (12,158)" Cash flows from financing activities: "Net increase in demand deposits, negotiable order of withdrawal accounts, and savings accounts" " 3,000 " Proceeds from sales of certificates of deposit " 63,000 " Payments for maturing certificates of deposit " (61,000)" Net increase in federal funds purchased " 4,500 " Net increase in 90-day borrowings 50 Proceeds from issuance of nonrecourse debt 600 Principal payment on nonrecourse debt (20) Proceeds from issuance of 6-month note 100 Proceeds from issuance of long-term debt " 1,000 " Repayment of long-term debt (200) Proceeds from issuance of common stock 350 Payments to acquire treasury stock (175) Dividends paid (240) Net cash provided by financing activities " 10,965 " Net decrease in cash and cash equivalents (179) Cash and cash equivalents at beginning of year " 6,700 " Cash and cash equivalents at end of year " $6,521 " Reconciliation of net income to net cash provided by operating activities: Net income " $1,056 " Adjustments to reconcile net income to net cash provided by operating activities: Depreciation $100 Provision for credit losses 300 Provision for deferred taxes 58 Loss on sale of investment securities 75 Gain on sale of equipment (50) Increase in trading securities (including unrealized appreciation of $25) (700) Increase in taxes payable 175 Increase in interest receivable (150) Increase in interest payable 75 Decrease in fees and commissions receivable 20 Increase in accrued expenses 55 Total adjustment (42) Net cash provided by operating activities " $1,014 " Supplemental schedule of noncash investing and financing activities: Conversion of long-term debt to common stock $500 Disclosure of accounting policy: For purposes of reporting cash flows, cash and cash equivalents include cash on hand, amounts due from banks, and federal funds sold. Generally, federal funds are purchased and sold for one-day periods.
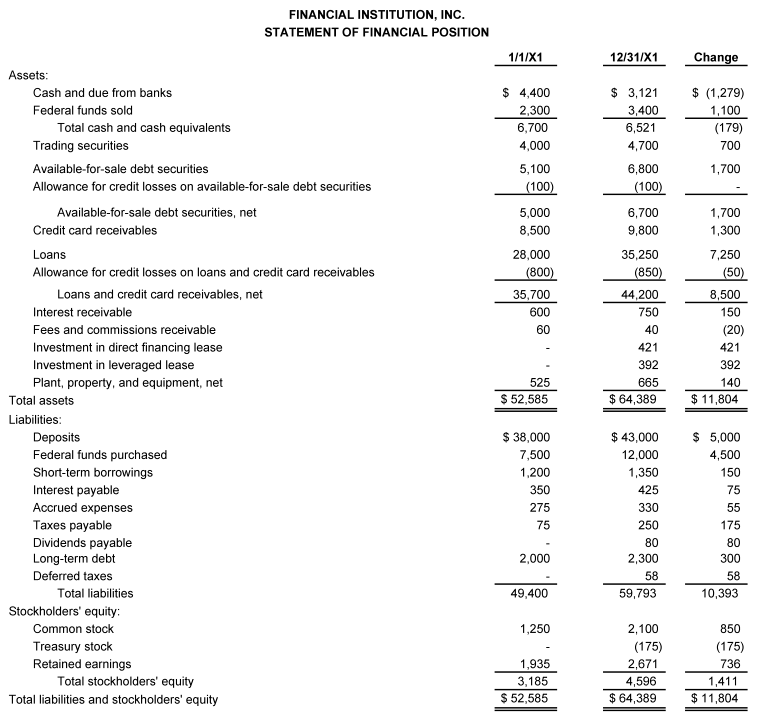 "FINANCIAL INSTITUTION, INC. " STATEMENT OF FINANCIAL POSITION 1/1/X1 12/31/X1 Change Assets: Cash and due from banks " $4,400 " " $3,121 " " $(1,279)" Federal funds sold " 2,300 " " 3,400 " " 1,100 " Total cash and cash equivalents " 6,700 " " 6,521 " (179) Trading securities " 4,000 " " 4,700 " 700 Available-for-sale debt securities " 5,100 " " 6,800 " " 1,700 " Allowance for credit losses on available-for-sale debt securities (100) (100) - "Available-for-sale debt securities, net" " 5,000 " " 6,700 " " 1,700 " Credit card receivables " 8,500 " " 9,800 " " 1,300 " Loans " 28,000 " " 35,250 " " 7,250 " Allowance for credit losses on loans and credit card receivables (800) (850) (50) "Loans and credit card receivables, net" " 35,700 " " 44,200 " " 8,500 " Interest receivable 600 750 150 Fees and commissions receivable 60 40 (20) Investment in direct financing lease - 421 421 Investment in leveraged lease - 392 392 "Plant, property, and equipment, net" 525 665 140 Total assets " $52,585 " " $64,389 " " $11,804 " Liabilities: Deposits " $38,000 " " $43,000 " " $5,000 " Federal funds purchased " 7,500 " " 12,000 " " 4,500 " Short-term borrowings " 1,200 " " 1,350 " 150 Interest payable 350 425 75 Accrued expenses 275 330 55 Taxes payable 75 250 175 Dividends payable - 80 80 Long-term debt " 2,000 " " 2,300 " 300 Deferred taxes - 58 58 Total liabilities " 49,400 " " 59,793 " " 10,393 " Stockholders' equity: Common stock " 1,250 " " 2,100 " 850 Treasury stock - (175) (175) Retained earnings " 1,935 " " 2,671 " 736 Total stockholders' equity " 3,185 " " 4,596 " " 1,411 " Total liabilities and stockholders' equity " $52,585 " " $64,389 " " $11,804 "
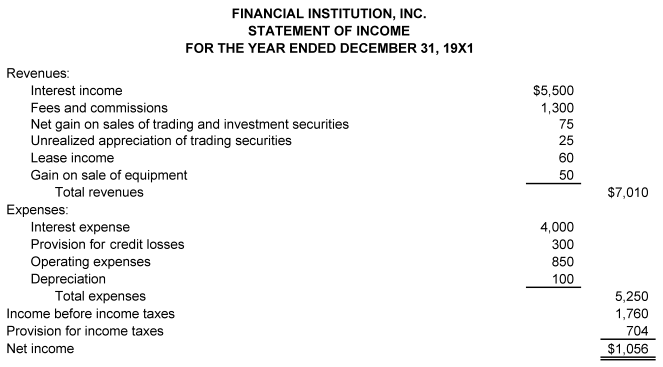 "FINANCIAL INSTITUTION, INC." STATEMENT OF INCOME "FOR THE YEAR ENDED DECEMBER 31, 19X1" Revenues: Interest income " $5,500 " Fees and commissions " 1,300 " Net gain on sales of trading and investment securities 75 Unrealized appreciation of trading securities 25 Lease income 60 Gain on sale of equipment 50 Total revenues " $7,010 " Expenses: Interest expense " 4,000 " Provision for credit losses 300 Operating expenses 850 Depreciation 100 Total expenses " 5,250 " Income before income taxes " 1,760 " Provision for income taxes 704 Net income " $1,056 "
- aFinancial Institution sold trading securities with a carrying value of $20,400 for $20,550 and purchased trading securities for $21,075. Financial Institution recorded unrealized appreciation on trading securities of $25. Financial Institution also sold investment securities with a book value of $2,300 for $2,225 and purchased new investment securities for $4,000.
- bFinancial Institution had a net decrease in short-term loans receivable (those with original maturities of 3 months or less) of $2,250. Financial Institution made longer term loans of $36,300 and collected $26,550 on those loans. Financial Institution wrote off $250 of loans as uncollectible.
- cFinancial Institution purchased property for $500 to be leased under a direct financing lease. The first annual rental payment of $131 was collected. The portion of the rental payment representing interest income totaled $52.
- dFinancial Institution purchased equipment for $1,000 to be leased under a leveraged lease. The cost of the leased asset was financed by an equity investment of $400 and a long-term nonrecourse bank loan of $600. The first annual rental payment of $90, of which $28 represented principal, was collected and the first annual loan installment of $74, of which $20 represented principal, was paid. Pretax income of $8 was recorded.
- eFinancial Institution purchased new property, plant, and equipment for $450 and sold property, plant, and equipment with a book value of $210 for $260.
- fCustomer deposits with Financial Institution consisted of the following.
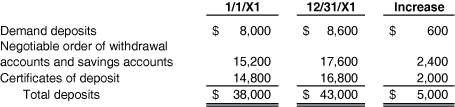 1/1/X1 12/31/X1 Increase Demand deposits " $8,000 " " $8,600 " $600 Negotiable order of withdrawal accounts and savings accounts " 15,200 " " 17,600 " " 2,400 " Certificates of deposit " 14,800 " " 16,800 " " 2,000 " Total deposits " $38,000 " " $43,000 " " $5,000 "
Sales of certificates of deposit during the year totaled $63,000; certificates of deposit with principal amounts totaling $61,000 matured. For presentation in the statement of cash flows, Financial Institution chose to report gross cash receipts and payments for both certificates of deposit with maturities of three months or less and those with maturities of more than three months. - gShort-term borrowing activity for Financial Institution consisted of repayment of a $200 90-day note and issuance of a 90-day note for $250 and a 6-month note for $100.
- hFinancial Institution repaid $200 of long-term debt and issued 5-year notes for $600 and 10-year notes for $400.
- iFinancial Institution issued $850 of common stock, $500 of which was issued upon conversion of long-term debt and $350 of which was issued for cash.
- jFinancial Institution acquired $175 of treasury stock.
- kFinancial Institution declared dividends of $320. The fourth quarter dividend of $80 was payable the following January.
- lFinancial Institution's provision for income taxes included a deferred provision of $58.
- mIn accordance with the definition of the term cash, interest paid includes amounts credited directly to demand deposit, negotiable order of withdrawal accounts, and savings accounts.
Related subtopics
- 230-10 OverallStatement of Cash Flows
- 230-830 Foreign Currency MattersStatement of Cash Flows
- 230-958 Not-for-Profit EntitiesStatement of Cash Flows
- 405-942 Financial Services—Depository and LendingLiabilities
- 205-958 Not-for-Profit EntitiesPresentation of Financial Statements
- 220-958 Not-for-Profit EntitiesIncome Statement—Reporting Comprehensive Income