ASC 810-30
Research and Development Arrangements
810 Consolidation
Source downloaded: .Record version 9f7a1527c1e2. Effective date must be checked in the source.
ASC 810-30 tells a sponsor how to account for a research and development arrangement in which the sponsor funds 100% of the R&D activities — typically by capitalizing a new entity (Newco) with cash and technology rights, spinning off Newco's Class A common stock to the sponsor's shareholders, and retaining a purchase option and nominal Class B shares. The sponsor reclassifies the contributed cash as restricted cash, recognizes R&D expense as the activities are performed, and records the Class A distribution as a dividend at the fair value of that stock. The Class A stock is presented as noncontrolling interest classified in equity but separate from the parent's equity, and exercise of the purchase option is accounted for like an acquisition of a noncontrolling interest.
Key points (7)
- Scope is limited to research and development arrangements in which all funds for the R&D activities are provided by the sponsor (810-30-15-2); arrangements funded by third parties fall under Subtopic 730-20 (810-30-15-3(a)).
- The VIE guidance in the Variable Interest Entities Subsections of Subtopic 810-10 must be applied first; if the legal entity is consolidated as a VIE, this Subtopic does not apply (810-30-15-3(b)).
- The sponsor must (a) reclassify cash contributed to the new entity as restricted cash at the time of distribution of the Class A common stock, (b) recognize research and development expense as the R&D activities are performed, and (c) account for the distribution of the Class A common stock as a dividend to its common stockholders (810-30-25-3).
- The dividend is measured at the fair value of the new entity's Class A common stock and recorded at the time of distribution to the sponsor's stockholders (810-30-30-1).
- If the purchase option is exercised, the excess of the exercise price over the carrying amount of the Class A common stock is allocated to assets acquired (generally in-process or completed R&D) and liabilities assumed, like an acquisition of a noncontrolling interest (810-30-35-1).
- If the purchase option expires unexercised, the Class A common stock is reclassified to additional paid-in capital as an adjustment to the initial dividend (810-30-35-1).
- The Class A common stock is presented as a noncontrolling interest classified as equity but separate from the parent's equity (810-30-45-1), and the sponsor's R&D expense is not allocated to the Class A stock in computing income available to common stockholders for EPS (810-30-45-2).
For students. This is a narrow, structure-specific rule aimed at "R&D spin-off" vehicles used to keep development costs off the sponsor's books — the point is that the sponsor still expenses the R&D and cannot treat the spun-off entity as a true third-party funder. The most common mistake is skipping the ordering rule: you must test the new entity under the VIE guidance in 810-10 first, and only if it is not a consolidated VIE (and the sponsor provides all the funding) do you apply 810-30.
Machine-generated study aid for ASC 810-30. Check the source paragraphs below.
810-30-00Status
Source downloaded: .Record version 6fa16187106b. Effective date must be checked in the source.
| Paragraph | Action | Accounting Standards Update | Date |
| Fair Value (3rd def.) | Added | Accounting Standards Update No. 2012-04 | 10/01/2012 |
| 810-30-15-3 | Amended | Accounting Standards Update No. 2015-02 | 02/18/2015 |
| 810-30-55-1 | Amended | Accounting Standards Update No. 2012-04 | 10/01/2012 |
| 810-30-55-3 | Amended | Accounting Standards Update No. 2012-04 | 10/01/2012 |
810-30-05Overview and Background
Source downloaded: .Record version 18bc632567aa. Effective date must be checked in the source.
810-30-15Scope and Scope Exceptions
Source downloaded: .Record version 9b78aee12621. Effective date must be checked in the source.
Overall Guidance
Transactions
- aTransactions in which the funds are provided by third parties, which would generally be within the scope of Subtopic 730-20. That Subtopic establishes standards of financial accounting and reporting for an entity that is a party to a research and development arrangement through which it can obtain the results of research and development funded partially or entirely by others.
- bLegal entities required to be consolidated under the guidance on variable interest entities (VIEs). That guidance must be applied first (see the Variable Interest Entities Subsection of Section 810-10-15) before considering this Subtopic. Consolidation by reporting entities of VIEs, which include many legal entities used in research and development arrangements, is addressed by the Variable Interest Entities Subsections of Subtopic 810-10.
Other Considerations
810-30-25Recognition
Source downloaded: .Record version 3c3e39dcbda1. Effective date must be checked in the source.
- aReclassify the cash contributed to the new entity as restricted cash at the time of distribution of the new entity's Class A common stock.
- bRecognize research and development expense as the research and development activities are performed.
- cAccount for the distribution of the new entity's Class A common stock as a dividend to common stockholders of the sponsor.
810-30-30Initial Measurement
Source downloaded: .Record version 4f887ebb3242. Effective date must be checked in the source.
810-30-35Subsequent Measurement
Source downloaded: .Record version f8a05579669c. Effective date must be checked in the source.
810-30-45Other Presentation Matters
Source downloaded: .Record version 4f37505a9121. Effective date must be checked in the source.
Presentation of the New Entity's Common Stock by the Sponsor
EPS
810-30-55Implementation Guidance and Illustrations
Source downloaded: .Record version d6a50cb263f6. Effective date must be checked in the source.
Illustrations
-
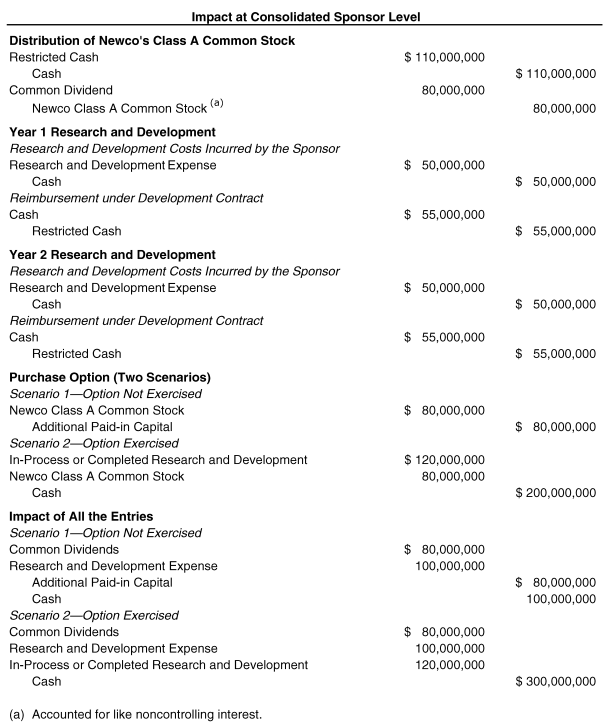 Impact at Consolidated Sponsor Level Distribution of Newco's Class A Common Stock Restricted Cash " $110,000,000 " Cash " $110,000,000 " Common Dividend " 80,000,000 " Newco Class A Common Stock (a) " 80,000,000 " Year 1 Research and Development Research and Development Costs Incurred by the Sponsor Research and Development Expense " $50,000,000 " Cash " $50,000,000 " Reimbursement under Development Contract Cash " $55,000,000 " Restricted Cash " $55,000,000 " Year 2 Research and Development Research and Development Costs Incurred by the Sponsor Research and Development Expense " $50,000,000 " Cash " $50,000,000 " Reimbursement under Development Contract Cash " $55,000,000 " Restricted Cash " $55,000,000 " Purchase Option (Two Scenarios) Scenario 1—Option Not Exercised Newco Class A Common Stock " $80,000,000 " Additional Paid-in Capital " $80,000,000 " Scenario 2—Option Exercised In-Process or Completed Research and Development " $120,000,000 " Newco Class A Common Stock " 80,000,000 " Cash " $200,000,000 " Impact of All the Entries Scenario 1—Option Not Exercised Common Dividends " $80,000,000 " Research and Development Expense " 100,000,000 " Additional Paid-in Capital " $80,000,000 " Cash " 100,000,000 " Scenario 2—Option Exercised Common Dividends " $80,000,000 " Research and Development Expense " 100,000,000 " In-Process or Completed Research and Development " 120,000,000 " Cash " $300,000,000 " (a) Accounted for like noncontrolling interest.
810-30-60Relationships
Source downloaded: .Record version 46dec4a8d012. Effective date must be checked in the source.
Collaborative Arrangements
Related subtopics
- 730-20 Research and Development ArrangementsResearch and Development
- 730-912 Contractors—Federal GovernmentResearch and Development
- 340-10 OverallOther Assets and Deferred Costs
- 810-958 Not-for-Profit EntitiesConsolidation
- 730-10 OverallResearch and Development
- 810-942 Financial Services—Depository and LendingConsolidation