ASC 720-45
Business and Technology Reengineering
720 Other Expenses
Source downloaded: .Record version 2f5f1052e65c. Effective date must be checked in the source.
ASC 720-45 governs the accounting for costs of business process reengineering (BPR) activities, including those bundled into information technology transformation projects (e.g., enterprise software installations). The core rule is that BPR costs—whether performed internally or by third parties—must be expensed as incurred, even when they are part of a project to acquire, develop, or implement internal-use software. When a bundled third-party consulting contract covers multiple activities, the contract price must be allocated among activities based on objective evidence of relative fair values.
Key points (6)
- Business process reengineering costs, whether incurred internally or paid to third parties, are expensed as incurred, including when the reengineering is part of a project to acquire, develop, or implement internal-use software (720-45-25-1).
- Specific costs that must be expensed as incurred include preparation of a request for proposal, current state assessment (except as it relates to current software structure), process reengineering, and restructuring the work force (720-45-25-2).
- Costs in the property and equipment acquisition or construction phase of a BPR project follow the entity's existing policies for productive assets (720-45-25-4).
- For third-party projects, the total consulting contract price (or the sum of linked contracts with the same vendor) is allocated to each activity based on the relative fair values of those separate activities, using objective evidence of fair value rather than the prices stated in the contract (720-45-30-1).
- The Subtopic applies to all entities but does not address or change accounting for internal-use software development costs (Subtopic 350-40) or the acquisition of property and equipment (720-45-15-1 through 15-2).
- The illustrative table in 720-45-55-1 sorts typical project components among expensing under this Subtopic, treatment under the internal-use software guidance in 350-40, and capitalization as part of a fixed asset; ASU 2025-06 amends the table (transition date December 16, 2027; transition guidance in 350-40-65-4).
For students. The exam trap is assuming that because reengineering work is bundled into a capitalizable enterprise software or ERP implementation, the whole contract can be capitalized—720-45-25-1 requires the reengineering portion to be expensed, and 720-45-30-1 forces a relative-fair-value split of the bundled fee based on objective evidence, not the vendor's stated line-item prices.
Machine-generated study aid for ASC 720-45. Check the source paragraphs below.
720-45-00Status
Source downloaded: .Record version 9cdf71e3ae2f. Effective date must be checked in the source.
| Paragraph | Action | Accounting Standards Update | Date |
| 720-45-55-1 | Amended | Accounting Standards Update 2025-06 | 09/18/2025 |
720-45-05Overview and Background
Source downloaded: .Record version 54463d858f5f. Effective date must be checked in the source.
720-45-15Scope and Scope Exceptions
Source downloaded: .Record version f24c15410c48. Effective date must be checked in the source.
Entities
Other Considerations
720-45-25Recognition
Source downloaded: .Record version 3e25ebed9141. Effective date must be checked in the source.
- aPreparation of request for proposal—the process of preparing a proposal.
- bCurrent state assessment—the process of documenting the entity's current business process, except as it relates to current software structure. This activity is sometimes called mapping, developing an as-is baseline, flow charting, and determining current business process structure.
- cProcess reengineering—the effort to reengineer the entity's business process to increase efficiency and effectiveness. This activity is sometimes called analysis, determining best-in-class, profit and performance improvement development, and developing should-be processes.
- dRestructuring the work force—the effort to determine what employee makeup is necessary to operate the reengineered business processes.
720-45-30Initial Measurement
Source downloaded: .Record version ad9f62698f4b. Effective date must be checked in the source.
720-45-55Implementation Guidance and Illustrations
Source downloaded: .Record version f6c691331db2. Effective date must be checked in the source.
Implementation Guidance
- aExpensed as incurred in accordance with the guidance contained in this Subtopic
- bExpensed as incurred in accordance with internal-use software guidance contained in Subtopic 350-40
- cCapitalized in accordance with internal-use software guidance contained in Subtopic 350-40
- dCapitalized as part of the cost of acquiring a fixed asset in accordance with a company's existing policy.
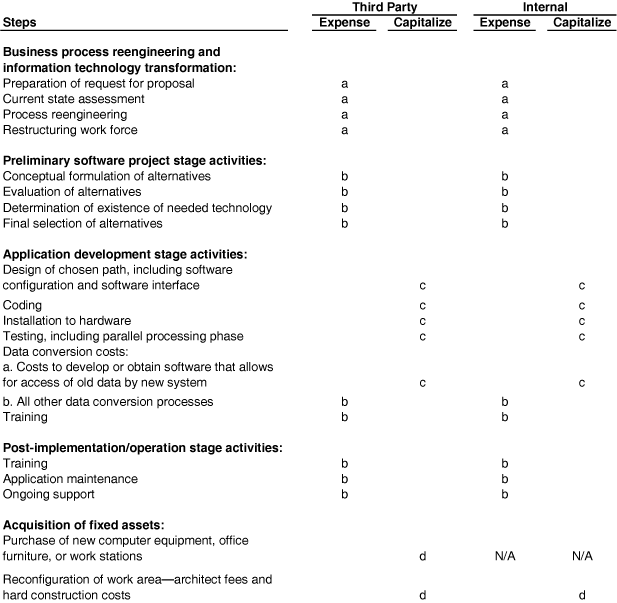 Third Party Internal Steps Expense Capitalize Expense Capitalize Business process reengineering and information technology transformation: Preparation of request for proposal a a Current state assessment a a Process reengineering a a Restructuring work force a a Preliminary software project stage activities: Conceptual formulation of alternatives b b Evaluation of alternatives b b Determination of existence of needed technology b b Final selection of alternatives b b Application development stage activities: "Design of chosen path, including software configuration and software interface" c c Coding c c Installation to hardware c c "Testing, including parallel processing phase" c c Data conversion costs: a. Costs to develop or obtain software that allows for access of old data by new system c c b. All other data conversion processes b b Training b b Post-implementation/operation stage activities: Training b b Application maintenance b b Ongoing support b b Acquisition of fixed assets: "Purchase of new computer equipment, office furniture, or work stations" d N/A N/A Reconfiguration of work area—architect fees and hard construction costs d d
- aExpensed as incurred in accordance with the guidance contained in this Subtopic
- b
- c
- dCapitalized as part of the cost of acquiring a fixed asset in accordance with a company's existing policy
- eCapitalized or expensed in accordance with the internal-use software guidance contained in Subtopic 350-40.
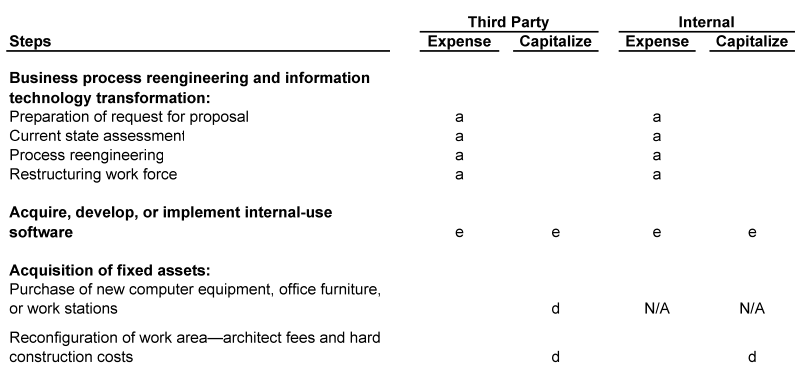 Third Party Internal Steps Expense Capitalize Expense Capitalize Business process reengineering and information technology transformation: Preparation of request for proposal a a Current state assessment a a Process reengineering a a Restructuring work force a a "Acquire, develop, or implement internal-use software" e e e e Acquisition of fixed assets: "Purchase of new computer equipment, office furniture, or work stations" d N/A N/A Reconfiguration of work area—architect fees and hard construction costs d d
Related subtopics
- 730-10 OverallResearch and Development
- 350-40 Internal-Use SoftwareIntangibles—Goodwill and Other
- 985-20 Costs of Software to Be Sold, Leased, or MarketedSoftware
- 720-970 Real Estate—GeneralOther Expenses
- 340-10 OverallOther Assets and Deferred Costs
- 340-40 Contracts with CustomersOther Assets and Deferred Costs