ASC 470-30
Participating Mortgage Loans
470 Debt
Source downloaded: .Record version ac788dd9918b. Effective date must be checked in the source.
ASC 470-30 governs how a *borrower* accounts for a participating mortgage loan — a mortgage in which the lender is entitled to share in appreciation in the fair value of the mortgaged real estate project, in its results of operations, or both. If the lender participates in fair value appreciation, the borrower recognizes a participation liability at the fair value of the participation feature at loan inception with an offsetting debt discount, remeasures the liability to current fair value each reporting period (adjusting the discount), and amortizes the discount to interest expense using the interest method. Participations in results of operations are charged to interest expense in the period incurred with a credit to the participation liability.
Key points (7)
- A participation liability with a corresponding debit to a debt discount account is recognized when the lender is entitled to participate in appreciation in the market value of the mortgaged real estate project (470-30-25-1).
- The participation feature is measured at fair value (per Subtopic 820-10) at inception of the loan (470-30-30-1).
- Interest expense has three components: stated interest, amounts for the lender's participation in results of operations, and amortization of the debt discount related to participation in fair value appreciation (470-30-35-2); the discount is amortized by the interest method using the effective interest rate (470-30-35-1).
- At the end of each reporting period the participation liability is adjusted to the current fair value of the participation feature, with the offsetting debit or credit to the debt discount account (470-30-35-4A), and the revised discount is amortized prospectively at the effective interest rate (470-30-35-5).
- Amounts due for participation in results of operations are charged to interest expense in the corresponding reporting period with a credit to the participation liability (470-30-35-4); stated interest is charged to income as incurred, based on the index/rate as it changes, and is subject to Subtopic 835-20 capitalization rules, with capitalized amounts not adjusted for reversals of appreciation (470-30-35-3).
- Early extinguishment produces a gain or loss equal to the difference between the recorded amount of the debt (including unamortized discount and the participation liability) and the amount exchanged, reported as required by 470-50-40-2 (470-30-40-1; 470-30-45-2).
- Borrowers must disclose the aggregate amount of participating mortgage obligations at the balance sheet date, separately showing aggregate participation liabilities and related debt discounts, plus the terms of the lender's participations (470-30-50-1).
For students. Exam traps: this Subtopic applies only to borrowers (not lenders) and excludes participating leases, lender-option equity-convertible debt, and participations arising from troubled debt restructurings. Remember the participation liability is remeasured to fair value every period through the debt discount (not through earnings directly) — earnings are affected only via prospective amortization of the revised discount.
Machine-generated study aid for ASC 470-30. Check the source paragraphs below.
470-30-00Status
Source downloaded: .Record version 6950b34e7ac4. Effective date must be checked in the source.
470-30-05Overview and Background
Source downloaded: .Record version b8f96a20df8a. Effective date must be checked in the source.
- aAppreciation in the fair value of the mortgaged real estate project
- bThe results of operations of the mortgaged real estate project.
- aDebtor-creditor relationships between those who provide initial cash outlays and hold the mortgages, and those who are obligated to make subsequent payments to the mortgage holders
- bReal estate collateral
- cPeriodic fixed-rate or floating-rate interest payments
- dFixed maturity dates for stated principal amounts.
- aUpon the sale of the project
- bAt a deemed sale date
- cAt the maturity or refinancing of the loan.
- aRevenue
- bIncome
- cCash flows before or after debt service.
- aThe contract interest the borrower is required to pay
- bThe risk that the borrower will be unable to pay interest at the stated or floating rate in the loan agreement and, consequently, the risk that the borrower will default on the loan and need to sell the property
- cThe amount of capital the borrower has at risk, because the loan-to-value ratio normally is higher.
470-30-15Scope and Scope Exceptions
Source downloaded: .Record version b83df8c006fc. Effective date must be checked in the source.
Entities
- aAll borrowers in participating mortgage loan arrangements.
- aCreditors in participating mortgage loan arrangements.
Transactions
- aParticipating leases
- bDebt convertible at the option of the lender into equity ownership of the property
- cParticipating loans resulting from troubled debt restructurings.
470-30-25Recognition
Source downloaded: .Record version 28853a10184b. Effective date must be checked in the source.
470-30-30Initial Measurement
Source downloaded: .Record version fbabfe973e72. Effective date must be checked in the source.
470-30-35Subsequent Measurement
Source downloaded: .Record version 514377c2f712. Effective date must be checked in the source.
- aAmounts designated in the mortgage agreement as interest
- bAmounts related to the lender's participation in results of operations
- cAmortization of debt discount related to the lender's participation in the fair value appreciation of the mortgaged real estate project.
- a
- b
- aThe balance of the participation liability shall be adjusted to equal the current fair value of the participation feature.
- bThe corresponding debit or credit shall be recorded in the related debt-discount account.
470-30-40Derecognition
Source downloaded: .Record version e27040948363. Effective date must be checked in the source.
470-30-45Other Presentation Matters
Source downloaded: .Record version e1438d176307. Effective date must be checked in the source.
470-30-50Disclosure
Source downloaded: .Record version f916b685bd5e. Effective date must be checked in the source.
- aThe aggregate amount of participating mortgage obligations at the balance sheet date, with separate disclosure of the aggregate participation liabilities and related debt discounts
- bTerms of the participations by the lender in either the appreciation in the fair value of the mortgaged real estate project or the results of operations of the mortgaged real estate project, or both.
470-30-55Implementation Guidance and Illustrations
Source downloaded: .Record version d8e7b5eeff85. Effective date must be checked in the source.
Illustrations
- a 15 year term
- b Interest-only periodic payments, principal to be repaid at end of term
- c 5% stated interest rate
- d 20% participation in appreciation in the value of the property above $10 million, payable at maturity (or earlier if the asset is sold or the loan is refinanced).
-
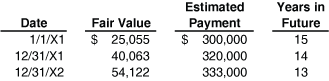 Date Fair Value Estimated Payment Years in Future 1/1/X1 " $25,055 " " $300,000 " 15 12/31/X1 " 40,063 " " 320,000 " 14 12/31/X2 " 54,122 " " 333,000 " 13
-
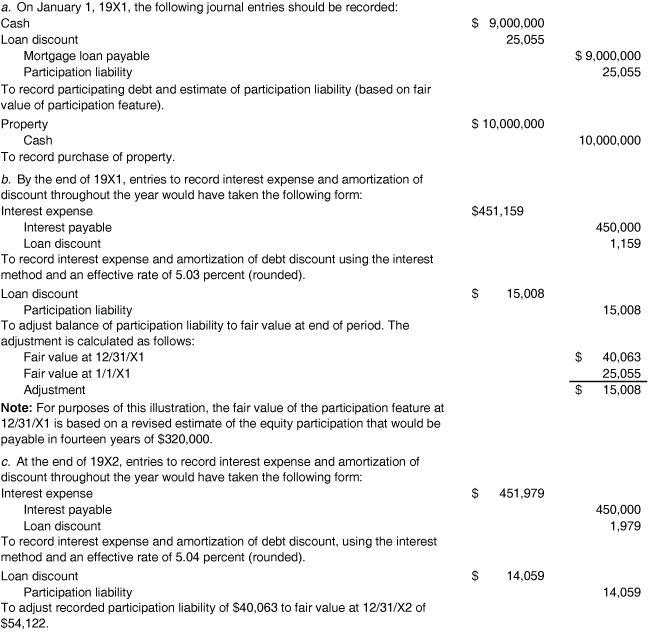 "a. On January 1, 19X1, the following journal entries should be recorded:" Cash " $9,000,000 " Loan discount " 25,055 " Mortgage loan payable " $9,000,000 " Participation liability " 25,055 " To record participating debt and estimate of participation liability (based on fair value of participation feature). Property " $10,000,000 " Cash " 10,000,000 " To record purchase of property. "b. By the end of 19X1, entries to record interest expense and amortization of discount throughout the year would have taken the following form:" Interest expense " $451,159 " Interest payable " 450,000 " Loan discount " 1,159 " To record interest expense and amortization of debt discount using the interest method and an effective rate of 5.03 percent (rounded). Loan discount " $15,008 " Participation liability " 15,008 " To adjust balance of participation liability to fair value at end of period. The adjustment is calculated as follows: Fair value at 12/31/X1 " $40,063 " Fair value at 1/1/X1 " 25,055 " Adjustment " $15,008 " "Note: For purposes of this illustration, the fair value of the participation feature at 12/31/X1 is based on a revised estimate of the equity participation that would be payable in fourteen years of $320,000." "c. At the end of 19X2, entries to record interest expense and amortization of discount throughout the year would have taken the following form:" Interest expense " $451,979 " Interest payable " 450,000 " Loan discount " 1,979 " "To record interest expense and amortization of debt discount, using the interest method and an effective rate of 5.04 percent (rounded)." Loan discount " $14,059 " Participation liability " 14,059 " "To adjust recorded participation liability of $40,063 to fair value at 12/31/X2 of $54,122."